



GLP derivative protocol strategy breakdown: Delta-neutral strategy, collateralized borrowing and lending, liquidity tokens, and competitors.
During a recent period of time, there has been surprising DeFi innovation on Arbitrum. One of the main reasons for this state of affairs is the deployment of decentralized derivative trading platform GMX on Arbitrum - thanks to DeFi's Lego-like properties, other DeFi protocols began building products based on GMX. The most common design is the product framework based on GLP.
Next, let's break down this type of product in detail.
First of all, what is GLP?
There are two types of tokens in the GMX ecosystem, one is the governance and dividend token GMX, and the other is the liquidity token GLP.
GMX is not an order book model. In GMX's market, one party is a liquidity provider and the other is a trader. Investors can provide liquidity to traders on GMX by purchasing GLP, and in return, investors can receive a 70% share of GMX trading fees. Liquidity providers and traders are counterparties, which means that a trader's profit represents a loss for GLP holders, and a trader's loss represents a profit for GLP holders.
GLP consists of a package of mainstream assets - 50% stablecoins, 28% ETH, 20% WBTC, and some other mainstream assets. Liquidity providers enter or exit the market by minting or burning GLP.
In the design of most GLP derivative products, their main goal is to reduce investors' risks, increase GLP holders' returns, and thus increase the capital efficiency of assets.
Next, let's take a look at the strategies of these protocols:
1、Delta Neutral Strategy
To provide investors with Delta-neutral strategies to acquire users is the mainstream practice of most GLP derivative agreements.
According to the explanation on Wikipedia, in the financial field, if an investment portfolio is composed of related financial products and its value is not affected by small price changes in the underlying assets, such investment portfolio has the property of Delta neutrality. In traditional finance, investment portfolio strategies aimed at making money in horizontal markets are called Delta neutral strategies.
That is to say, Delta neutral trading in Delta aims to establish a position that does not respond to small changes in the price of the underlying asset. Therefore, the goal of GLP Delta neutral strategy is to provide returns for GLP holders while reducing their sensitivity to price.
Let's take Rage Trade as an example.
Rage Trade provides users with a vault product called "Delta Neutral Vault", which is divided into Risk-On Vault (9% APY) and Risk-Off Vault (5% APY). Users can earn benefits by depositing USDC, and the vault has reached its limit currently.
How does a vault operate?
The basic work of Vault is to provide liquidity for GMX in a Delta-neutral way to earn ETH returns. However, in order to reduce users' risk exposure, Rage Trade has launched two products to meet the needs of users with different risk preferences. By combining funds in Risk-On Vault and Risk-Off Vault, Rage Trade achieves returns under different risks.
Phase One: Rage Trade converts a portion of the user's USDC into GLP, deposits it into GMX, and receives a share of the fee income.
Phase Two: Based on the ETH and BTC positions in GLP, borrow ETH and BTC through flash loans on Balancer and sell them on UniSwap to obtain USDC. Rage Trade then deposits the USDC into AAVE, borrows ETH and BTC, and repays the loan on Balancer. To improve capital efficiency, Rage Trade maintains a healthy factor of 1.5 for its short position in Aave.
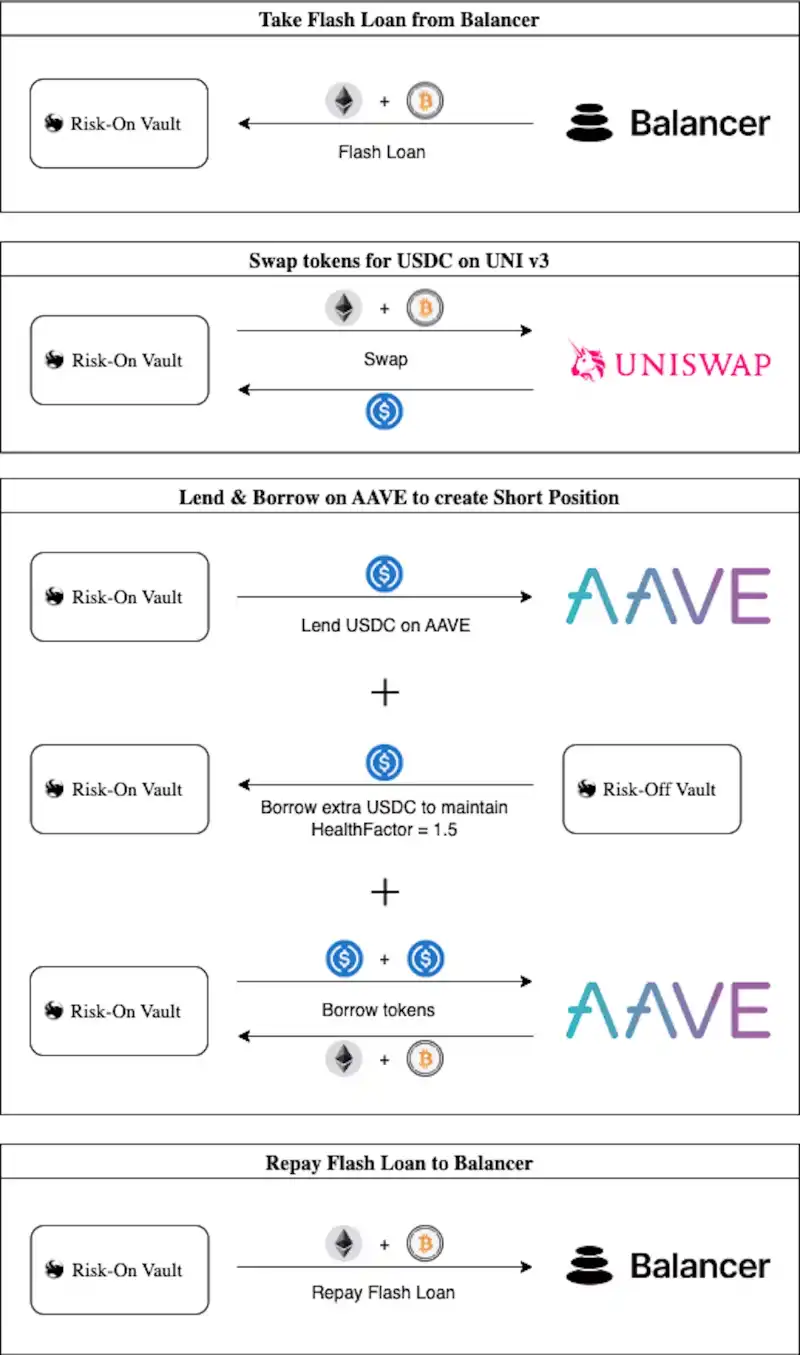
其中,Risk-On Vault borrowed USDC from Risk-Off Vault to open short positions and hedge against price fluctuations of ETH and BTC, in addition to pledging GLP to receive GMX fee dividends.
Meanwhile, Risk-Off Vault earns interest by borrowing USDC on Aave, and also receives a small amount of ETH reward from GLP based on the amount of USDC lent to Risk-On Vault.
Every 12 hours, Risk-On Vault will update its hedging position based on changes in weight and price, and automatically compound GMX's ETH earnings into GLP.
Phase Three: Based on the utilization rate of the Risk-Off Vault, the ETH rewards generated from GMX since the last rebalancing are allocated between the Risk-On and Risk-Off Vaults.
Risk-Off Vault's ETH reward share will be automatically converted to USDC and deposited on Aave to earn more interest.
Rage Trade's product design pursues a Delta-neutral investment strategy, and provides different profit strategies for users with different risk preferences through Risk-On and Risk-Off forms.
Compared to other Delta neutral vaults, Rage Trade's product design and volatility strategy are more complex. It refines the process of its predecessors, for example, DeCommas only buys half of USDC to purchase GLP and deposits the other half into AAVE to earn interest, in order to reduce risk exposure. And this design is precisely Rage Trade's main advantage.
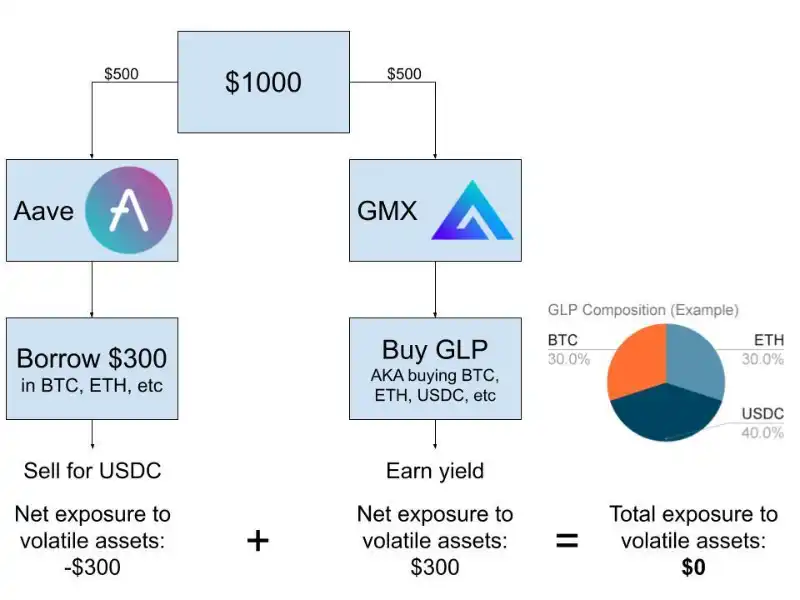
DeCommas Delta Vault Operation Mode
2、GLP Mortgage Loans and Stablecoin Minting
Due to the fact that GLP is composed of a basket of mainstream assets, with 50% of it being USDC, its volatility is relatively low, making it very suitable for use as collateral for mortgage loans.
We take Vesta Finance as an example.
Users can deposit GLP into Vesta Finance, and Vesta will directly stake GLP in GMX. Therefore, users will receive interest income from borrowing and lending, as well as dividend income from GLP (Vesta takes a 20% cut). Users who deposit GLP can also mint stablecoin VST, which can be used for collateral liquidation and liquidity mining. This greatly improves the capital efficiency of GLP holders. At the same time, the protocol expects to accumulate esGMX to increase the income of staking users.
Currently, Vesta Finance's TVL (Total Value Locked) is 22 million, and the number of VST minted is 8.75 million.
3、GLP Liquidity Certificate
Another way to improve capital efficiency is to create liquidity certificates, just like how Lido provides stETH certificates for ETH pledgers.
GMD Protocol is a good example.
It adopts a pseudo Delta-neutral strategy and provides investors with a vault product called "Delta-Neutral Vaults".
Investors can pledge USDC, ETH, and BTC to GMD Protocol's single currency vault. GMD Protocol will compound users' investments, and users will receive gmdUSDC, gmdETH, and gmdBTC as asset certificates. GMD Protocol will encourage users to earn additional income through these tokens. When users choose to withdraw, they can exchange their gmdTokens for USDC, ETH, BTC, and additional income.
Does GMX have competitors?
The answer is yes.
Vela Finance is a perpetual leverage trading platform that has launched its liquidity supply product VLP. Compared to GMX, the asset category in VLP only includes USDC. Users only need to collateralize USDC to obtain VLP. As there are no volatile assets, VLP holders only incur losses when traders make profits. The income of VLP holders comes from the losses of traders and 60% of the trading fees.
Due to its inherent Delta-neutral properties, VLP holders do not require other protocols to provide Delta-neutral strategies. Sections "2" and "3" in the previous text may be the parts that are based on innovation using VLP.
Vela Finance 如何与 GMX 竞争呢?
How does Vela Finance compete with GMX? It offers higher liquidity injection rewards and rewards VLP providers with native tokens. The event will begin on March 14th. The VLP treasury, currently worth $2.5 million, has already been filled.
However, compared to GMX, which has already established a leading position and moat, Vela Finance, which has just started, still has a long way to go. In the short term, especially when the GLP derivative agreement has become mature, VLP cannot pose a threat to GLP. The real threat to GMX's market share comes from Gains Network, which uses the DAI treasury.
Due to the nature of synthetic assets in the DAI treasury, Gains Network provides users with more trading pairs (cryptocurrencies, forex, and stocks), higher leverage, and complex risk management mechanisms with high capital efficiency. Thanks to this, Gains Network will be able to compete with GMX, which adopts full asset protection - now deployed on Arbitrum.
DAI Vault is similar to GLP in principle, but does not have the high scalability of GLP. However, on December 8th of last year, Gains Network announced a new vault strategy: users will receive gToken after depositing assets into the vault. If we deposit DAI into the vault, we will receive gDAI tokens. The redemption price of gToken will be affected by accumulated fees and unrealized trading PnL measurement data. The principle is similar to VLP, but more complex than VLP. Subsequently, Gains Network will also set up liquidity lock-up incentives.
Due to the more complex and Delta-neutral nature of the gToken model, it increases the difficulty of building products based on it, and it is highly unlikely to become a trend among developers.
Final
The GMX and GLP derivative agreement is a win-win collaboration, with GMX providing investors with low-volatility LP Tokens and the GLP derivative agreement offering GLP holders a more capital-efficient and higher hedging return strategy. The GLP launched by GMX not only feeds the GLP derivative agreement, but also drives GLP to continue to expand its share and establish a strong liquidity moat for GMX. Challengers in the spot/futures leverage trading arena can only attract liquidity providers through higher incentives, as seen with Vela Finance. Perhaps only with the emergence of innovators in this arena will there be a chance to truly threaten GMX's leading position in the future.
Original article link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia







