Arthur Hayes: Review of the Crypto Lehman Incident and the Future of Crypto
Original title: "Speechless"
Original author: Arthur Hayes
Original translation: MarsBit
I have nothing to say...
Just kidding!
I actually have a ton of things to say to you.
A few days ago I asked a question on Twitter wondering who would be the Lehman Brothers of this crypto credit cycle.
Many people said it would be FTX, and to be honest I just laughed it off. I never believed they would fall - and yet, here we are. The trigger for their downfall is the same as always - a good business that overextended itself, through cheap credit secured by high and rising valuations of assets on its balance sheet. As money became more expensive, the cycle began to turn, exposing their nakedness.
This post is a simple story. I will go through the tweets and public statements one by one. I intend to read between the lines and give my opinion on how this all happened and what the future holds. To that end, I believe the last candle of this crypto bear market is coming soon, and we will emerge from it with less futility and more opportunity for those who survive.
Before we begin, I sincerely believe that Sam Bankman-Fried (SBF) is a trading genius of a generation. Even though he just blew himself up, there is something about the empire he built that is hard to come by. I have to give more credit to Baron CZ - when news broke that Binance might acquire FTX, I sent CZ the following message:
"I fucking love you man. Big shot, Rushby."
Let's get started.
This was all a dream, I used to read Coindesk Magazine...
It all started with a Coindesk article featuring details of a leaked Alameda balance sheet.
The financials crystallized what industry observers already suspected. Alameda is big. As of June 30, the company had $14.6 billion in assets. Its single largest asset: $3.66 billion in “unlocked FTT.” The third-largest item on the asset side of its accounting books? A pile of $2.16 billion in “FTT collateral.”
Among its $8 billion in liabilities, there are even more FTX tokens: $292 million in “locked FTT.” (Most of that is $7.4 billion in loans.)
It’s fascinating to see that the majority of the net assets of the Alameda business are actually tokens that FTX centrally controls and prints itself, said Cory Klippsten, CEO of investment platform Swan Bitcoin, who is known for his critical views on altcoins, referring to cryptocurrencies other than Bitcoin (BTC).
Alameda CEO Caroline Ellison declined to comment. FTX did not respond to a request for comment.
Other significant assets on the balance sheet include $3.37 billion in “cryptocurrency holdings” and a large number of Solana blockchain native tokens: $292 million in “unlocked SOL,” $863 million in “locked SOL,” and $41 million in “SOL collateral.” Bankman-Fried was an early investor in Solana. Other tokens mentioned by name are SRM (a token from the Serum decentralized exchange co-founded by Bankman-Fried), MAPS, OXY, and FIDA. There is also $134 million in cash and equivalents and $2 billion in "equity securities investments."
Most of the assets on their balance sheet are illiquid FTT tokens and a bunch of shitcoins. Let's analyze why FTT is so important to the FTX/Alameda empire.
According to FTT’s stated tokenomics, FTX has pledged to buy back FTT with a third of all trading platform fees. SBF owns a majority stake in Alameda, and he keeps diluting his ownership of FTX to haul in capital from VC puppets. What these VC fools may not realize — or maybe they do, and that’s even worse for their investors — is that a large portion of FTX’s revenue is funneled from FTX to Alameda via Alameda’s large FTT stake. Presumably, Alameda received a large allocation of FTT for providing necessary market-making services to FTX, and for participating in FTT’s initial token offering.
Okay, that’s not ideal for FTX’s investors, but it’s not what’s going to deal a fatal blow to FTX’s solvency. The real question — and one that people are starting to ask after the Coindesk article — is whether FTX is lending money to Alameda (most likely in USD or a fiat stablecoin), and using Alameda’s FTT stake as collateral. If FTX did lend the funds, this isn’t an inherently fatal problem either — FTX is free to lend its retained earnings to whomever it likes. But the most pressingly relevant question is whether FTX rehypothecated customer deposits to Alameda, with FTT as collateral. And, as a subset of that, could a drop in the value of FTT or some of the shitcoins on Alameda’s balance sheet cause Alameda to go bankrupt as a result. Finally, if Alameda went bankrupt, did FTX lend money from customer funds to prop it up? Again, these are the questions people started asking after this article came out.
Lucas Nuzzi has an interesting theory about the connection between FTX, Alameda, and FTT. In short, he thinks Alameda blew up along with Three Arrows Capital and others, but FTX lent Alameda money to survive in exchange for FTT tokens that Alameda deserved by participating in the FTT ICO.
Then, CZ made his move.
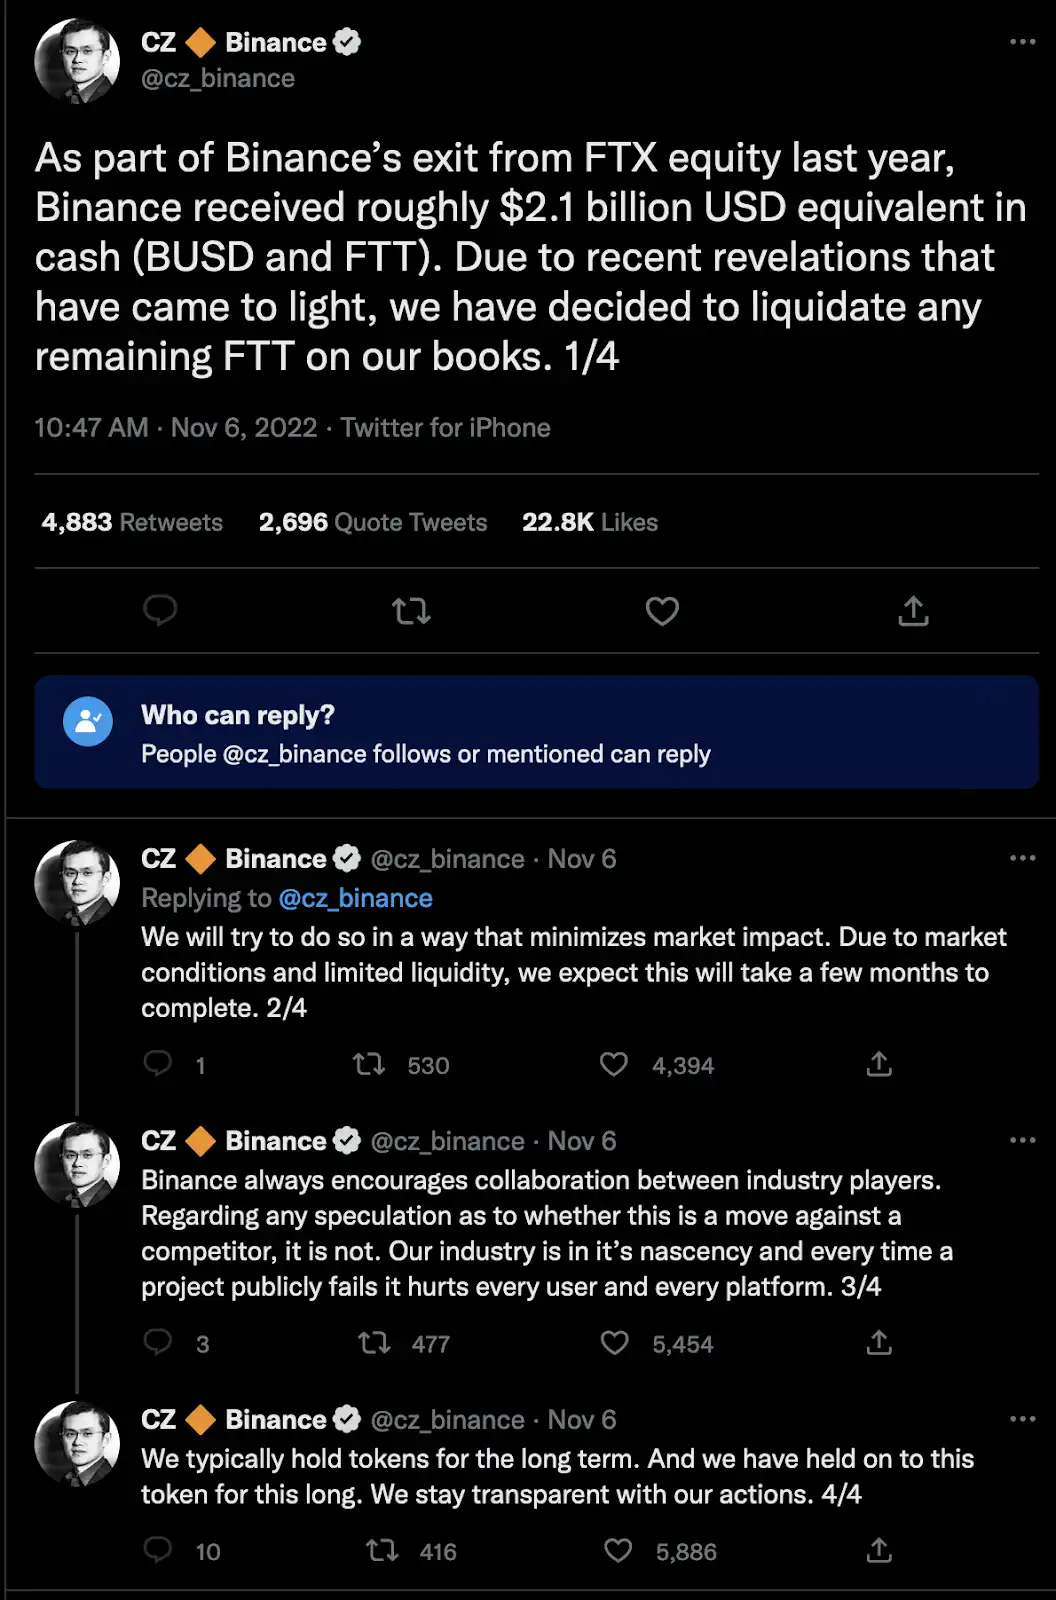
Presumably, CZ read the same article as the others and decided to dump Binance’s massive FTT holdings on the market. There was also apparently some bad blood between the two crypto barons.
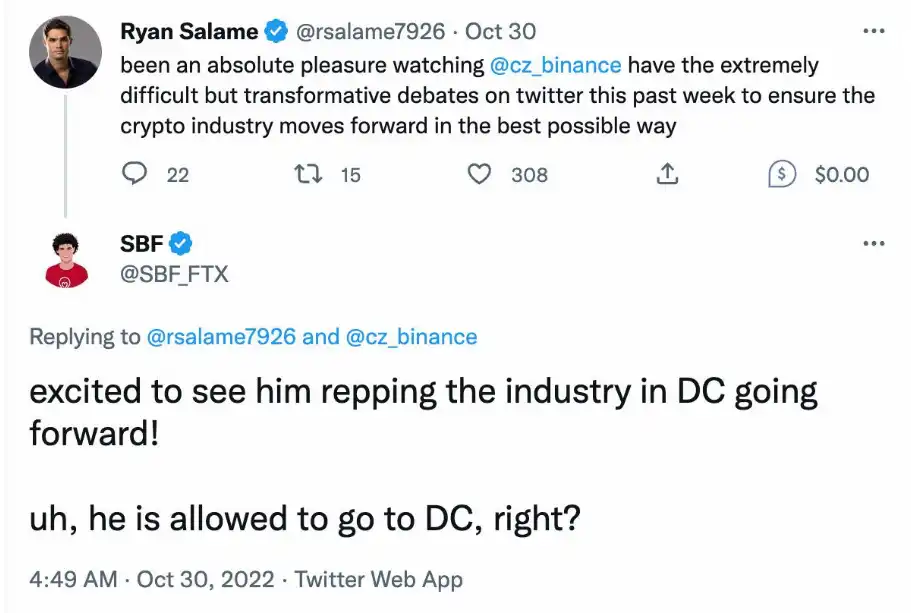
That’s not very nice, Sam.
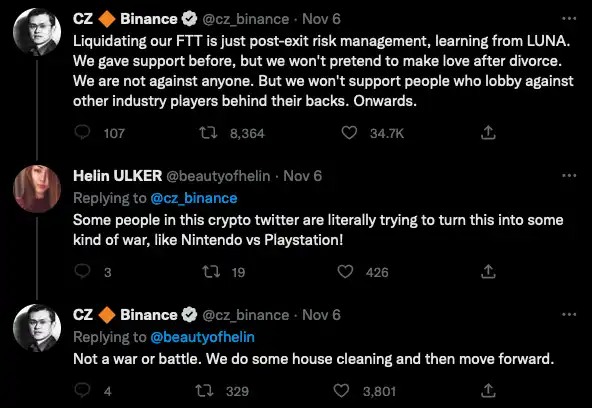
CZ not having sex after divorce…seems to make sense. I guess CZ and SBF had a bad breakup.
However, once CZ started voicing his concerns, alarm bells started going off in the minds of FTX depositors.
In crypto, when you have even a hint that a trading platform might be insolvent, you withdraw your funds immediately and ask questions later. Logic dictates that even if Alameda went bankrupt, FTX would have no problem processing all the withdrawals. They are two separate companies, and according to SBF, FTX’s customer deposits are not being reinvested — not even in ultra-safe U.S. Treasuries.
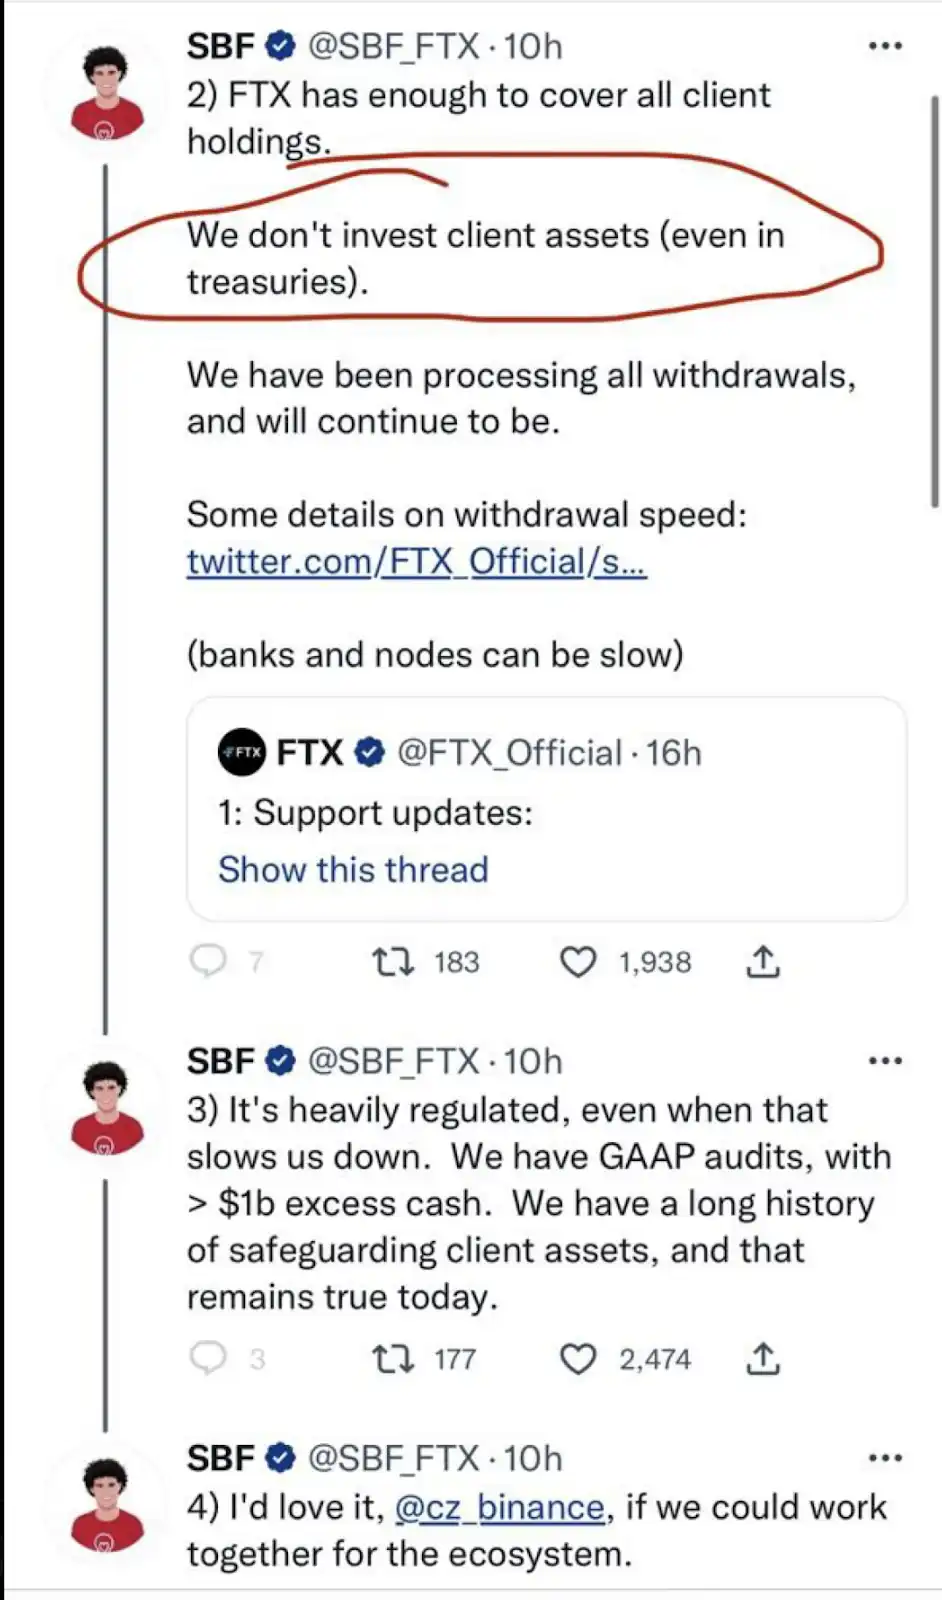
At this point, there’s no reason to believe SBF is lying. But even if it were, you wouldn’t just wait for your money to come out. So capital began a sprint to the exits.
As always, whoever sold first sold best. Those who withdrew their funds immediately got them back quickly. But as Monday bled into Tuesday, FTX’s withdrawal processing ground to a halt — all the while the price of FTT continued to plummet. The market was clearly trying to figure out if there was an FTT margin call to punish Alameda for overextending itself.
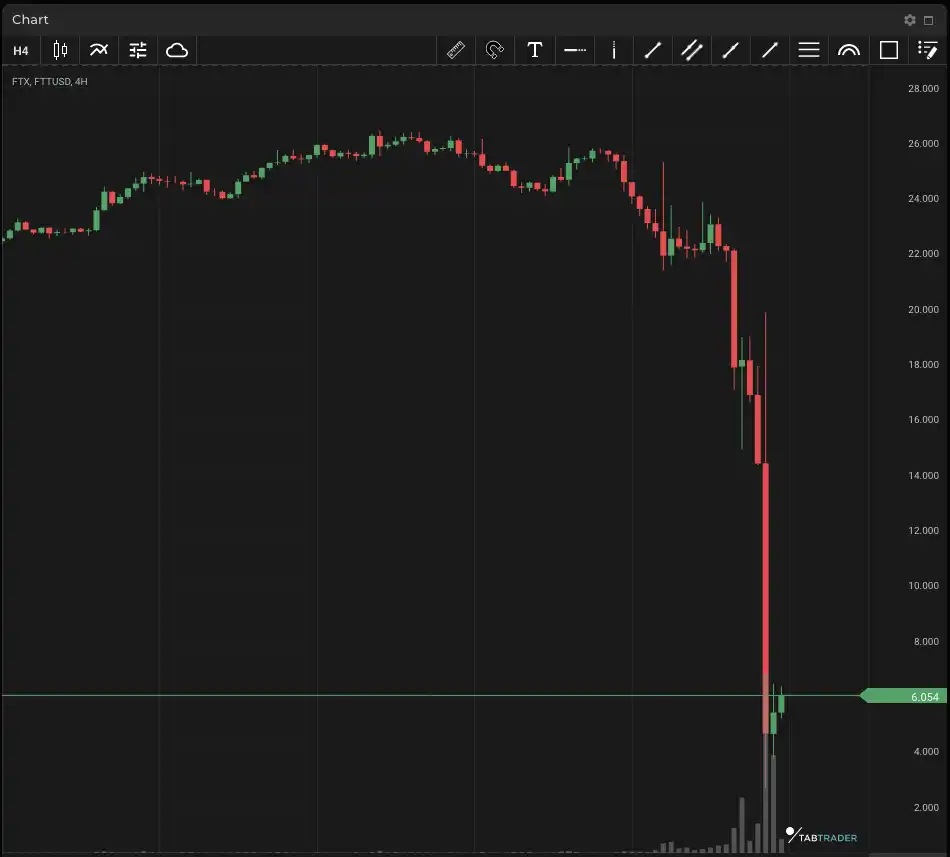
On Tuesday, I woke up to messages from many friends spreading rumors speculating that FTX may have been playing a joke on its customers. I prayed to Lord Satoshi that FTX had not reached into its customers’ cookie jar.
Then, this bombshell hit the electromagnetic ball:
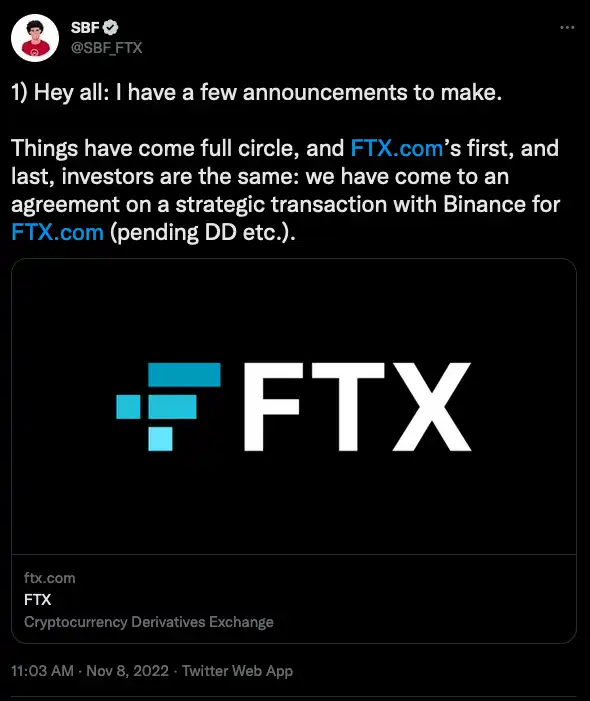
This crazy announcement provides possible answers to many questions.
Did FTX rehypothecate customer funds, or euphemistically "effectively" use said funds?
We don't have a definitive answer to this question. However, Binance signed a non-binding letter of intent to purchase all of FTX and promised to try to pay off all customer deposits in full. This suggests that FTX has a run on its deposits and cannot meet all customer withdrawal requests. Otherwise, why did FTX need a bailout from Binance? FTX could have blown off all the VC ragdoll powder supporting Alameda, and it still wouldn't have impaired their ability to meet withdrawals - unless they were immersed in a honeypot.
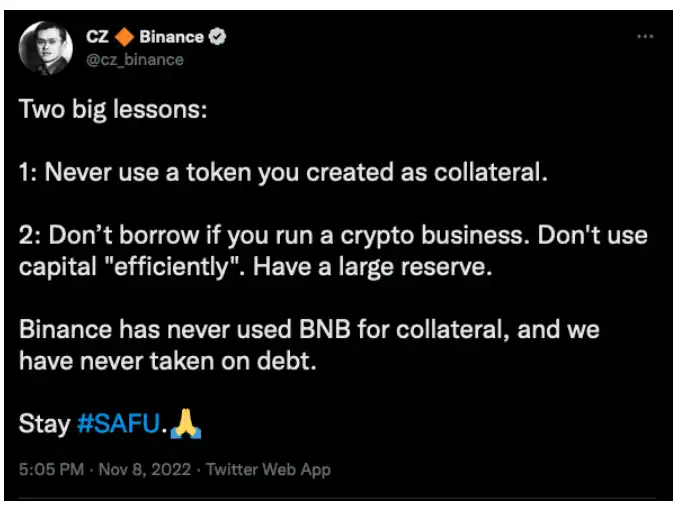
“Two important lessons.” Hmm… not sure what scenario he’s referring to? Baron CZ is clearly suggesting that FTX may have done something shady with customer funds, and therefore had their hands in the cookie jar when the bank run occurred.
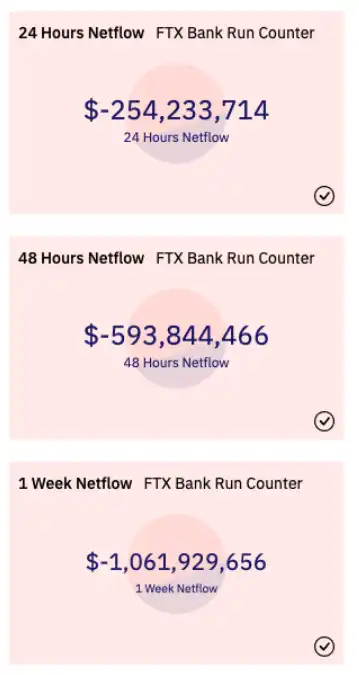
$1 billion in deposits fled FTX last week. Here’s what led to this horrible turn of events. And these are just the withdrawals that were processed. We have no idea how many poor souls are still waiting for their money to come back.
Is Alameda insolvent or bankrupt?
We don’t have a definitive answer to this question. However, if FTX needed a bailout from Binance, and because FTX allegedly provided financial help to Alameda, then we can assume that Alameda may also be donezo.
I’ll leave you with the words of Carolyn Ellison, CEO of Alameda.
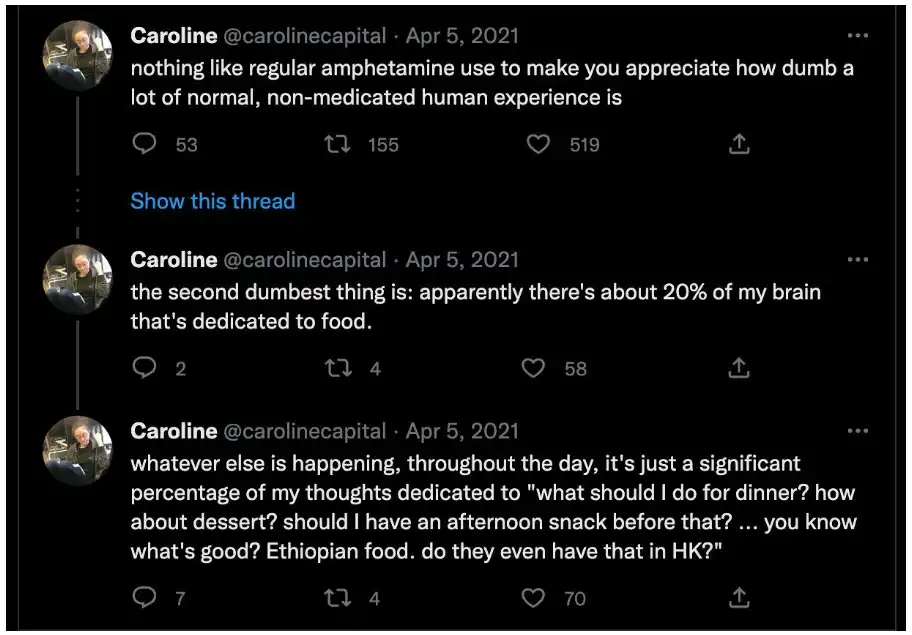
I’m sure she’s putting 100% of her brain into saving everything at Alameda.
Will the deal really go away?
A non-binding letter of intent is nice, but a firm commitment from Binance to buy FTX and lock up all of its liabilities would be better. I imagine Binance’s corporate finance folks are busy digging into the financials of FTX and Alameda. If the hole is too big, then I expect Binance to walk away from the deal. No one can afford to take a huge loss from FTX if Binance can’t or won’t do the deal.
What if FTX can’t find a new home?
Similar to Mt Gox, we could be heading into another high-profile bankruptcy situation where depositors line up to recover what they can. This could be a long or short process, but given the complexity I believe holding FTX entails, recovery of any portion of deposits could take a long time.
Obviously, this is a travesty in itself. But when looking at the broader market impact, the bigger question is:
What companies operating crypto loan books have been exposed to FTX and/or Alameda?
SBF is the original credit in all of crypto. He is a pioneer in the IT crypto space. His beautiful angelic features have graced the pages of the most prestigious mainstream financial magazines. His skin gleams like someone who only eats carrots and cucumbers. He can do no wrong - investing with anything SBF touches is a surefire path to wealth. Look at the Solana boom!
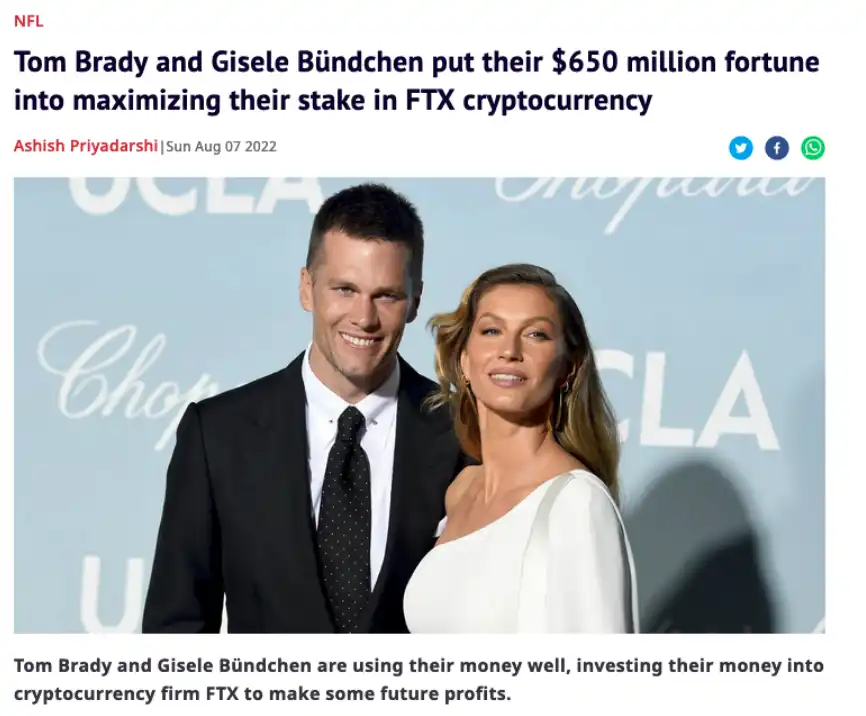
SBF even got Tom Brady to YOLO onto FTX, oops!
So you can imagine that if FTX potentially used customer funds to save Alameda, both entities probably used their good reputations to borrow as much money as possible to stay afloat in the dying months. Therefore, this possible default may well have infected the loan books of the remaining major centralized lenders.
Given this potentially significant exposure, the question becomes - can the largest centralized lenders survive:
Cannot stop, and will not stop Jay Powell, who is determined to beat inflation by continuing to raise short-term rates and reduce the size of the Fed's balance sheet? The implosion of LUNA/TerraUSD? The bankruptcy of Three Arrows Capital? And now, the possible bankruptcy of FTX and Alameda?
Problems 1) through 3) are the “legendary” centralized lenders that have died, like Celsius, BlockFi, and Voyager. There are probably a handful of zombies left — I won’t name them here, but anyone thinking critically can speculate who might come under pressure next.
It was bad enough that FTX and Alameda bit the dust. That was our Lehman Brothers — but who was AIG? Who was CountryWide? Fannie Mae and Freddie Mac anyone? Oh, they’re out there — hiding in plain sight.
It wasn’t until March 2009 that the S&P 500 bottomed during the 2008 global financial crisis. It was months after Lehman went bankrupt, and every independent US investment bank that received money from Warren Buffett or was swallowed up by a commercial bank who could legally use the Fed’s discount facility. It was supposedly after Treasury Secretary Paulson knelt down to Congresswoman Nancy Pelosi to secure passage of the Troubled Asset Relief Program (aka let’s print some fucking money and give it to the bankers). And finally, it was after Nobel Prize winner Ben “Helicopter Money” Bernanke announced that the Fed would engage in quantitative easing.
While I am extremely bullish on the prospects for crypto in 2023 (I know the dates keep slipping, but I reserve the right to change my mind in the face of market conditions), I believe we are about to trade to new lows as everyone wonders which crypto household name will go bankrupt from borrowing money from FTX/Alameda.
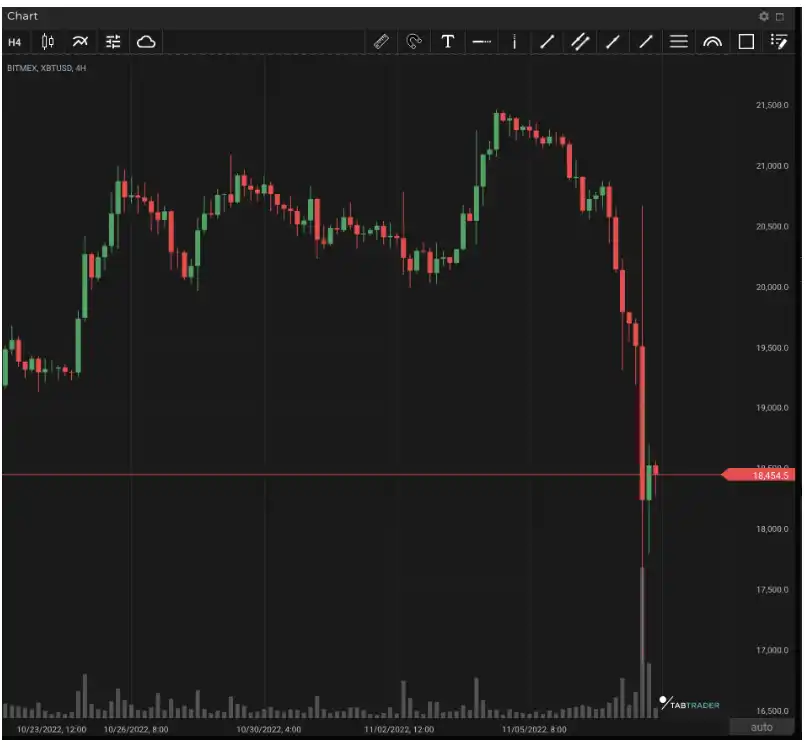
On BitMEX’s XBTUSD perpetual contract, Bitcoin fell to nearly $17,500. On various other spot trading platforms, Bitcoin experienced similar declines, falling to levels close to $17,000. Be prepared for lower times, because it’s coming. But the good thing about crypto is that no central bank is going to bail out the balance sheets of reckless companies with newly printed fiat shitcoins. The crypto industry will be forced to eat its humble pie quickly — leading to a rapid recovery that will make it stronger than ever.
Before I end this post, let me be clear: centralized exchanges will always face these kinds of trust issues on behalf of their customers. FTX is not the first high-profile exchange to fail, and it won’t be the last. But throughout all of this, blocks on Bitcoin, Ethereum, and all other blockchains are still being produced and validated. Decentralized money and finance have and will continue to survive and thrive in the face of the failure of centralized entities.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles