$115 billion all-stock merger: why are Marvell and Lumentum both falling together?

TL;DR
· Marvell announced on November 2 that it will acquire Lumentum in an all-stock deal, with an implied enterprise value of approximately $115 billion, and Lumentum shareholders will receive 4.5 Marvell shares per share.
· On the announcement day, Marvell fell about 13% and Lumentum fell about 19%, as the market balked at the consideration of about 33 times core profit, the all-stock payment, and a closing window that could stretch to 2028.
· Related tickers: MRVL, LITE; watch AVGO, NVDA, COHR.
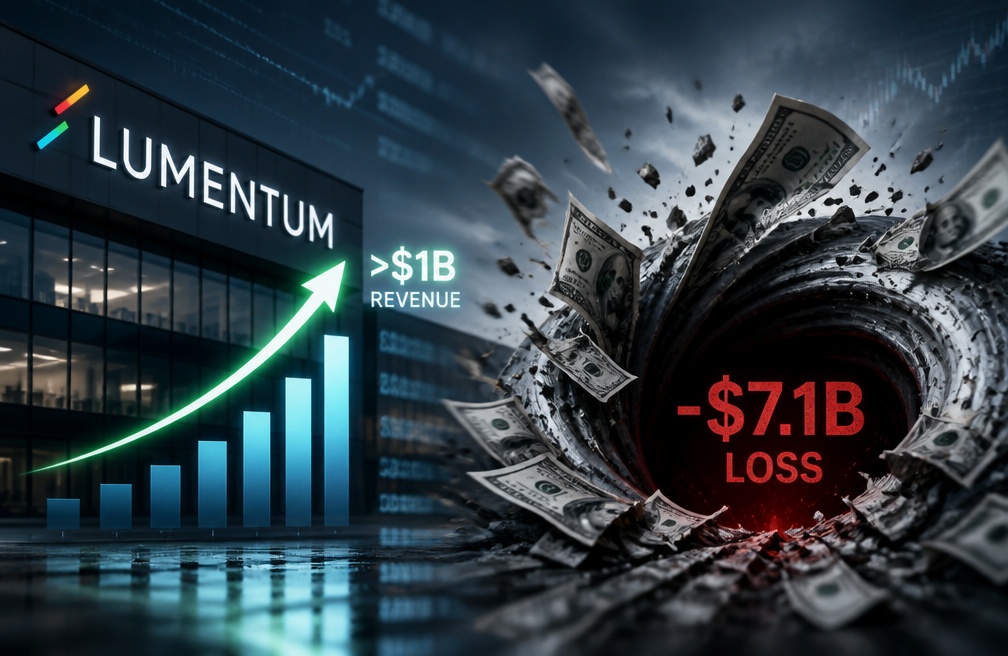
On November 2, Marvell announced the acquisition of optical component company Lumentum in an all-stock deal, with an implied enterprise value of approximately $115 billion. On the day the news was announced, Marvell closed down about 13% and Lumentum fell about 19%, making a transaction both sides called strategically complementary send both buyer and seller lower.
Based on the unaffected closing price on October 28, the consideration equates to $1,132 per share, a premium of about 23.9%. The $115 billion is enterprise value, including net debt, corresponding to an equity value of about $102.5 billion. Lumentum shareholders are receiving 4.5 Marvell shares per share, not cash. As Marvell fell, the consideration was revised down accordingly, and the implied consideration based on the announcement-day share price has dropped to $770 to $778.
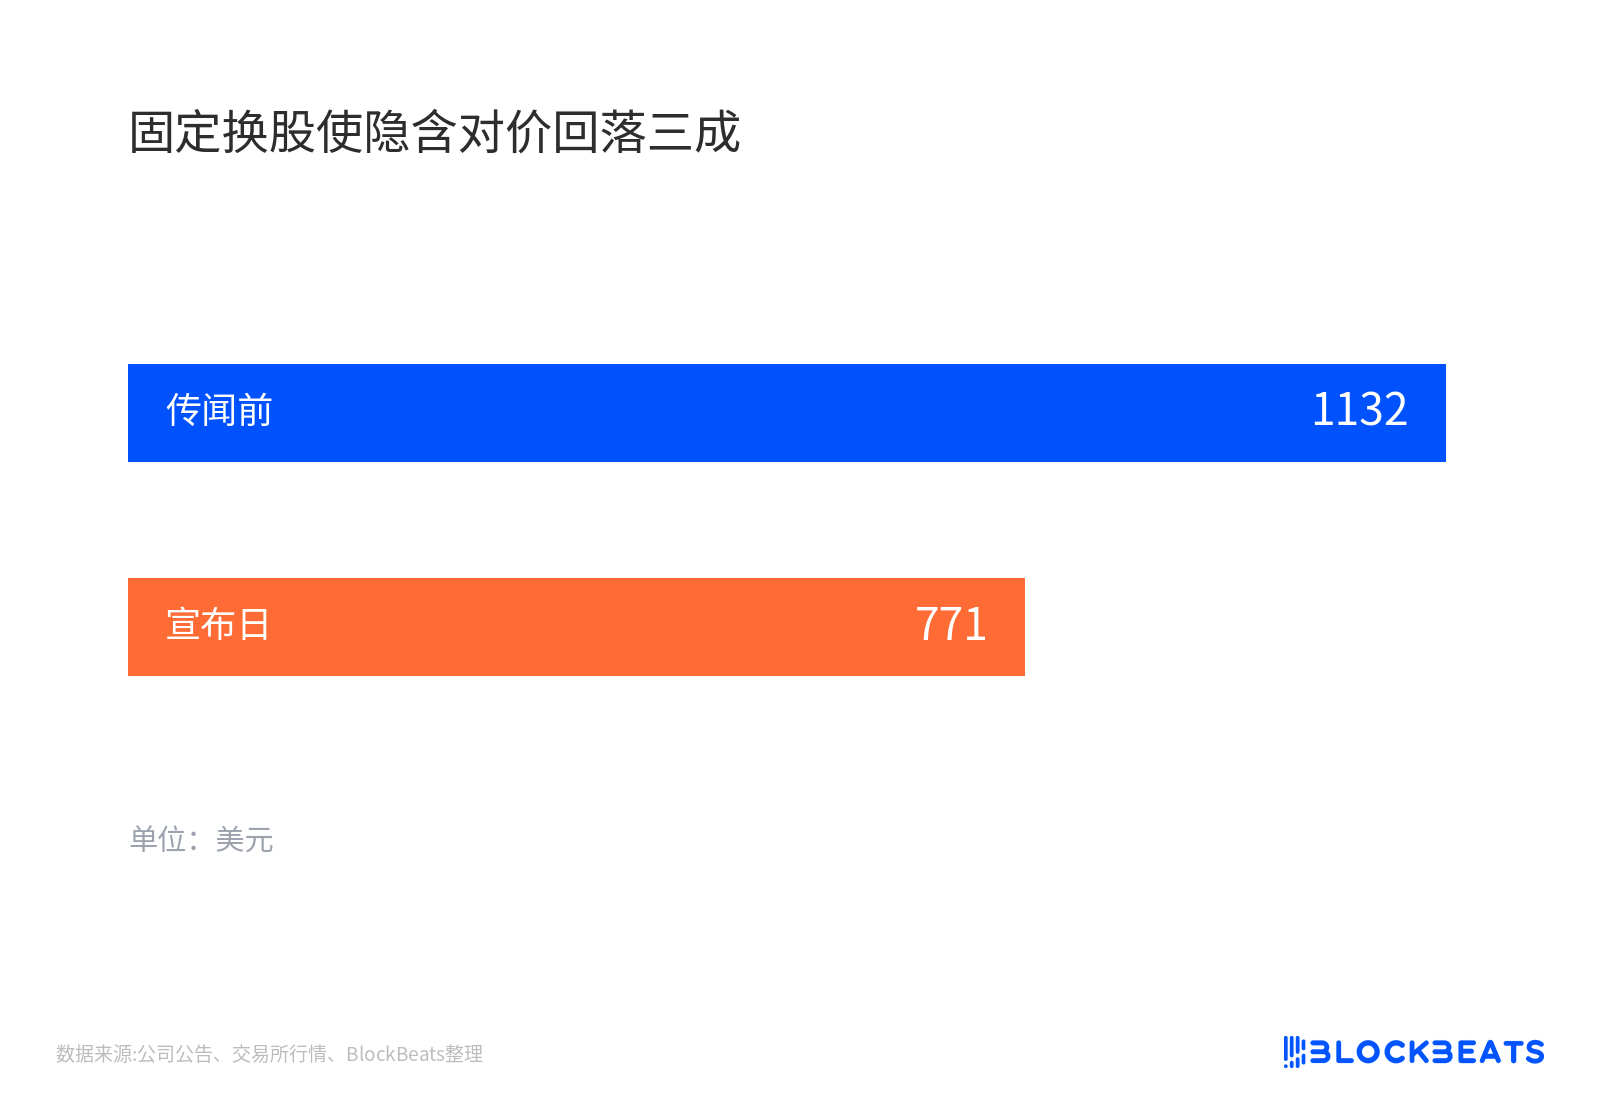
Fixed exchange ratio pulls implied consideration down by three-tenths
No one questions the direction of optical interconnect. What the market is selling off is the price, the payment method, and the closing timeline.
Optics moves into packaging, who sells electrical and who sells optical
In AI clusters, data volumes between chips and between racks are growing larger and larger, and copper wire is increasingly struggling on bandwidth and power consumption. The focus of discussion has shifted from "how much longer can copper hold up" to "when will optics move next to the package." CPO (attaching optical modules next to the chip package) and NPO (near-packaged optics) are the two main routes, while OCS (using optical switches to route lines) handles inter-cluster connections.
Marvell sells the electrical side: DSPs, switch chips, and custom accelerator chips. Lumentum sells the optical side: indium phosphide lasers, optical modules, and optical switches. Broadcom does both sides, while Marvell has only half, so buying Lumentum is equivalent to putting laser capacity, a co-design entry point, and optical switches into the same company.
Marvell Chairman and CEO Murphy called this a generational migration of AI infrastructure toward optical interconnect, where electrical and optical must be seamlessly co-designed. Lumentum President and CEO Hurlston said that after the merger the combined company can cover interconnect across all distances, and laser capacity is already sold out into early 2029.
Nvidia cannot be avoided. In March 2026, it invested $2 billion each in two companies, accompanied by multi-year laser procurement and custom chip partnerships. But Nvidia made no statement on this merger—it is a co-shareholder, not a endorser of the deal.
The market is punishing the stock-swap, valuation, and closing window
The most direct layer is the stock-swap structure. 4.5 shares for 1 share is a fixed ratio, not locked-in $1,132 cash. Marvell fell 13%, and Lumentum shareholders' consideration shrank by 13% in tandem. Sellers haven't received the shares yet, but they're already bearing the downside of the buyer's stock price.
Valuation is the second layer. According to LSEG calculations, the consideration is about 33 times Lumentum's core operating profit for the next 12 months, versus a semiconductor peer median of about 16 times. Using one's own high-flying stock to buy a more expensive asset—the books say "23.9% premium," but what's actually being paid is overvalued shares.
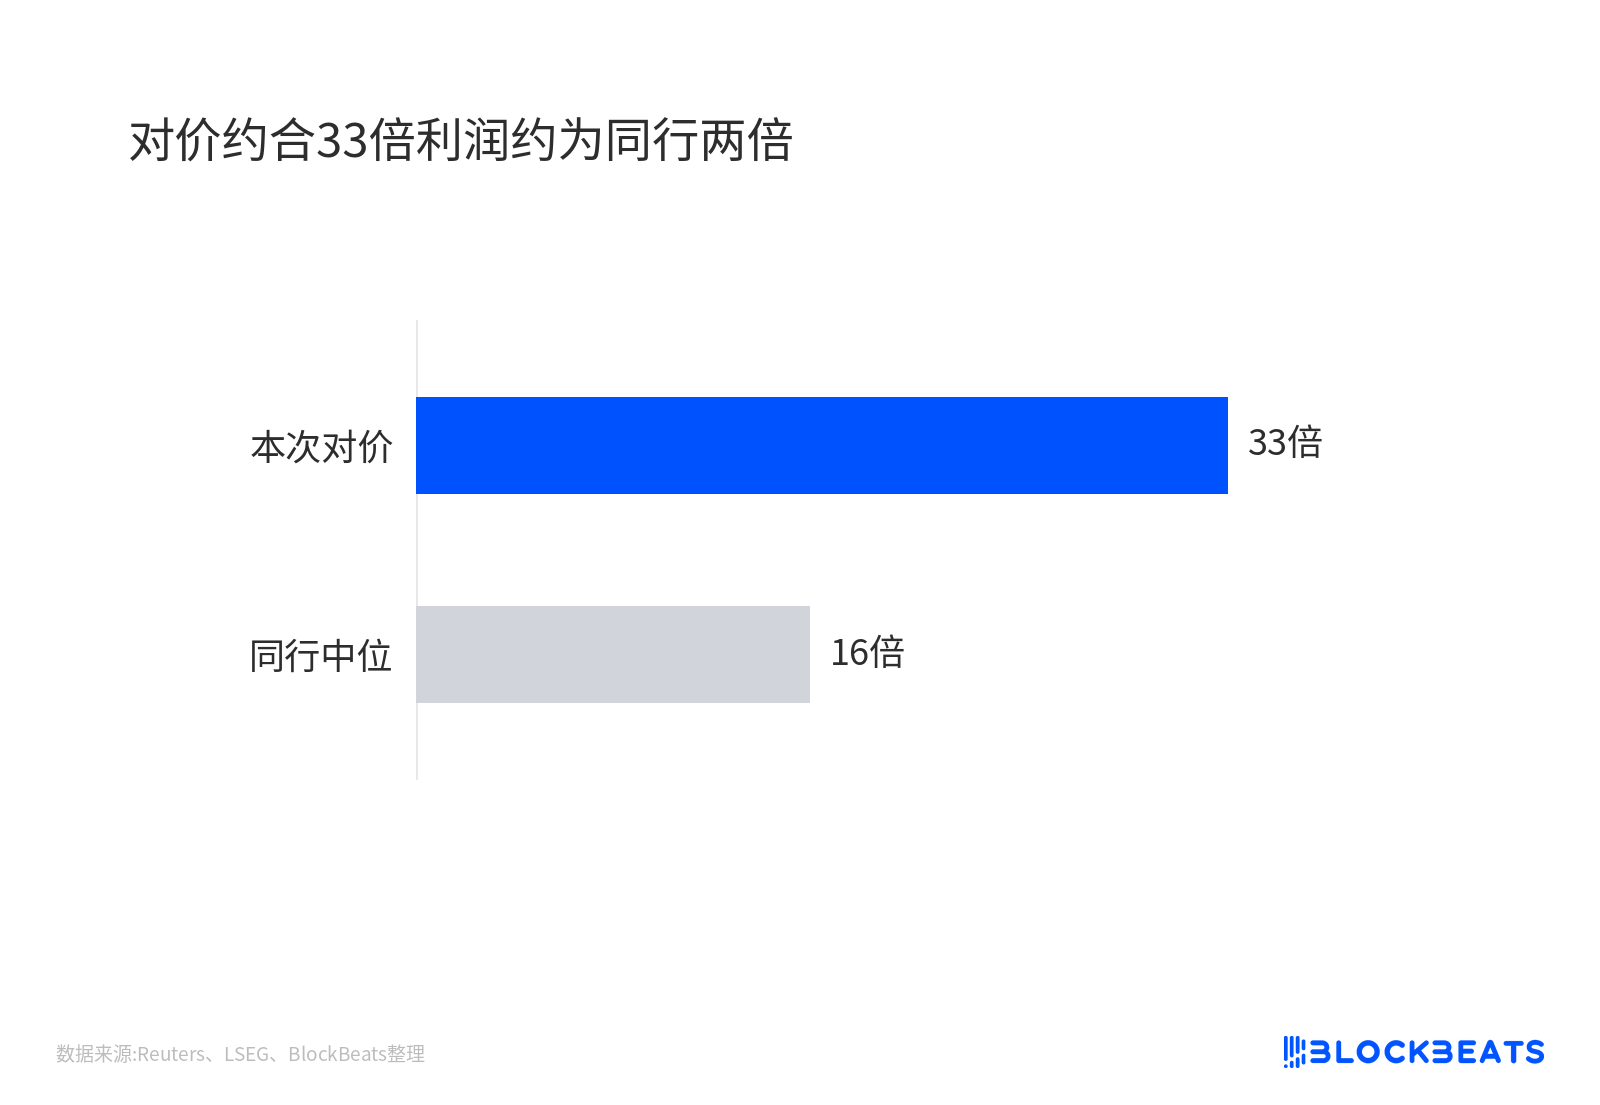
Consideration at about 33x profit, roughly twice that of peers
Time stretches the math. Closing is expected in the first half of 2028, with a regulatory extension window lasting as long as August 2028 in between. If the deadline is missed or regulatory approval fails, Marvell pays a $3.2 billion termination fee; if the board changes its mind, $5.8 billion; Lumentum pays $2.9 billion in the equivalent scenario.
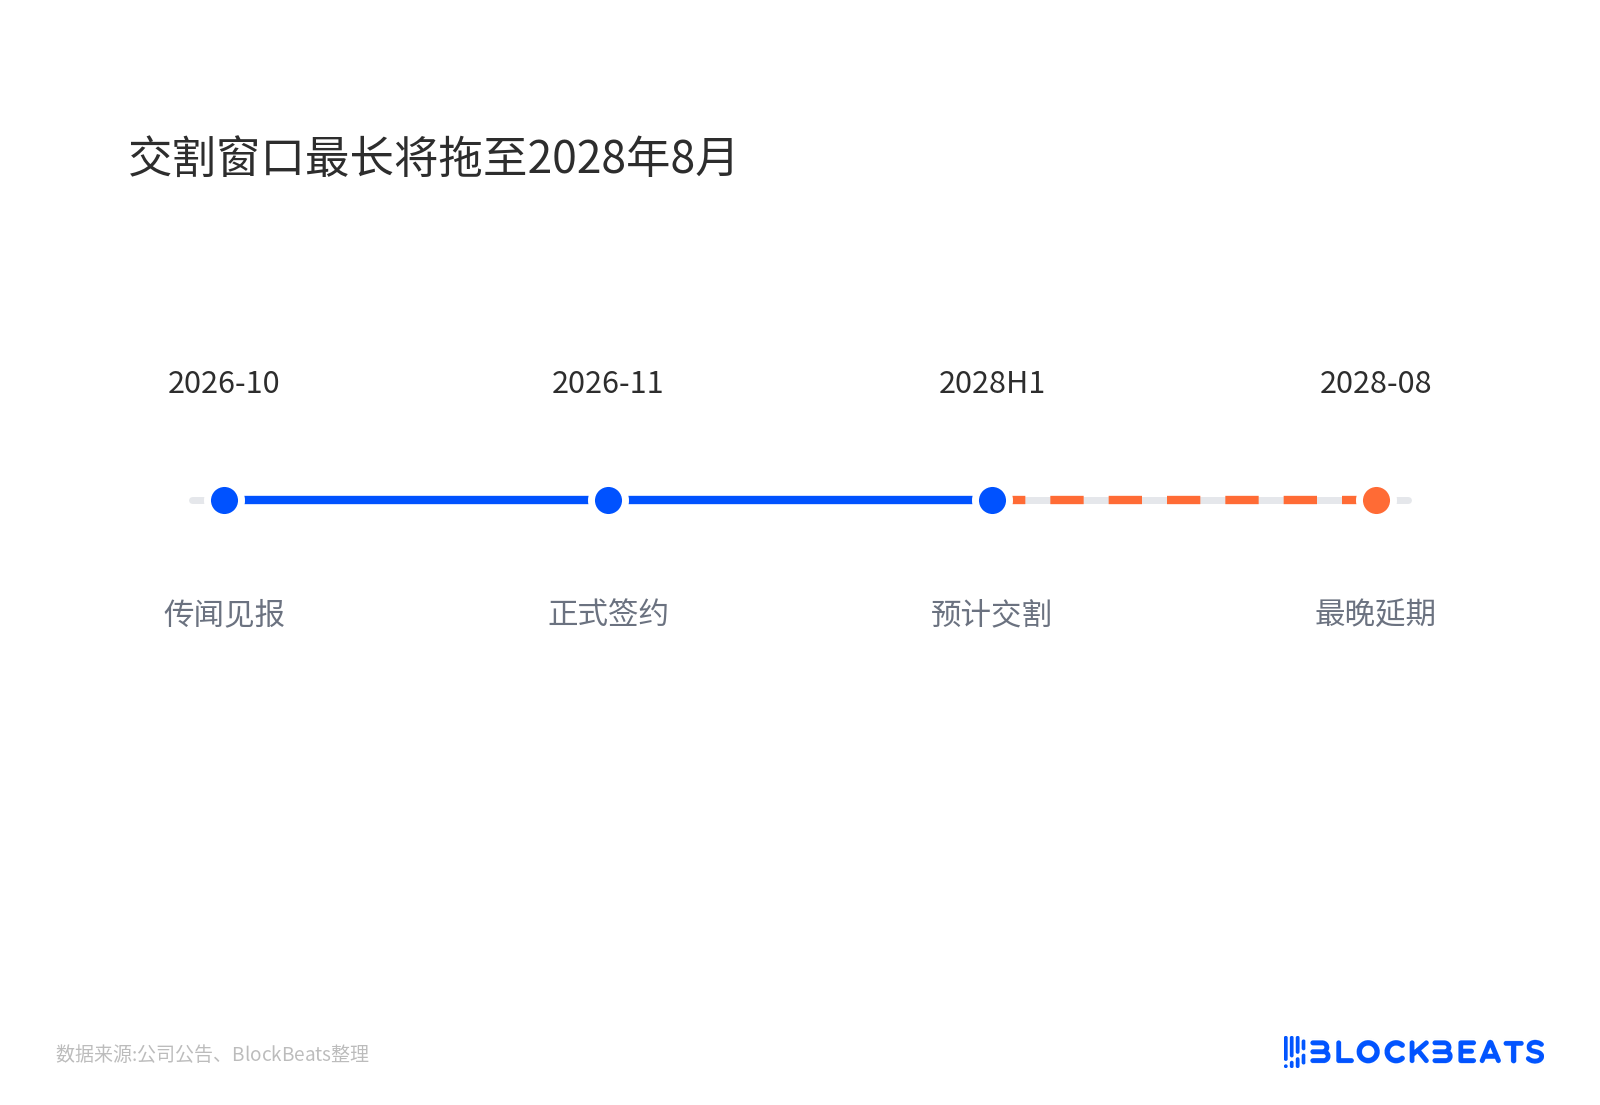
Closing window could drag out as long as August 2028
BofA's Vivek Arya downgraded Marvell from Buy to Neutral that day, cutting the price target from $400 to $225. The reasons had nothing to do with strategy: all-stock, protracted, limited accretion, and Lumentum's pluggable module business would create channel conflicts with module makers that procure Marvell DSPs.
Analysts are not unanimous. Raymond James's Simon Leopold upgraded Lumentum to Strong Buy, believing the selloff was overdone. Stifel's Tore Svanberg maintained Marvell at Buy, believing long-term synergies can absorb the dilution.
Lumentum's orders did not deteriorate on signing day
The numbers Lumentum gave the same day were quite strong. For the fiscal quarter ending September 26, 2026, revenue was $1.26 billion, up 136% year-over-year, with a non-GAAP operating margin of 42.3%.
Guidance for the next quarter is revenue of $1.575 billion to $1.625 billion, with an operating margin of 45% to 46%. In the quarter, it secured its second major CPO/NPO project, with purchase commitments exceeding $5 billion, and optical switch demand points to potential billion-dollar-level annual revenue.
Marvell's stated figure is more than $1 billion in annualized cost synergies after the merger, mainly from cost of goods sold, accretive to Marvell's non-GAAP earnings per share in the first year after closing, with combined annual revenue exceeding $21 billion.
These numbers show that industrial capital recognizes the direction of the deal, and the strength of the seller's assets has not deteriorated as of the signing date. What has worsened is the payment method. Marvell is using stock valued at 33 times to acquire a faster-growing, smaller asset, while selling a regulatory option of up to 18 months to shareholders.
Stock-swap discount and Chinese approval not yet settled
Whether Chinese approval enters the required list is currently undecided. The public version of the agreement does not name China, but about 36% of Marvell's revenue comes from the Chinese market, and Lumentum's China and Hong Kong share is about 26.6%.
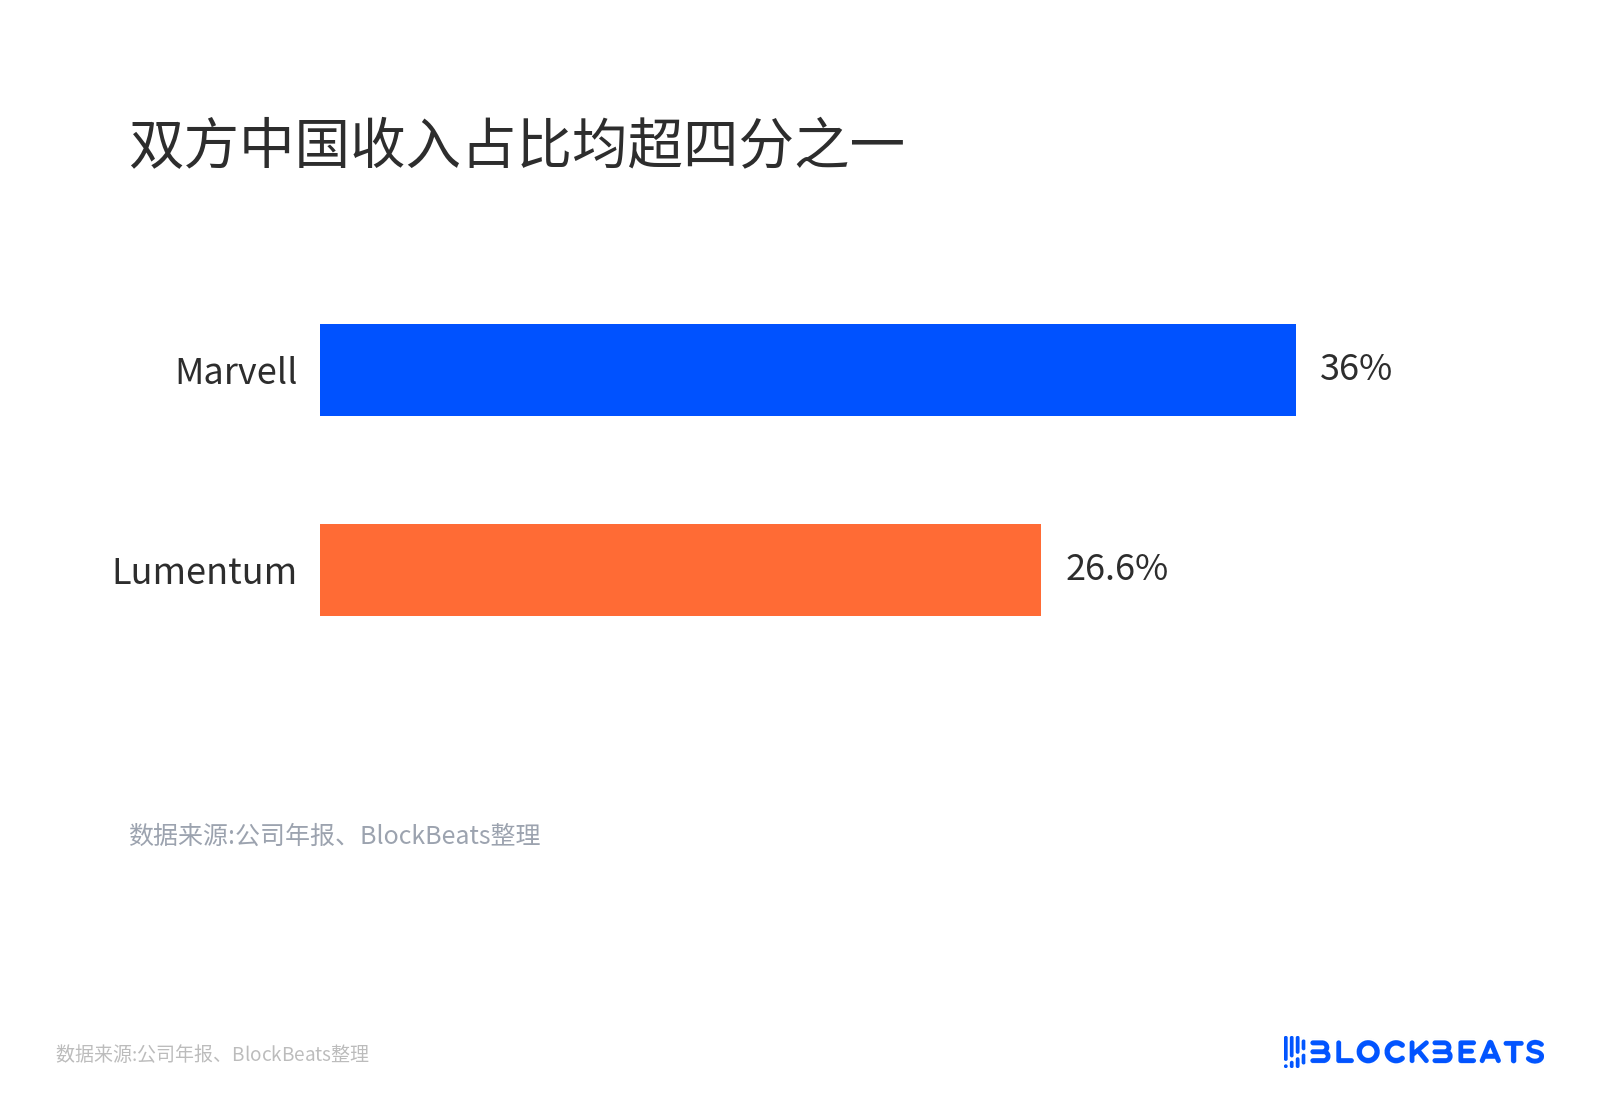
Both parties' China revenue share exceeds one quarter
Conditions commonly used by Chinese regulators include supply commitments and non-discrimination clauses, while under the agreement Marvell is not obligated to accept remedies that are material to the combined business. If approval comes with such requirements, a chunk of the strategic benefit would be cut away.
Stock-swap depreciation is another line. The $1,132 figure was based on the October 28 stock price, and the actual consideration on the announcement date has fallen to $770 to $778. If Marvell continues to slide, Lumentum shareholders will recalculate whether this stock swap is worth it when they vote.
Whether the discount can narrow depends on which of these two lines lands first. Consideration revaluation before the shareholder vote is the most direct; the lower the stock price, the harder it is to persuade the seller with the synergy story. The regulatory list and remedy conditions determine whether the deal can be completed under the original structure. Before closing in the first half of 2028, every word of the additional terms will rewrite the strategic benefit.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
 Related Articles