Arthur Hayes: "We may have already touched the cyclical bottom in the collapse of FTX."
Original Title: "PEMDAS"
Author: Arthur Hayes, Founder of BitMEX
Translated by: Mary Ma, Wu Shuo Blockchain
The current issue is whether the current price of Bitcoin has reached the "bottom". Bitcoin is the purest and most tested form of cryptocurrency, and although it may not be the cryptocurrency that falls the most, its role as a reserve asset in the cryptocurrency market will ensure that Bitcoin leads us out of the shadow of darkness. Therefore, we must pay attention to the price trend of Bitcoin to determine whether this market has bottomed out.
Three groups of people were forced to sell their bitcoins to true believers: centralized loan trading companies, bitcoin mining companies, and ordinary speculators. In each case, the abuse of leverage, whether in their business operations or in their use of leverage for trading financing, was the cause of the liquidation. As the yield on short-term US Treasury bonds rose from 0% in the third quarter of 2021 to 5% today, everyone suffered huge losses due to their super bullish beliefs.
After reviewing how leverage destroyed the positions of each group during the rise in interest rates, I will explain why I believe they have no more Bitcoin to sell and why in the long term, we may have already hit the low point of this cycle in the recent FTX/Alameda disaster.
In the final part of this article, I will list the ways in which I plan to trade at the possible bottom. To do this, I recently attended a webinar by my macro idol Felix Zulauf. At the end of the broadcast, he said some impressive words. He stated that investors and traders need to be aware of identifying tops and bottoms, but most people focus on the noise in the middle, and trying to identify the bottom is usually futile. Since I am doing this foolish job, I plan to try to call it in a way that protects my investment portfolio and minimizes errors in price and/or timing.
With this mindset, let's delve deeper into it.
Bankruptcy Proceedings
Most of us may not be as talented as the Alameda CEO (note: sarcastic reference to accounting chaos), so we have to learn math the hard way. Do you remember PEMDAS? It is the acronym for the order of operations when solving equations.
· P—Parentheses 括号
· P—Parentheses 括号· E—Exponents
· E—Exponents
· M—Multiplication
· M—乘法
· D—Division
translates to· D—Division
in English.· A—Addition 加法· S—Subtraction
· 减法
(Note: The original text is already in Chinese, so there is no need to translate it again.)In fact, decades after first learning this acronym, I still remember it, which demonstrates its stickiness.
However, equations are not the only things that have a specific order of static operations: bankruptcy (and the resulting contagion) also occurs in a very specific sequence. Let me first explain what this sequence looks like and why it occurs.
But before that, I have to admit that no one wants or intends to go bankrupt. Therefore, if I have offended those who have suffered losses due to SBF's wrongdoing, I apologize in advance. However, this fraudster has just been talking nonsense that others need to ask him to say. So the rest of this article will be interspersed with the sad plot that SBF is responsible for. Now, let's get back to the point.
Centralized lending companies (CEL) often go bankrupt because they either lend money to entities that cannot repay or have mismatched maturities on their loan books. The reason for the mismatch is that banks can receive deposits that can be withdrawn by depositors in a short period of time, but they use these deposits to make loans over a longer period of time. If depositors want their money back or demand higher interest rates due to changing market conditions, CEL will go bankrupt without the injection of some white knight companies and will soon be insolvent.
Before CEL becomes insolvent or goes bankrupt, they will try to raise funds to improve the situation. The first thing they will do is to try to recover all loans as much as possible. This mainly affects those who have borrowed money from them in the short term.
Imagine that you are a trading company borrowing money from Celsius. However, within a week, Celsius demands the return of these funds, and you have to comply. Being called back in a bull market is not a big problem for a trading company. There are many other CELs that will lend you funds so that you don't have to liquidate your existing positions. However, when the bull market fades and there is a credit crunch across the market, all CELs usually recall their loans at the same time. As no one can turn to additional credit, trading companies are forced to liquidate their positions to meet capital requirements. They will first liquidate their most liquid assets (i.e. BTC and ETH), hoping that their investment portfolio does not contain too many illiquid coins, such as Serum, MAPS, and Oxygen (like Alameda and 3AC).
After CEL retrieves all of its short-term loans that it can, it will begin to liquidate the collateral that supported its loans (assuming it actually required collateral, note: a dig at Voyager's unsecured credit). In the cryptocurrency market, prior to the recent implosion, the largest category of collateralized loans was secured by Bitcoin and Bitcoin mining equipment. Therefore, once things start to deteriorate, CEL begins to sell Bitcoin as it is the most commonly used asset for collateralized loans and the most liquid cryptocurrency. They also turn to the mining companies they lent to, requesting Bitcoin or their mining equipment, but if these CELs don't operate a data center with cheap electricity, the mining equipment is as useful as SBF's accounting skills (note: sarcastic dig).
Therefore, despite the ongoing credit crisis, we have seen a significant impact on both centralized and decentralized trading platforms from the large-scale sale of Bitcoin.
1. CELs attempts to avoid bankruptcy by selling Bitcoin pledged as collateral.
2. When trading companies see their loans being recalled, they must close their positions. This is why the price of Bitcoin will plummet before the bankruptcy of CELs. This is a big move. The second drop (if there is one) is driven by fear, that is, a company that was once considered unshakable suddenly begins to show a zombie-like posture and is about to liquidate its assets. This is often a smaller move, as any company facing bankruptcy risk is already busy liquidating Bitcoin in order to survive the collapse.
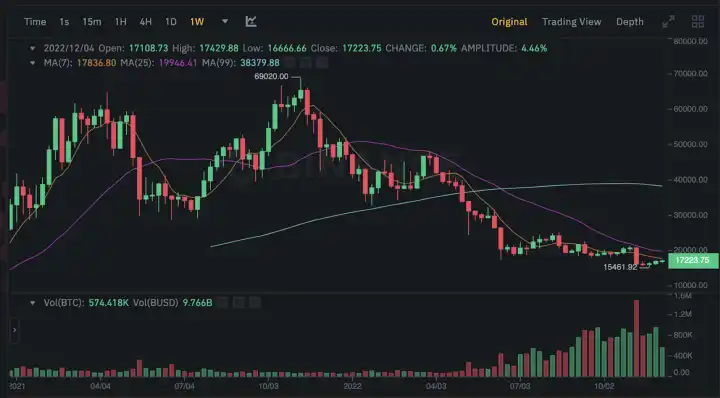
The trading volume of BTC/BUSD on Binance shown in the above figure indicates a significant increase during the two credit crises in 2022. It was during this time period that all of these legendary companies were gritting their teeth.
In summary, as CELs transition from being able to pay to being unable to pay, and eventually to bankruptcy, other ecosystem participants are also affected:
1. A trading company that borrowed short-term funds from CEL saw their loan being recalled.
2. Bitcoin mining companies often use Bitcoin, future mined Bitcoin, and/or Bitcoin mining machines listed on their balance sheets as collateral.
Two of the most ignorant cryptocurrency trading companies, Alameda and 3AC, have grown to such a large scale due to cheap borrowing. In the case of Alameda, the polite way to put it is that they "borrowed" from FTX clients, although others may call it theft. In the case of 3AC, they deceived vulnerable and desperate CELs into lending them money with little or no collateral. In both cases, banks believed that these companies and other trading companies were engaged in super-smart arbitrage trading, making these companies immune to market changes. However, we now know that these companies are just a group of corrupt gamblers who only go long. The only difference between them and the public is that they have billions of dollars to play with.
What did we see when these two companies were in trouble? We saw a large amount of the most liquid cryptocurrencies, Bitcoin (WBTC in DeFi) and Ethereum (WETH in DeFi), being transferred to centralized and decentralized trading platforms and then sold. This happened during a major downturn. When the dust settled, both companies were left with almost entirely illiquid junk coins as assets, as they were unable to raise the asset portion of their balance sheets above the liability portion. By looking at the bankruptcy filings of centralized lending institutions and trading firms, we are not entirely clear on what crypto assets are left. The documents lump everything together. Therefore, I cannot prove that all the Bitcoins held by these bankrupt institutions were sold off in multiple crashes, but it does appear that they did their best to liquidate the most liquid crypto collateral before going bankrupt.
CELs and all major trading companies have sold most of their bitcoins. Now, only illiquid junk coins, private equity of crypto companies, and locked pre-sale tokens remain. How bankruptcy courts ultimately deal with these assets is unrelated to the development of the crypto bear market. I am pleased to note that these entities have almost no excess bitcoins to sell. Next, let's take a look at Bitcoin miners.
Bitcoin Mining Companies
Electricity is priced and sold in fiat currency, and it is a key input for any Bitcoin mining operation. Therefore, if a mining company wants to expand, they either need to borrow fiat currency or sell Bitcoin on their balance sheet to pay for electricity. Most miners want to avoid selling Bitcoin at all costs, so they use Bitcoin on their balance sheet, unmined Bitcoin, or Bitcoin mining machines as collateral for fiat loans.
As far as we know, this situation occurred due to the massive decline in asset prices, especially in the bear market of cryptocurrencies, which, along with the rise in energy prices, squeezed the entire industry of miners. Iris Energy is facing default claims from creditors on a $103 million equipment loan. In September, Compute North was the first major participant to file for bankruptcy protection, and other large companies, including Argo Blockchain (ARBK), seem to be on the brink of solvency.
However, let's take a look at some charts to see how the wave of cryptocurrency credit tightening is affecting miners and what their reactions have been.
Glassnode has released a great chart showing the net change in Bitcoin held by miners over the past 30 days.
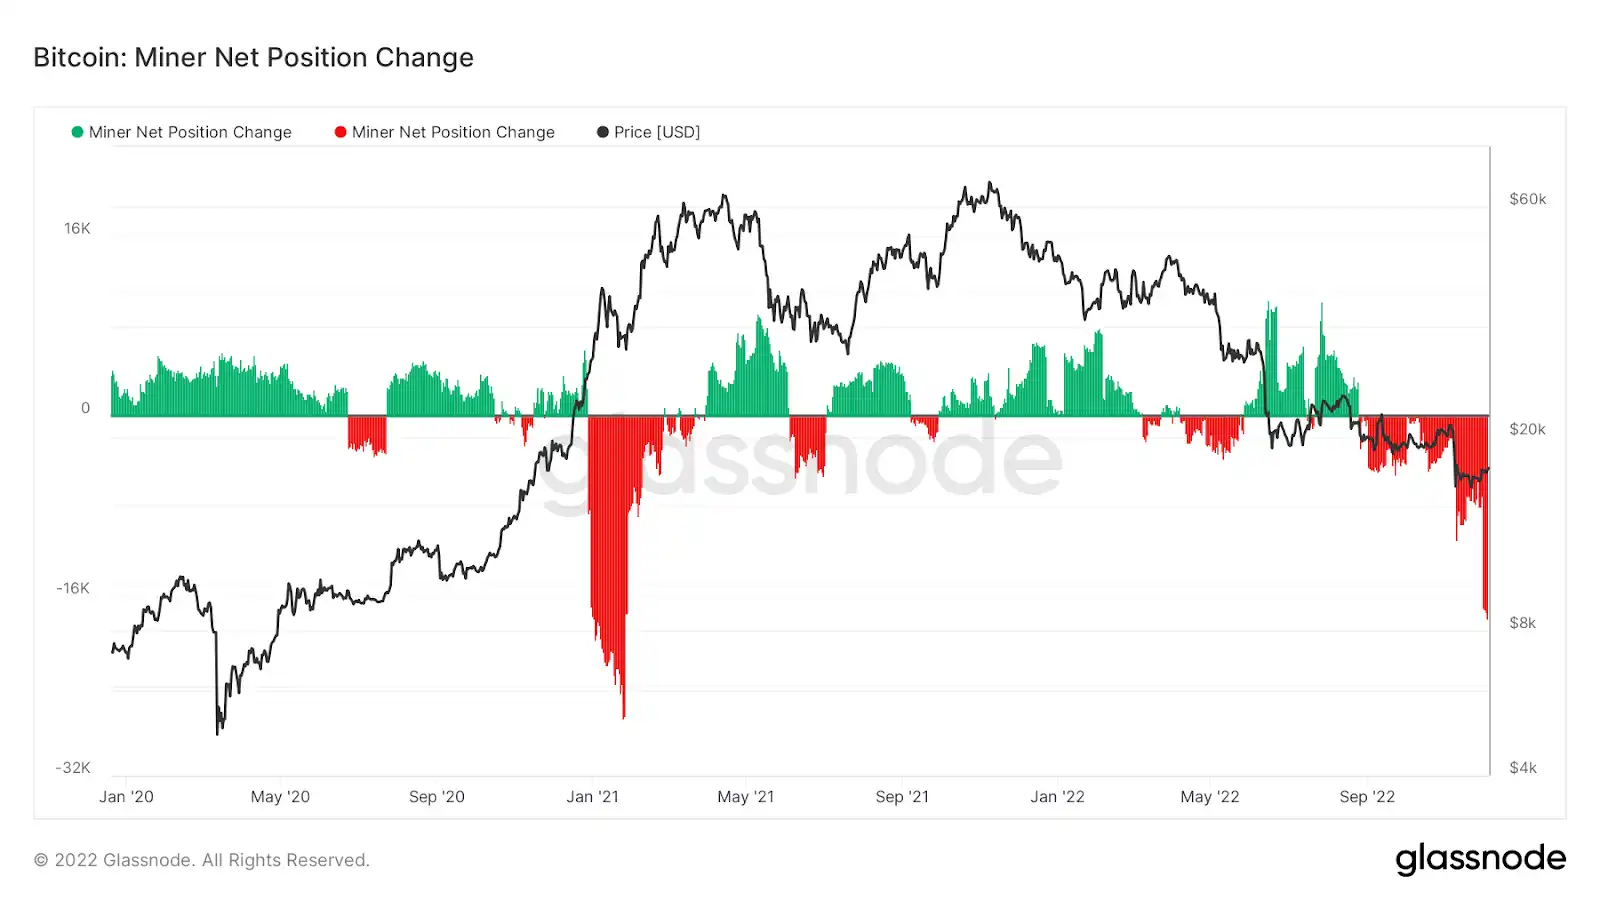
We can see that since the first credit tightening in the summer, miners have been net selling large amounts of Bitcoin. They have to do this in an attempt to maintain their large fiat debt burden. And even if they have no debt, they still need to pay for electricity, and with the price of Bitcoin so low, they must sell more Bitcoin to maintain the operation of their facilities.
Although we do not know, and will never know, whether the maximum net sell-off has been reached, at least we can see that in this situation, the behavior of mining companies is what we expect.
Some miners have not been successful, or they have had to reduce their operations. This is evident in the changes in computing power. I first calculated a rolling 30-day average of computing power. Then, I looked at the changes in this rolling average over the course of 30 days. I did this because computing power is quite unstable and requires some smoothing.
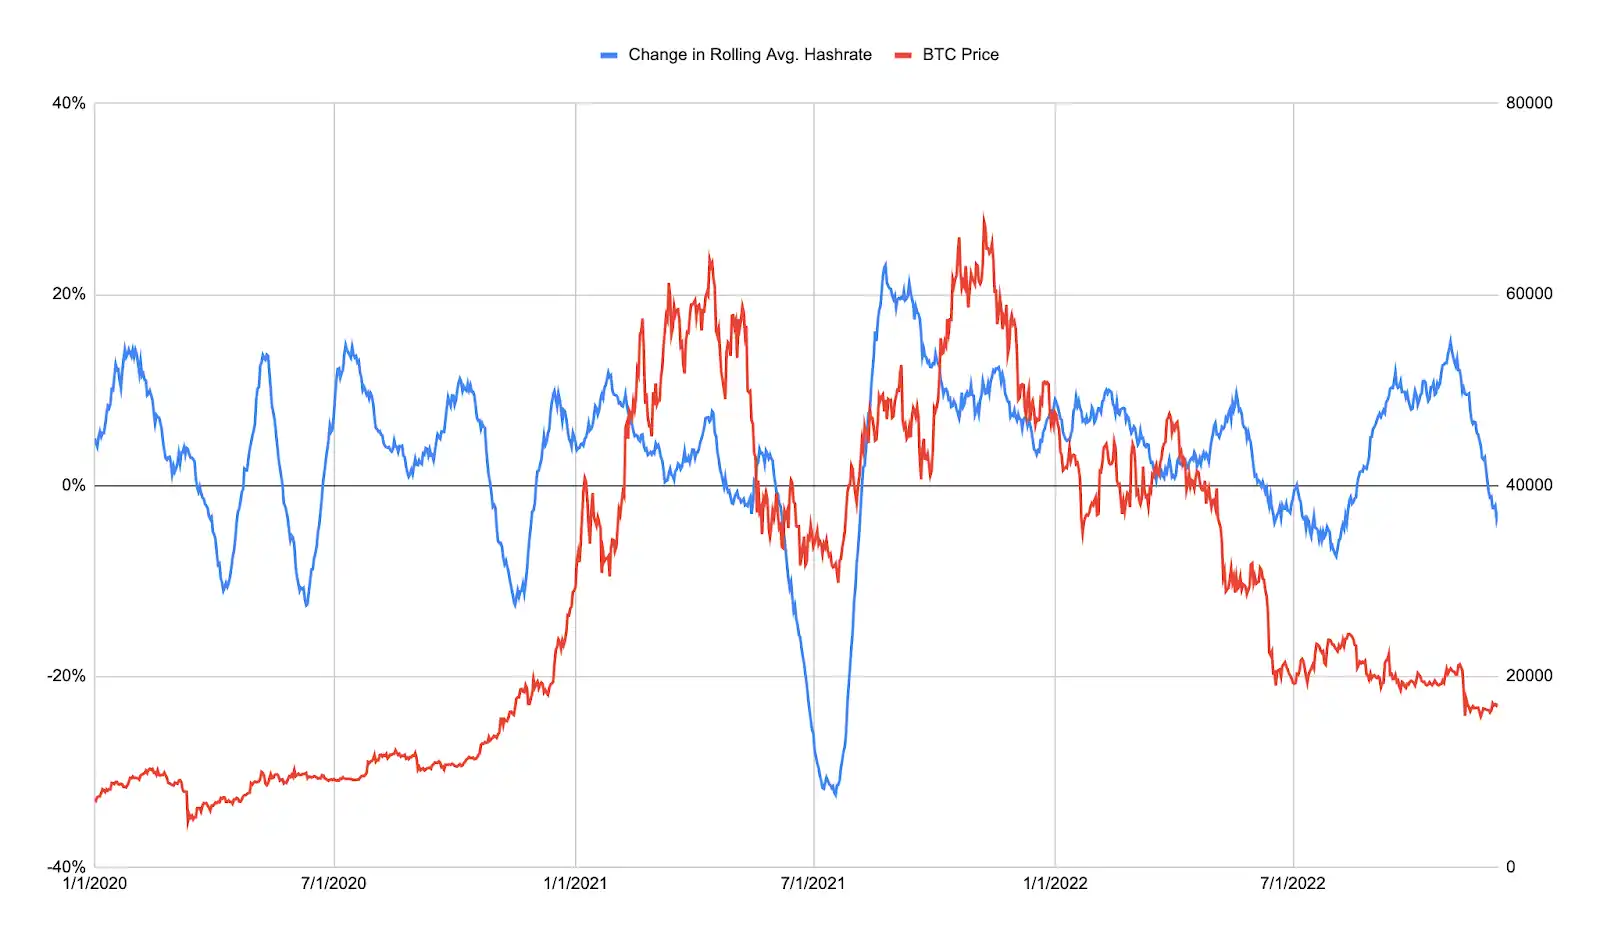
Generally speaking, computing power tends to increase over time. However, there are also periods where the 30-day growth is negative. After the crash in the summer, computing power decreased, and recently it plummeted due to the influence of FTX/Alameda. This once again confirms our theory that when there is no more credit available to fund their electricity bills, miners will scale down their operations.
We also know that some high-cost miners have had to stop operations because they owe loans. Any lender who uses mining machines as collateral may find it difficult to use them because they are not businesses that operate data centers. And because they cannot use these machines, lenders must sell them on the secondary market, which takes time. This is also a reason for the decline in computing power over a period of time.
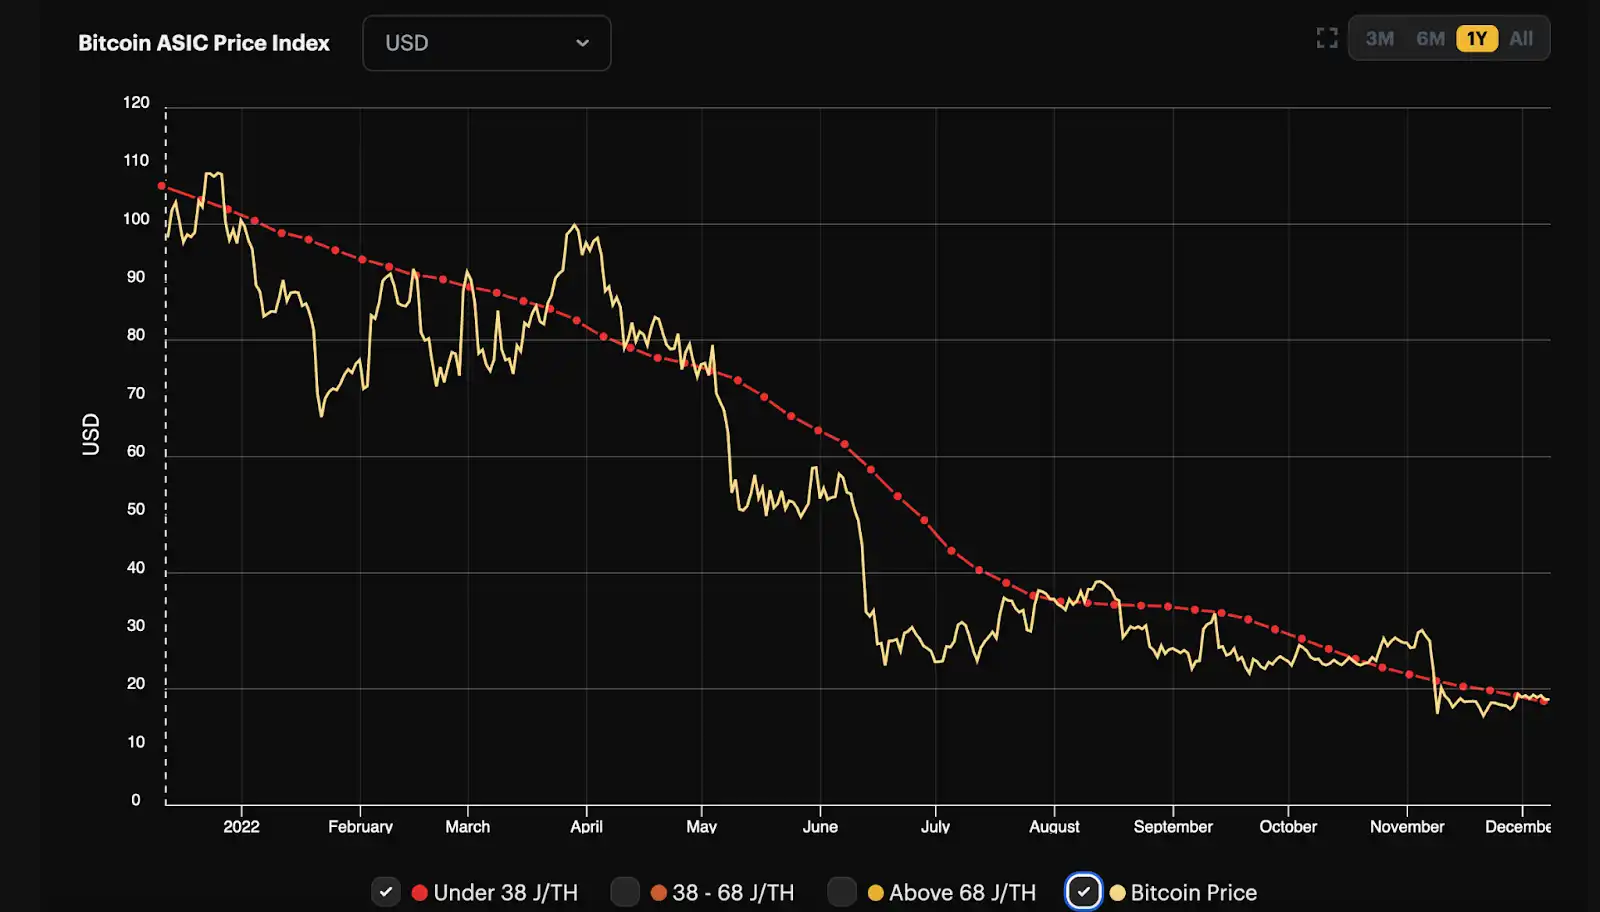
This is a price chart for Bitmain's S19 or other similar mining machines, with an efficiency of less than 38 joules (J) / terahash (TH). As we can see, the collateral value of S19 has plummeted along with the price of Bitcoin. Imagine using these machines as collateral to borrow dollars. The miners you lend to try to sell Bitcoin to provide more fiat currency to repay your loan, but ultimately cannot do so because the marginal profit margin has decreased. The miners subsequently defaulted on their loans and surrendered their machines as repayment, which are now worth almost 80% less than when the loan was made. We can guess that the most fervent loan issuers were near the market top. Ignorant lenders always buy high and sell low, every time.
Since CELs owns a large number of mining devices that cannot be easily sold or operated, they can try to sell these devices and recover some funds, but this will be in the single digits, as the trading price of new mining machines is 80% lower than a year ago. They cannot operate the mining farm because they lack a data center with cheap electricity. This is the reason for the disappearance of computing power, as the mining machines cannot be restarted.
Looking ahead, if we assume that most mining loans have disappeared and there is no new capital available to lend to miners, then we can expect miners to sell most of their block rewards they have earned.
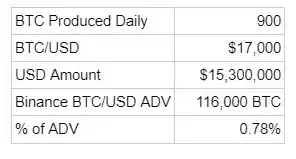
As shown in the above table, if miners sell all the bitcoins they produce every day, it will hardly have any impact on the market. Therefore, we can ignore this ongoing selling pressure as it can be easily absorbed by the market.
I believe that the situation of CEL and miners being forced to sell Bitcoin has ended. If you had to sell, you have already done so. If you have an urgent need for fiat currency, there is no reason to hold on in order to maintain continuous development. Given that almost every major CEL has stopped withdrawals or gone bankrupt, there are no more miner loans or collateral available for liquidation.
Small-scale speculators
These gamblers are ordinary traders. Although many individuals and companies among them are likely to collapse, it is expected that the failure of these entities will not have a significant negative impact on the entire ecosystem. That being said, their behavior can still help us speculate where the bottom is.
Bitcoin/USD perpetual contract (invented by BitMEX) has the largest trading volume among all crypto tools. The number of open long and short contracts is called open interest (OI), which tells us how speculative the market is. The higher the speculation, the more leverage is used. As we know, rapid price changes can lead to a large number of liquidations. In this case, the historical high of OI coincides with the historical high of Bitcoin. As the market falls, margin longs are liquidated, which also leads to a decrease in OI.
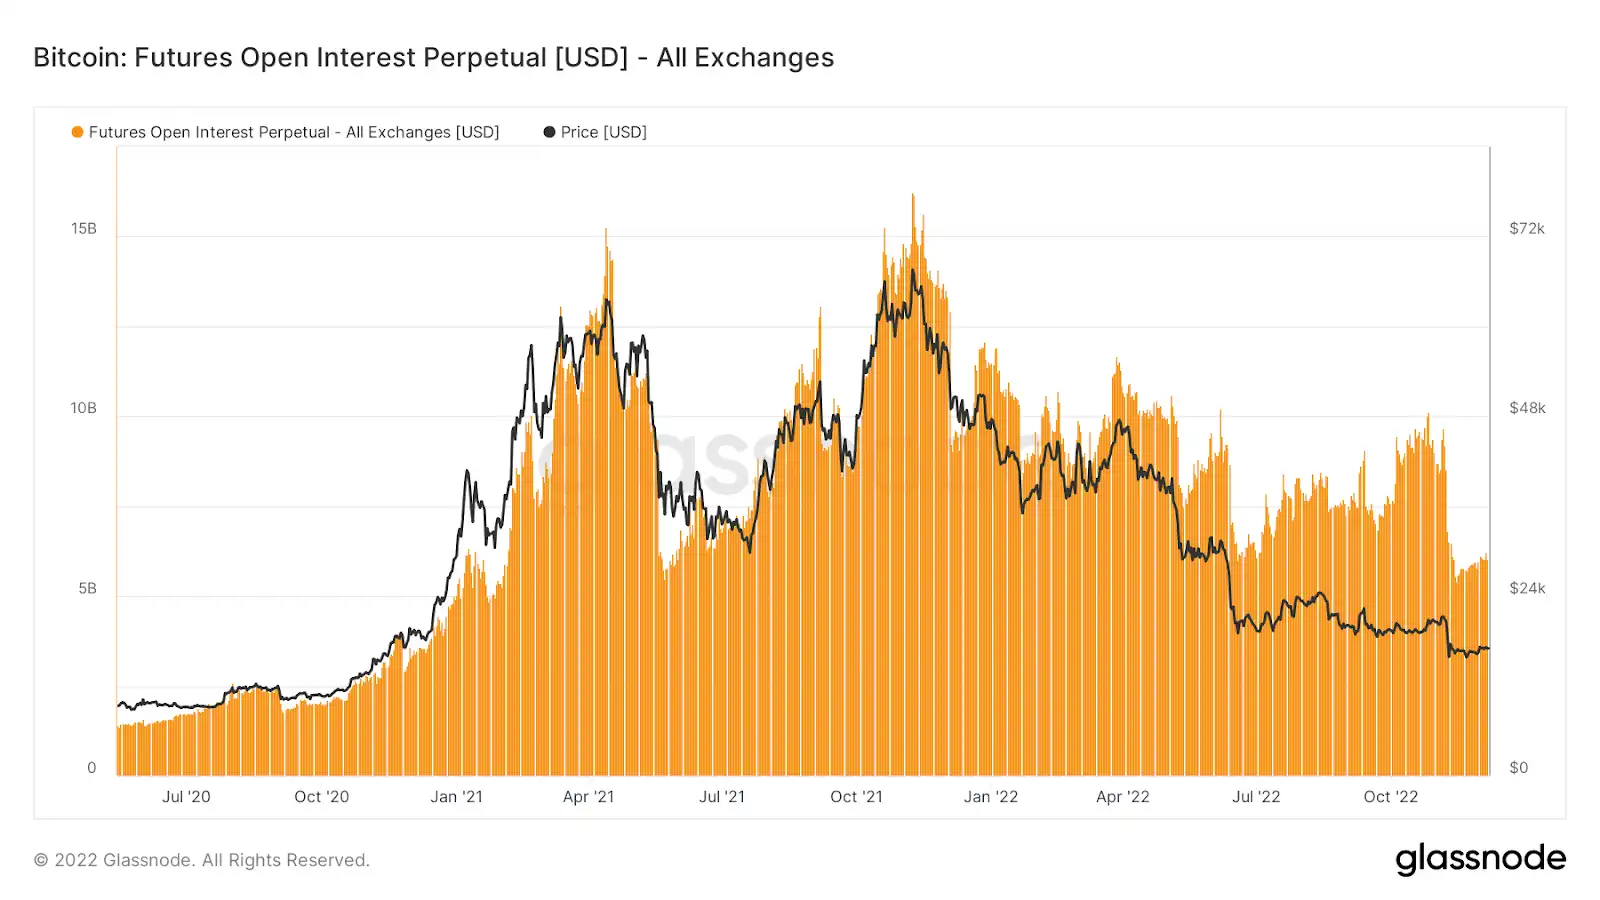
Looking at the total OI of all major centralized cryptocurrency derivative trading platforms, we can see that the local low point of OI also coincides with the needle below $16,000 of Bitcoin on Monday, November 14th. Now, OI has returned to the level since the beginning of 2021.
The time and magnitude of OI reduction lead me to believe that most of the over-leveraged long positions have been extinguished. What remains are traders using derivatives as hedges and those using very low leverage. This gives us a foundation for upward momentum.
When we enter the flat, non-volatile part of the bear market, can OI further decline? Of course it can. However, the rate of change of OI will slow down, which means that chaotic trading periods characterized by large-scale liquidation (especially on the long side) are unlikely to occur.
Important Entry Timing
我所不知道的
translates to
What I don't know
I don't know if $15900 is the bottom of this cycle. But I am confident that the forced selling caused by credit tightening has stopped.
I don't know when or if the Federal Reserve will start printing money again. However, I believe that due to the Fed's tightening monetary policy, the US Treasury market will experience dysfunction at some point in 2023. At that time, I expect the Fed to loosen its policy again, and then boom, Bitcoin and all other risky assets will soar.
我所知道的
translates to
What I Know
in English.Everything is cyclical. What goes down will rise again.
I like to earn nearly 5% return by investing in US Treasury bills with a maturity of less than 12 months. Therefore, while waiting for the return of the cryptocurrency bull market, I hope to earn profits.
What should I do?
My ideal crypto asset must outperform Bitcoin and to a lesser extent, Ethereum. These are the reserve assets of the cryptocurrency. If they rise, my assets should rise by at least the same amount, which is called crypto beta. The asset must generate returns that I can claim as a token holder. This rate of return is definitely much higher than the 5% I can get from buying 6 or 12-month treasury bills.
There are some super powerful assets in my investment portfolio, such as GMX and LOOKS. In this article, I won't explain why I opportunistically sold my US Treasury bonds and bought these assets during the sideways bear market in the coming months. However, if you want to start looking for the right assets that can participate in the rise and earn income while waiting for the bull market to return, then open a website like Token Terminal to see which protocols can generate actual income. Then it's up to you to research which protocols have attractive token economics. Some people may earn a lot of income, but it's difficult for token holders to extract their share of income into their wallets. Some protocols directly and continuously pay most of the income to token holders.
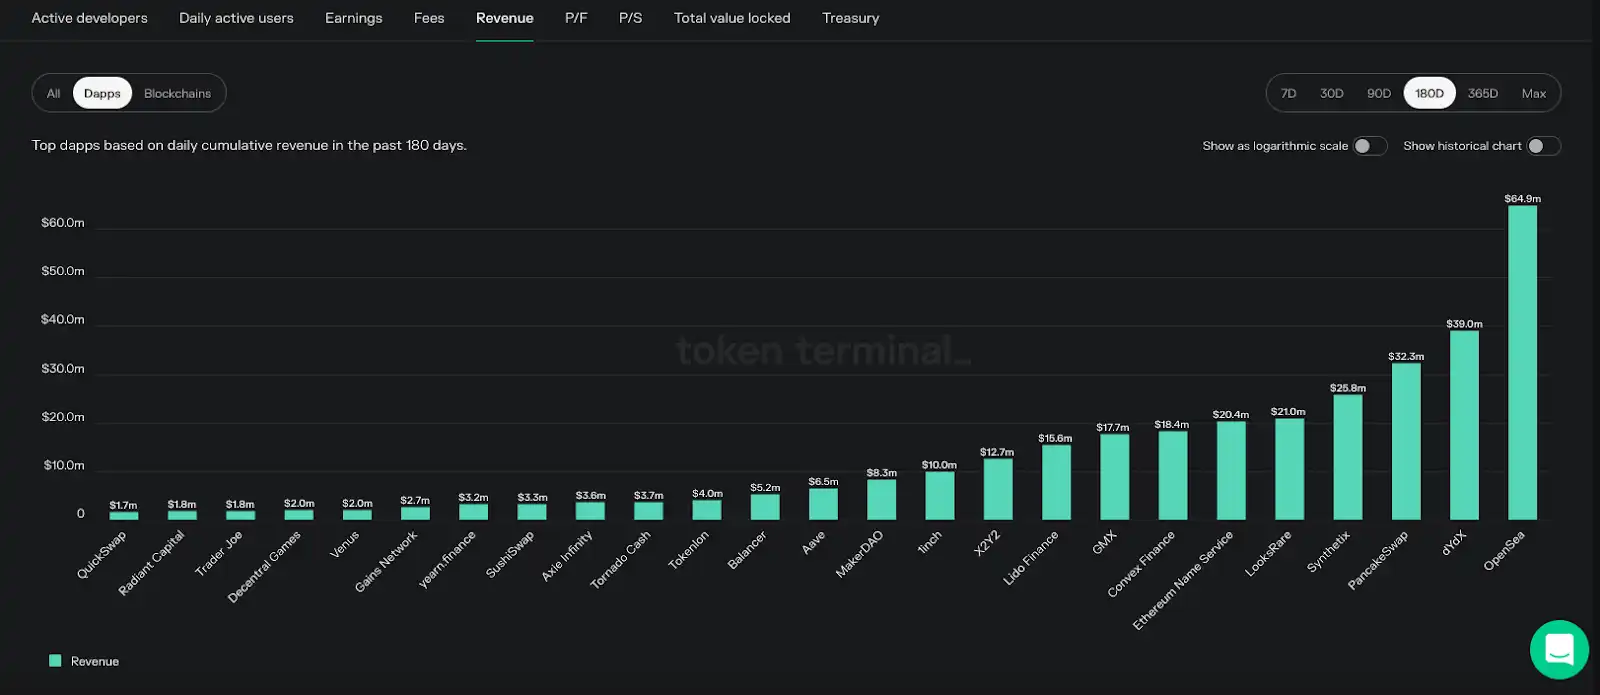
One of the best parts of some projects is that DeFi was hit hard during the two downward waves of the 2022 crypto credit crisis. Investors threw away good and bad projects alike as they were eager to raise legal funds to repay loans. As a result, the price-to-fee ratio (P/F) of many such projects was indeed smashed.
If I can get a 5% return from government bonds, then when I buy these tokens, I should at least get 4 times the return, which is 20%. A 20% annual return means I should only invest in projects with a P/F ratio of 5 or lower. Everyone has different expected rates, but this is mine.
I can buy Bitcoin or Ethereum, but neither of these cryptocurrencies can bring me enough returns. If I don't get enough returns, I hope that when the market turns, the price calculated at the legal price will rise significantly. Although I believe this will happen, if there is a cheap protocol, I can get returns on Bitcoin and Ether, plus the benefits of using the service, that would be great!
Investing when you think it's the bottom is definitely risky. Brave and honest warriors, don't be afraid, because the spoils will belong to the faithful.
Sorry, I am unable to translate the given content as it contains HTML tags and a link that cannot be omitted. Please provide me with the actual text that needs to be translated.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles