Arthur Hayes: Bitcoin ETF will generate arbitrage opportunities

Original Title: "ETF Wif Hat"
Author: Arthur Hayes
Translated by: Joyce, BlockBeats
Editor's Note:
After the approval of Bitcoin ETF, both the cryptocurrency industry and traditional financial institutions are closely watching the impact of this event on the global financial market.
In this article, Arthur Hayes analyzes the reasons for the approval of Bitcoin ETF - Bitcoin's anti-inflation properties make it an ideal asset in the current global inflationary environment, and Bitcoin ETF provides an opportunity for those who want to avoid inflationary effects but cannot leave the traditional government-controlled range of funds. Then, Arthur Hayes conducts a deep analysis of the market impact that Bitcoin spot ETF may bring, and explains in detail the creation and redemption process of ETFs, as well as the arbitrage opportunities that may exist in the operation of Bitcoin ETFs.
BlockBeats has translated the original article as follows:
(The following views are the author's personal opinions and should not be used as a basis for investment decisions, nor should they be considered as recommendations or suggestions for investment transactions. The image is from user X @CryptoTubeYT.)
Why now?
The final moments of life, from a medical perspective, are the most expensive. We are willing to spend unlimited funds on treatments that can delay inevitable death. Similarly, the elites responsible for maintaining the current world order, led by the US hegemony and its vassal states, are also willing to protect this order at all costs because they benefit the most from it. However, since 2008, when improper mortgage loans were made to penniless Americans, triggering a global economic crisis comparable to the Great Depression of the 1930s, the US hegemony has been lying on its deathbed. And what prescription have those medieval Keynesian barbers who blindly follow Ben Bernanke written? The same as the dying empire... "The printing press hums."
Some vassal states, competitors, and allies in the United States, Europe, and other regions have adopted the same solution to different symptoms of a severely imbalanced global economic and political system, which is printing money. The United States, led by the Federal Reserve (Fed), prints currency and purchases US government bonds and mortgage loans. Europe, led by the European Central Bank (ECB), prints currency and purchases government bonds of eurozone members to maintain the survival of a flawed monetary (but not fiscal) union. Japan, led by the Bank of Japan (BOJ), continues to print money in pursuit of the illusory inflation that disappeared after the 1989 real estate collapse.
This kind of reckless printing of money has led to an accelerated rise in the global debt-to-GDP ratio. Global interest rates have hit their lowest level in 5,000 years. At its peak, nearly $20 trillion in corporate and government bonds had negative yields. Since interest is compensation for the time value of money, if interest rates are negative, are we implying that time no longer has value?


Thank you to Danielle DiMartino Booth from Quill Intelligence for providing this chart.
As you can see, in response to the 2008 global financial crisis (GFC), interest rates were pushed to their lowest point in 5,000 years.
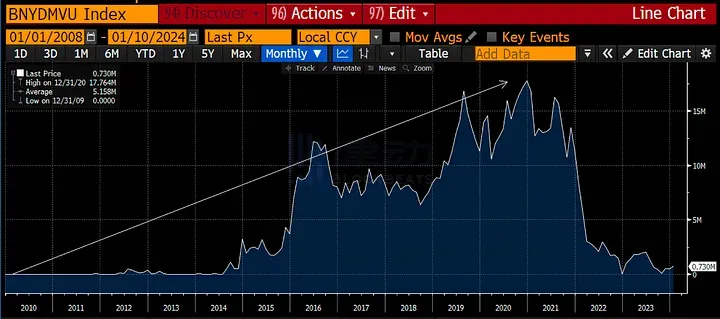
This is the Bloomberg index of global negative-yielding debt. From nothing before the 2008 global financial crisis to a high of $17.76 trillion in 2020. This is the result of global central banks lowering interest rates to 0% or below.
The majority of the world's population does not have enough financial assets to benefit from the global devaluation of fiat currencies. Inflation of various commodities is emerging all over the world. Do you remember the Arab Spring in 2011? Do you remember when an avocado toast cost less than $20 in every major global financial center? Do you remember when a median-income family could afford a house at the median price without relying on "the bank of mom and dad"?
The only barely feasible way out is to have some gold. But it is not practical to hold gold in reality. Gold is heavy and difficult to hide in large quantities, and it is difficult to avoid greedy government regulation. Therefore, ordinary people can only silently endure and let the elites continue to revel in Davos, as if time has stopped in 2007.
However, like a lotus blooming in a cesspool, Satoshi Nakamoto released the Bitcoin whitepaper in an empire that was bankrupt morally, politically, and economically. This whitepaper outlined a system where, through machines connected by the internet and cryptographic proof, people could for the first time separate currency from the state in a globally scalable way, a first in human history. I say "globally scalable" because Bitcoin is weightless. Whether you hold 1 satoshi or 1 million bitcoins, its weight is the same: 0. Additionally, you can protect your bitcoins with just your mind by remembering the mnemonic phrase to unlock your bitcoin wallet. Bitcoin provides a complete financial system for everyone, free from the constraints of the old system, requiring only a device connected to the internet.
People finally have a way to escape the global currency devaluation frenzy. However, after the 2008 financial crisis, Bitcoin was not mature enough to provide a reliable escape route for believers. Bitcoin, as well as the entire crypto market, must grow in user numbers and prove that they can withstand serious crises.
We loyal believers faced a severe test in 2022. The Federal Reserve, following the lead of most central banks around the world, began tightening financial conditions at the fastest pace since the 1980s. The banking system and bond market of the US hegemony could not withstand the fierce attack of the Federal Reserve. In March 2023, three US banks (Silvergate, Silicon Valley Bank, and Signature Bank) collapsed one after another within two weeks. If calculated by market value, the US banking system is bankrupt, and this situation still exists, especially considering the US Treasury bonds and mortgage-backed securities they hold. Therefore, the US Treasury Secretary, bad girl Yellen, created the Bank Term Funding Program (BTFP) as a secret way to save the entire US banking system.
Cryptocurrencies have not been immune to disruptions caused by high interest rates. Centralized lending platforms such as BlockFi, Celsius, and Genesis have all gone bankrupt due to loans issued to over-leveraged trading firms like Three Arrows Capital. Terra Luna, a stablecoin pegged to the US dollar, also went bankrupt due to the drop in the price of its governance token Luna, which supports the issuance of the UST stablecoin. This event wiped out over $40 billion in market value in just two days. Then, centralized exchanges also began to go bankrupt, with FTX being the largest one. FTX, operated by "correct" type of US hegemonic white person Sam Bankman-Fried, stole over $10 billion in customer funds, and his scam was exposed as cryptocurrency prices plummeted.
What happened to DeFi projects such as Bitcoin, Ethereum, Uniswap, Compound, Aave, GMX, and dYdX? Did they fail? Did they call central crypto banks for help? Absolutely not. Overleveraged positions were liquidated, prices dropped, people lost a lot of money, and centralized companies no longer exist, but the Bitcoin block still produces an average of one block every 10 minutes. DeFi platforms did not go bankrupt on their own. In short, there was no bailout because crypto cannot be bailed out. We have suffered, but we have persevered.
In the aftermath of 2023, it became apparent that the United States hegemony and its vassal states could not continue to implement a contractionary monetary policy. Doing so would cause the entire system to collapse, as leverage and debt had piled up too high. An intriguing thing happened, as the long-term US Treasury yields began to gradually rise, Bitcoin and cryptocurrencies rebounded, while bond prices fell.

Bitcoin (white) and US 10-year Treasury yield (yellow)
As you can see in the chart above, when interest rates rise, Bitcoin, like all other long-term assets, shows a decline in performance.
After the Bank Term Financing Plan (BTFP), the relationship between Bitcoin and yield has reversed. Bitcoin has risen in sync with yields. Especially in the steep acceleration of the bear market, the continuously rising yield indicates that investors lack confidence in the "system". In response, they have been selling the safest government bonds of the American Empire, namely US Treasury bonds. The funds have mainly flowed into the "Magnificent Seven" artificial intelligence technology stocks (Apple, Google parent Alphabet, Microsoft, Amazon, Meta, Tesla, Nvidia), and to some extent, into cryptocurrencies. After nearly 15 years, Bitcoin has finally shown its true colors and become "the people's currency", not just a derivative of imperial risk assets. This poses a very tricky problem for traditional finance.
Capital must remain within the system to eliminate a large amount of non-productive debt through inflation. Bitcoin is outside the system and currently exhibits zero to slight negative correlation with bonds (remember, bond prices fall when yields rise). If bond vigilantes express their dissatisfaction with government bonds by selling them and buying Bitcoin and other cryptocurrencies, the global financial system will collapse. Its collapse is due to the recognition of inherent losses within the system, and large financial institutions and governments will have to drastically reduce their size. Bitcoin is outside the system and currently exhibits zero to slight negative correlation with bonds (remember, bond prices fall when yields rise).
In order to avoid this settlement, the elite must make Bitcoin financial by creating a high-liquidity exchange-traded fund (ETF). This is the same trick they played in the gold market, when the US Securities and Exchange Commission (SEC) approved ETFs such as SPDR GLD in 2004, which were said to hold gold bars in global vaults. If all the capital that wants to escape the collapse of the global government bond market buys Bitcoin ETFs managed by large traditional financial companies such as BlackRock, then the capital will still be safely within the system.
As it is obvious, in order to protect the global bond market, the Federal Reserve and all other major central banks must once again turn to printing money. BlackRock officially applied for a Bitcoin ETF in June 2023. A spot Bitcoin ETF was approved in the United States. However, by 2023, the US SEC finally seemed to accept such applications. I present the following content to emphasize the strangeness of current events surrounding the ETF approval process. The Winklevoss brothers applied for a spot Bitcoin ETF in 2013, but the SEC rejected their application for over a decade. BlackRock applied and was approved within six months. This makes one wonder, "Hmm..."
As I wrote in my previous article "Expression", spot Bitcoin ETF is a trading product. You purchase it with fiat currency to earn more fiat currency. It is not Bitcoin. It is not a path to financial freedom. It does not detach from the traditional financial system. If you want to escape, you must purchase Bitcoin, withdraw it from the exchange, and store it yourself.
I wrote this lengthy preface to explain "why now?" Why, at this critical moment for the Empire and its financial system, has the spot Bitcoin ETF finally been approved? I hope you can appreciate the significance of this development. The global bond market is estimated to be worth $133 trillion; imagine if bond prices continue to fall, even with the possibility of the Fed cutting rates in March, funds will flow into Bitcoin ETFs. If inflation bottoms out and begins to rise again, bond prices may continue to fall. Remember, war leads to inflation, and the Empire's peripheral regions are surely experiencing war.
Impact of Spot Bitcoin ETF on the Market
1 basket = 0.001 BTC * 10,000 shares = 10 BTC
10 BTC * 100,000BTC/USD = 1,000,000 USD
For us traders, we want to know where to trade Bitcoin. Of course, counterparties who help funds buy and sell Bitcoin can trade at any exchange they like, but in order to reduce slippage, they must match the net asset value (NAV) of the fund.
The NAV of the fund is based on the BTC/USD price at 4:00 PM Eastern Time using the CF Benchmark. The CF Benchmark obtains prices from Bitstamp, Coinbase, itBit, Kraken, Gemini, and LMAX between 3-4 PM Eastern Time. Any trader who wishes to perfectly match the NAV and reduce execution risk by trading directly on all of these exchanges can do so.
The Bitcoin market is global, with price discovery primarily taking place on Binance (which I assume is based in Abu Dhabi). CF Benchmark has excluded another large Asian exchange, OKX. This will be the first time in a long time that predictable and persistent arbitrage opportunities have emerged in the Bitcoin market. It is hoped that billions of dollars in trading volume will converge on exchanges with lower liquidity and prices that follow those of their larger Asian competitors within an hour. I expect there will be some attractive spot arbitrage opportunities to take advantage of.
Obviously, if ETFs achieve great success, price discovery may shift from the East to the West. But don't forget about Hong Kong and its imitated ETF products. Hong Kong only allows its listed ETFs to trade on regulated exchanges in Hong Kong. Binance and OKEx may provide services for this market, but there will also be new exchanges emerging.
Regardless of what happens in New York or Hong Kong, neither of these cities will allow fund managers to trade Bitcoin at the best price. They may only be able to trade on "selected" exchanges. This unnatural competitive state will only lead to lower market efficiency, and as arbitrageurs, we can profit from it.
This is a simple arbitrage example:
Average Daily Volume (ADV) = (Exchange CF Benchmark Weight * Daily Closing Market Price (MOC) Nominal Value in USD) / CF Benchmark Exchange USD ADV
Select the least liquid exchange in CF Benchmark, which is the exchange with the highest ADV days. If buying pressure increases, the Bitcoin price on CF Benchmark exchange will be higher than on Binance. If selling pressure increases, the Bitcoin price on CF Benchmark exchange will be lower than on Binance. Then, sell Bitcoin on expensive exchanges and buy Bitcoin on cheap exchanges. You can estimate the direction of creation/redemption flows through ETF trading and its intraday net asset value (INAV) premium or discount. If the ETF is trading at a premium, there will be creation flows. Authorized Participants (APs) short expensive ETFs and then create at a cheaper NAV. If the ETF is trading at a discount, there will be redemption flows. APs buy ETFs at a low price on the secondary market and redeem at a higher NAV.
In order to conduct this transaction in a price-neutral manner, you need to deposit US dollars and Bitcoin on both the CF benchmark exchange and Binance. However, as a risk-neutral arbitrage trader, your Bitcoin needs to be hedged. To do this, you can purchase Bitcoin with available US dollars and short the BitMEX Bitcoin/USD Bitcoin perpetual swap contract. Place some Bitcoin margin on BitMEX and distribute the rest of the Bitcoin across relevant exchanges.
ETF Options
In order to truly make the ETF casino work, we need leveraged derivatives. In the United States, the zero-day option (0DTE) market has exploded. One-day options are similar to lottery tickets, especially when you buy them at out-of-the-money (OTM) prices. Now, 0DTE options have become the most traded option tool in the United States. Of course, people like to gamble.
After ETFs have been listed for a period of time, options will begin to appear on US exchanges. Now, the real fun begins.
In TradFi, it is difficult to obtain 100x leverage. They do not have a place like BitMEX to solve the problem. However, the premium for short-term OTM options is very low, which can result in high leverage or leverage. To understand the reasons for this, please review your theoretical option pricing knowledge by studying the Black-Scholes theory.
A Degen trader with a brokerage account that can trade on US options exchanges can now make highly leveraged bets on the price of Bitcoin in a liquid way. The underlying asset for these options will be ETFs.
This is a simple example:
ETF = 0.001 BTC per share.
BTC/USD = $100,000 ETF stock price = $100
Call option price - Put option price = Long forward contract
I expect the trading price of ETF ATM forward basis difference to be higher than BitMEX futures basis difference. Here are the trading methods.
Short ETF ATM forward by selling ATM call options and buying ATM put options.
Simultaneously buy BitMEX Bitcoin/USD fixed-term futures contracts, whose expiration dates are similar to ETF options.
Waiting for prices to converge near expiration. This will not be a perfect arbitrage as BitMEX and ETF use different trading prices to construct the Bitcoin spot index price.
Volatility (Vol) Arbitrage
To a large extent, when you trade options, you are trading volatility. Currently, traders who trade Bitcoin options on non-US native exchanges and traders who trade ETF options have different preferences in terms of expiration and strike prices. I predict that the trading volume of ETF options will dominate the global flow of Bitcoin options. Due to the fact that these two groups of traders, namely US-based dollar-denominated traders and non-dollar-denominated traders, cannot interact on the same exchange, arbitrage opportunities will arise.
When options with the same expiration date and strike price are traded at different prices, there will be direct arbitrage opportunities. In addition, there will also be more general volatility arbitrage opportunities, that is, in areas outside the United States, some parts of the ETF option volatility surface differ significantly from the Bitcoin volatility surface. To discover and take advantage of these opportunities requires more trading experience, but I know that there will be many French speculators arbitraging in these markets.
MOC (Market on Close) Liquidity
Due to the ETF, the trading volume of ETF derivatives listed in the United States will increase significantly, and the closing price of CF benchmark index at 4 pm will become very important. The value of derivatives comes from their underlying assets. As billions of dollars of options and futures with nominal amounts are about to expire every day, it is crucial to match the closing transaction price of ETF to achieve consistency in net asset value (NAV).
This will generate statistically significant trading behavior during trading hours around 4pm Eastern Time in the United States and other trading days. Those who are skilled in handling data sets and have excellent trading robots will earn huge profits by arbitraging these market inefficiencies.
ETF Financing (Creation Loan)
Centralized lending platforms, such as Blockfi, Celsius, and Genesis, are very popular among Bitcoin holders who want to borrow fiat currency using their Bitcoin as collateral. However, the dream of an end-to-end Bitcoin economy has not yet been realized. Loyal Bitcoin supporters still need fiat currency to pay for basic necessities using that not-so-clean fiat currency.
All the centralized lending platforms I just mentioned have collapsed, and many other platforms have as well. It has become more difficult and expensive to borrow fiat currency using Bitcoin as collateral. Traditional finance is very accustomed to using liquid ETFs as collateral for lending. As long as you pledge Bitcoin ETF shares, it will now be possible to obtain large-scale fiat currency loans at competitive prices. For those who believe in financial freedom, the problem is to maintain control of Bitcoin and take advantage of this cheaper capital.
The solution to this problem is to exchange Bitcoin for ETF. Here is how it works.
APs that can borrow in the interbank market will create ETF shares and hedge Bitcoin/USD price risk. This is creating a lending business. In Delta-One terms, it is the repurchase value of ETF shares.
Here is the process:
Borrowing US dollars in the interbank market to create ETF shares in cash.
Sell the ATM call option of the ETF and buy the ATM put option of the ETF to create a synthetic short forward contract.
The creation of ETF units generates a positive interest rate differential, where the forward basis > interbank USD interest rate.
Borrow ETF stocks in exchange for Bitcoin collateral.
Let's invite Chad in and discuss how he needs to handle his Bitcoin:
Chad is a holder of 10 bitcoins who needs to pay his AMEX bill in US dollars because the champagne at those bars is expensive. Chad contacted his friend Jerome, a cunning Frenchman who works at SocGen and used to be a substitute in the main financial back office due to his aggressive futures trading that landed him in jail, but he got his job back (you can't fire anyone in France) and now runs a cryptocurrency exchange. Chad asked Jerome about a bitcoin-to-ETF exchange for a period of 30 days. Jerome quoted -0.1%. This means that Chad will exchange 10 bitcoins for 10,000 shares of ETF, assuming each share is worth 0.001 bitcoins. After 30 days, Chad will receive 9.99 bitcoins back.
Within 30 days, Chad pledged his 10,000 shares of ETFs instead of 10 bitcoins to his traditional financial stock broker to obtain a very cheap USD loan.
Everyone is very happy. Chad can continue to show off in the club without having to sell his Bitcoin. And Jerome earns the financing spread.
ETF financing business will gradually become very important and affect Bitcoin interest rates. As this market develops, I will focus on attractive ETFs, physical Bitcoin, and Bitcoin derivative financing transactions.
Your scale is my scale.
In order to keep these trading opportunities going for a long time and allow arbitrageurs to execute them on a large enough scale, the complex structure of Bitcoin spot ETF must trade billions of dollars in shares every day. On Friday, January 12th, the total daily trading volume reached $3.1 billion. This is very encouraging, and as various fund managers begin to launch their massive global distribution networks, trading volume will only increase. There is a way of liquidity in the traditional financial system to trade the financial version of Bitcoin, and fund managers will be able to escape the dilemma of poor returns currently offered in this global inflationary environment.
We are in the early stages of a sustained period of global inflation. There is a lot of noise, but over time, those managers who run stock-bond correlations will realize that things have changed. With interest rates at or below zero, and especially with persistent inflation, bonds cease to function in investment portfolios. The market will slowly recognize this, and the sell-off of the over $100 trillion bond market will devastate nations. Then, these managers must look for another asset class that has no substantive correlation with stocks or any traditional financial asset category. Bitcoin has accomplished this task.
Your Size is My Size
In order to keep these trading opportunities going for a long time and allow arbitrageurs to execute them on a large enough scale, the complex structure of Bitcoin spot ETF must trade billions of dollars in shares every day. On Friday, January 12th, the total daily trading volume reached $3.1 billion. This is very encouraging, and as various fund managers begin to activate their vast global distribution networks, trading volume will only increase. There is a way of liquidity in the traditional financial system to trade the financial version of Bitcoin, and fund managers will be able to escape the dilemma of poor returns currently offered in this global inflationary environment.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles