SBF: How do you view the development and industry regulation of Stablecoin
Testimony of Sam Bankman-Fried Co-founder and CEO of FTX
MIM, Deep Tide TechFlow
Note: This is the full text of the congressional testimony prepared by Samuel Bankman Fried (SBF), co-founder and CEO of FTX. We could have given a brief overview and a large amount of content was about FTX itself, but we think a complete text is easier to understand the narrative logic in the Western context, and express in detail SBF's particular emphasis on the supervision of Stablecoin. SBF also talks a lot about liquidity and Stablecoin For the importance of this industry, all the prosperity of this industry is based on liquidity, therefore, in the appendix, dedicated to Stablecoin Regulatory statements. The full text is too long, you can browse selectively the part you are interested in.
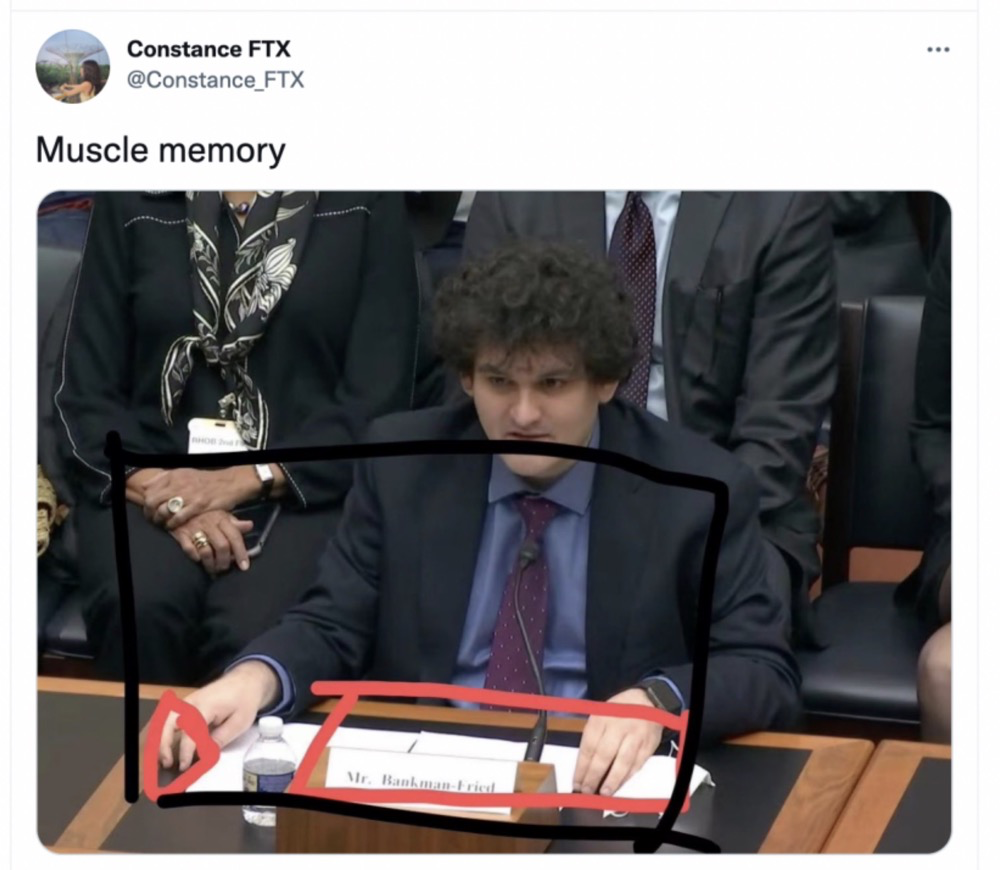
Finally, an Easter egg: muscle memory of experienced LOL players.
The following is the full text of the testimony:
Chairman Waters, Chief Member McHenry, committee members and distinguished guests, thank you for inviting me to testify before this committee. As a member of this committee, I am honored to share some information and insights about the digital asset industry, as this chamber has worked with Congress on a variety of key issues. I am happy to work with my colleagues and teammates to provide you with as much information as you need to ensure that we can have a robust debate about whether and how this Committee will address some of these key issues.
FTX background
作为加密资产交易的交易平台或市场,FTX 公司集团成立于 2019 年。在美国,该公司是一家联邦监管的交易平台运营商,拥有财政部和美国商品期货交易委员会(CFTC)的许可证。FTX 由 Samuel Bankman Fried、Gary Wong 和 Nishad Singh 三个美国人成立,自 2019 年 5 月开始运营。成立 FTX 的目的是要建立一个数字资产交易和交换平台,致力于发展成为用户体验更好、且对客户有足够保护的创新产品。FTX 建立 FTX.com 交易平台是想要开发一个对于专业交易公司而言足够强大、对于新用户而言觉得足够简洁的平台。
Given the core founding team's experience with large engineering systems at Google and Facebook, as well as their Wall Street trading experience, they have unique experience building a trading platform from zero to one and understanding how that platform can be done without being affected by legacy technologies or market structures. FTX aims to combine the best practices of traditional financial systems with digital asset ecosystems.
早期成功。自推出以来,FTX.com 交易平台一直很成功。今年平台每天交易额约 150 亿美元,目前约占全球加密交易量的 10%。FTX 团队在全球范围内已有 200 多人,其中大部分负责合规和客户支持。FTX 集团的主要国际总部和运营基地位于巴哈马,根据《2020 年数字资产和注册交易法》,公司在巴哈马注册为数字资产业务。
除提供有竞争力的产品外,FTX 还以高性能和可靠的交易平台而闻名。在整个数字资产市场的高波动期,与主要竞争对手相比,FTX.com 交易平台经历了相对较短期的停机时间和技术性能问题。对客户和产品可靠性的关注是 FTX 交易平台自 2020 年 1 月以来能够在与其他 交易平台的竞争中,保证交易量增长最快的关键原因。
Core products include FTX.com, which provides a way for crypto assets to enter the market. Platform users can also enter the market through FTX applications on mobile.) , vertically integrated single technology stack (support order matching engine). , an application programming interface or API, hosting services and wallets for customers, and a settlement, clearing, and risk engine system. In daily transactions, only buyers, sellers and trading platforms are involved.
FTX Group operates and licenses in dozens of jurisdictions around the world, including the United States. At the time of this writing, the FTX platform has several million registered users and the FTX US platform has approximately one million users. For FTX.com, about 45 per cent of users and clients are from Asia, 25 per cent from the EU and the rest from other regions than the US (excluding people from sanctioned countries). Almost all ftx. us users are from the United States.
Us business. FTX serves customers in the US through the FTX US platform, which also includes FTX US Derivatives. FTX US is an independent business entity with a management structure and capital structure similar to that of the entire business family, with its own website ftx.us and mobile application. Like FTX.COM, FTX US's core product is a spot trading platform for digital assets that, like other crypto platforms in the US, is enabled by having a compliance licence. FTX US is headquartered in Chicago and has offices in other U.S. cities.
FTX US Derivatives was formed by acquiring and rebranding LedgerX, and is now a business unit that offers Derivatives such as futures and options contracts on digital goods to BOTH U.S. and non-U.S. consumers. FTX US Derivatives has four business licenses from the Commodity Futures Trading Commission (CFTC) : a Designated Contract Market (DCM) license, a Swap Execution Facility (SEF) license, a Designated Clearing Organization (DCO) license, and a Chief Process Officer (CPO) license. Prior to the acquisition, the business was the first crypto native platform to receive a Designated Clearing Organization (DCO) license from the COMMODITY Futures Trading Commission (CFTC) in 2017, a milestone for both the agency and the cryptocurrency industry. The license was later amended in 2019 to allow the clearing of futures contracts.
Commitment to a diverse workforce. FTX is proud to have a team of employees and believes that a team culture of mutual respect and cooperation is one of our main strengths. This team culture comes from the diversity of the team and requires empathy, understanding and humility. These characteristics are conducive to business development and are also the main reason why FTX can successfully understand customer needs and provide customers with appropriate products. FTX employs people from all over the world and ethnic backgrounds, and 60 per cent of the team is female.
Commitment to climate mitigation. FTX takes environmental issues very seriously and is committed to reducing the impact of our lives and work on the global environment. FTX as a company has taken a number of important steps to ensure this. Here, I would like to explain to you item by item why FTX has the least impact on the environment and the additional measures FTX has taken to further reduce its impact on the environment.
First, FTX has no factories or physical products, so it does not take advantage of the global transportation network, which is an important source of energy consumption. FTX does not have a large number of employees or a large number of offices. It rents a few small offices around the world and operates online. Therefore, the business operation of FTX will not have a direct impact on global climate change.
Second, the storage and withdrawal of digital assets on FTX does consume energy, as the public chain is required to facilitate and record these transactions. But more than 80% of deposits and withdrawals on FTX use low-cost, carbon-compliant proof-of-stake (PoS) public links. These PoS public chains are in contrast to proof-of-work (PoW) public chains, which consume a lot of energy to maintain networks (the Bitcoin blockchain is an example). By using PoS's public chain for the vast majority of FTX deposits and withdrawals, FTX significantly reduces the climate impact of blockchain. To reduce the energy consumption associated with the remaining 20% or so of deposits and withdrawals, FTX has subsidized the blockchain network fee to share the cost of paying for this energy consumption. FTX separates deposits and withdrawals. Transactions and transfers within the trading platform (that is, the operations of the vast majority of users) do not require public chain activities, only the amount of energy required to run a web-based trading place.
At the same time, FTX is also trying to bear our mining environmental costs related to the public chain, and has purchased carbon offsets to neutralize these costs. Due to the decentralized nature of mining activities, it is not easy to pinpoint the source and proportion of energy consumption, so it is extremely difficult to estimate the cost of energy consumption and carbon output associated with blockchain mining. Still, FTX estimates the cost at $1m and has bought a total of 100,000 tonnes of carbon offsets through two suppliers for $1,016m. In addition, FTX, through its affiliate FTX Climate, has created a comprehensive program focused on solutions that have the greatest impact possible on climate change. In addition to achieving carbon neutrality, our initial plan also funds research that we believe can have a big impact, and supports other special projects and carbon removal solutions. FTX plans to spend at least $1 million a year through FTX Climate.
Four, FTX think PoW network energy consumption and its impact should be in the proper context, we believe that the assessment activities should consider the benefits, including understanding the difference between them and PoS system network and how each type network is being used and the development, and comparing with other energy consumption activities even industry. For example, bitcoin has brought benefits to many people in terms of access to financial products, asset transmission and wealth creation, and those benefits should be weighed against the cost of network energy.
In addition, while PoW networks are getting a lot of attention for their energy consumption, transaction activity on PoS networks is growing significantly due to their excellent performance in processing more transactions in less time and at lower cost. FTX believes these PoS networks will become increasingly important over time. Over time, PoS networks will continue to minimize the climate impact of the entire blockchain. Finally, PoW blockchain uses relatively little energy compared to other industries, especially the Bitcoin network, to which it is often compared. Among the assets that trade futures on CFTC premises, bitcoin actually ranks low in terms of environmental impact relative to traditional, physically mined commodities, oil, livestock and other assets that have an impact on the environment.
The promise of return. FTX is committed not only to improving the lives of its customers through exceptional products, but also the wider community around the world. To this end, FTX created the FTX Foundation, whose mission is to donate money to the world's most effective charities. FTX has made a commitment to donate one percent of its net fee income to the foundation. To date, FTX, its affiliates and employees have donated more than $10 million to help save lives, prevent suffering and ensure a better future for humanity.
Discuss & have spent
In this article I will explore the following topics:
(1) Summarize the products offered by FTX and their role in the digital asset economy;
(2) Stablecoin And how to address the risks associated with these tools;
(3) The current state of regulation and the principles guiding policy makers to achieve good policy outcomes.
When discussing these issues, I will distinguish between FTX's non-US business and ITS US business, using FTX International and FTX US for both.
My statement covers several key themes, as it covers a wide variety of topics.
1. FTX empowers individual investors and consumers. We offer products that are easily available and affordable, so investors and consumers can achieve their economic goals by making simplified choices. They can easily get anywhere financial products (a lot of people are using mobile phones to do so), FTX without those who evaluate the rent of the gatekeeper, also won't pose a risk to investors in the process - digital assets ecosystem that affect real daily life of relevant personnel, and help them achieve economic security in the process. This easily accessible financial instrument provides a supportive and inclusive policy environment (balanced with other policy objectives) that is bound to further empower individual investors.
Second, FTX has designed and provided a market structure platform with reduced risk. To be sure, there are some irresponsible actors in the digital asset industry who have made headlines. But FTX is not. In fact, FTX has built a resilient, low-risk platform, which is one of its competitive advantages. Thus, the FTX model should be able to adapt to any regulatory framework with the highest risk standards in the world, provided policymakers are willing to be flexible and allow a risk-reducing, round-the-clock, direct-to-investor market structure to exist and exempt it from the structural requirements of traditional intermediary markets. But this regulatory structure is not always best for individual investors.
Iii. FTX has been regulated by the highest federal standards in the United States, including the Commodity Futures Trading Commission (CFTC) and the United States Department of the Treasury, as well as other global and state regulatory agencies. As discussed below, FTX supports and wishes to operate under a uniform regulatory regime at the federal level. In any case, FTX views regulators in the official sector as stakeholders and partners with whom it needs to engage in a continuous and active dialogue, a view that applies equally to the US Congress. We at FTX are always welcome and we are eager to share our insights into the digital asset industry and how it can continue to improve People's Daily lives.
Of course, the future is difficult to predict, but FTX believes that digital assets and blockchain technology more generally are likely to endure and continue to present exciting opportunities for consumers, investors and entrepreneurs. FTX believes the US should continue to lead the way in such opportunities at home. FTX fully supports the regulatory framework for digital asset trading to protect investors and achieve the hallmarks of an orderly market. To maintain US leadership, policymakers will need to continue to leverage the best features of existing policy, but also adapt to the best features of the digital asset industry, which we see as empowering for consumers and a risk-mitigation move at the market level.
1.FTX products and their role in the digital Asset economy & NBSP;
Core product: digital asset trading platform. As mentioned above, FTX's core products are its digital asset trading platforms, FTX.com and FTx.us. On these two platforms, users can exchange digital assets for cash and Stablecoin with other users. And other digital assets. Users can set up different order types on the spot trading platform's central Limit Order book (CLOB). Users can place orders at a specific price (limit order) or trade on a central Limit Order Book (CLOB) with the best price displayed. There is a powerful matching engine that connects buyer and seller orders and displays the best available prices.
Futures and volatility contracts linked to digital assets are listed on the platform, leveraged or not. The leverage limit on FTX.com is 20 times, and until now, ftx.us users have not been able to use leverage (although it has offered other forms of credit facilities to eligible contract participants -- see below). These platforms already list cash settlements that are settled quarterly (and permanent futures contracts only on FTX.com). FTX.com also offers MOVE volatility contracts. MOVE volatility contracts are similar to futures, but instead of maturing at the price of a digital asset, they mature by the amount of dollars that MOVE over a day, week or quarter in the price of Bitcoin. FTX.com also lists bitcoin options for trading. Finally, FTX US Derivatives offers bitcoin and Ethereum (ETH) options, futures and swaps to USERS in the US.
To cover initial and maintenance margins, users of derivatives and leveraged products are paid in cash, Stablecoin Or other digital assets to post collateral on their accounts. Trading platform and integrated risk management and back office system, clearing and settlement for trading, including the digital assets or updates are trading assets ownership records (settlement) of futures and options contracts, and to transfer value between user account (settlement), adopt the way of settlement of payment or delivery of delivery. The market events of the past week have shown that FTX's core products have effective risk mitigation attributes. On the evening of December 3, 2021, multiple digital assets saw their value fall for a short period of time, and the trading volume of these assets on THE FTX platform increased significantly.
This is especially true when the FTX risk engine is activated and begins to clear relevant client positions on the platform. The market decline began late, well after the close of trading in the United States. But because digital assets trade around the clock, the FTX risk engine is able to react immediately to falls in asset prices and begin liquidating positions before any client accounts become net negative. If this had happened in a traditional trading market, the risk management system would not have reacted immediately, but would have waited more than two days before the market reopened. During this time, the client's position may decline sharply before an opportunity arises to stem losses on the client's account. Importantly, FTX's risk model avoids the systematic stockpiling of such risks during weekends or other market closures by taking an immediate, real-time approach to dealing with risky positions and accounts.
An off-site portal used to arrange and match user orders. FTX.com also offers an over-the-counter portal that allows users to connect with other big users, request quotes for physical digital assets and trade directly. The portal forwards quote requests to large users, returns quotes and allows users to place orders. It serves a similar function to other facilities in traditional markets, where a central limit order book is not used to match trades.
Margin lending. FTX users can lend their digital assets to those who need them for spot transactions. Users who want access to digital assets they don't have (including qualified users on FTx.us) can post cash, Stablecoin Or provide collateral in the form of other digital assets held in their accounts, borrowing money from users willing to lend digital assets. FTX platform has a built-in loan book system, which has the function of matching borrowers and borrowers.
NFT market. FTX operates a marketplace that users can use to forge, buy and sell unfordable tokens (NFTs). NFTs are tokens that are not interchangeable with any other Token. They can be used in many forms, for example, in exchange for physical objects or experiences (like movies or phones), or in connection with digital images, and so on. FTX's NFT market is conducted through an auction system. Alternatively, users can purchase directly at the current sale price set by the seller. Users can choose to display their NFT collection on the FTX NFT Marketplace portal, continue to buy or sell on the NFT Marketplace, or do both. The NFT marketplace is open to FTX.com and ftx.us users.
FTX Pay (FTX). FTX Pay is a service for merchants to accept payment in digital assets or fiat currency. Users can choose to top up their FTX account with ACH or a credit card and then use the FTX account to make payments to registered merchants. For digital asset payment, the FTX account of the relevant user will be deducted the amount of the selected digital asset, which is equivalent to the amount payable to the Merchant. FTX facilitates users' payment to merchants by providing payment infrastructure.
Mortgage. FTX.com offers users the ability to "pledge" certain supported digital assets on the platform. Users can pledge these digital assets for collateral rewards; In addition, users can use certain tokens on the FTX platform to obtain benefits such as reduced transaction fees, withdrawal fees and other rewards. In general, users can "unpledge" their digital assets at any time, but wait until a unpledge period or after the unpledge period has passed. For certain features of digital assets, FTX may allow users to immediately unsubscribe by paying a cancellation fee.
Type of digital asset on FTX platform. FTX has developed listing standards and frameworks that define which digital assets can be listed on the FTX platform. Part of the listing standards and framework requires that assets be evaluated to ensure safety, compliance risk, legal risk, technical risk and other factors. On FTX.com (also unavailable to US users), FTX already lists about 100 stablecoins and other digital assets on its spot trading platform. Digital assets include tokens such as Bitcoin (BTC), Ether (ETH), Uniswap Protocol Token (UNI), Chainlink Token (LINK), Solana (SOL), and Aave (Aave). Stablecoins include tokens such as USDT (USD Tether) and DAI.
On FTx.us, FTX takes what we believe is a conservative approach to listing digital assets and trading. Because ftX.US has stricter listing standards, there are far fewer tokens traded on ftX.US. The FTx.us platform has taken steps to avoid listing assets that have characteristics of US securities. The assets and tokens it lists are more similar to bitcoin and Ethereum, which have been explicitly recognized by the CFTC as goods subject to its jurisdiction.
All in all, a quick review of these products led us to the conclusion that the current digital asset economy and FTX products are very similar to those in the traditional financial sector. This reflects the maturity of the industry as more sophisticated investors enter the sector and demand products and solutions they are familiar with in traditional finance.
Similarly, a defining feature of these products, unlike traditional finance, is that investors can access all of them on one platform, rather than going through multiple intermediaries. In addition, all market data is open and free, and all users have full access to orders and transactions. Easy access to financial products and solutions on an easy-to-use platform is a powerful feature that empowers investors, consumers and entrepreneurs. By simplifying the use of these tools, users can focus more on their daily financial goals and core needs, which is ultimately why FTX believes it can promote financial openness and economic security for more people.
2. Benefits of Stablecoin and its risk response & NBSP;
FTX considers Stablecoin to be one of the most important payment innovations in the digital asset industry, and users on our platform rely heavily on using Stablecoin for payment and settlement transactions. FTX recognises the important work of the President's Working Group on Financial Markets and we read with interest the recently released Report on Stablecoin. FTX has shared advice on how best to ensure the safety and robustness of Stablecoin, which I list here as an exhibit for this statement, clickhttps://www.ftxpolicy.com/stablecoinsLink to read.
In addition to our recommendations for the regulation of Stablecoin, FTX believes that there are two key points worth raising with this committee, which are listed here for your information.
First, the Committee should understand that FTX does not believe that there is currently bank-type federal regulation of Stablecoin issuers. FTX allows stablecoins to be used on our platform and does use them for our own corporate fund transfers because we believe they reduce risk. In fact, FTX has chosen to use Stablecoin to transfer very large funds, including our M&A activities, rather than through the traditional banking system.
While Stablecoin is seen by some as less risky than the heavily regulated payment routes of the banking system -- because Stablecoin transfers are settled almost instantaneously and can be easily confirmed by both parties by looking at deposits in wallets on the public chain -- it is a distinct difference from the typical wire transfer process. There are many middlemen between transferor and transferee in the process of telegraphic transfer, and each middleman has the risk of counterparty. It takes several days to complete and settle; And it's expensive compared to Stablecoin transfers. Other payment systems (such as ACH or credit card networks) also have scale limitations and cost issues that they hide from users.
FTX therefore doubts that bank-like regulation of all Stablecoin issuers is the best solution for consumers. Our concern is that in either case, bank-like regulation might inadvertently introduce the risks Stablecoin currently avoids. However, we recognize that both the publisher and the Stablecoin they issue should meet a minimum standard of certain core requirements, including: & NBSP;
1) Daily document which assets (cash, bonds, etc.) support Stablecoin.
2) Regular audit to confirm whether asset support meets requirements.
3) Impairment of assets with moderate risk.
4) Provide an open line for law enforcement to blacklist addresses and people associated with financial crimes.
These core requirements can be met in a variety of regulatory Settings, including regulators other than federal bank regulators, such as the CFTC or the Securities and Exchange Commission (SEC). In fact, members of Congress have introduced legislation targeting these regulatory agencies.
Secondly, FTX believes that the continued use of stablecoins with appropriate standardized safeguards will protect the hegemony of the US dollar as the world's reserve currency, rather than threaten it. Again, this might seem counterintuitive, but the most widely used stablecoins today are pegged to the DOLLAR, so eventually these stablecoins are denominated in dollars. Such a system would only promote the world's continued reliance on the dollar, not threaten it. In fact, FTX is concerned that overly onerous regulation of stablecoins risks the reserve currency status of the DOLLAR, as Stablecoin publishers may be forced to move to other jurisdictions and focus on stablecoins tied to fiat currencies other than the DOLLAR.
To be sure, consumers would benefit most from some level of competition among payment providers, which U.S. policy makers have previously allowed or facilitated. FTX argues that for policymakers, new innovations (including stablecoins in payments) are often achieved outside the defined regulatory boundaries, which usually means that service providers within the same range are not providing the services the market needs, often for a variety of reasons. However, in order for innovation to continue and healthy competition to continue, policymakers should be careful to maintain the right balance and not insist on moving all innovators into the same regulatory sphere. FTX commend the committee for its hearings and the benefit of being aware of innovations such as Stablecoin before acting on the recommendations of the PWG report.
3. Market regulation and operation challenges of encryption platforms in the United States
The committee has in the past asked thoughtful questions about the best way to oversee cryptocurrency platforms that offer transactions, and some members of the committee have indeed proposed legislation addressing the subject. Other members questioned the need for federal-wide legislation. We are very grateful for that.
Last week, FTX released the "Main Principles of Market Regulation for FTX's Cryptocurrency trading platform". I list it here as evidence for the claim, which readers can click onhttps://ftxpolicy.comTake a look. The document was designed and released to help the Commission and other policy makers consider how best to protect investors and serve the public through reasonable market regulation of cryptocurrency platforms.
The FTX Key Principles document contains some details, but I would like to highlight a few points here for the Committee's consideration.
1. In considering a framework for monitoring the trading markets for cash and derivatives cryptocurrencies, policymakers should take a principles-based approach, leveraging existing policy objectives that apply to traditional capital and derivatives markets. These existing policy objectives are broadly common to all markets and include ensuring customer and investor protection, promoting market integrity, preventing financial crime, and ensuring the safety and soundness of the overall system. FTX believes that any new policies relating to cryptocurrency platforms should also serve these objectives, which necessarily means that many of the principles reflected in the Commodity Exchange Act (CEA), the Securities Act of 1933, and the Securities Exchange Act of 1934 are relevant to our industry. FTX believes it makes sense to make appropriate use of these objectives as well as the experience and expertise of the CFTC and SEC.
Second, FTX and other cryptocurrency platforms have brought important innovations to trading, and a sound policy framework should preserve these innovations as much as possible, as they help minimize risk, promote capital efficiency and protect investors in order to better serve the public. As mentioned in this statement, some of the key innovations include:
(1) Automatic risk management system, which ensures that customer accounts trading a variety of different assets will not have a net negative customer position;
(2) round-the-clock trading hours, which reduce risk by allowing the market and its systems to manage risk without interruption and too long a market interval;
(3) Allow non-intermediary market structure, so that all investors have the same and equal access to the market, which helps to minimize conflicts of interest;
(4) Market data is freely available to all platform users, which aligns the interests of platform operators with those of investors.
A successful policy framework should allow cryptocurrency platforms to offer spot and derivative trading of cryptocurrency assets under a unified system, with a set of rulebooks and a technology platform to manage the risks associated with all trading activity in customer accounts. In jurisdictions with mature markets, such as the US, regulatory frameworks are designed to address the fragmentation of markets for securities, commodities and derivatives for these assets. FTX has demonstrated that the integration of assets and derivatives markets for these assets provides important benefits to market participants. These benefits come from having a rulebook that applies to all trades, having a collateral and risk margin program, and a single technology stack from the front end (user interface) to the back end (settlement and risk management positions). Public policy should allow this single rulebook model to continue because of its risk reduction and customer protection properties.
To achieve this, where there are multiple market regulators, such as in the US, regulators should work together and can use their powers, where applicable, to adapt to the crypto asset model. Our key Principles document proposes a scenario in which crypto platform operators could opt into a joint CFTC and SEC regulatory program, with one of the two market regulators serving as the primary regulator and the other as a subsidiary regulator. This model, which is familiar to global market regulators, requires shared responsibility and co-operation among regulators. One feature of this pattern is the need for a primary regulator, which may be necessary to ensure that a set of rule books, a matching engine, and a risk engine supported by a technology stack are accommodated. It is these characteristics that again reduce risk.
FTX believes that such a model could essentially be created under existing CFTC and SEC agencies, but there may be other policy gaps, including appropriate treatment and disclosure of certain types of crypto assets -- assets that are not exactly securities, or whose function and purpose can change over time, But it fits CEA's definition of a good in any case. While some of these tokens count as securities, others are not clearly classified under existing definitions, so policymakers should probably establish more definitions and different disclosure frameworks for some assets. In any case, the key tenets of FTX are to once again assume that all tokens and derivatives based on them can be traded on the same platform, under the same set of rule books, and that there is a unified system to manage the risks associated with all trading activity in customer accounts.
Fourth, an appropriate regulatory policy framework for crypto asset markets should maintain market structure neutrality and explicitly allow the existence of non-intermediary markets. While FTX believes that U.S. market regulators have the authority to accommodate the current type of market structure, it is not the market structure that the CFTC and SEC regimes generally consider. As the owner and operator of registered futures markets and clearing houses, FTX is quite familiar with the CFTC system and believes that the CFTC's princips-based approach to overseeing these functions makes sense. The system platform operators should make public and approved policies and procedures in order to solve the key problems, such as asset custody, key characteristics related to the transaction life cycle and report to regulators market activities, provide market data to the platform, to ensure enough financial resource, as well as to prevent the network attack and financial crime. This type of approach makes particular sense given the continuing emergence of digital asset classes. It gives the CFTC and platform operators the flexibility to respond to new market developments by rapidly changing the platform's rulebooks, policies, and procedures.
Conclusion & have spent
FTX thanks the Committee for the opportunity to share information about the digital asset ecosystem and suggest ways to continue to reap industry benefits and deliver on its promises in a responsible manner.
FTX believes that most or many of the products and tools it offers on the platform can continue to be made available to US customers within the current regulatory paradigm, despite some careful modifications or fruitful explanations by regulators in some cases. Our recommendations for Stablecoin and market regulation are based on our view that new policies affecting the digital asset industry and FTX business should build on the best existing policies. Through this approach, FTX believes that by combining the best aspects of traditional finance and digital assets, consumers will continue to use this empowerment tool to seek economic security, all in one place and from a single low-risk platform.
The appendix
Stablecoin regulation & have spent
Note: As regulators around the world continue to consider whether and how to regulate various components of the digital asset ecosystem, we felt it was critical to share our views on practical, responsible and thoughtful regulatory approaches. This article is not a comment on the current regulations surrounding stablecoins, nor is it a legal interpretation of them, nor is it a recommendation for the applicability of trading or owning a particular Stablecoin. This article is an exploration of a hypothetical Stablecoin new regulatory framework designed to address key regulatory priorities and preserve key usability characteristics.
Background of Stablecoin regulation & NBSP;
As the cryptocurrency industry matures, it is critical to have a strong regulatory regime in place and grow with it. In this way, the cryptocurrency industry takes seriously its responsibility to protect consumers, ensure transparency and prevent illegal activities, while still allowing innovation and growth.
Stablecoins play a crucial role in the cryptocurrency ecosystem; Stablecoin, through which most crypto transactions are settled, is one of the most promising payment tools in the broader financial sector. As of now, it is not clear what regulatory regime Stablecoin will end up under.
What is a Stablecoin?
Let's start with the core question: what exactly is a Stablecoin?
A variety of Stablecoin designs are used in the cryptocurrency ecosystem. For illustration purposes, we assume the dollar is a Stablecoin in this article, although parallel assets do exist in the euro, sterling and other currencies. Let's say it's one to one; That is, one Token represents $1. We also assume that the Token will use the ticker symbol STBC.
In this scenario, the hypothetical Stablecoin-STBC is a blockchain-based asset that can be exchanged for dollars. This can usually be achieved through the following mechanisms and arrangements:
Reserves: usually, one & NBSP; Stablecoin is backed by one or more US dollar accounts or other similar assets, usually held by banks, in the name of Stablecoin promoters, issuers or other similar entities. The dollar value of these assets should be at least the supply of stablecoins.
Tokens: STBC is a blockchain-based Token, with one Token representing $1 (supported by the create/redeem process, described below). These tokens can be issued by private companies, central banks or decentralized agreements.
Create/Redeem: In order to create an STBC Token, an eligible user must deposit $1 into a reserve account. In return, the agreement mints a new STBC Token and returns it to the user.
Similarly, eligible users can send 1 STBC Token back to the protocol to redeem $1. The protocol destroys the Token and returns $1 to the user.
What are the benefits of Stablecoin?
We believe that... Stablecoin is one of the most important innovations in the cryptocurrency industry.
Suppose you want to transfer $20 to a friend. What are your options?
A) You might want you and your friends to all use the same peer-to-peer money transfer app (like Venmo) and then each figure out separately how to send/send money from that app.
B) You can send a wire transfer of $20 to your friend. This can take a day and cost more than $5; If you send money internationally, it can take a week and costs much more.
C) If you and your friend both use US dollar bank accounts, you can send us $20 via ACH. Then the transfer would not be fully settled for several months and both parties would face "refund risk".
D) You can go to the ATM and withdraw $23, pay a $3 fee, and give $20 to your friend, who then has to find a way to use the paper version of the dollar bill.
E) You can send 20 STBCS to your friend's cryptocurrency wallet; If an efficient blockchain is used (or both parties use the same trading platform), the money will arrive within a minute for a fraction of a cent.
Option (e) gives a convincing example of how Stablecoin is an efficient way to send money.
Taking our real-world use case one step further, suppose a user wants to build a blockchain-based application. How should users of the application store and retrieve assets?
At this point, users are faced with the same potential choices and cost structures as before; Stablecoin is once again the cheapest, safest and fastest way for users to use the app.
What are the risks of Stablecoin?
There are three main risks associated with Stablecoin:
Risk of reserve fluctuation
If Stablecoin is backed by money other than dollars in the bank account, the asset may depreciate against the dollar. For example, if you use a $1,000,000 SPY (S& P500) 1,000,000 stablecoins issued by ETF, and if the stock market price drops by 5%, then you are left with $950,000 supporting 1,000,000 Stablecoins, This means that the "stable" Token has actually depreciated, at least in terms of its purported redeemable reserves!
Unlike investment products, where the client benefits from the asset appreciation of the supporting product, stablecoins are typically not worth more than $1 because the client can always create more for each $1. This means that the core idea behind the stablecoin-backed assets should be to focus on assets with very low volatility, which are very similar to the dollar. Us Treasuries may be suitable assets for stable monetary reserves; If bitcoin is used, it must be over-mortgaged to reduce the risk of loss for Stablecoin holders. The risk of supporting 100 Stablecoins with $101 BTC is unbearable: a drop of just 2% in the Bitcoin market would cause stablecoins to fall short of full conversion to $1. On the other hand, backing 100 Stablecoin stocks with $400 BTC is more defensive, as 75% volatility risk is small until the forex reserves have a chance to reduce risk. Any Stablecoin issuer or designer must have a transparent, robust risk model to mitigate the volatility of their reserves and determine which assets are suitable to hold as reserves.
The redemption risk
A related concern is that a user may have 1,000 STBCS, go to the card issuer to redeem their STBC, and be rejected.
This would happen if the reserves were in fact running out of dollars. So there's nothing to redeem the STBC; This could mean that the reserves are not dollars and have depreciated.
Or it could happen if the issuer arbitrarily decides to block your redemption, perhaps to preserve more impressive metrics for the STBC.
In either case, the lack of redemption capability (or lack of transparency in the redemption process and requirements) creates risks for users.
Financial crime
The final risk of stablecoins is that they could be used for financial crimes or to finance illegal activities.
Any publisher or designer of Stablecoin must include creation, redemption, and use mechanisms that are coordinated with regulations to address and avoid this use case.
What is a reasonable Stablecoin regulatory framework?
As stated above, we believe Stablecoin presents an important positive use case to the world and has the potential to revolutionize the payments and remittance industry. Stablecoin will revolutionize the payments industry in the future, dramatically reducing friction and transaction costs and bringing reliable and usable value delivery to people around the world. We believe, therefore, that it is important to ensure a continuing regulatory discussion around the Stablecoin framework approach, based on a practical structure that addresses the same issues of availability, reliability, transparency, consumer protection and the identification and prevention of financial crime.
We look forward to talking to regulators about what such a framework might look like. There are many different approaches, and we are happy to receive feedback from regulators and other players in the cryptocurrency industry and welcome their active participation.
As mentioned above, stablecoins carry real risks and frameworks should be built to mitigate these risks.
So while we look forward to continuing discussions on the details, we will support the Stablecoin proposal for a transparency-based reporting and registration system.
The proposed framework might look something like this:
A) Stablecoins must be issued to US users under the supervision of one or more US regulatory authorities and registered on the official list of "Regulated Stablecoins".
B) The registration itself will be based on notification filing, with a focus on transparency and reporting, while clarifying obligations for record keeping, reporting and periodic inspections. The regulatory authority authorizing the program will have the authority to decertify registered Stablecoin.
C) Registration will include publishing a daily reserve list detailing the total net Stablecoin reserves and breaking it down into exact quantities of specific categories (e.g. "XYZ Bank $100; US Treasury bill $95; US corporate Tier 1 commercial paper $50; European corporate Tier 1 + commercial paper $30; [other appropriate assets permitted by regulations and Stablecoin registration documents] $10")
D) Require issuers to maintain "adequate" reserves. This can be defined by the reduction of various types of reserves. In an FDIC-insured bank account, for example, the dollar discount might be 0.10%; American Treasury bills were down 1%; 10% discount of grade I or above commercial paper; A 15% reduction in tier 1 commercial paper; 20% reduction of Euro, British pound, Japanese yen, Swiss franc, Canadian dollar, Australian dollar, Singapore dollar and Hong Kong dollar; And a 50% discount on Bitcoin.
E) To confirm the representativeness of the reserve, the accounting firm is required to conduct an audit every six months.
F) Stablecoin is required to have clear and transparent redemption requirements (for example, based on knowledge of your customer documentation) and a clear customer complaint process if a redemption is rejected.
G) In order to address financial crime, all registered Stablecoins must be on the public ledger, and the creation and redemption process must be sufficiently structured to ensure that stablecoins associated with illegal activity (as observed through an on-chain monitoring and analysis tool through a standard blockchain monitoring software set) cannot be called back.
As mentioned above, this is a basic framework for illustrating the key components of a potential Stablecoin registration program. Each of these points is designed to protect the availability of Stablecoin while addressing regulatory issues that need to be addressed. If designed correctly, this framework can enhance the ultimate usability of Stablecoin. We look forward to engaging policy makers, regulators and market participants on these concepts.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles