Arthur Hayes: Why He Is Strongly Bullish on ENA
Original Title: Yen-quake
Original Author: Arthur Hayes, Co-founder of BitMEX
Original Compilation: Golem, Odaily Planet Daily
Editor's Note: In his latest article "Yen-quake," Arthur Hayes argues that the Japanese yen is poised to appreciate against the US dollar, with the most likely path being the Japanese government utilizing the FIMA mechanism to pledge its held Treasury bonds to the Federal Reserve for repo financing, borrowing US dollars, and then using those dollars to buy yen. Arthur Hayes also states that this will lead to a surge in dollar liquidity, driving up the prices of assets such as Bitcoin and physical gold. He believes that at this stage, aside from Bitcoin and Ethereum being undervalued, ENA is also expected to rise 5-10x in the coming months.
Arthur Hayes reveals that his "bullets" have not all been spent yet, and what he must now wait for is Warsh convening the subcommittee and amending the FIMA rules, paving the way for Japan to use the FIMA mechanism to drive yen appreciation. Odaily Planet Daily has compiled the core content of the full article as follows, enjoy~
Over the past decade, the yen has weakened continuously and even become extremely weak, driving global asset markets ever higher. But like all good things that benefit wealthy financial asset holders, this situation will eventually come to an end. The yen is the most undervalued currency in the world and a focal point of debate between the two major powers, China and the US, as well as ordinary Japanese voters. To unravel the yen conundrum, there are three paths, but the US Treasury and Japanese politicians favor only one of them.
I will explain the mechanics of each method to drive yen appreciation and summarize why the last one is the preferred option. Subsequently, I will discuss how to implement this third option at the political level. Finally, I will elaborate on why, as dollar liquidity surges, Bitcoin and cryptocurrencies will experience a massive rally (I know this is also why you read my "human nonsense").
The three options are as follows:
1. The Bank of Japan (BOJ) sharply raises interest rates, thereby eliminating the interest rate differential between the dollar and the yen (at least in terms of short-term rates);
2. The government lobbies domestic institutions and public institutions (such as the Government Pension Investment Fund GPIF) to change investment strategies, selling overseas assets and buying domestic assets;
3. [Preferred Option] The Japanese Ministry of Finance (MOF) pledges its held US Treasury bonds to the Federal Reserve through repo to obtain US dollars, then sells dollars in the foreign exchange market and buys yen.
Before diving into the details, all you "degens" in the crypto world should ask yourselves: why are we discussing yen appreciation at this time? Over the past few decades, countless people have predicted that the yen was about to appreciate and bring an end to the global carry trade. Two weeks ago, senior monetary policy officials from the US and Japan carried out a joint currency manipulation operation, which was of course euphemistically called "intervention" by the authorities. The same behavior, if done by ordinary people, would be called "collusion" and "conspiracy"; but when the operators become nations, it is called something entirely different.
US Treasury Secretary Bessent declared that he wants the Federal Reserve to raise the counterparty limits on the FIMA repo facility so that Japan's Ministry of Finance can use its massive asset reserves to defend the yen exchange rate. Japan's Ministry of Finance also announced that it is working with the US side to push down the USD/JPY exchange rate. The authorities have made it clear that they will change the global monetary landscape, so we must take this seriously.
Three options to drive the yen stronger
Options one and two simply won't work, because none of the parties involved can bear the political and economic consequences of departing from the policies established since the 2010s.
Option One: The Bank of Japan raises interest rates
Currency trading is often based on interest rate differentials, and the yield on the dollar is 2.75% higher than that on the yen. Borrowing yen, converting it into dollars, and buying US Treasuries can generate a positive carry return. Therefore, according to the no-arbitrage principle, the USD/JPY exchange rate must rise (that is, the yen must depreciate against the dollar) to offset this interest rate differential. The most direct way to make the yen appreciate against the dollar is for the Bank of Japan to raise interest rates, bringing its rate level in line with other central banks that have been raising rates since the COVID-19 pandemic.
To understand the dilemma facing the Bank of Japan in raising interest rates, you must remember: because of the yield curve control (YCC) policy implemented over the past decade or more, that is, limiting the yield on 10-year Japanese government bonds by printing money to buy bonds, the Bank of Japan has become the largest holder of these "junk" Japanese government bonds.
Once interest rates rise, bond prices fall; the lower bond prices fall, the greater the Bank of Japan's unrealized losses become. Unlike ordinary investors, the Bank of Japan, which can print unlimited money, can withstand unlimited yen losses. However, once the Bank of Japan's large-scale money printing causes the world to lose confidence in the yen and stop accepting yen settlement for oil, food, medicine, and other transactions, the situation will become critical.
Although things have not yet reached that point, the Bank of Japan must face this potentially catastrophic prospect. It is precisely because of fear of seeing losses on its balance sheet that the Bank of Japan hesitates and only dares to make tiny rate hikes, watching helplessly as the market sells off long-term Japanese government bonds. As a result, the yen continues to depreciate, while inflation driven by imported energy severely hits the foundations of Japanese society.
Politicians do not want the Bank of Japan to raise interest rates, because they must issue Japanese government bonds to cover fiscal deficits. If yields rise, debt servicing costs will increase accordingly, which will weaken their ability to "buy off" ordinary citizens through various government subsidies (usually consumption tax cuts).
If the Bank of Japan raises interest rates rapidly, causing the yen to appreciate and thereby driving up USD/JPY exchange rate volatility, then all investors who use yen financing to buy global stocks or bonds will be forced to unwind their positions.
Remember July 2024? At that time, the yen exchange rate rose from 160 to 140 in just a few trading days. I wrote two articles providing in-depth analysis on this, but in short, the Bank of Japan's new governor, Kazuo Ueda, unexpectedly announced a rate hike and promised further rate increases in the future. The market panicked as a result, and speculators who were short the yen and long other financial assets rushed to unwind their positions. At the time, there were rumors that several hedge fund PMs were forced to leave as a result, just as Kenny G ended AI stock guru Leopold.
At that time, the yen exchange rate touched 140, and both the Nasdaq 100 Index and the Nikkei Index fell by more than 10%. The Bank of Japan panicked and announced on August 12 that it would consider "market conditions" when assessing the future path of rate hikes, which effectively meant that future rate hikes had been shelved. As soon as the news came out, the yen weakened, stocks bottomed out and rebounded, and resumed their upward momentum.
Compared with the central banks of other countries, the Bank of Japan has moved too quickly in the process of interest rate normalization, and therefore cannot withstand the severe market pressure triggered by it.
Option Two: "Japan Inc." sells overseas assets to repatriate yen
I define "Japan Inc." as the corporate and public sectors that hold financial assets.
Albert J. Alletzhauser recounts an interesting anecdote in The House of Nomura: The Inside Story of the Legendary Japanese Financial Dynasty: after the 1987 stock market crash, Japan's Ministry of Finance instructed Nomura Securities to buy U.S. stocks to support the market. As a private company, Nomura had no obligation to obey this instruction, but Japan is a society that values conformity and collective action, and Nomura ultimately carried it out.
Many times, the highest goal of a company is not shareholder returns, but achieving full employment and safeguarding "national honor" (whatever its definition may be). If the government suggests that private companies and individuals sell overseas assets (mainly U.S. stocks and U.S. Treasuries), sell dollars to buy back yen, and repatriate the funds, "Japan Inc." will comply.
The indicator that best releases the "Japanese capital repatriation" signal is none other than the moves of Japan's largest pension fund — the Government Pension Investment Fund (GPIF). GPIF is managed by a bureaucratic committee whose members are appointed by various government departments.
In 2014, in order to align with the massive money-printing policy under "Abenomics," the then Prime Minister, after years of effort, replaced GPIF's leadership, prompting it to vote in favor of increasing the allocation of overseas stocks and bonds in its portfolio. This was crucial because GPIF manages a portfolio worth as much as $1 trillion to $2 trillion. In October 2014, when their investment strategy changed, an unstoppable wave began — they started selling yen for dollars and buying U.S. stocks and bonds.
This move created a structural yen seller, which reassured speculators who could use cheap yen to finance various financial assets without worrying about the yen appreciating when loans were rolled over or repaid.
I mention GPIF because the head of Japan's Ministry of Finance, Mr. Katayama, recently declared that in his view, it is time to adjust GPIF's investment strategy to favor domestic securities over foreign securities. However, the bureaucrats within GPIF are not buying it and have publicly stated they will adhere to prioritizing the best interests of policyholders. Clearly, given that they are proponents of "Abenomics," they will never support shifting investment focus to Japanese domestic securities.
Just as Abe took control through personnel arrangements between 2012 and 2014, Prime Minister Takaichi must also employ the same tactics. For us investors, the signal is already very clear: GPIF's investment strategy will eventually change, forcing it to sell hundreds of billions of dollars' worth of foreign securities, and the capital repatriation will drive up the yen exchange rate.
Although this process will take years to complete, it is enough to make Bessent deeply worried, because it means that "Japan Inc.," as one of the largest holders of U.S. securities, will shift from a buyer's stance to a seller's stance. This will destroy the stock and Treasury bond markets that "His Majesty America" relies on to support its spendthrift empire. However, precisely because "His Majesty America" provides guarantees for Japan's national security, "Japan Inc." actually cannot sell off its holdings of U.S. assets.
What has been said above is nothing new. Everyone believes the yen exchange rate is at a low level, and both the U.S. and Japan want the dollar to appreciate against the yen. But if the USD/JPY exchange rate falls from 160 to 90 (the fair value based on purchasing power parity), neither side can afford the losses that would result.
And the moment Trump's close friend, "Weasel" Warsh (who indeed looks like a weasel and is just as cunning and sinister in his actions), became Fed Chair, the third option was approved for launch.
The 2026 "Treasury-Fed Accord" remains firmly in effect; beyond using reverse repo tools and a policy rate below nominal growth to directly fund the short-term Treasuries issued by Bessent, Warsh also has the authority to implement "Option Three," thereby once and for all adjusting the USD/JPY exchange rate to the level needed to rebalance the global economic system.
Option Three: Lending to America
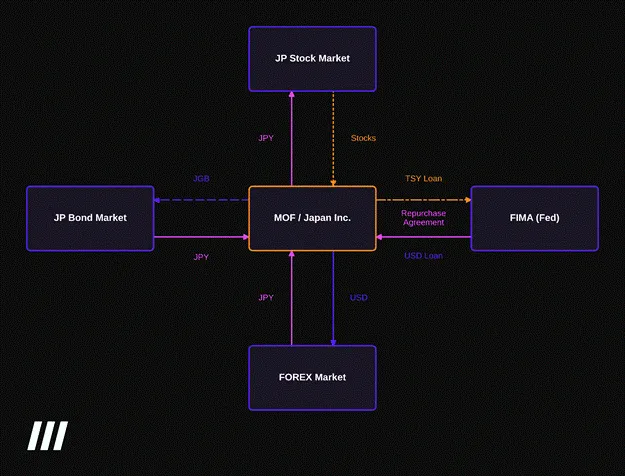
Bessent made it crystal clear: Japan's Ministry of Finance and Japanese companies should not raise funds to boost the yen by selling U.S. securities, but should instead use the FIMA facility to pledge their Treasury holdings to the Fed for repo financing, borrow dollars, and then use those dollars to buy yen. There's a small flaw in his plan, which I'll discuss later, but the "boxes and arrows" diagram above expresses exactly this process. Let's walk through it once more:
1. Japan's Ministry of Finance purchases Treasuries and obtains dollar loans from the Fed's FIMA facility;
2. Japan's Ministry of Finance sells dollars and buys yen in global foreign exchange markets;
3. Japan's Ministry of Finance reinvests these yen funds domestically, buying Japanese government bonds and equities.
The main effects of this policy include:
· The Fed provides dollar funding by printing money, and its balance sheet will expand in tandem with the increase in outstanding FIMA repo balances;
· A falling USD/JPY exchange rate means the yen appreciates;
· Japanese bond yields decline due to yen purchases of Japanese bonds;
· Japanese stocks rise due to yen purchases of equities.
So who's the "sucker" here?
1. American taxpayers: Japan owes American taxpayers money that, for political reasons, will never be repaid. Because this is purely money printing, it will trigger inflation in financial assets and physical goods. America cannot demand repayment of this loan by putting at risk its forward operating bases in the Asia-Pacific region against China and Russia.
2. Anyone short the yen: Once the trend becomes clear, they must immediately close their positions. This isn't a major problem, because USD/JPY volatility will decline, allowing the yen carry trade to unwind in an orderly fashion over many years.
Why has Option Three not yet been implemented?
The current situation is that the FIMA facility imposes a $60 billion cap on outstanding loans to each counterparty. In the most recent operation to manipulate the USD/JPY exchange rate, the U.S. Treasury and Japan's Ministry of Finance deployed over $100 billion, yet only managed to push the yen up by 5%, and that appreciation effect lasted only a few trading days. To utilize the FIMA facility, this cap must be completely removed, and the range of eligible counterparties must be expanded to include large Japanese corporations and quasi-public investment institutions (such as GPIF).
Who manages the FIMA facility? During the COVID pandemic, the Federal Open Market Committee (FOMC) delegated the authority to adjust the operational framework of the FIMA facility to the Subcommittee on Foreign Currency. The voting members of this committee include Warsh (FOMC Chairman), Williams (FOMC Vice Chairman and President of the New York Fed), and Jefferson (Vice Chairman of the Federal Reserve Board of Governors). The committee meets as needed at any time, publishes neither meeting minutes nor voting records, and the outside world can only learn of its decisions after the fact.
So, will this committee take orders from Bessent? The answer is absolutely yes.
Trump and Warsh communicate frequently, and given that Bessent has clearly articulated how to reshape the global economic balance by adjusting the USD/JPY exchange rate, Trump is obviously fully supportive. Therefore, Trump and Bessent will convey instructions to Warsh. Warsh has previously proven himself to be a slippery and blustering "paper tiger." Under Williams' stewardship of the New York Fed, the Federal Reserve's balance sheet continues to expand through RMP.
Warsh once claimed he would listen to the market when formulating policy, and the market clearly demands rate hikes, as the two-year Treasury yield has risen more than 0.5% above the effective federal funds rate, yet Warsh refused to raise rates at the July meeting. Instead of immediately undertaking thorough and drastic reform of how the Fed operates, Warsh set up five special working groups specifically to study how and why the Fed should change. I'm afraid that before these working groups produce any recommendations, "Godot" will have long since arrived.
(Odaily note: The allusion comes from "Waiting for Godot." Arthur Hayes is satirizing the efficiency of the five working groups—).
Therefore, Warsh has already proven in a short time that he is just another obedient partisan politician who merely does what his boss tells him. This is just like his predecessor, the spineless, sycophantic "softie" Powell, and even earlier, the "garden gnome granny" Yellen (who, after being promoted to Treasury Secretary, did transform into a "bad girl").
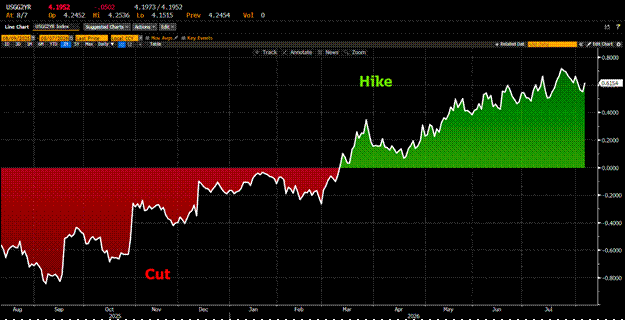
The difference between the two-year Treasury yield and the effective federal funds rate
I don't know when Warsh will convene the subcommittee to announce adjustments to the FIMA facility, thereby allowing unlimited money printing to manipulate the USD/JPY exchange rate lower, but I am certain it will happen. In fact, I am betting it will happen, and I am continuously increasing my investment exposure to assets that would reflect the impact of another massive expansion of the Fed's balance sheet. These assets include Bitcoin, physical gold, and gold miner stocks.
The implementation of the third option will push Bitcoin prices higher
The more the Fed prints money, the higher Bitcoin's price goes. So, is this FIMA trick enough to serve as a massive "pump," with trillions of dollars in enormous capital injected into it, thereby driving up the prices of the assets we hold?
Currently, we are only focusing on Treasury holdings, because Treasuries are the only assets eligible as FIMA collateral. This may change in the future, but let's first focus on the assets currently permitted under this facility. The two largest entities holding Treasuries are the Japanese government and GPIF. The Japanese government holds $1.143 trillion in U.S. Treasuries, and GPIF holds $230 billion, totaling $1.373 trillion.
That is a considerable amount. To put this scale into perspective, we can refer to the situation during the COVID pandemic, when the Fed printed approximately $4 trillion, as seen in the expansion of its balance sheet from 2020 through the end of 2021.
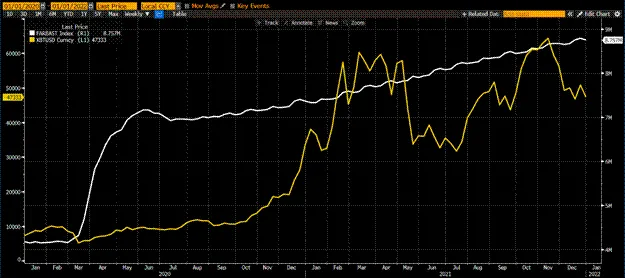
There is a very clear correlation between the growth in the Fed's balance sheet (white curve) and the surge in Bitcoin's price (gold curve). In a previous article, I speculated that the AI buildout is entering a phase of capital waste. This assertion is critical because the Trump administration wants this liquidity to be used to drive domestic U.S. AI capital expenditure, rather than to push up cryptocurrency prices.
But I believe that extending credit at this point to AI companies that cannot achieve positive returns on capital (whether those hyperscalers that have invested heavily but cannot truly turn a profit, or those U.S. AI labs that cannot achieve profitability at "China market token prices") is essentially wasteful; and the rise in Bitcoin's price precisely reflects this non-productive use of capital.
Recently, the price of gold has rebounded sharply from its cyclical lows, sending us a signal: the market would rather channel the impending flood of fiat dollars into monetary and financial assets than hand money to Altman's "money-burning machine" OpenAI, or Musk's pie-in-the-sky space data centers.
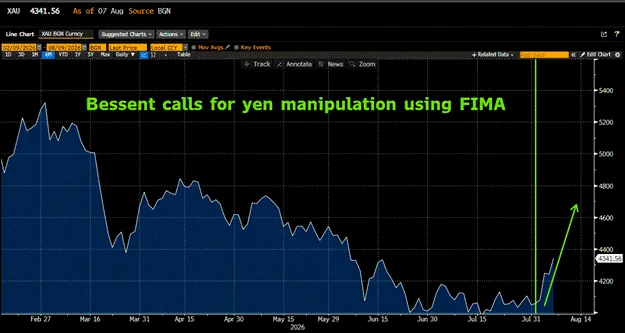
The altcoin frenzy is coming, bullish on ENA for a 5x return
I know you all want to understand what we're specifically doing at Maelstrom, but to build investment conviction, you must first understand the macro backdrop.
As I said earlier, when Bessent speaks, I listen intently. If there's one thing he's a master at, it's currency manipulation. Just Google his illustrious track record working with Soros, and you'll understand. Implementing this kind of monetary "trick" requires neither the approval of elected politicians nor the nod of those whose terms are expiring and who face public Senate confirmation hearings. All it takes is convening that usually sleepy "Foreign Exchange Subcommittee" to tweak the rules of the game, and it can trigger a gusher of dollar printing.
When I saw the news about Bessent calling for reform of the FIMA mechanism, I immediately had a bullish intuition. Every macro analyst I follow believes this signals a major turning point in the USD/JPY exchange rate trajectory. You have to position ahead of time, because this time they're playing for keeps.
Money printing is a political decision made to address unsustainable economic realities. Politics is always complicated, but under current circumstances, the Trump administration's intention is clear: they want you to log into your brokerage account and buy financial assets. That's exactly why Bessent is explicitly signaling to anyone who will listen, pointing out where the printed money will begin to spread. I'm listening, and I will fulfill my "duty" — Buy in.
We already hold a large amount of Bitcoin, so the next question is who else will perform better?
This is not an AI stock recommendation article, but if you're interested in that stuff, feel free to buy the dip. The "Leopold Low" has already provided you with an excellent entry point for AI-related assets. Speaking of crypto, the large-cap dark horse that has yet to explode is ETH — the only major coin that failed to break its all-time high in the 2025 rally; moreover, Ethereum will become the security layer for RWA assets.
Next up is an altcoin at its lows but poised to easily achieve a 5x to 10x gain — Ethena (ENA).
One issue with Ethena is the lack of a buyback mechanism, but given that it is still the sixth-largest USD stablecoin by circulating supply, this can be overlooked. The problem with ENA is that, as the token price decline caused Bitcoin basis yields to disappear, the yield for holding USDe is now only slightly higher than that of U.S. Treasuries. Taking on centralized exchange counterparty risk and smart contract risk just to hold staked USDe is simply not worth it.
Because of this, its circulating supply has dropped 75% from its peak, and the ENA token price has fallen by more than 90%. But even a small increase in dollar liquidity in the future could push Bitcoin prices higher, thereby driving basis yields up and causing a large inflow of funds into USDe. ENA does not need much to escape its slump, so over the next few months, it may be a "speculative" option worth considering for a quick 5x.
I have not yet used all my bullets, and we must wait for Warsh to convene the subcommittee and revise the FIMA rules. Keep a close watch, because this could suddenly happen when no one is paying attention. However, gold and the USD/JPY exchange rate should begin fluctuating before the policy announcement. After all, those large players close to the Trump administration are very likely to position themselves ahead of the news. This kind of situation is common in other asset classes, and gold and foreign exchange markets are no exception.
In short, the days of "cheap" yen are coming to an end.
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia