Zero funding rate? The HyperEVM new contract design that foreigners are all talking about
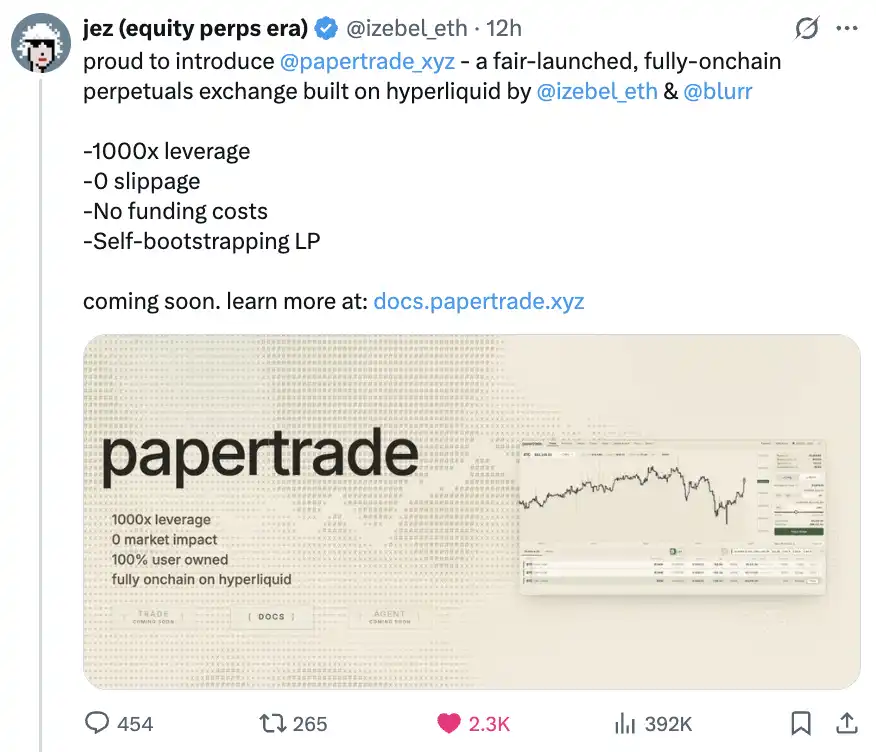
Crypto trader Jez announced his new protocol PaperTrade, developed on HyperEVM, in May this year, sparking heated discussions in the English crypto community. According to the official plan, PaperTrade will officially launch tonight at 22:00. BlockBeats has compiled the project-related information as follows:
Jez is a long-time evangelist of perpetual contracts. He heavily invested in Hyperliquid early on, and his account address ranks at the top of the airdrop points leaderboards for Lighter and Variational. This time, he personally stepped in to create a Perp DEX with no fees, no slippage, and no funding rates.
Ancient Casino Exiled On-Chain
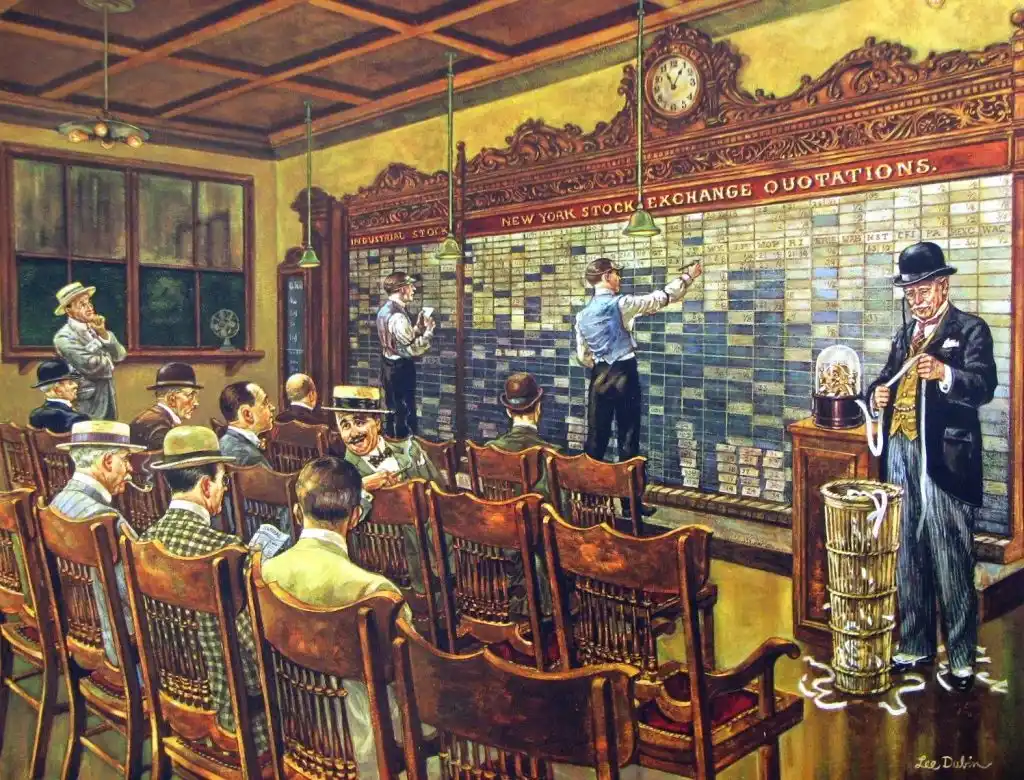
The mechanism of PaperTrade has a disreputable predecessor in financial history. In the 1900s, bucket shops in small American towns hung up securities firm signs, with chalk-written real-time quotes from the NYSE behind the counter, but customer orders never left the owner's drawer. Essentially, it was customers betting against the shop owner. This business was legislated against in New York State in 1909 and largely died out by the 1920s.
When users open or close positions on PaperTrade, the platform directly reads Hyperliquid's order book prices and settles the difference between opening and closing directly against the public LP pool. Throughout the process, no orders enter Hyperliquid's matching system, and there is no real perpetual contract turnover. The trading parties are always the user and the LP pool, with no third-party counterparty.
Perpetual Contracts + P2P + DeFi Ponzi
PaperTrade draws on models from both DeFi mining and P2P lending.
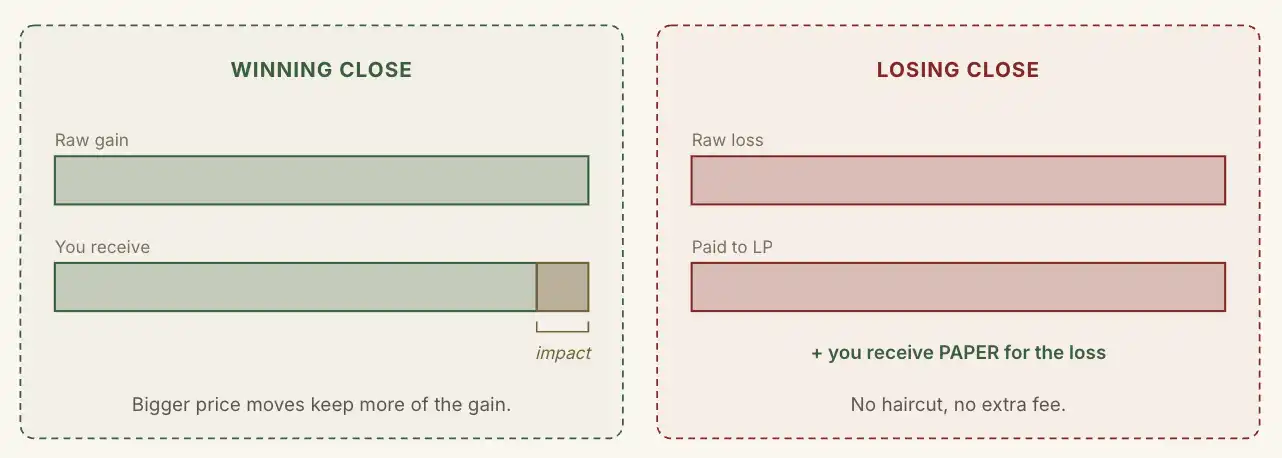
Users' losses on PaperTrade go directly into the protocol's LP pool, while users' profits are subject to a platform cut. The smaller the price fluctuation, the more profit is collected. In other words, the more users earn, the less the protocol takes as a cut.
Unlike HLP, PaperTrade's LP pool has no team pre-deposits, no VC funding, and does not accept any form of external deposits. Its only source of funds is the margin from users' losses.
The question arises: if the LP pool only has $100, but a user earns $5,000, how does the protocol pay out?
PaperTrade brings the debt queue of traditional P2P lending onto the blockchain.
This $5,000 will enter an ordered on-chain queue, waiting for the next losing trade to come in and fill the hole, with the queue paying out from the front in order. Users' principal is always returned first, and only the profit portion gets queued.
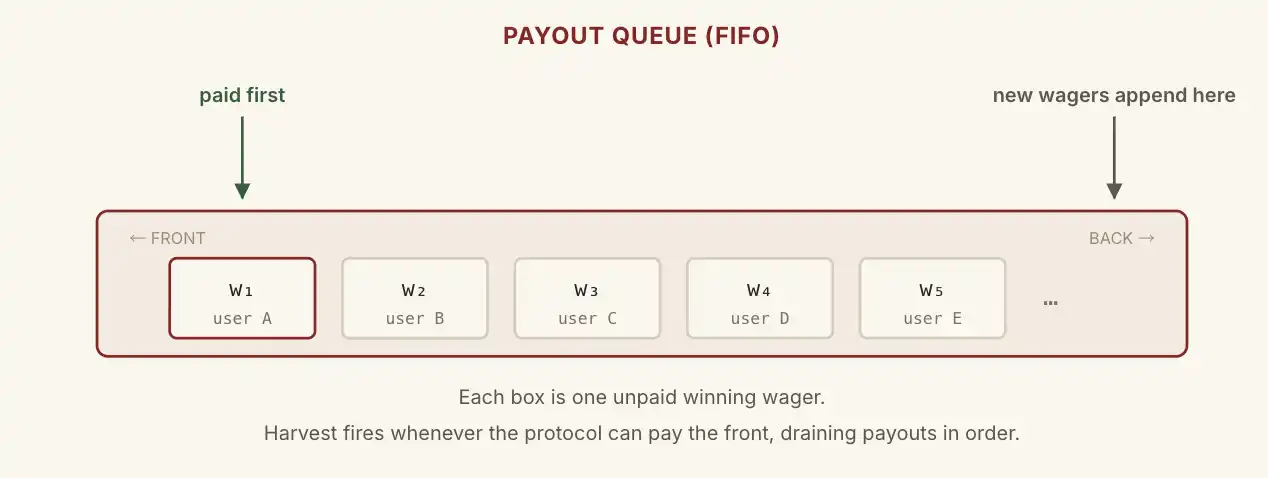
Theoretically, the LP can be temporarily "insolvent," but every winner will eventually be paid in full, unless the losers' losses cannot cover the profits the platform owes to the winners.
If it ended there, the project would be doomed to die, because if the LP pool runs out of money, it means winners may have to wait a long time in the queue to get their profits, and naturally there would be no incentive to trade. Traders would leave one after another, and even the losers would be gone, and the money the platform owes the winners would become bad debt.
The essence of PaperTrade is its token PAPER.
Every time a user loses one dollar, the protocol mints a certain amount of PAPER according to a curve.
When the LP balance is below $2 million, the minting ratio is fixed at 100 PAPER per $1 lost; after the LP exceeds $2 million, the rate begins to decay, and the larger the LP balance, the less PAPER is minted.
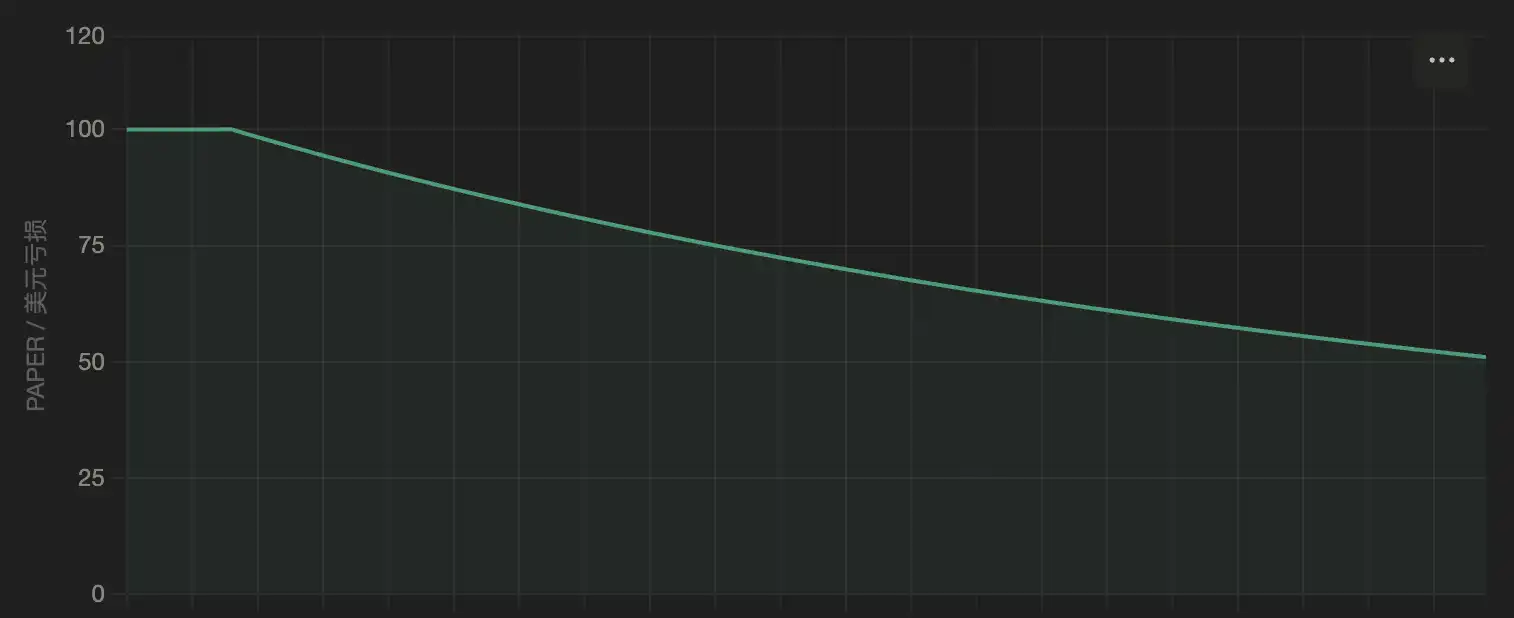
X-axis: amount of PAPER received per unit of loss; Y-axis: LP balance (one grid = 1M)
Staking PAPER earns two types of dividends: first, the protocol's rake income; second, once the balance exceeds $5 million, all excess amounts are fully allocated to stakers.
In other words, the size of the LP pool is designed with a $5 million ceiling. Beyond that size, users' losses are fully returned to PAPER holders. This forms a closed loop of "losers receive platform equity, winners take the losers' money, and the platform rakes winners to subsidize losers."
Therefore, a reasonable participation strategy can be summarized as: bet and lose money to mint PAPER when the LP pool's TVL is low, and stake PAPER when the LP pool's TVL is high to collect dividends.
HyperEVM's Stress Test
In my view, the biggest uncertainty for PaperTrade lies in its deployment on HyperEVM.
PaperTrade merely uses Hyperliquid's quotes as a free native oracle, while all remaining logic resides in contracts on HyperEVM.
This means that any high-performance chain with similar capabilities, as long as it is willing to integrate an external price oracle, can replicate PaperTrade's entire mechanism on its own chain. Replicators could even offer what HyperEVM cannot: lower gas fees, higher TPS, more generous early subsidies, and more aggressive token incentives.
During last year's Q1 meme season on HyperEVM, there was a period of slow on-chain speeds and high gas fees, and PaperTrade's launch represents another test for HyperEVM.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia