



Coinbase vs. Wall Street: Who Is Deciding the Next Move for the US Financial System?
Original Title: The Crypto CEO Who's Become Enemy No. 1 on Wall Street
Original Authors: Amrith Ramkumar, Dylan Tokar, Gina Heeb, the Wall Street Journal
Translation: Peggy, BlockBeats
Editor's Note: When the cryptocurrency industry truly touches the financial core areas of banking deposits and payments, the conflict is no longer a battle of ideas, but a battle of interests. This article takes Brian Armstrong's confrontation with Wall Street as a clue to reveal the nature of the game between banks and crypto platforms behind the "CLARITY Act." This is not only about whether stablecoin yields are legal, but also about who will dominate the rule-making power of the next generation financial system.
The following is the original text:
Last week, during the World Economic Forum held in Davos, Switzerland, Brian Armstrong, the CEO of the largest cryptocurrency company in the United States, was having coffee with former UK Prime Minister Tony Blair when Jamie Dimon suddenly intervened.
"You are talking nonsense," Jamie Dimon, who has long been skeptical of cryptocurrency and once called Bitcoin a 'fraud," said, pointing directly at Armstrong's face with his index finger.
According to sources familiar with the matter, Dimon's core message was simple: he wanted Armstrong to stop lying on television. Just the week before, Armstrong had accused banks on multiple business TV shows of trying to sabotage a piece of legislation that aims to establish a new regulatory framework for digital assets.
This public confrontation was clearly not in line with the purpose of the Davos annual meeting to "promote global leader cooperation."
As the crypto industry rapidly enters the mainstream US financial system, some heavyweights on Wall Street have begun to realize that a threat is looming. Although banks have to some extent embraced crypto assets—such as helping clients invest in Bitcoin or using digital assets to enhance cross-border transfer efficiency—when crypto businesses touch their core territory, banks choose to draw a line: resident deposits.
Surrounding a key issue, banks and Coinbase are in a direct conflict of positions: should cryptocurrency exchanges be allowed to offer "yield on holdings" to users. This so-called "reward" usually refers to regularly paying stablecoin holders a certain percentage return, such as 3.5% annualized. Stablecoins are a type of digital asset pegged to real-world currencies like the US dollar.
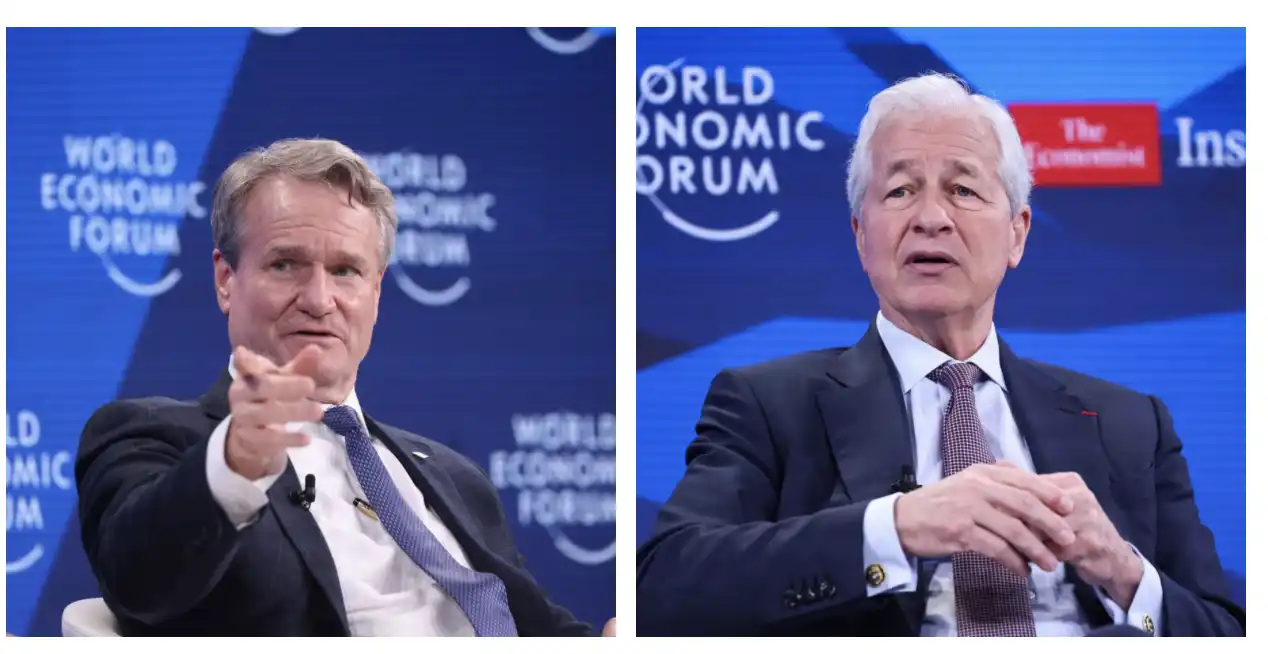
Bank of America CEO Brian Moynihan and JPMorgan Chase CEO Jamie Dimon.
Banks argue that such user-pay rewards are essentially no different from bank account interest. Due to the much lower yield offered by banks — typically below 0.1% for savings accounts — they are concerned that the result will be a significant number of consumers moving funds into crypto assets. This outflow of funds, banks argue, will weaken the viability of community banks and impact lending to businesses.
On the other hand, Brian Armstrong and other crypto industry figures believe that the free market should prevail: banks could easily compete by increasing deposit rates or by entering the stablecoin business themselves.
This legislation, called the Clarity Act, could reshape the future of everyday financial services, including bank deposits and electronic payments.
According to sources familiar with the matter, in the latest round of compromise-seeking efforts, the White House is planning to convene a meeting on Monday between banking and crypto industry groups, with David Sacks, the Trump administration's AI and crypto affairs lead, expected to attend. Coinbase's US policy chief, Kara Calvert, is also among the invitees.
At 43 years old, Armstrong co-founded Coinbase in 2012 and has played a key role in pushing for legitimacy and mainstream adoption in the crypto industry. As the head of a company valued at around $55 billion, Armstrong holds significant sway in industry debates, especially in this Washington-centered game.
Just a day before a Senate committee was set to vote on a certain version of a bill — a version that could substantially prohibit companies like Coinbase from offering rewards to customers, potentially causing losses in the billions — Armstrong posted on X Platform, "We would rather not have a bill than have a bad bill."
A few hours later, the vote was unexpectedly postponed, much to the surprise of the financial industry.
Policy and Advocacy Lead at digital asset trading firm Wintermute, Ron Hammond, said, "It now seems more like Coinbase versus banks rather than the crypto industry versus banks."
Armstrong's counterattack did not stop with the January 14th X tweet. He later reiterated his views on a TV show, stating in a Bloomberg interview that bank lobbyists "are trying to stifle competition" and accusing banks of "essentially taking their deposits and lending them out without customer permission."
According to sources familiar with the matter, these comments directly led to a series of uncomfortable confrontations with several bank CEOs in Davos.
"If you want to be a bank, just go be a bank." Brian Moynihan said this to Armstrong last week during a 30-minute meeting at the main Davos venue. The meeting appeared friendly on the surface but somewhat tense.
Citigroup CEO Jane Fraser only gave Armstrong less than a minute. (Coinbase is a client of both Citigroup and JPMorgan and has business partnerships with multiple banks.)
And this "one minute" was even more than what Wells Fargo CEO Charlie Scharf gave. When Armstrong approached him, Scharf bluntly stated that there was "nothing to talk about." Dimon, Scharf's former boss, was nearby when this happened.
"Banking Disruptor"
Armstrong studied economics and computer science at Rice University in Houston and was an early advocate of digital currency and blockchain concepts. He had read the Bitcoin whitepaper published in 2008 by the pseudonymous Satoshi Nakamoto and, during his time at Airbnb in 2011, was frustrated by the difficulty of sending remittances to South America.
These experiences paved the way for the founding of Coinbase. The company initially sought to address a core issue plaguing crypto investors: the lack of a secure place to store digital assets. Subsequently, as some users wanted more than just "hodling" Bitcoin but to engage in trading, Coinbase evolved into an exchange.
Coinbase quickly outgrew its humble beginnings in a small apartment in San Francisco (the company's first office). By 2017, when another co-founder departed, Armstrong had become the company's undisputed leader.
Former colleagues had previously told The Wall Street Journal that Armstrong is introverted, sometimes struggling to communicate with employees and not very adept at giving direct feedback to subordinates in person. Some former employees felt his approach was somewhat akin to the calm and restrained "Vulcans" known from Star Trek.
2014 saw Brian Armstrong, CEO of Coinbase.
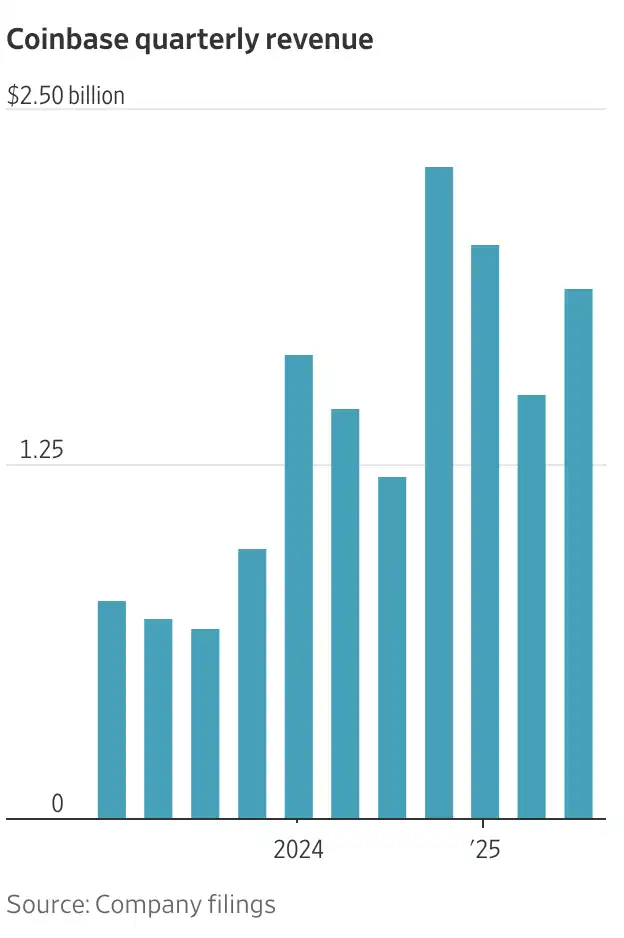
However, Armstrong's ambitions for Coinbase were never hidden. He positioned Coinbase as the American company leading cryptocurrency into the mainstream. Today, Coinbase's business landscape covers multiple areas, from online payments and stock trading to commodities and prediction markets.
“Fundamentally, we want to be an alternative to the banks,” he said last year on Fox Business. “We want to build a super app that offers all kinds of financial services.”
With business expansion, Armstrong invested tens of millions of dollars to build the largest lobbying machine in the industry. After experiencing the boom and bust of several cryptocurrency market cycles, Coinbase went public in April 2021, reaching a market capitalization of $100 billion at one point. Armstrong's personal stake briefly rose to around $13 billion.
Surviving the industry collapse in 2022 and the regulatory crackdown during the Biden administration in 2023, Armstrong began a strong counterattack and gradually found his own voice. The founder who once preferred wearing headphones, coding in the office, and was somewhat reluctant to make public statements, has now become the most active advocate for the cryptocurrency industry in Washington. Meanwhile, the U.S. political attitude towards cryptocurrency is undergoing a drastic shift.
Through a network of Super PACs, Coinbase has invested around $75 million in the 2024 election cycle to counter candidates with a skeptical view and build grassroots organizations to garner public support for crypto-related bills. The Super PAC group announced on Wednesday that it currently holds $193 million in funds.
Trump's victory in 2024 opened a policy window that Armstrong had been chasing for a decade. He praised Trump for ushering in the “dawn of the crypto new era” and attended a “Crypto Ball” with a performance by Snoop Dogg before and after Trump's inauguration. Now, this executive changes into a suit at least every two months, leaves his iconic t-shirt and black jacket behind, and heads to Capitol Hill to meet with politicians.
“In all matters related to cryptocurrency in the U.S., Coinbase is at the forefront,” said Anthony Scaramucci, founder of SkyBridge Capital and a long-time crypto investor.
Last summer, Trump signed the Genius Act into law, clearing the way for multiple companies to issue stablecoins. This law has propelled rapid growth in stablecoin activity. The act prohibits issuers from directly paying interest to users but does not cover exchanges or third parties like Coinbase. This "omission" has been seen by banking industry groups as a regulatory loophole and is a key point of contention surrounding the Clarity Act conflict.
The Long Road to Legislation
The House had already passed its version of the Clarity Act last year, but progress in the Senate has been widely seen as more challenging, partly due to significant disagreements on what rules crypto companies should follow. The Senate Agriculture Committee, responsible for provisions related to regulatory oversight and the Commodity Futures Trading Commission, advanced its own version on Thursday. Legislators will still need to have a full Senate vote to pass a single text and coordinate with the House version.
According to sources familiar with the matter, Brian Moynihan's core point to Armstrong is: if Coinbase and other crypto companies want to provide deposit-like services, then many banks believe they should be subject to the same regulatory burden as banks. Regulatory bodies, including the Federal Reserve and the Office of the Comptroller of the Currency, review banks' risk profiles, conduct regular operational checks, and impose strict capital requirements for lending and investment.
"The controversy surrounding the 'reward mechanism' is actually an exception in our overall relationship with banks," said Coinbase's Chief Policy Officer Faryar Shirzad. "We have a close partnership with banks and have already announced multiple partnerships."
Coinbase has formed a lucrative partnership with the stablecoin issuer Circle, allowing it to receive a significant revenue share from the mainstream stablecoin USDC. Through this unique arrangement, Coinbase is able to offer a 3.5% yield to some USDC holders, which is uncommon in the industry. The company stated that such incentives help attract users and offer consumers more options in an environment of very low savings interest rates.
"There's no reason not to pay consumers interest," Armstrong said in an interview with The Wall Street Journal last year.
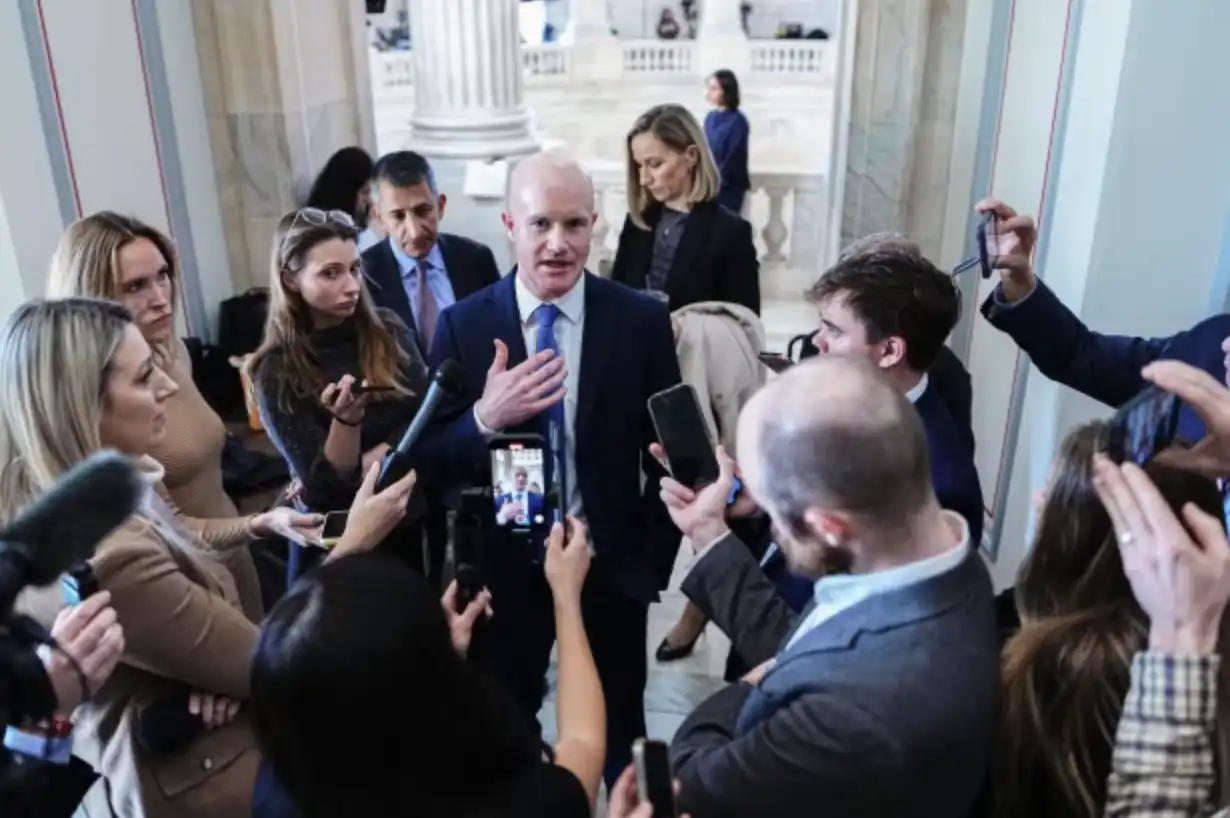
On January 15, 2026, Brian Armstrong appears on Capitol Hill.
As the Clarity Act gradually makes its way to Congress for a vote, banks have started behind-the-scenes intense lobbying efforts. Citing a government estimate, banks claim that approximately $66 trillion in deposits could be “siphoned off” from the traditional financial system if the relevant restrictions are lifted. This lobbying quickly proved effective: in this nearly 300-page draft bill, a series of provisions and potential amendments were included that Armstrong sees as equivalent to a failure for the crypto industry. He promptly withdrew his support, and Senate Banking Committee Chairman Tim Scott (Republican, South Carolina) also postponed the scheduled vote just hours later.
According to insiders, Armstrong has already envisioned how to break the deadlock. He reportedly suggested to Brian Moynihan that a new stablecoin issuer category could be established: as long as they meet stricter regulatory standards, they would be allowed to pay interest to users. This way, banks theoretically could also enter the competition under the same rules framework as Coinbase.
Other proposals advocate largely prohibiting interest payments but carving out small exceptions for institutions like Coinbase.
Regardless of the final proposal, legislative progress is almost inseparable from Armstrong's endorsement.
“The current situation is that everyone believes whether this legislation will pass ultimately depends on whether Coinbase gives the nod,” said Hilary Allen, a professor at the American University Law School, expert in securities law, and a crypto skeptic. “This is a truly astonishing reality.”
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia






