Data survey: the Coinbase Effect or the Coinbase curse?
Data Survey: The Curse of Coinbase
Fais Khan
0xBread, Deep Tide TechFlow
Marc Andreessen has been a little shy lately.
Is he worried about being exposed?
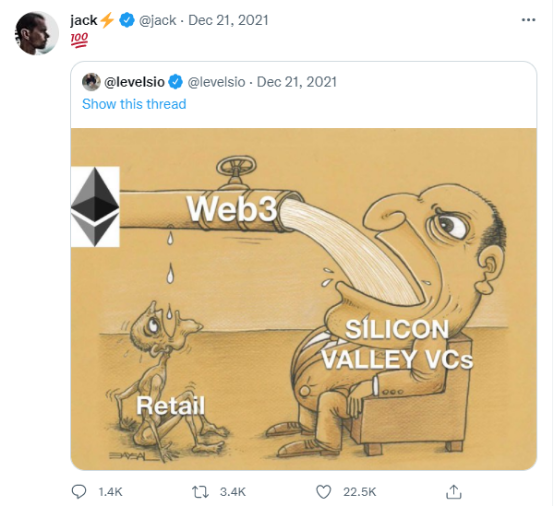
Jack Dorsey has been out in force to expose VCS profiting from copycat coins, despite their claims to be pushing for "decentralization." Which brings me to this: Marc Andreessen actually sits on Coinbase's board of directors. Meanwhile, Coinbase made its tokens available to the public. Isn't that a conflict of interest?
I started to wonder how these tokens would perform over the long term, especially compared to Bitcoin and Ethereum -- these benchmarks are hard to look at and calculate.
If tokens, especially VC-backed tokens, have consistently underperformed bitcoin/Ethereum since Coinbase went public, that suggests to me that insiders are waiting for a large, dollar-based exchange to go public so they can sell -- venture capital gains at the expense of retail investors. Those insiders include venture capital firms like A16Z and, incredibly, Coinbase's own venture capital arm, which has some investments in Coinbase. Other exchanges, such as Kraken, FTX and Gemini, are also active in venture capital and have their own investment lists.
Why is this important, and not just nerd economics? For one thing, Coinbase is like the New York Stock Exchange for cryptocurrencies -- listing there is a huge deal that typically generates huge profits for everyone involved. But unlike the New York Stock Exchange or Nasdaq, Coinbase can use its own process to select any assets they want.
Second, a16Z and Coinbase's own returns are particularly interesting, given that A16Z is considered the best investor in the sector and has potential conflicts of interest. Is the game rigged?
Third, Coinbase shifted its strategy last year from caution to as much ground currency as possible. This provides more trading pairs for them and their users.
So I started digging into it, and what I found surprised me: Most tokens underperformed, returns got worse over time, and vC-backed tokens fared the worst.
But another thing I found -- over the past few years, Coinbase has published the names of tokens they're considering for listing, and I've analyzed those tokens -- and found that they performed even better than those already listed, while vC-backed tokens didn't perform as well.
Let's dig deeper.
Coinbase Effect or Coinbase curse?
For years, trading on Coinbase has been the holy grail of cryptocurrencies -- the Wall Street equivalent of an IPO. Like ipos, this seems to generate "traffic" -- crypto research firm Messari notes in a report that, on average, Coinbase's ipo results in a 91 percent gain within five days.
But I think there are two flaws in this analysis:
1. This is a very short time frame. If you believe, as I do, that most token returns come from illiquidity rather than fundamental value, then the sudden influx of buyers after the ipo will create a buzz that eventually turns negative as insider lock-in ends.
What does illiquidity mean? Basically, many people have a large supply fixed or "locked in" in Defi agreements and have an incentive not to sell. Project developers and investors will hold large amounts of tokens, but over time the supply will be freed up.
2. Showing returns on an absolute basis is meaningless. If you're a hedge fund, you have to beat the benchmark. The benchmark for any cryptocurrency should be Bitcoin (BTC) and/or Ethereum (ETH). In my opinion, Ethereum makes sense because most of these "Web3" tokens are built on ethereum's vision, not Bitcoin's.
For example, the Coindesk article above cites Filecoin's "six times" return. But investors who chose to buy Filecoin over Bitcoin when Coinbase went public on December 10 actually underperformed relatively, falling rapidly in the first month (yellow line).
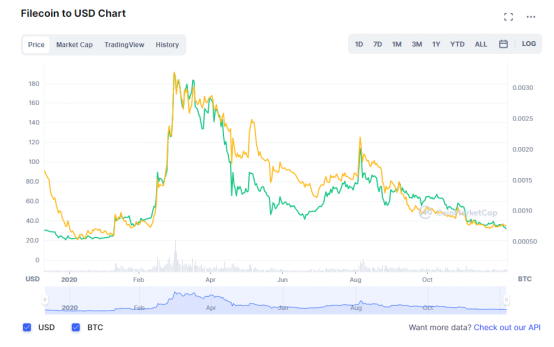
Note: The yellow line is the performance against bitcoin, and the green line is the DOLLAR.
Most of the return they mentioned was bitcoin's rally, and Filecoin actually underperformed bitcoin badly over that period -- 55%!
I'm not alone in this. Most people with crypto trading experience will look at the price of BTC or ETH, not the price of US dollars to evaluate.
How is Coinbase trading? I took 128 lists (excluding stablecoins and pegs) from Coinbase and split the list by year.
Note: For the most part, I use Coinbase's official Coinbase Pro dates. Most coin transactions usually begin within 2 days and usually on the same day.
In my view, the results largely confirm my thesis. Coinbase and VC may trumpet US dollar returns to prove that cryptocurrencies allow retail investors (the "community")
Participate in the development of these networks. But the reality is that most of the returns came well after listing -- 2021 coins did well, but everything in 2020 and beyond underperformed!! What does that tell us? The 2021 returns were also lower than the 91% prevalence cited by Messari, suggesting that they all lost value after the boom.
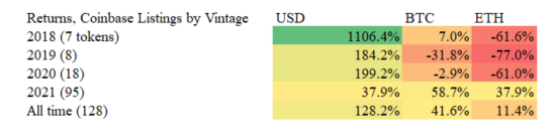
Once a token has been on Coinbase for a year, it seems to lag far behind Bitcoin and Ethereum.
I also looked for tokens that would earn a return in the year prior to listing (68 out of 128) to show that tokens haven't performed badly since inception:
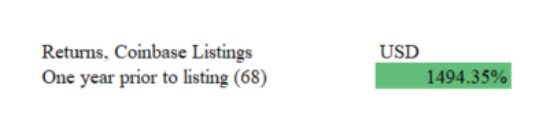
If we split the coins that went public last year, we still see the same pattern:
The most recent six-month coin (65) performed better than the previous six-month coin. If you withdraw just two tokens (Polygon and Solana) out of 63 tokens older than six months, Coinbase's returns also turn negative (-10.5% for Bitcoin and -55.0% for Ethereum).
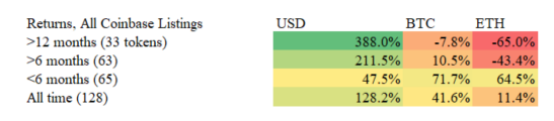
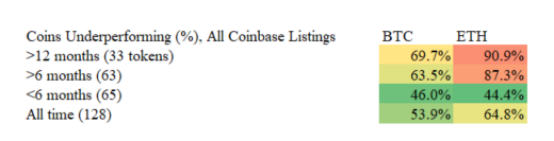
In terms of hit ratio, 91% of all the tokens listed were behind Ethereum when they went public over a year ago, and 70% were behind Bitcoin. These numbers also get worse the further back you go.
Thirst for liquidity
Surely, if we filtered the list of A16z on Coinbase, would we get better results? On the contrary...
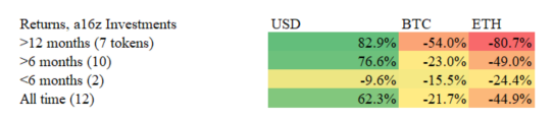
A16z's returns are much worse than Coinbase's overall list! That smacks of insider trading to me. These should be the best tokens considering a16Z's access, but instead, 100% of coins over 12 months old and 90% of coins over 6 months old lag behind Ethereum:
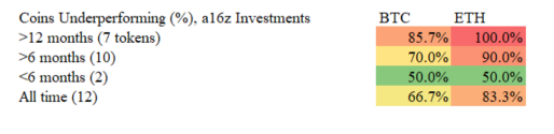
"It's a hot business," Marc Andreessen might retort. But: & have spent
1) Retail investors don't create complete portfolios like VCS do.
2) It's a public offering, so the return should be more like a stock with a positive average return
3) the "hit" in VC is supposed to be a "100x" return to compensate for dozens of failures, but in a16Z's list, only one (Solana) has at least doubled in BTC.
Back in 2018, when I used to trade digital currencies for fun, checking the market cap tables of big-name investors like Andreessen Horowitz was the best way to avoid getting caught in a "carpet pull" -- when coins suddenly crashed. I would say it worked well.
However, when I tried to deploy a similar strategy on Coinbase in 2021, I kept losing money. I think now I know why.
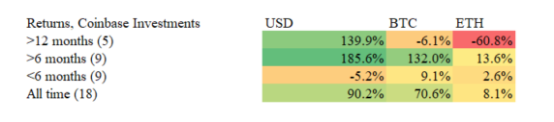
I also looked at Coinbase Ventures investments. They seem to be doing better -- though the old tokens are also doing poorly. Coinbase's portfolio is younger, and its outperformance has been driven entirely by two tokens: Polygon and Wrapped Luna. Without those two, Coinbase Ventures' portfolio of 15 other coins averaged returns of -6.0% BTC and -42.6% ETH.
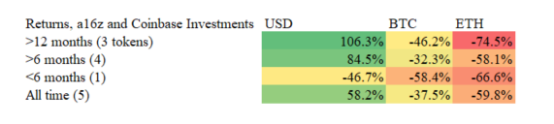
My favorite Angle is to see when Coinbase and A16Z invest together. This seems to be the darling of the industry (DeFi's darling?). "Was actually the worst performer of all the groups! (In case you're curious, Uniswap, Celo, Keep Network, Rally and Compound).
There are also good reasons to sell on Coinbase as a U.S. VC investor: (1) you don't want to be double taxed, which would cause (2) you're a U.S. entity and can't open an account with Binance or any other exchange that first lists these coins, and (3) it's safer to host and trade on Coinbase, since on other exchanges you may have to use hardware wallets, sort out cross-exchange transactions, etc.
I also looked at why Coinbase's investment is likely to outperform the market. One thing I noticed is that Coinbase lists its investments but at a smaller market cap (see below). For seven of the 18 Coinbase-backed tokens, I checked Coinbase or Binance (an exchange that tends to be more aggressive in terms of regulation), and in five out of seven cases, Coinbase ranked first -- better than average. One wonders if Coinbase knew Binance's ipo would hurt their bottom line by siphoning off returns!
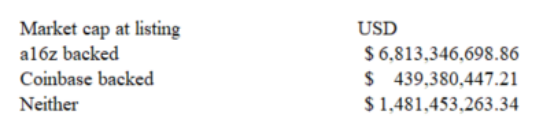
(If you're wondering if the A16Z's low returns can be explained by a larger listed market cap, the answer is no - they seem larger simply because Internet Computer debuted at around $52B, otherwise they're pretty much in line with everyone else.)
Pudding to prove
These numbers alone do not prove anything about Coinbase or A16Z, a spokesman for them said. Newer cryptocurrencies perform better because of better technology! And those returns have faded for all exchanges, not just Coinbase. Now, shut up before we charge you.
But fortunately, we have what economics calls a "natural experiment." Until 2020, Coinbase will announce that they are considering listing a set of tokens. Some get green lights (included in my analysis above) and some don't.
How are those unlisted tokens doing? Many of them are exploding. On a USD/BTC basis, unlisted currencies have been significantly outperforming listed corporate currencies, but slightly underperforming ETH (in line with my position that ETH is the best benchmark).
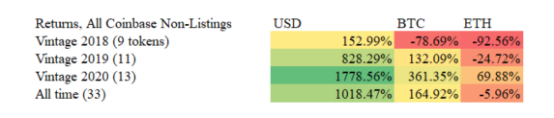
Importantly, as coins age, returns get worse -- even worse than Coinbase's coins. I think this is for a couple of reasons :(1) Coinbase's selection criteria may exclude the worst of the junk coins (2) it's been off the market longer, which means it's been degraded longer.
If we just look at 2020, and we have a fairly even comparison (17 Coinbases listed versus 13 unlisted), the difference in returns is almost astronomical. This is not a winner's product - 4 non-listed are positive for ETH and only 1 out of 17 actual listed are!
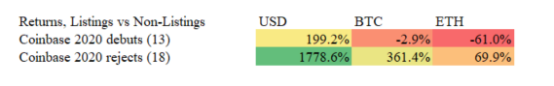
This negative effect seems so strong that in 2019 and 2020, your odds of beating BTC or ETH significantly improve if you choose Coinbase's unlisted content -- 2020, Five times higher than ETH (94% of Coinbase 2020 coins underperformed compared to 69% of Coinbase's rejections). This strongly suggests that the availability of US dollar liquidity seems to exceed Coinbase's 'halo effect'... Or people are selling.
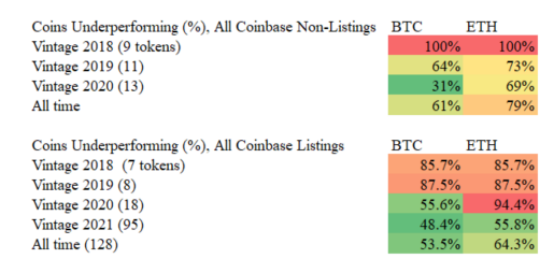
My conclusion:So much for the "Coinbase effect" : Getting people to sell coins in dollars seems to do more harm than good. If anything, there seems to be a Coinbase curse.
This feels like good support for two of my arguments :(1) most tokens appreciate due to illiquidity, not value (since both listed and unlisted degrade over time) and (2) liquidity on Coinbase caused these tokens to underperform, possibly in part due to insider trading.
Insider trading? You don't say anything about this section....
lock
We've looked at a16Z tokens and found that they underperformed the average listings of BTC, ETH, and Coinbase.
What about unlisted tokens? The sample of four coins was much smaller, but the results were stark:
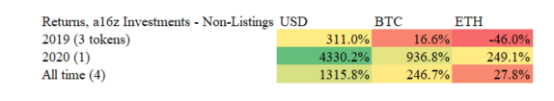
The unlisted A16Z token actually outperformed bitcoin, and the listed token didn't even come close. Arweave has investment from A16Z and Coinbase Ventures, but has never gone public -- and has had its strongest performance to date, a full 10 times since Coinbase said it was "evaluating" whether to go public!
Starting with "DeFi Summer" in 2020, we can basically tell our story for three coins: & NBSP;
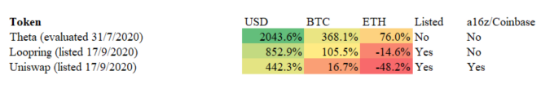
These coins have all gone through the same "macro" environment. Coins that never appear on the market are the best; Listed non-VC coins are better; Listed, VC-backed tokens are the worst.
What does that mean?
My first thought when I saw this was that I wouldn't buy anything listed on Coinbase myself, especially after the initial coin craze passed and stopped trusting VC-backed tokens. As it turns out, I haven't lost all my trading skills...
The logical corollary is to buy only BTC and ETH, even though those returns have also declined year after year (including last year), even though the risk is still much lower than these smaller coins. Overall, they seem better than buying "Web3" tokens.
I think it also has important implications for some of the biggest debates in the crypto space:
1) Contrary to the "Balaji" argument. Balaji likes to reiterate that the main value proposition of "web3" is to help the "little guy" : get users involved in value creation (for example, having some ownership in the project). However, the vast majority of users buy on Coinbase and thus underperform bitcoin.
2) Support the "Jack" argument. Jack's argument is that most tokens are owned by VC's and that they are destroying Bitcoin by using the "Web3" narrative to siphon off liquidity generated by demand for deflationary assets. Jack is kind of like a Bitcoin Titan, so it's self-serving, but so far, it looks like he might be doing something.
Other thoughts: Coinbase could drop its brand here, too. They may need new assets to encourage trading, but others think the shift away from caution may have been Balaji's influence -- which makes sense, given his thesis on "helping" investors, but he may have misread the data. Plus, Balaji used to work for A16Z and Coinbase -- so no one can really say what motivated him!
And finally -- do I think there's something improper going on at both companies? I actually don't think so - they may not even have looked at the numbers themselves. They may just be the most transparent, as data from other investors and exchanges is hard to come by. But they are also by far the most influential. As Uncle Ben said, with great power...
Instead, I think it's a microcosm of how bad cryptocurrency incentives are -- VCS and private investors who used to have to wait a decade for liquidity can now get it in a year. The last time it happened was in 1999, and we know how that ended. It was a recipe for adventure, and then quickly communicated to the public.
Some objections to my analysis:
1) You are a nobody. No, I'm long BTC, ETH and NEAR, and the March 22 $26 BITO hedged some recent volatility.
2) You're a big Bitcoin investor. No, I worked for Joe Lubin and ConsenSys for three years.
3) You didn't look at other exchanges. Given that Coinbase is by far the most "popular" exchange listing, I suspect the liquidity slump will also be the strongest. I also think the A16Z-Coinbase Nexus is the best study because A16z and Coinbase are juxtaposed and have the greatest influence. I also suspect A16Z has an account in Kraken or Gemini because they have a vested interest in Coinbase, so I wouldn't imagine a relationship there. I'm interested inan analysis of Binance, so this could be the analysis of the future.
4) These are not bad returns. Last year (basically 2021) was a good year for the listing currency, and the DOLLAR was positive. That's fine, but I would say if these coins are only going up because Bitcoin is going up, what happens when bitcoin has a bad year? What's the point of Coinbase if you just lose out to Bitcoin?
5) You did it during the bear market, so it looks worse. No - I ran the raw numbers in December (BTC around $50,000) before I wrote this article, and all the same trends held.
I suggest a solution(Hello, Gary Gensler)
The first question I have to ask is should this be legal? Both NASDAQ and NYSE have venture funds, but their investments must be approved by the SEC before they can be publicly listed! No regulator checks every Coinbase listing. Sure, maybe they had processes and acted in good faith, but would you trust the financial statements of any old company if no one audited them?
Think of it this way: It's like Google invested in Goldman Sachs (in this case, Messari), and then Goldman published research on Google's work, and then Google did an IPO in which it invested. No one has to reveal what they are buying or selling. Will you get any good message out of this bad incentive?
Here are some of the solutions I believe are necessary to better protect investors and correct some of these bad incentives:
1. Fund disclosure. Hedge funds and mutual funds are regulated by 13F and 13D: for 13F, they must disclose their holdings quarterly, and for 13D, as long as they acquire more than 5% of a listed company's shares. My view is that VCS and other crypto investors should do the same for crypto. Want to sell to the masses? Follow open market rules. Otherwise, it's not fair to the moms and dads who clicked on Coinbase's billionth YouTube AD.
One could argue that 13F and 13D don't do much and may not help small investors who don't read the documents. But I said it would allow professional investors to evaluate the tokens of those investors who received quick liquidation, which would allow reputation to be won/lost.
2. Fix recognised investor rules -- but not just deregulation. Populists will say "Get rid of the approved investor rules! It prevents people from participating in economic growth!" I say absolutely. But did you know that public companies (you know, "unlicensed" investments) are also subject to regulatory and disclosure rules? These advocates want VC deregulation (necessary) in the absence of public market rules (necessary). That means s-1 style public documents. S-1 typically discloses the relationship between investors and directors, the risks and, importantly, the ownership of management and major investors.
I believe the Balaji and Ryan Selkis of the world would say this idea would "kill" innovation: Contrary to popular belief, I don't believe companies will stay private longer because of onerous rules (although they are onerous), but public markets have become more tolerant of losses, which means you can go public with bigger and bigger losses. If you can avoid dilution and get a bigger exit, as a founder or investor, why wouldn't you?
3. Close utility and governance coin loopholes. The SEC accidentally created a huge loophole when it said Ethereum wasn't a security because ethereum coins were functional.
Let's say you're a deli and you decide to sell sandwich coupons online (utility!). . If people on the Internet seem willing to pay for them, why don't you issue a billion sandwich coupons? Sure, your little deli won't sell a billion sandwiches in the next 10,000 years, but that's not your problem.
Most DeFi coins use a "governance token" model, where one token is one vote. This falls under the very similar "How many votes?" Gray area.
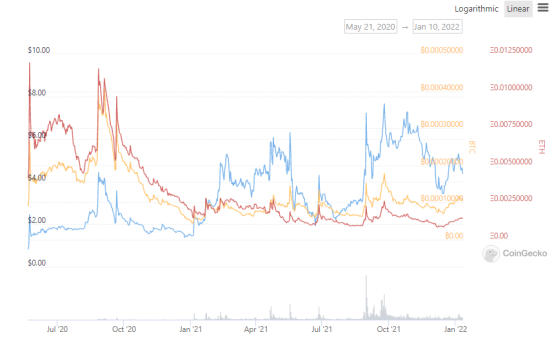
Let's take Celo as an example: "Between 2018 and 2020, Celo raised over $46.5 million by selling approximately 120 million Celo tokens." Since then, it has stated that the total supply of tokens will never exceed 1 billion, of which only 6 percent (60 million) were in circulation at launch. Since then, it went public on Coinbase (Coinbase and A16Z Investments) on September 3, with approximately 12% of the tokens in circulation, and in the 15 months since then, that percentage has increased to 37% today!
The value of this coin is that it can "vote to create stablecoins", so of course we need a billion of them.
If utility/governance tokens remain an open loophole, issuers need to provide a fair estimate of how many tokens users actually need in disclosure -- so investors can hold them accountable.
Take a look at how performance has flattened out since April 2021 when release schedules significantly accelerated (1.2% per month) :
4. Stricter (non-) listing rules. Coinbase currently has no rules for minimum market capitalization, minimum number of shareholders, or minimum daily trading volume. That means Shitcoins can go down, down, down. The New York Stock Exchange and NASDAQ have many of these rules, which is why they are so well known around the world. These also include rules governing how much inventory the team can control. If cryptocurrency exchanges have to repeatedly remove their tokens due to lack of liquidity or falling prices, it will damage their reputation -- incentivizing them to demand high quality.
conclusion
In Urdu, we call dog legs chamcha, "spoon" - because they can meet your needs. At the end of the day, I'm someone on the Substack -- but sadly, I think the state of crypto investing today is that all the "research" you get comes from someone's Chamcha.
I don't know whether balaji or jack will in ten years later proved to be correct, but all this support what I call "Charlie" lee (Wright coin) founder of the argument: the demand for deflation assets, such as COINS can be large, but the biggest problem is that anyone can create a similar encryption currency, so it is not true deflation.
What will Coinbase's return on its 2021 coins look like next year? I would be willing to bet that the same pattern will continue, where the price of coins explodes and then fades away, with lower returns than bitcoin. At the very least, I hope Coinbase users will eventually see this -- just like you do with ETFs or mutual funds. It is only right that Coinbase is offering riskier and riskier assets over time.
At best, investors and exchanges are those who want to reshape finance but underestimate its complexity. As Matt Levine points out, many cryptocurrencies are simply repeating the mistakes of financial history. At worst, the rich team up with their friends to take advantage of the bubble and help them buy $100 million homes. It's time for these big companies and regulators to take action to make sure everyone can use the same standards and data. Until then, buyer beware.
Notes:
1. In eight cases, the unlisted tokens were not traded at all before Coinbase evaluated them. In that case, I used the oldest market data available on Coingecko. Interestingly, of the 8 that haven't traded anywhere yet and are being evaluated for a listing, 5 have received investment from A16Z or Coinbase!
2. I used A16Z and Coinbase Ventures' own investment list, but in one case (Livepeer) I found an outside source pointing out that Coinbase had made an investment but had no record of it on their website (they may have divested the position).
3. For Coinbase's backed vs. unbacked market cap comparison, I couldn't find the following listed market cap: Braintrust, Clover Finance, Jasmy, Kyber Network, Loom Network, Moss Carbon Credit, Voyager Token, Wrapped LUNA, Orchid - protocol.
Reference:
1. All my data analysis and source data can be viewed here
2.Coinbase offers all new listings on its blog
3.Coinbase lists its investments on its website
4.A16z's portfolio has two lists: Crypto and all.
5.Messari also has Coinbase and A16Z portfolios, but I cross-reference them for accuracy
6. All prices from Coingecko.com. Based on returns as of 9 January 2022.
The original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles