Coinbase Pressure Mounts as Interest-Bearing Stablecoins Enter Key Decision Week
Original Title: Coinbase raises pressure as crypto bill moves to Senate markup
Original Authors: Emily Mason, Olga Kharif and Lydia Beyoud, Bloomberg
Translation: Peggy, BlockBeats
Editor's Note: As U.S. crypto regulation gradually takes shape, the stablecoin "reward mechanism" has become a new point of contention. Coinbase has warned that if Congress restricts the platform from providing stablecoin rewards to users in the upcoming market structure bill under consideration, it may withdraw its support for the bill.
On the surface, this is a debate about a business incentive rule; in essence, it touches on the boundary of interests between the crypto platform and the traditional banking system. The banking industry is concerned that stablecoin rewards will draw deposits away, weakening the credit base; while platforms like Coinbase believe this mechanism is critical to stablecoin scale, the USD network effect, and industry competition fairness.
The following is the original article:
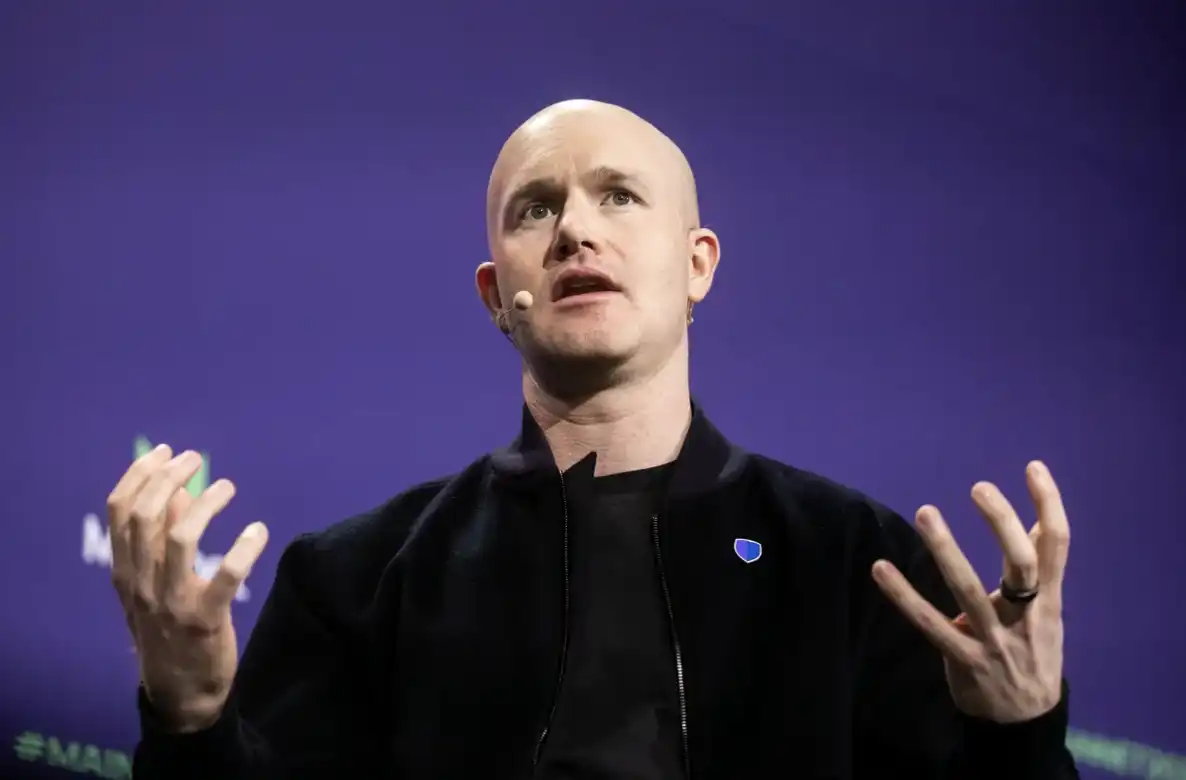
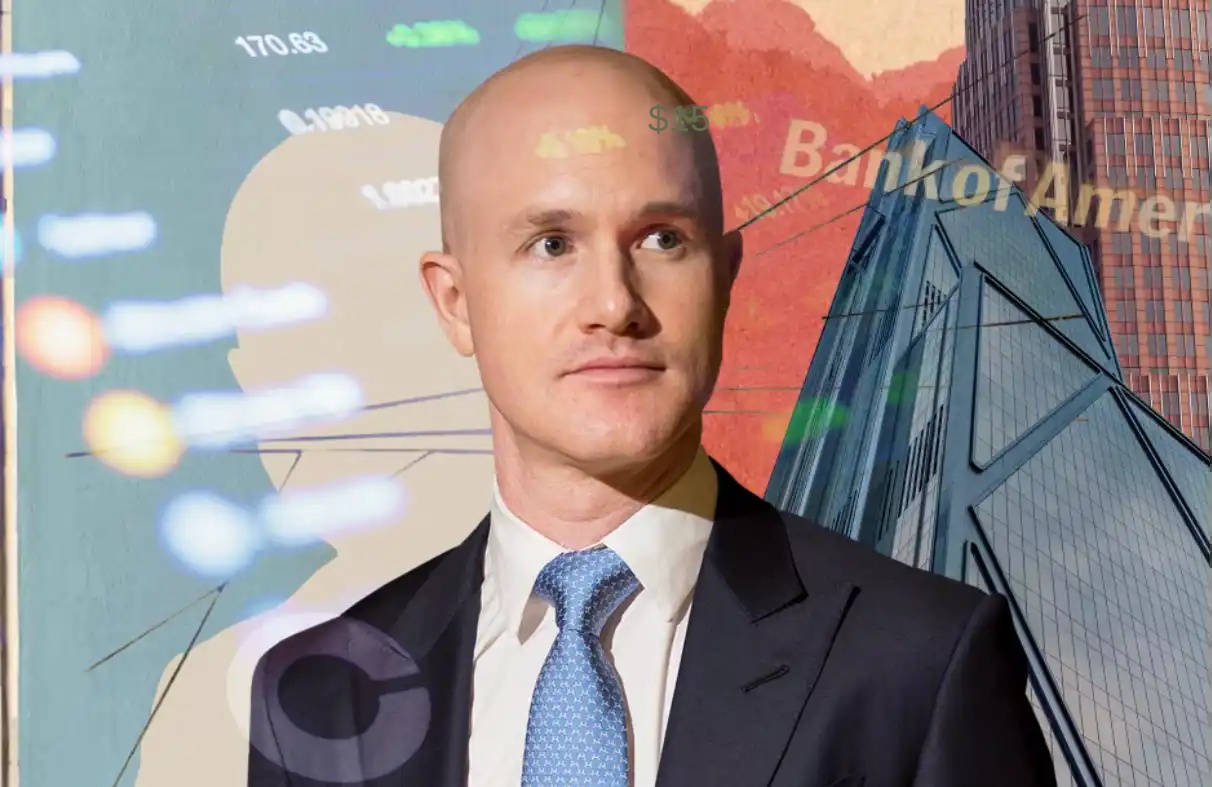
Coinbase's CEO Brian Armstrong
Coinbase Global Inc. is increasing pressure on U.S. lawmakers in an effort to preserve its ability to offer rewards to customers holding stablecoins. The company believes that if certain restrictions under discussion are included in a significant crypto bill expected to be unveiled on Monday, this business will be at risk.
According to a person familiar with the company's thinking, if the bill text includes anything beyond "enhanced disclosure related to rewards," the largest U.S. cryptocurrency exchange may reconsider its support for the digital asset market structure bill. The bill is expected to enter the markup stage in at least one Senate committee on Thursday.
Coinbase did not respond to a request for comment.
Industry sources say one scenario under consideration is to restrict eligibility for rewards to regulated financial institutions. This approach has garnered support from some in the banking industry who believe that interest-bearing stablecoin accounts could "draw" deposits away from the traditional banking system. Coinbase has applied for a nationwide trust charter, which if granted, could allow it to continue offering such rewards under those rules. However, crypto-native companies are pushing to retain the "platform-based rewards" model without a license and warn that broader restrictions could disrupt the industry's competitive landscape.
The threat of "Withdrawal of Support" is not to be taken lightly. The cryptocurrency industry was the highest corporate political spender during the 2023-2024 election cycle, funneling significant funds to favored candidates. Coinbase, led by co-founder and CEO Brian Armstrong, donated $1 million to Donald Trump's presidential inauguration and was also one of the companies funding the construction of a banquet hall for the White House.
For Coinbase, the reward issue is crucial. The exchange shares in part of the interest income generated by Circle Internet Group Inc.'s USDC stablecoin reserves. The USDC held on the Coinbase platform provides a stable source of income, especially vital during bear markets. Coinbase also holds a small amount of Circle's shares; Circle is currently the largest compliant stablecoin issuer under a U.S. law passed in July.
For example, Coinbase incentivizes users to hold USDC on the platform by offering a 3.5% reward for USDC in Coinbase One accounts. If legislation on market structure prohibits such incentive measures, the stablecoin holdings on the platform may decrease, affecting Coinbase's overall stablecoin revenue. According to Bloomberg data, this revenue is projected to reach $1.3 billion by 2025.
Of course, the devil is in the details, and the impact is not yet fully clear, depending on the specific wording of the legislation. However, insiders say it is certain that the bill will include relevant language regarding rewards.
《GENIUS Act》
Trump's second government quickly brought a "positive" development to the digital asset industry, including the first federal-level stablecoin issuance regulatory framework passed in July, known as the "GENIUS Act." After the signing of the bill, a series of announcements were made from retailers to traditional financial institutions, expressing their intention to enter the stablecoin space. Even before the bill became law, World Liberty Financial, co-founded by members of the Trump family, had already launched its proprietary stablecoin called USD1.
Despite government support to expedite the legislation, the "Stablecoin Reward" issue is undermining the bipartisan consensus of the market structure bill. Coinbase has warned of a possible withdrawal of support, indicating an escalating tension that could slow down the passage of the bill, possibly preventing legislation from being completed this year. Bloomberg Intelligence analyst Nathan Dean stated that if the deliberation stage lacks bipartisan support, the probability of passing related legislation in the first half of this year may drop below 70%.
The GENIUS Act prohibits stablecoin issuers from paying any form of interest or yield to users solely based on holding the token, but does not prohibit third-party distribution partners like Coinbase from offering rewards based on customer balances.
The banking industry strongly opposes exchanges paying stablecoin rewards, arguing that this would erode deposit scale in the banking system and impair community lending capacity.
The American Bankers Association stated in a recent letter, "If billions of dollars are drawn out of community bank lending, small businesses, farmers, students, and homebuyers in towns like ours will be impacted. Cryptocurrency exchanges and their related stablecoin companies are not designed to fill this lending gap and cannot offer FDIC-insured products, but they often gloss over this in their aggressive advertising."
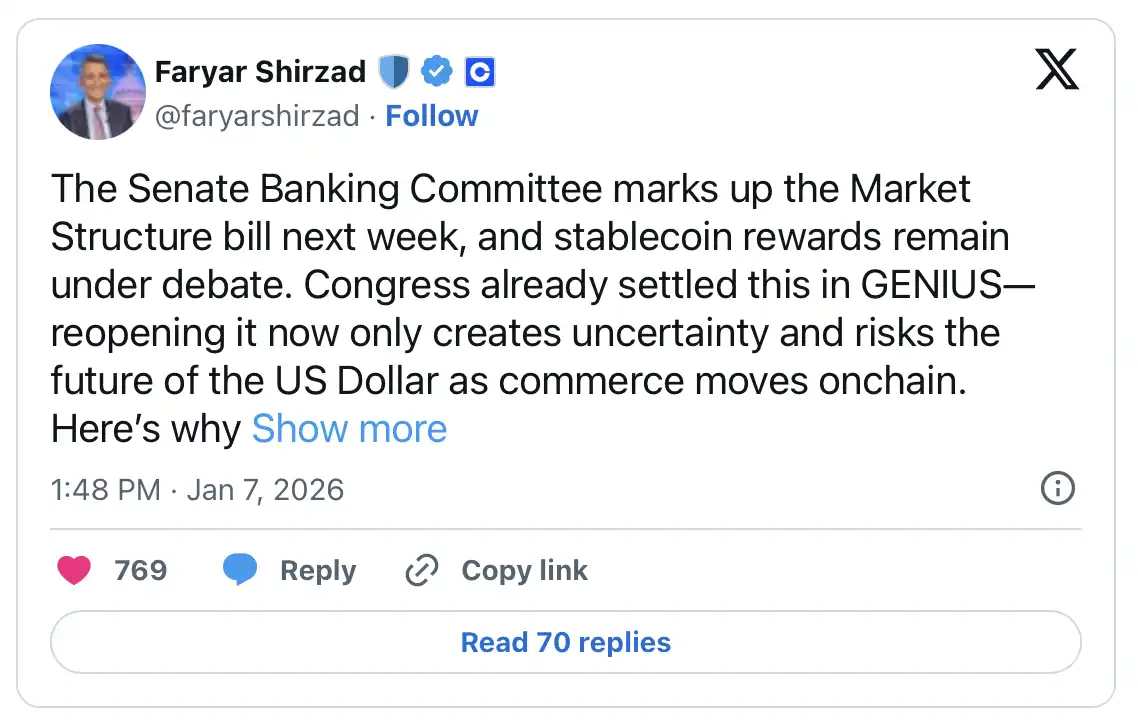
In contrast, the crypto industry portrays the banking industry's efforts as an attempt to undermine the consensus already reached in the GENIUS Act. Coinbase's Chief Policy Officer, Faryar Shirzad, recently posted on X platform, stating that maintaining a rewards mechanism tied to stablecoins is crucial to preserving the dollar's dominance position; he also pointed out that China has recently announced plans to pay interest on its central bank digital currency, the digital renminbi.
This tension has put senators in a dilemma. Insiders and observers suggest that on one hand, the government is pushing for more legislation; on the other hand, they have to make a nearly uncompromising decision on a contentious issue.
Sources say a possible middle ground is to only allow entities with a banking charter or financial institutions to offer rewards to users based on stablecoin balances. The Office of the Comptroller of the Currency (OCC) has recently granted conditional approval to five crypto companies to become nationally chartered trust banks. However, these approvals have faced strong opposition from banking lobbying groups, who believe that crypto companies are stretching the boundaries of the "limited-purpose trust charter" and may pose a threat to the stability of the U.S. financial system. Given the existing approval precedents, if the market structure bill allows chartered entities to offer yield, it may appease some players in the crypto industry.
However, some industry insiders believe that even if restrictions are imposed, it will only trigger a game of whack-a-mole—crypto companies will continually seek new ways to incentivize users.
Payment giant Stripe's Chief Technology Officer and Head of Business, William Gaybrick, stated in an interview last year, "There's no world in which we can't reward consumers inside an application. When you hold a stablecoin within an app, that app will always find some way to reward your behavior."
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
 Related Articles