One More Rate Cut Closer, Will the Market Kick Off a FOMO Rally Post September?

On August 22, Federal Reserve Chair Powell stated that the continuously "changing" economic risks provided the Fed with a more compelling reason to cut interest rates. This statement indicates that Powell has aligned himself with the "dovish" camp within the Federal Open Market Committee responsible for setting rates, and suggests he may signal support for a 25 basis point rate cut at the Fed's next meeting in September. While Powell acknowledged that the impact of the government's trade war on consumer prices is now "evident," he implied that this impact is unlikely to persist and may be a one-time shock that the central bank can overlook.
He stated, "Given that the labor market is not particularly tight and faces increasing downside risks, this outcome seems unlikely." He also added, "Inflation faces upside risks while employment faces downside risks, presenting a challenging situation." This also implies that the long-awaited rate cut may be imminent.
So, does a rate cut always lead to a market rally? From a historical perspective, the answer is that it likely does, but not every rate cut results in a rally.
In the market's intuition, "rate cuts" are almost synonymous with liquidity injection and a signal of asset price appreciation. However, looking back over the past thirty years, it becomes clear that the Fed's rate cuts are far from being as straightforward as they seem. Sometimes they are preventive measures to avert risks, and other times they are emergency relief in times of crisis.
Since 1990, the Fed has gone through five major rate-cutting cycles, each with different economic backgrounds and policy motivations, and the stock market's response has shown vastly different faces. To understand the relationship between rate cuts and the market, one must not simply view it as a "bull market button" but must analyze it in the context of the macro environment and investor sentiment at that time.
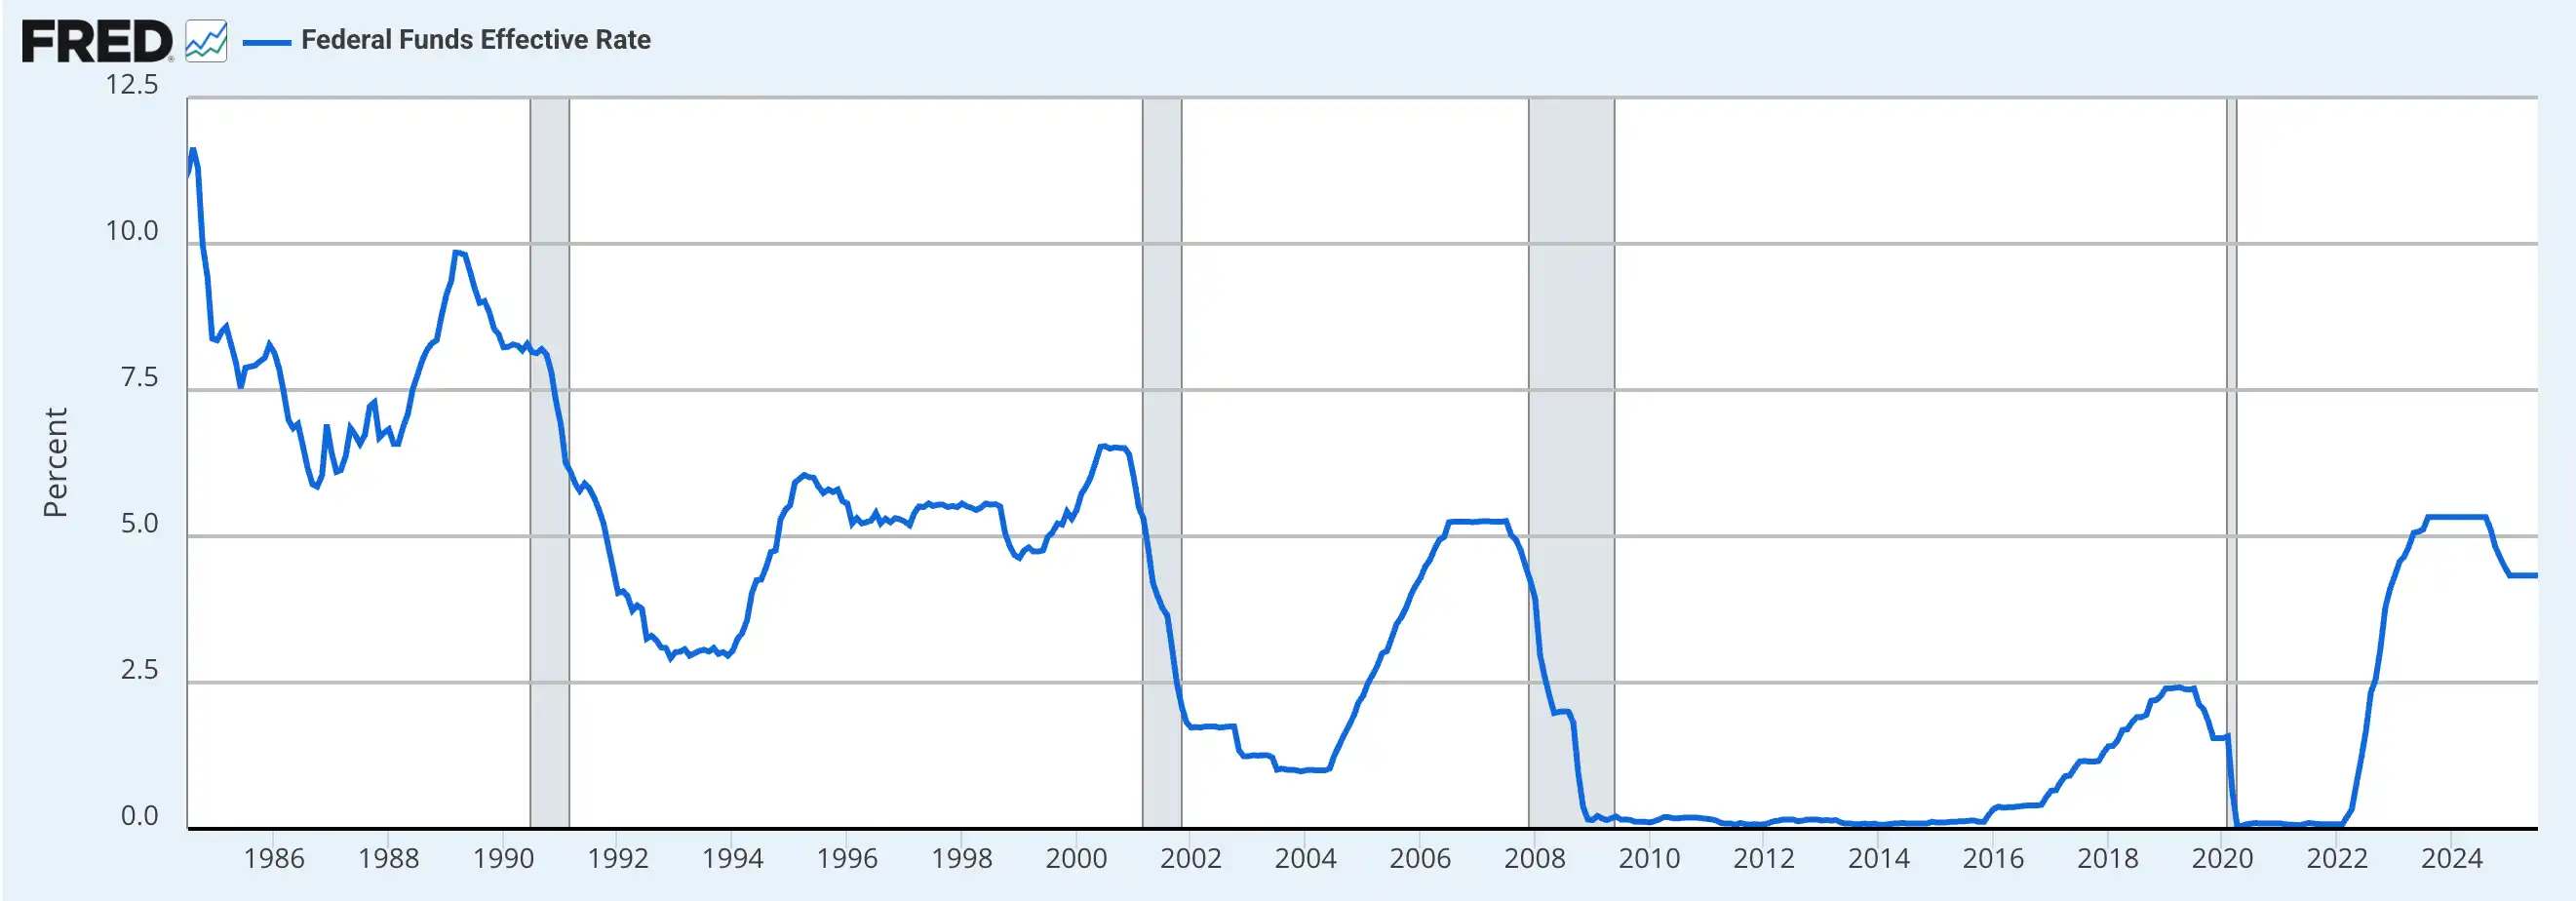
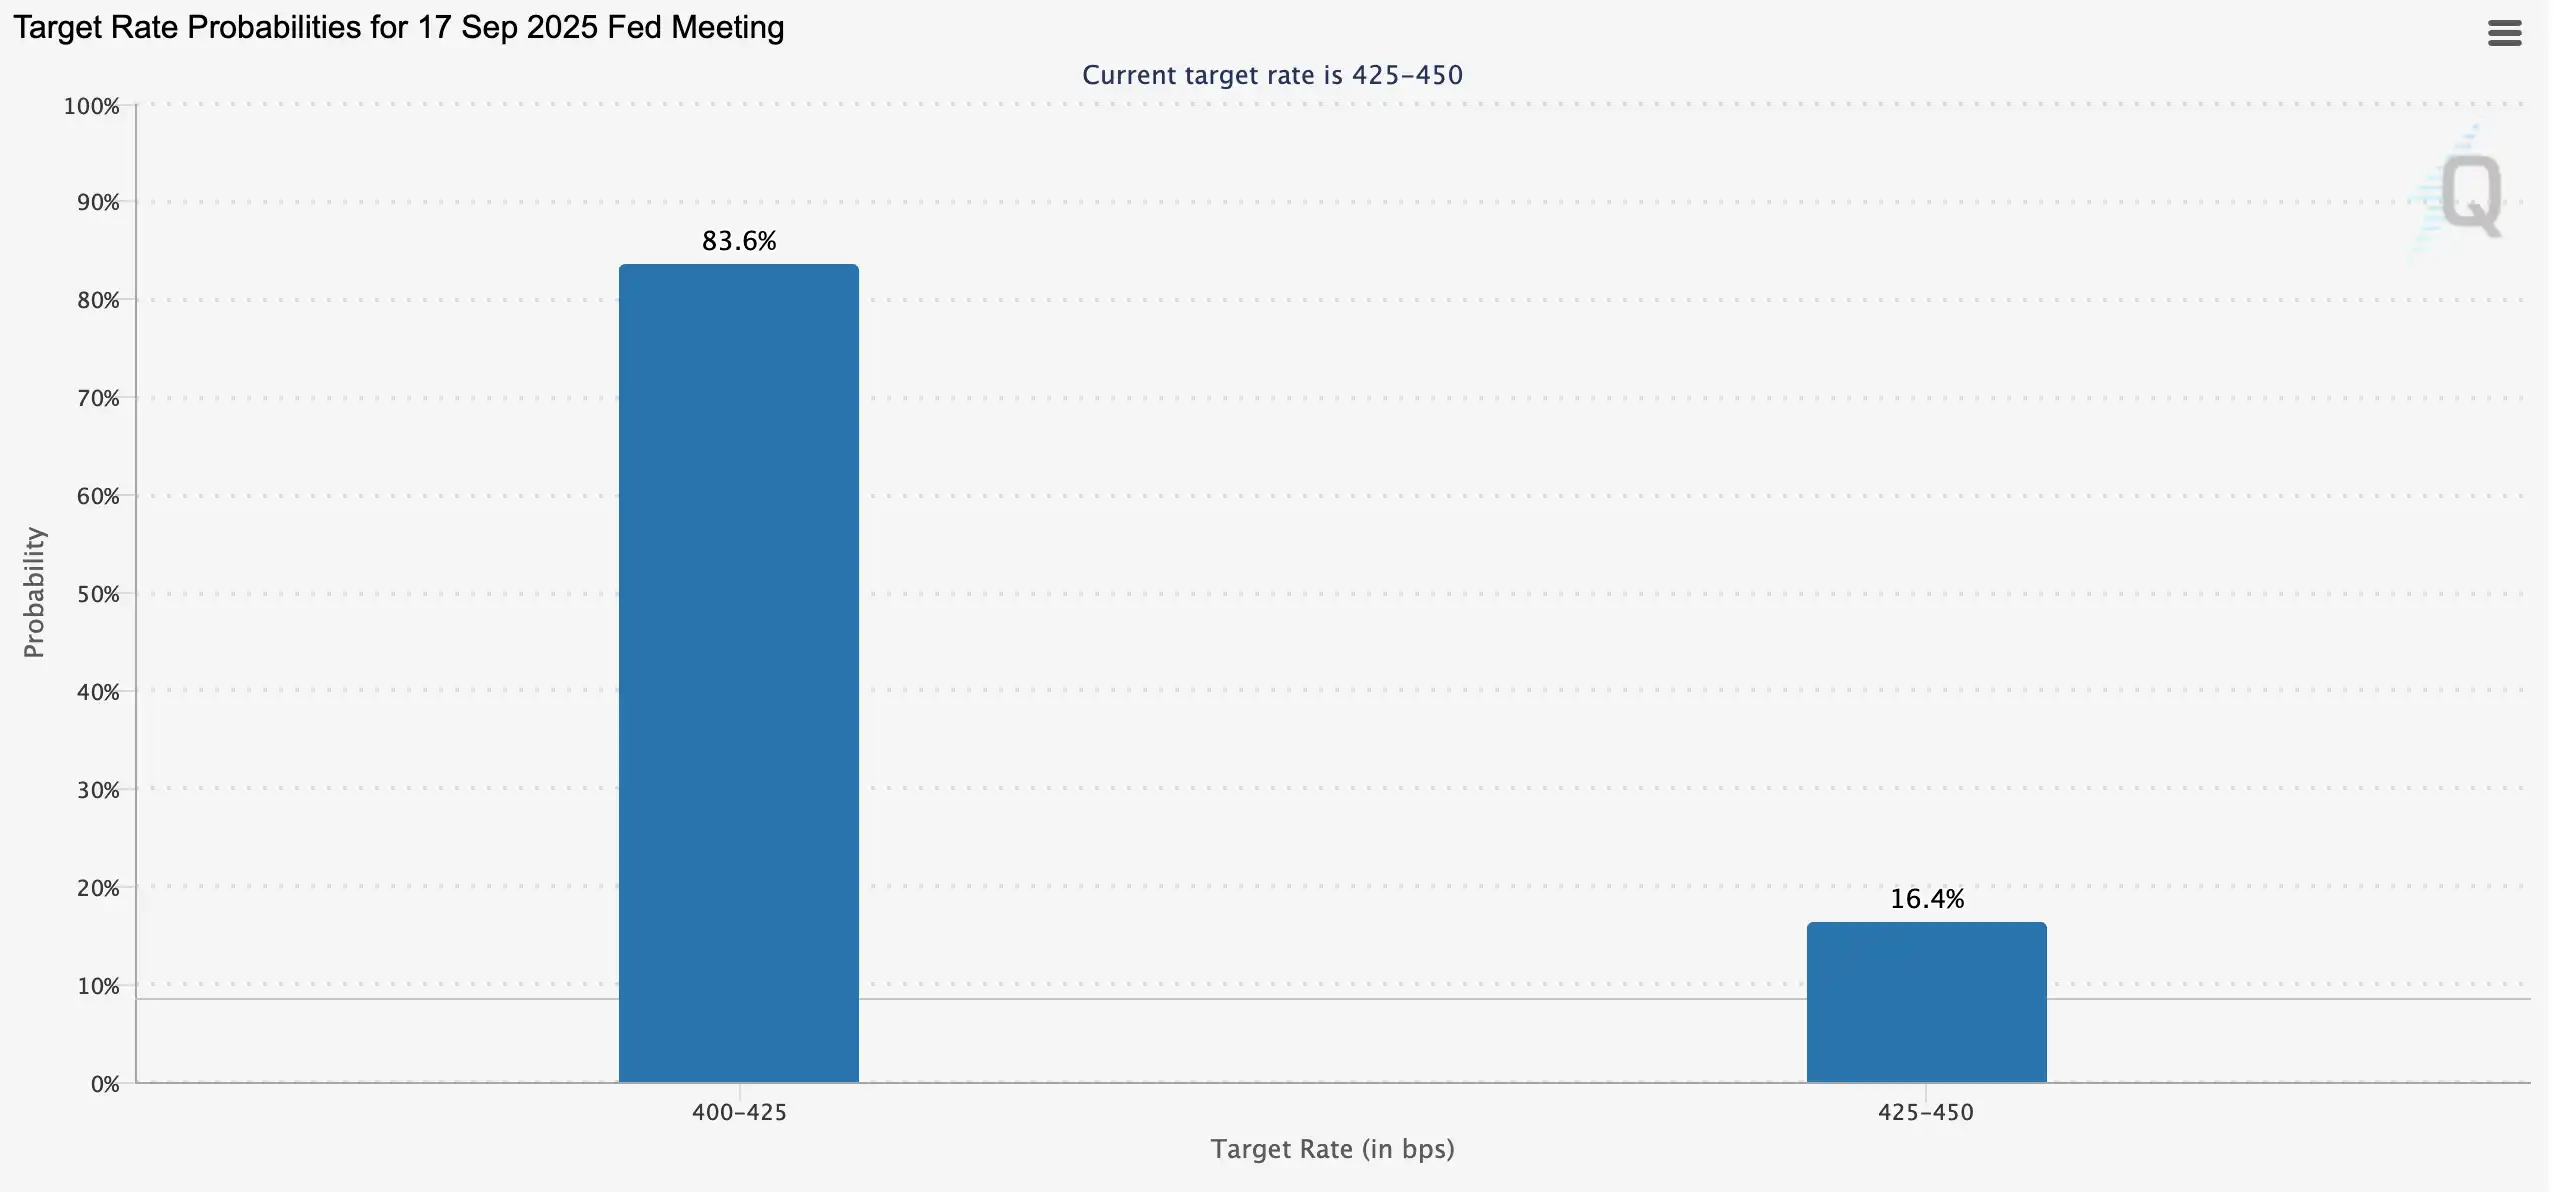
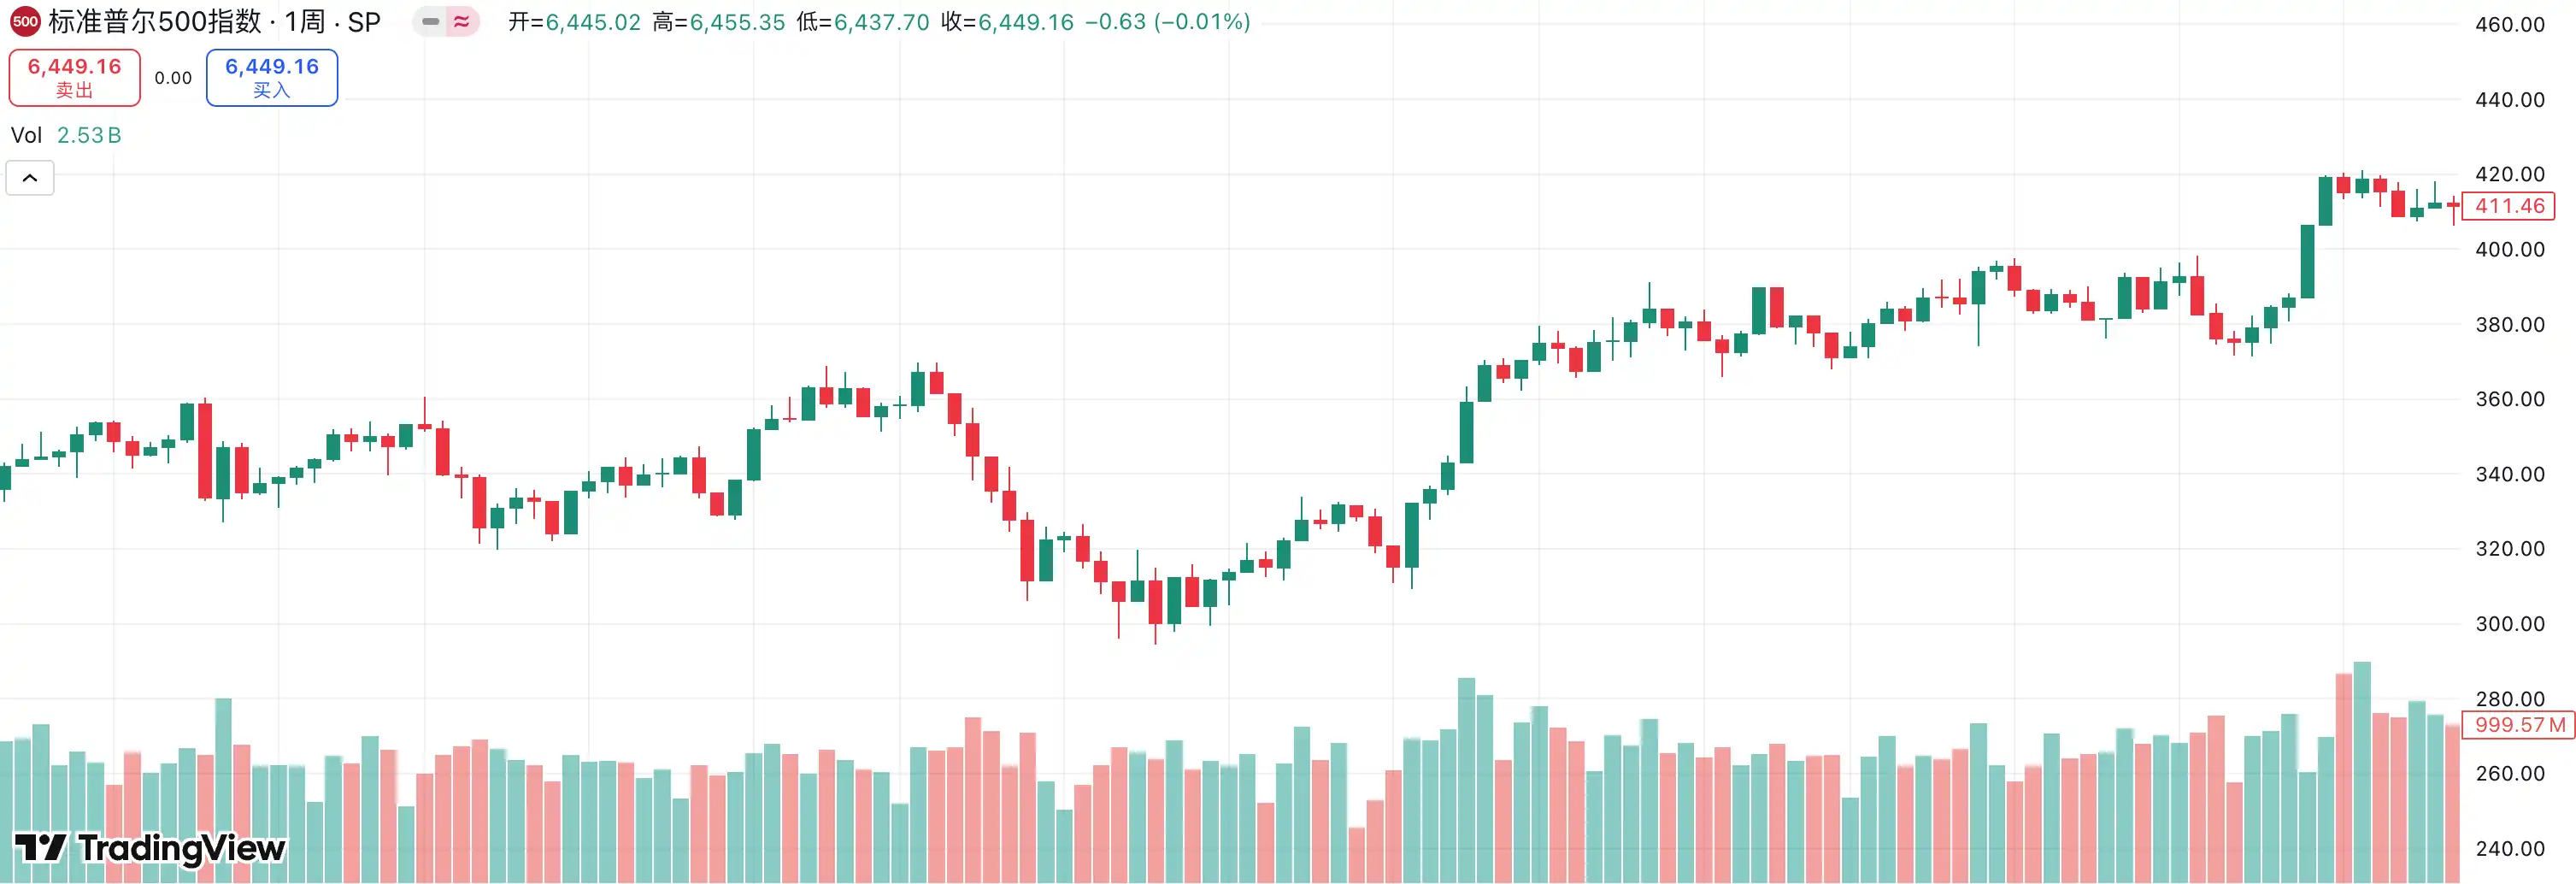
It has been a full year since the last rate cut, and now the market's attention is once again focused on the September interest rate meeting. According to FedWatch data, the probability of a 25 basis point rate cut by the Fed in September has reached 83.6%. Looking back over the past year, after the rate cut, not only did the S&P and Nasdaq refresh historical highs, but Bitcoin also saw a rally, once again sparking the market's anticipation of the "rate cut equals bull market" logic. However, is there truly an inevitable connection between rate cuts and market performance? This article will review the economic and stock market performance during each rate-cutting cycle by the Fed since 1990, providing a more rational basis for determining whether a bull market is imminent.
Rate Cuts and Bull Markets: Stock Market Performance During Rate-Cutting Cycles
1990-1992: Gulf War and the Soft Landing After the S&L Crisis
From 1990 to 1992, the U.S. economy faced the impact of the Savings and Loan (S&L) Crisis and the Gulf War, leading to a credit crunch, a sharp slowdown in consumption and investment, and a rapid economic recession. The Federal Reserve began lowering interest rates in July 1990 and continued until September 1992, with the federal funds rate dropping from 8% to 3%, initiating a round of strong easing.
Initially, the Federal Reserve only observed weakening economic momentum and financial market instability, choosing to gradually shift towards accommodative policy. However, Iraq's invasion of Kuwait in August, resulting in soaring oil prices and economic downturn, spread market panic, forcing the Fed to accelerate its rate cuts. By October, as the economy further weakened and the government reached a budget agreement to reduce the deficit, the Fed intervened again. By the end of 1990, while financial system stress intensified, inflation eased, creating space for a more significant easing.
This rate cut effectively alleviated the credit crunch and the negative impact of the geopolitical crisis. The U.S. CPI rose from 121.1 points in 1989 to 141.9 points in 1993, but the year-on-year growth rate dropped from 4.48% to 2.75%, controlling inflation; GDP growth rebounded from -0.11% in 1991 to 3.52% in 1993, putting the economy back on a growth trajectory.
The capital markets' response was more direct. From 1990 to 1992, the Federal Reserve's rate cuts significantly boosted investor confidence, with the Dow Jones Industrial Average rising by 17.5%, the S&P 500 increasing by 21.1%, and the tech-heavy Nasdaq soaring by 47.4%, becoming the strongest performer in the recovery period after the crisis.
1995-1998: Preventing Economic Recession and the Asian Financial Crisis
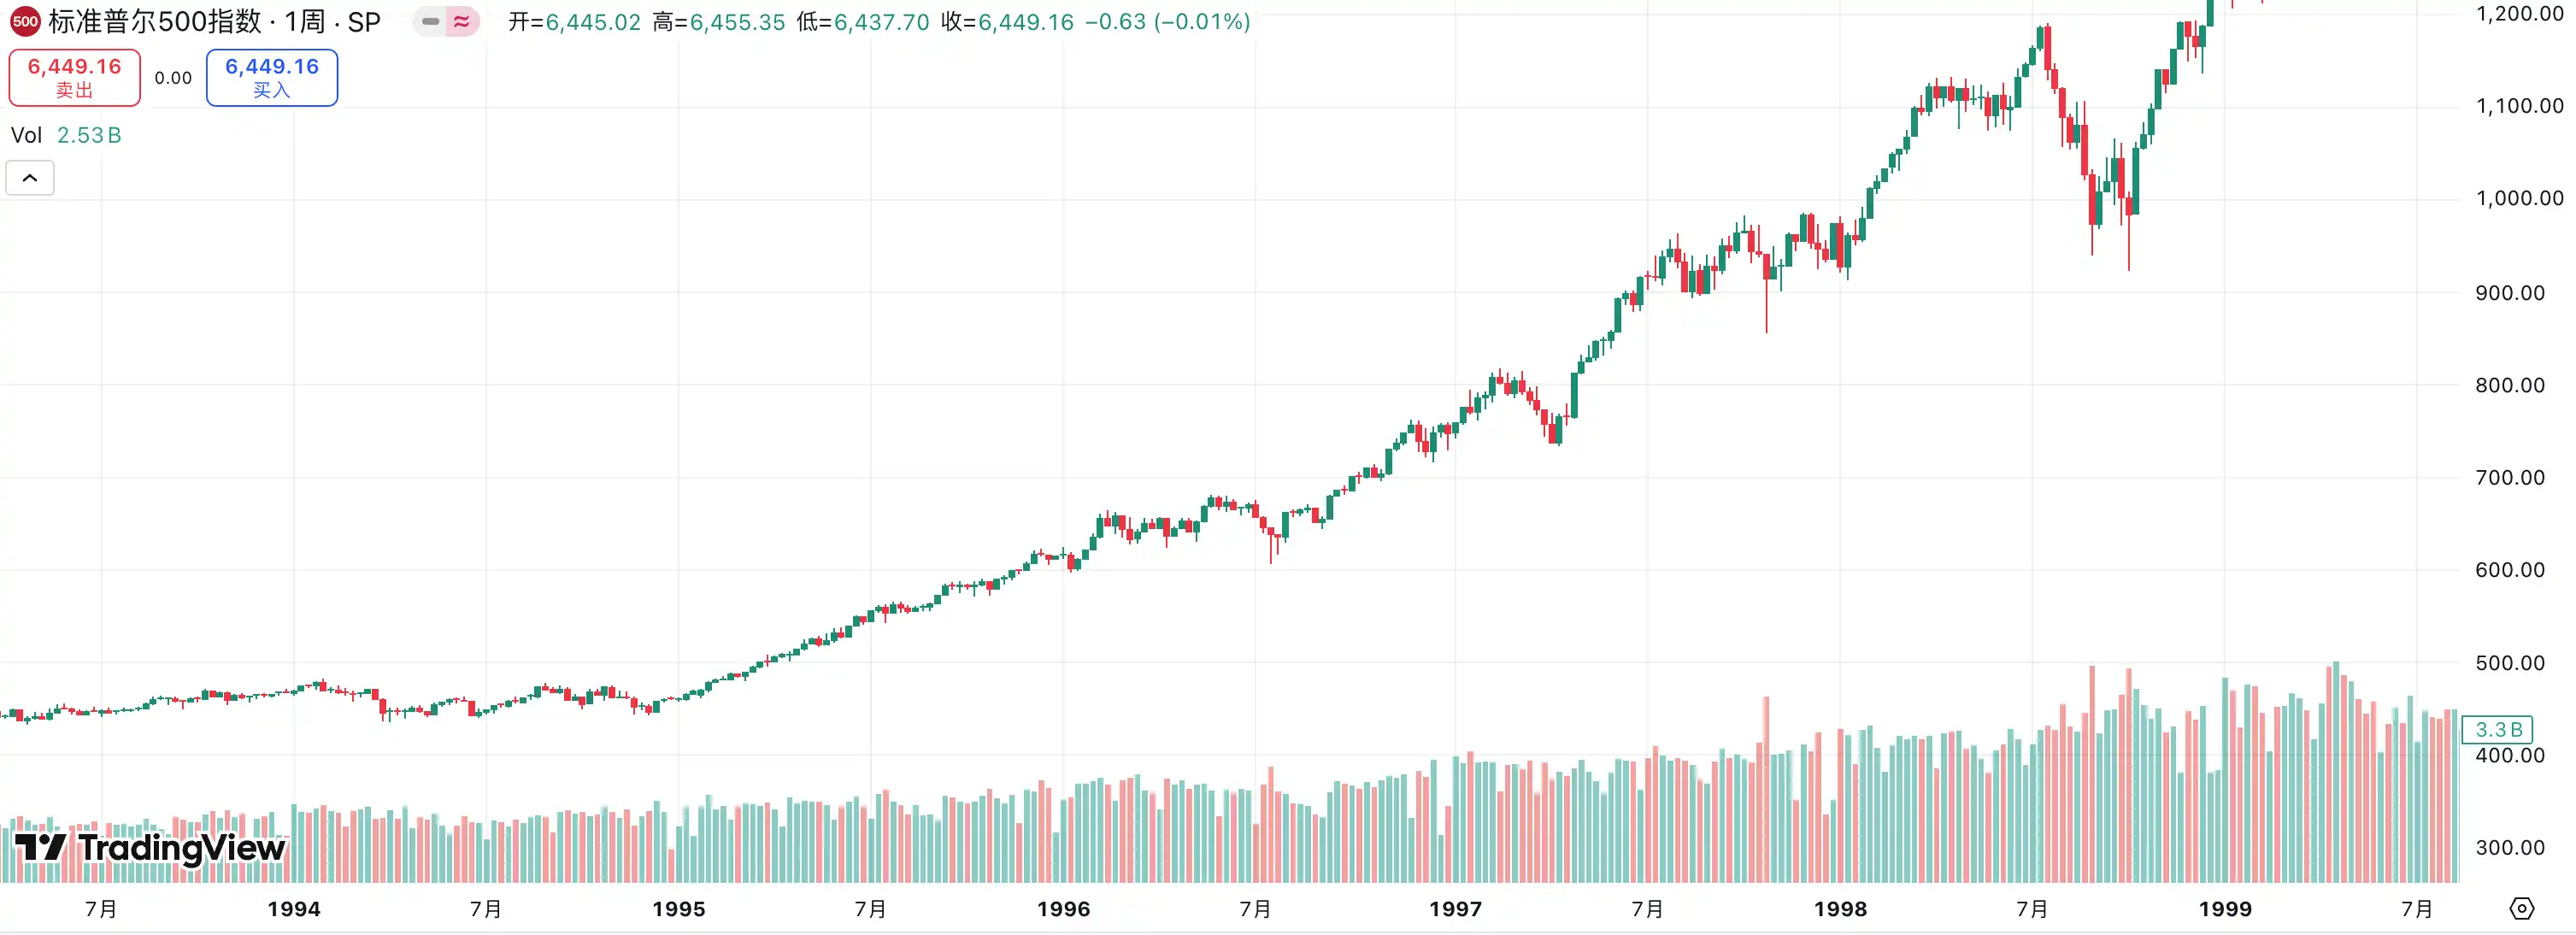
After experiencing a tightening cycle in 1994-1995 and successfully achieving a "soft landing," the U.S. economy still faced concerns about slowing growth. To prevent excessive tightening that could lead to a recession, the Federal Reserve decisively turned to accommodative policy in 1995-1996, cutting interest rates to support the economy. This operation proved to be quite successful—U.S. GDP growth increased from 2.68% in 1995 to 3.77% in 1996 and further surged to 4.45% in 1997, propelling the economy back into an upward trajectory.
However, in July 1997, the Asian financial crisis erupted, causing severe market turmoil. While the U.S. domestic fundamentals remained strong, global uncertainty surged rapidly, and the LTCM (Long-Term Capital Management) crisis sparked market panic. To prevent external shocks from dragging down the domestic economy, the Federal Reserve cut rates three times between September and November 1998, reducing the federal funds rate from 5.5% to 4.75%.
The impact of this round of gradual interest rate cuts has been quite significant, with the economy maintaining its expansion and the capital markets experiencing a euphoric rally. Since the easing began, the Dow Jones Index has more than doubled, registering a 100.2% gain; the S&P 500 has surged by 124.7%; and propelled by the tech boom, the Nasdaq has soared by 134.6%, preloading energy for the subsequent dot-com bubble.
2001–2003: Recovery After the Dot-Com Bubble
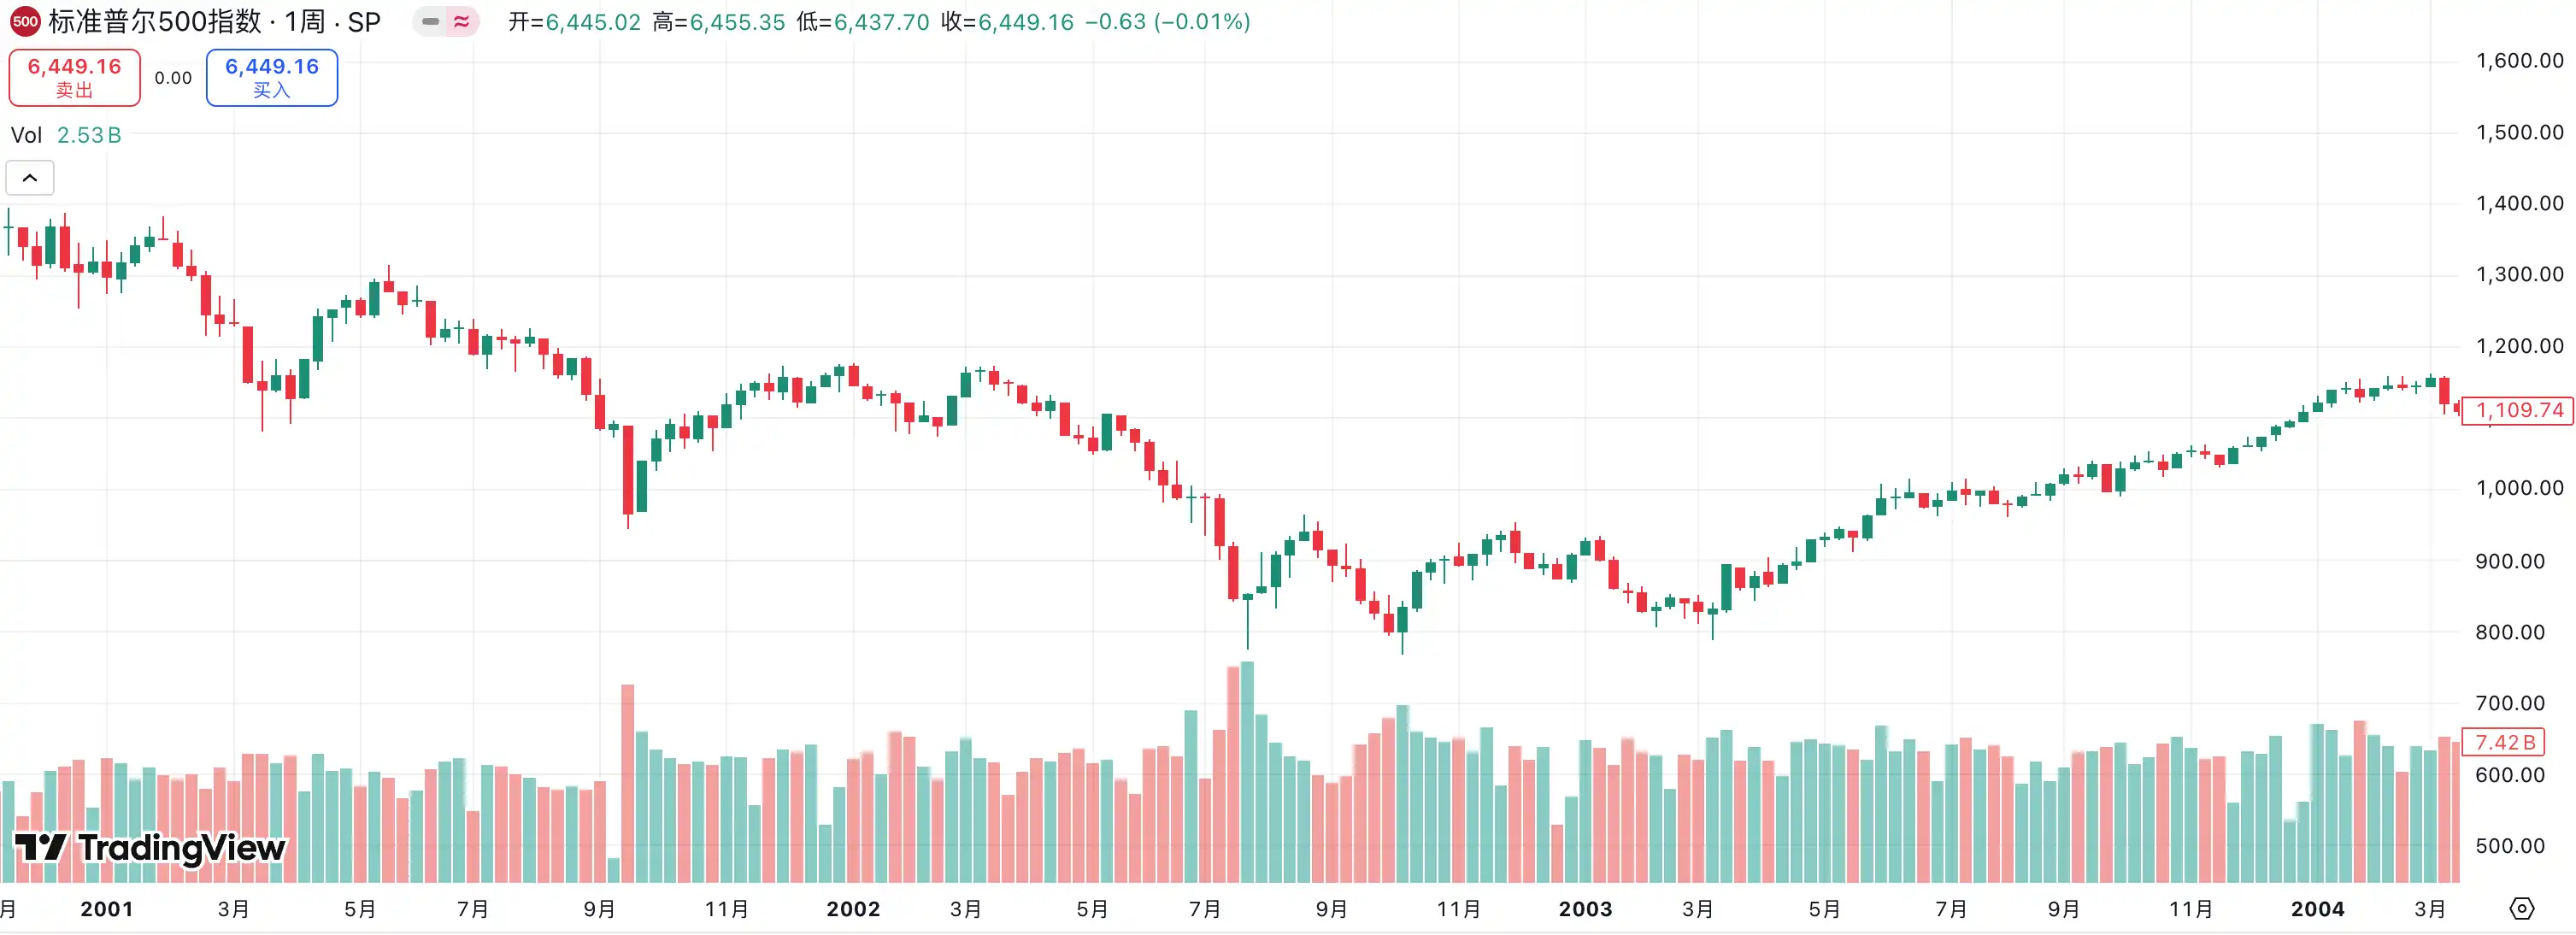
Between 2001 and 2003, the U.S. economy suffered from the burst of the dot-com bubble, the 9/11 terrorist attacks, and the subsequent impact of a recession, with the market plunging into a deep slump. The collapse of the dot-com bubble led to a stock market crash that quickly spread to the real economy, causing a sharp decline in corporate investment, a surge in unemployment, and ultimately triggering an eight-month-long recession. The initially fragile recovery momentum suffered a severe blow in September 2001 after the terrorist attacks, causing a rapid downturn in financial markets and consumer confidence.
To address these pressures, the Federal Reserve embarked on one of the most aggressive easing operations in history over a short span of two years. The federal funds rate plummeted from 6.5% at the beginning of 2001 to 1.75% in December of the same year, further dropping to 1% in June 2003, totaling a hefty 500 basis points cut. The Fed aimed to stimulate reinvestment by businesses and consumer spending through ultra-low financing costs to stabilize the economic foundation.
The policy indeed averted a more severe systemic crisis, but the recovery process was far from smooth sailing. In 2002, the U.S. real GDP grew by only 1.7%, with weak corporate investment and persistently high unemployment rates, making the economic recovery arduous. However, as the accommodative policy gradually transmitted, the growth momentum significantly picked up in 2003–2004, with the GDP growth rate rising to 3.85% in 2004, indicating a stabilization of the U.S. economy.
However, the stock market's reaction fell far short of expectations. The drastic rate cuts failed to reverse the capital market's decline, with the three major indices still posting losses from 2001 to 2003: the Dow Jones Index fell by 1.8%, the S&P 500 dropped by 13.4%, and the tech-heavy Nasdaq plummeted by 12.6%. The experience during this period demonstrated that even substantial monetary easing struggled to immediately combat the profound impact of a structural bubble burst.
2007–2009: The Financial Crisis and the Zero Interest Rate Era
In 2007–2008, the global financial crisis broke out, causing a profound impact on the U.S. economy and financial system. The crisis originated from the bursting of the real estate bubble and the concentrated outbreak of subprime mortgage issues. Prior to this, the U.S. real estate market had been thriving for a long time, but as housing prices fell, a large number of borrowers defaulted. Financial institutions suffered heavy losses due to holding a substantial amount of subprime loans and related derivatives, leading to a credit market freeze and a sudden depletion of liquidity.
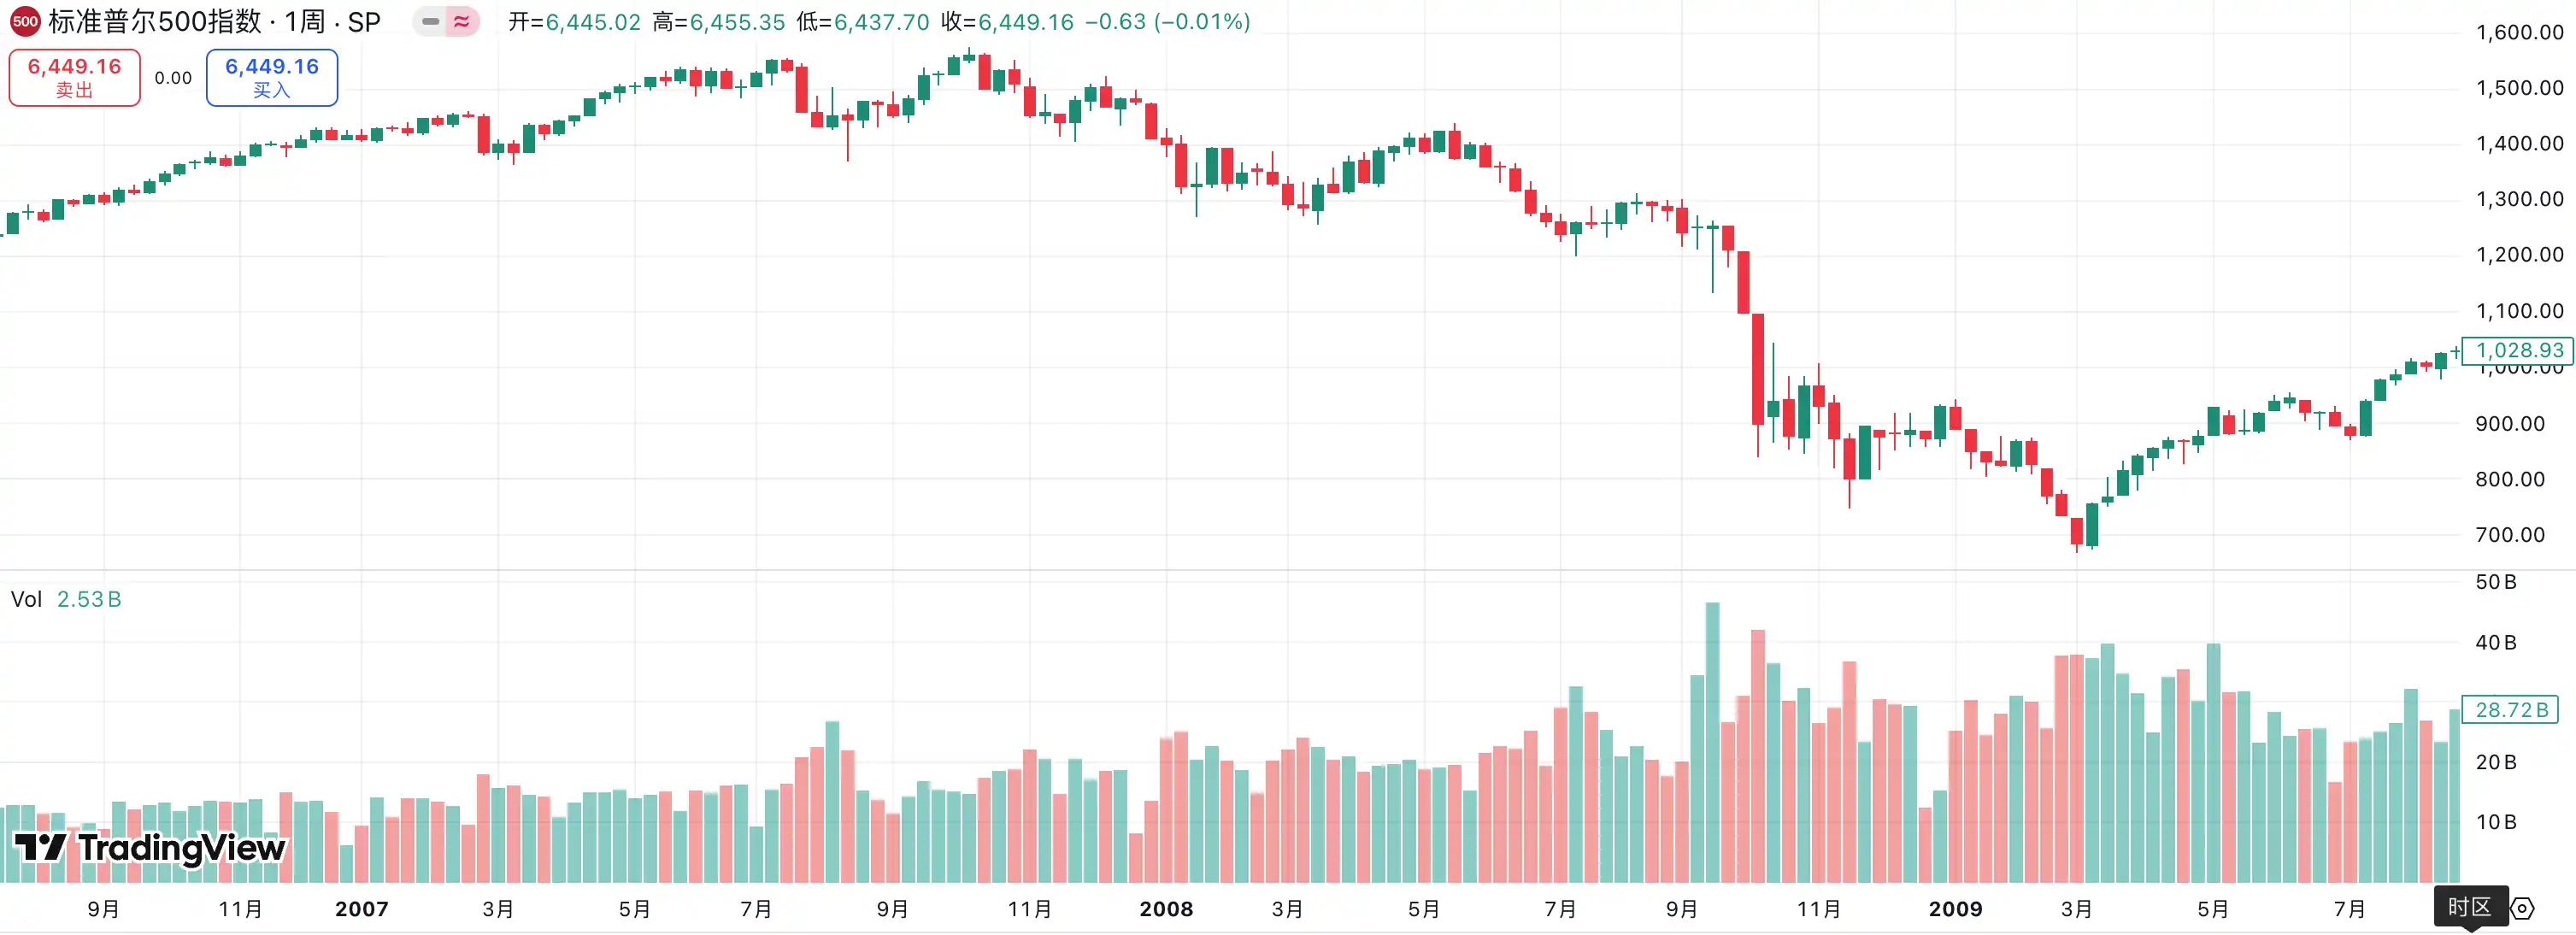
Facing the rapidly escalating crisis, the Federal Reserve embarked on an aggressive rate-cutting cycle starting in September 2007. The federal funds rate was continuously reduced from 5.25% to a range of 0–0.25% by the end of 2008, with a total reduction of 450 basis points, nearly touching the zero lower bound. Its core purpose was to stabilize the financial markets and the banking system through extremely loose liquidity supply, alleviating the impact of credit tightening on the real economy. In March 2008, the Federal Reserve even intervened to facilitate JPMorgan's acquisition of the failing Bear Stearns to prevent the crisis from spreading contagiously.
However, the market's panic did not dissipate. In September 2008, Lehman Brothers collapsed, marking the full outbreak of the financial crisis. Subsequently, global markets descended into a liquidity panic, with the U.S. unemployment rate soaring to over 10%. Business and household assets plummeted, and the economy plunged into the most severe recession since the Great Depression. CPI experienced rare deflationary pressures, reflecting a cliff-like drop in demand.
From a macro perspective, rate cuts failed to halt the spread of economic recession. U.S. GDP growth had already dropped to 1.9% in 2007, further declining to -0.1% in 2008, and shrinking by -2.5% in 2009. It wasn't until 2010 that the U.S. economy gradually stabilized, with GDP growth rebounding to 2.6%, laying the foundation for the decade-long expansionary cycle that followed.
The stock market's performance was even more brutal. Between 2007 and 2009, the Dow Jones Industrial Average plummeted by 53.8%, the S&P 500 Index fell by 56.8%, and the Nasdaq Index dropped by 55.6%. This "Great Recession" revealed that relying solely on rate cuts was insufficient to resolve the crisis.
2019–2021: Preemptive Easing and Pandemic Shock
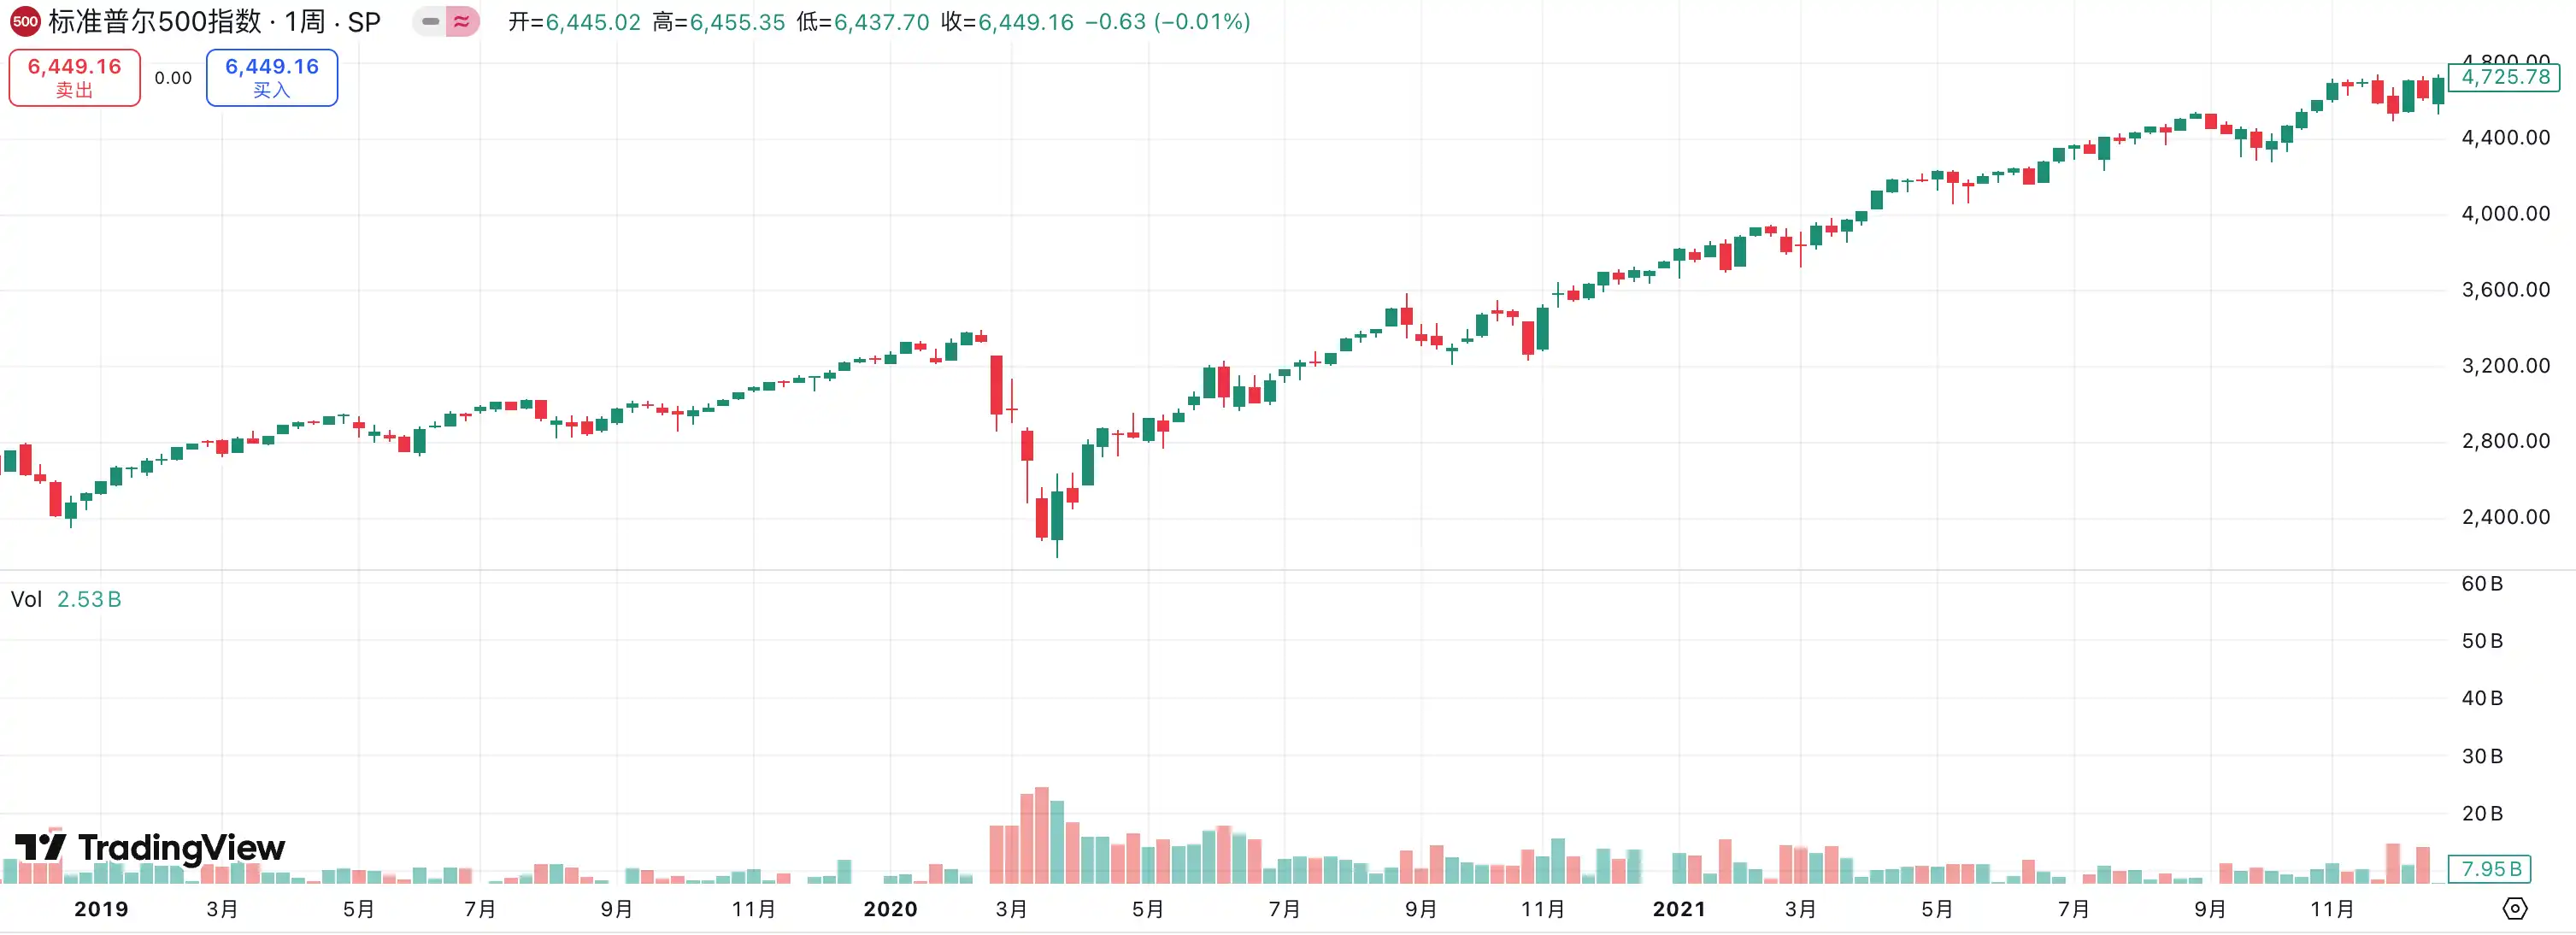
In August 2019, the Federal Reserve initiated a new round of rate cuts to address global economic slowdown and uncertainty caused by events such as the U.S.-China trade tensions. However, this seemingly mild preemptive easing was pushed to the extreme in early 2020 by the sudden onset of the COVID-19 pandemic. The pandemic rapidly spread, leading to an unprecedented economic lockdown and wave of shutdowns, global supply chain disruptions, rapid consumption declines, soaring unemployment rates, and severe financial market turmoil.
To stabilize the situation, the Federal Reserve in March 2020 urgently cut the federal funds rate from 2.25% to the near-zero level of 0.25% and, in conjunction with large-scale fiscal stimulus by the government, implemented an unlimited quantitative easing policy, leading to a sharp expansion of the balance sheet. This was not just a rate cut but also an extremely rare "unconventional operation" in monetary policy history, demonstrating the central bank's determination to stabilize the financial system and the economic foundation.
From a macro perspective, the U.S. economy remained relatively stable in 2019, with a GDP growth rate of 2.3%, slightly lower than previous years but still within a healthy range. However, the year 2020, under the impact of the pandemic, became a turning point, with the U.S. GDP experiencing a historic contraction of -3.4%, the most severe shrinkage since the 2008 financial crisis. Thanks to the ultra-loose monetary and fiscal combination, the U.S. economy rebounded rapidly in 2021, with a GDP growth rate as high as 5.7%, making it one of the fastest recoveries in forty years.
The stock market's performance was equally breathtaking. After a sharp downturn in March 2020, driven by the loose policy and a flood of liquidity, the U.S. stock market embarked on a "V-shaped reversal" and then surged all the way: from 2019 to 2021, the S&P 500 Index accumulated a 98.3% increase, the Nasdaq rose by an astonishing 166.7%, and the Dow Jones Industrial Average also recorded a substantial 53.6% gain. The extreme rate cuts and massive liquidity injection during the pandemic ultimately gave rise to the most vigorous liquidity bull market in U.S. stock market history.
The Two Biggest Bull Markets in Crypto History: How They Happened
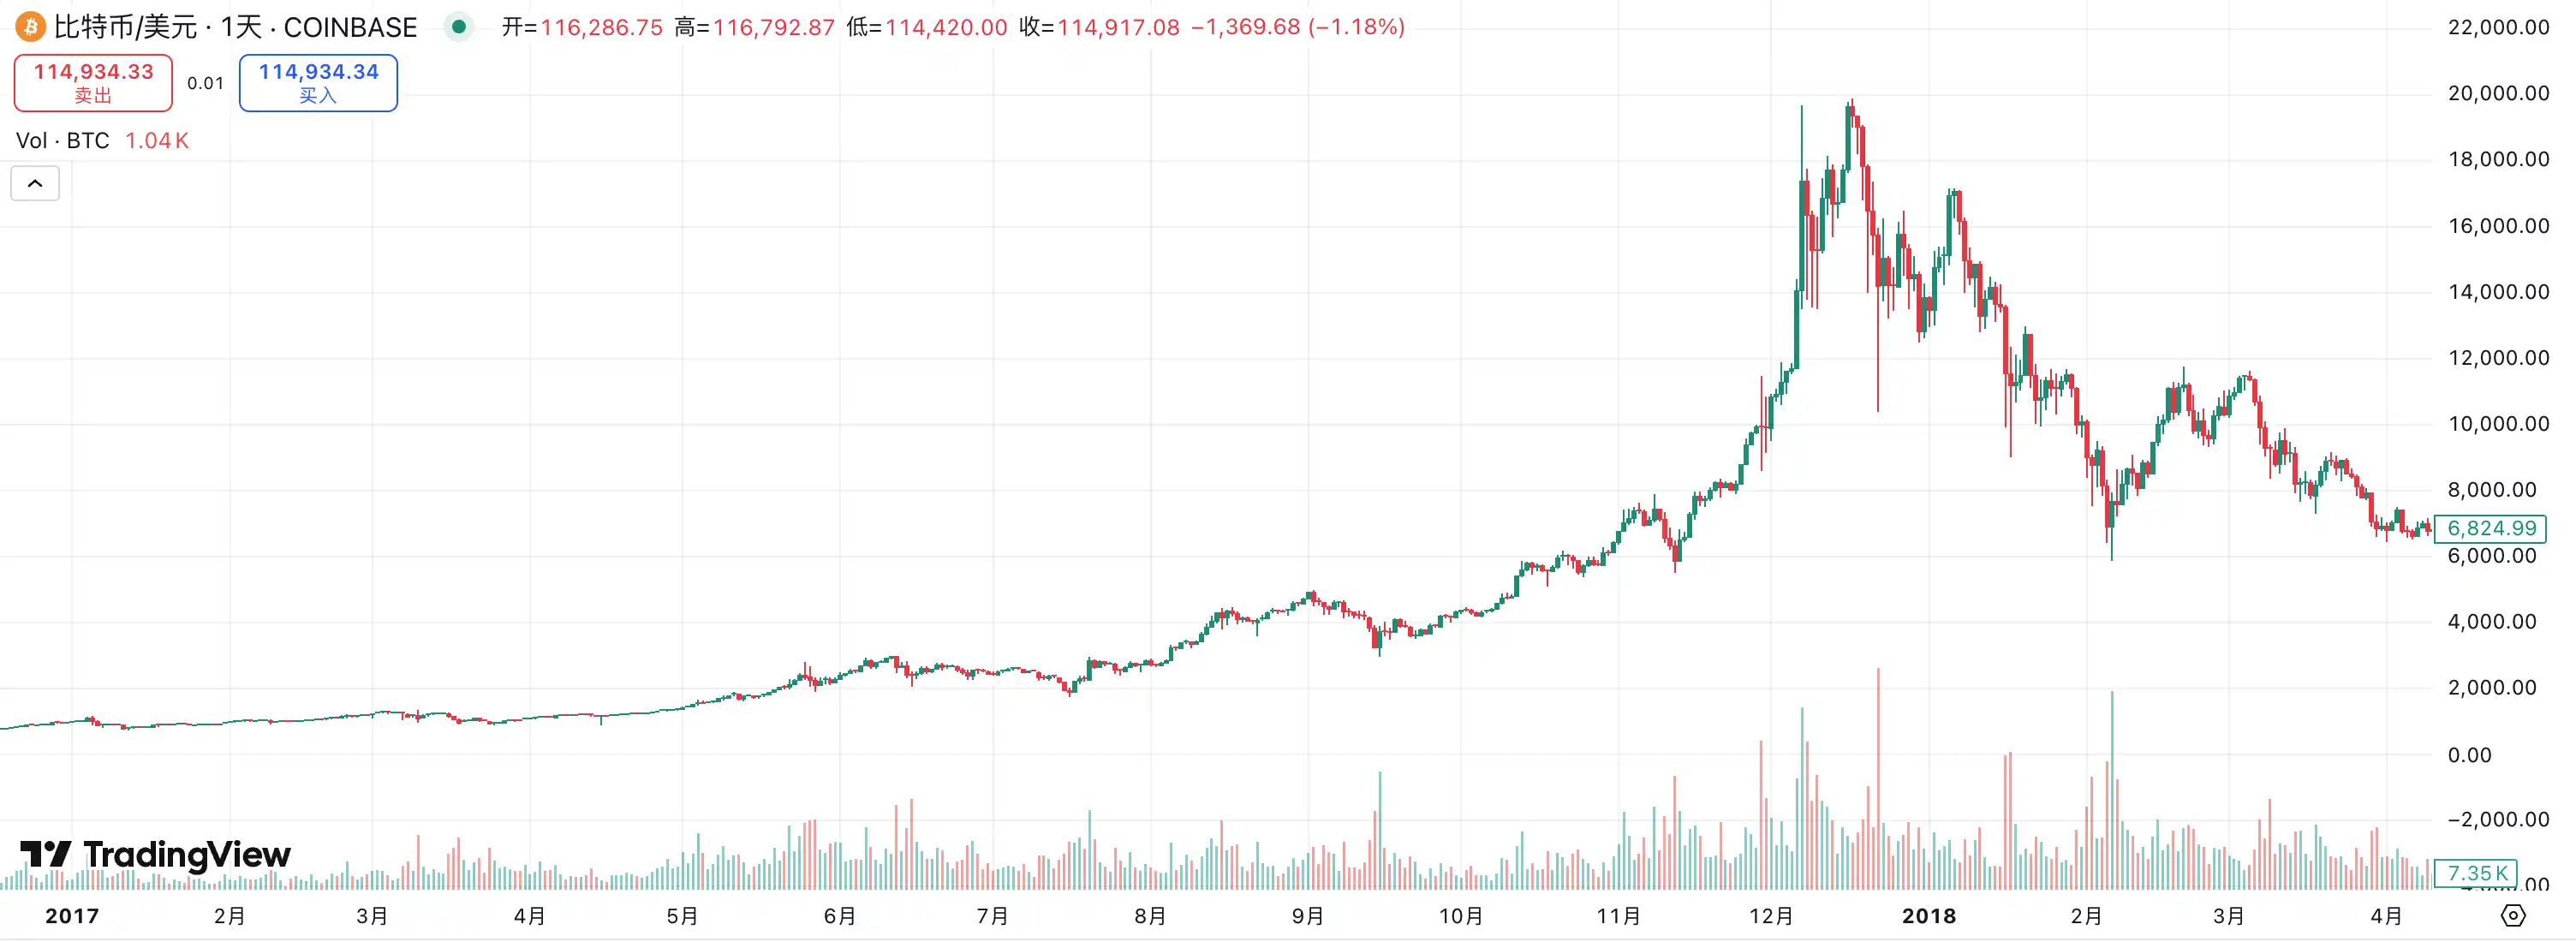
2017: The ICO Craze and the First Crypto Bubble
2017 is widely regarded as the "first major breakout" in the crypto market, marking the starting point when altcoins truly entered the public eye. Against the macro backdrop, the global economy was in a recovery phase, the U.S. economy was performing steadily, and although the Federal Reserve had begun its rate hike attempts, overall interest rates remained at historically low levels, with the liquidity left by previous years of monetary easing still lingering in the market. This macro environment provided fertile ground for speculative assets.
Bitcoin's price skyrocketed throughout the year from under $1,000 at the beginning to nearly $20,000 at the end of the year. The surge of the flagship asset directly attracted a large amount of new capital and retail investors to enter the market. In this context, altcoins experienced an unprecedented boom. Unlike before, the main driver of the 2017 altcoin rally was the ICO model: almost any project that issued tokens on Ethereum could quickly raise funds. A large number of new coins emerged, creating a scene where "hundreds of coins took flight" in the market.
Ethereum has undoubtedly been the core beneficiary of this round of the bull market. As ICO projects are generally based on Ethereum issuance, Ethereum itself has become the main entry point for market funds. The price of ETH soared from a few dollars to $1,400 within a year, driving the overall valuation of the entire altcoin sector. At the same time, whether the narrative is solid or not, from public chains, payments, storage to various new concept tokens, almost all could receive funding frenzy in a short period of time.
However, behind the frenzy often lies a bubble. The altseason of 2017 was essentially a liquidity-driven speculative feast, where investment logic relied more on "new stories" rather than actual applications. As we entered the beginning of 2018, with Bitcoin peaking and falling back, altcoin prices generally experienced 80% to 90% deep retracements. Many projects lacking fundamentals quickly went to zero, leaving a mess behind.
Looking back on this history, the altseason of 2017 laid the foundation for the first global recognition of the crypto market: crypto assets can generate huge wealth effects under the promotion of liquidity and narrative, but they will also demonstrate extremely high risks when the bubble bursts.
2021: Liquidity Flood and the DeFi, NFT Craze
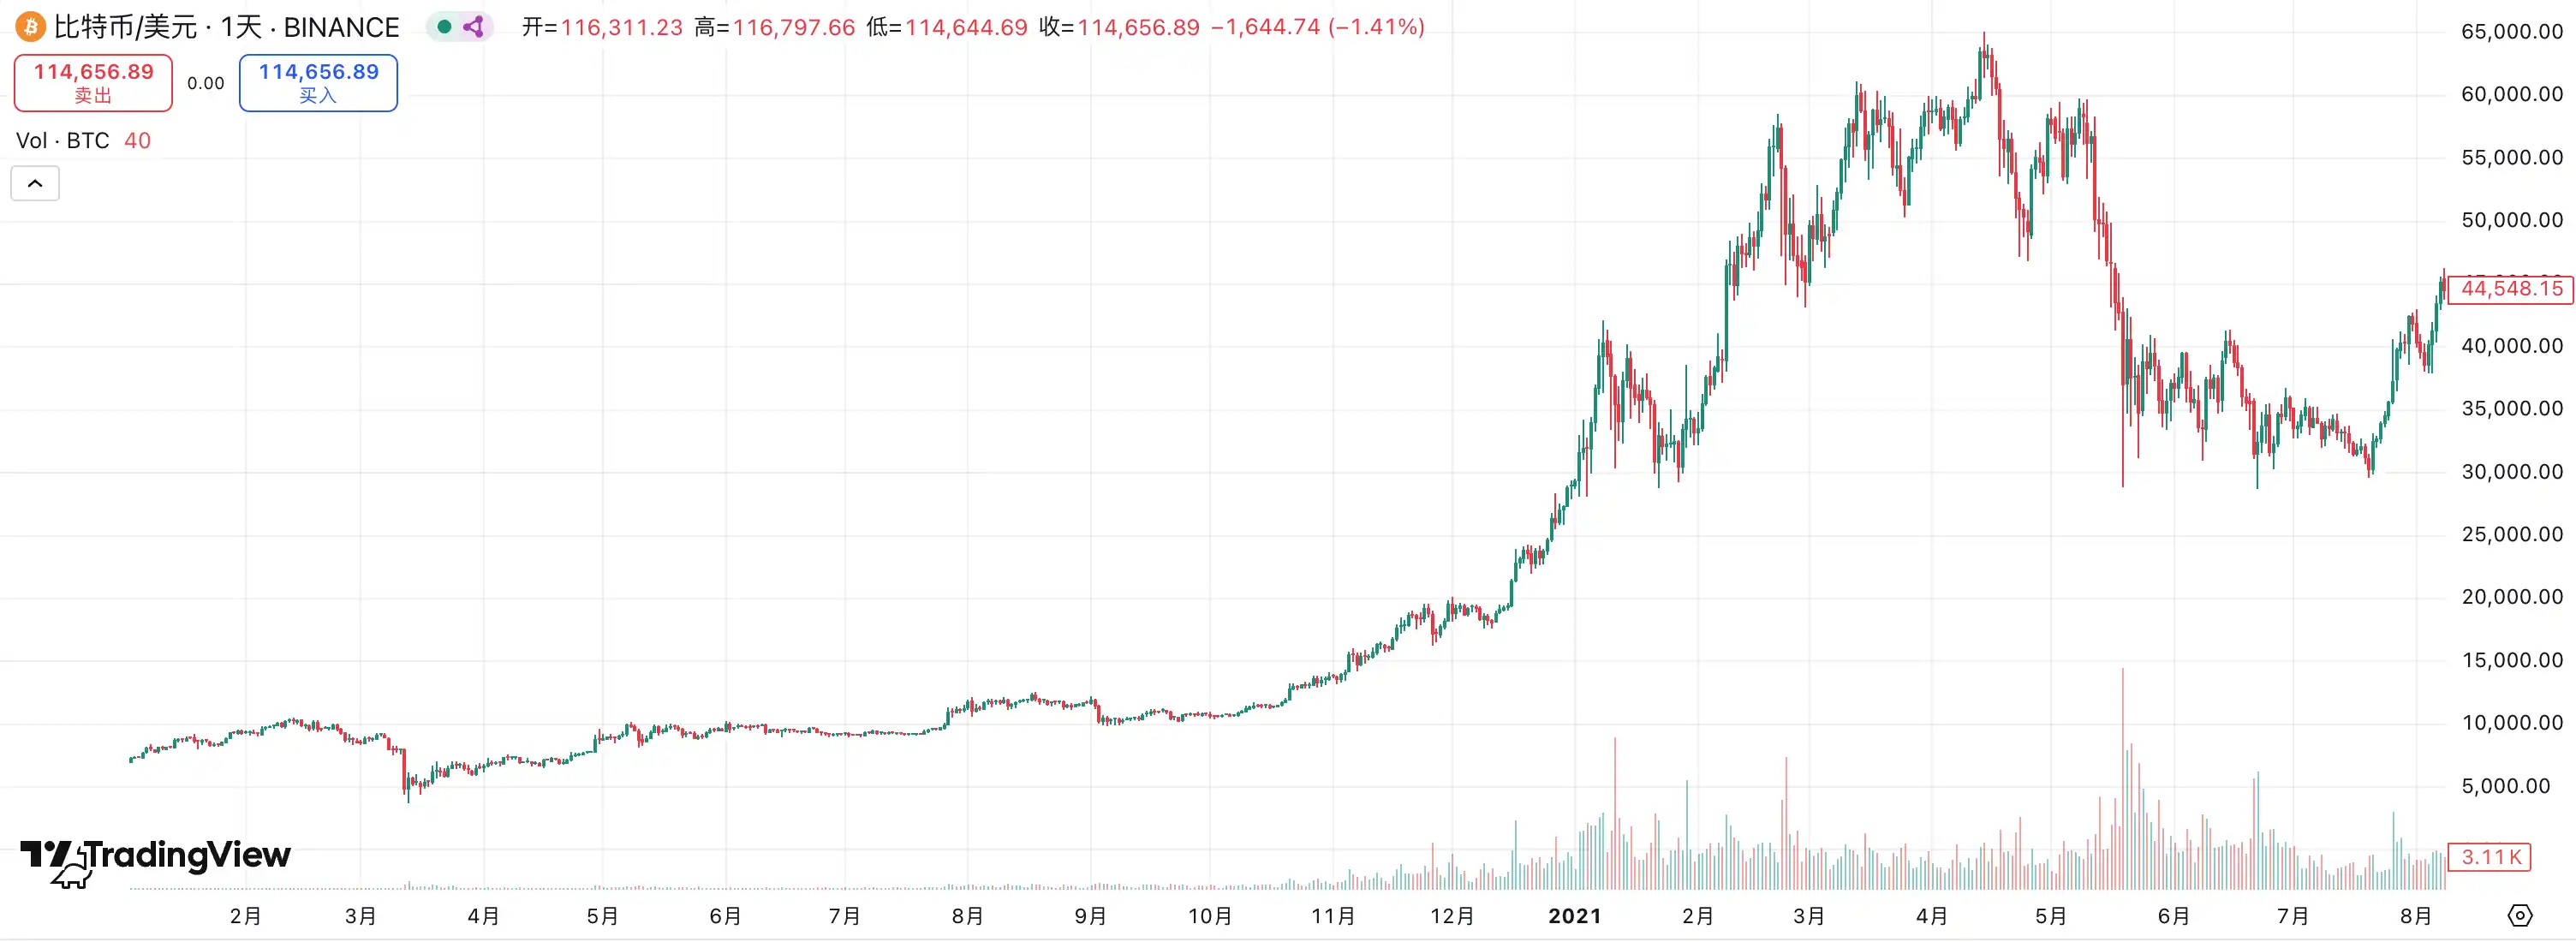
If the altseason of 2017 was a speculative feast ignited by ICOs, then the altcoin market of 2021 was a comprehensive carnival under the backdrop of global liquidity flooding.
In terms of the macro environment, at the beginning of 2020, the COVID-19 pandemic broke out, the Federal Reserve quickly cut interest rates to near zero, and launched an unprecedented quantitative easing (QE) program. At the same time, the U.S. government rolled out large-scale fiscal stimulus, directly issuing cash checks to residents. Loose monetary and fiscal double stimuli led to financial market liquidity flooding, with traditional assets and risk assets inflating simultaneously. After the V-shaped rebound of the U.S. stock market in 2020, Bitcoin broke through the $20,000 mark at the end of the year and quickly surged to $60,000 in the first quarter of 2021, opening up space for the altcoin market.
Unlike the "single-point outbreak" of 2017 centered around ICOs, the altseason of 2021 presented a pattern of "multi-track simultaneous advancement." First, there was the rapid development of DeFi. The TVL (Total Value Locked) of protocols such as Uniswap, Aave, and Compound grew rapidly, propelling DeFi concept tokens into independent trends. Secondly, the emergence of NFTs, projects such as CryptoPunks and Bored Ape made "digital collectibles" a globally hot topic, and trading volumes on platforms like OpenSea exploded. At the same time, the prosperity of Ethereum's ecosystem drove the rise of new public chains such as Solana, Avalanche, and Polygon, officially kicking off the public chain competition landscape.
Under this narrative, ETH rose from less than $1,000 at the beginning of the year to $4,800; SOL rose from less than $2 to $250, becoming one of the biggest dark horses of the year. The entire crypto market cap surpassed $3 trillion in November 2021, reaching a historical peak.
However, the rapid expansion of the market also planted the seeds of a bubble. Numerous copycat projects, over-financialized DeFi products, and meme coins lacking fundamental support quickly gained popularity during the influx of hot money but saw sharp declines after liquidity dried up. As the Federal Reserve initiated a rate hike cycle in 2022, global liquidity tightened, causing a rapid cool-down in the crypto market, with most altcoins experiencing a deep retracement of 70% to 90%.
Reflecting on this phase, the 2021 altcoin season showcased how the crypto market, driven by a liquidity flood and diverse narratives, could reach such extreme prosperity.
The Current Insight: Preemptive Easing and Altcoin Season
A historical review shows that the Federal Reserve's rate cuts can be divided into two types: preemptive cuts and remedial cuts. The years 1990, 1995, and 2019 belong to the former, with rate cuts occurring before a full-fledged economic downturn, more as a risk hedge that often injects new growth momentum into the market; whereas 2001 and 2008 saw forced significant cuts under the heavy pressure of financial crises, leading to steep market declines. In the present context, with a weak labor market, tariff and geopolitical uncertainties, but signs of easing inflation, the overall environment is closer to "preemptive easing" rather than a crisis backdrop. It is precisely because of this that risk assets have continued to strengthen this year, with both Bitcoin and US stocks hitting historic highs.
The environment facing the crypto market is also different from before. On the policy front, it has seen an unprecedented positive development: stablecoins are gradually being brought into compliance frameworks, Digital Asset Treasuries (DAT) and treasury management represented by MicroStrategy have become an enterprise trend, institutions have formally entered through ETFs, and the tokenization narrative of Real World Assets (RWA) is also rapidly gaining popularity. Different narratives intertwine, driving a broader market foundation than ever before.
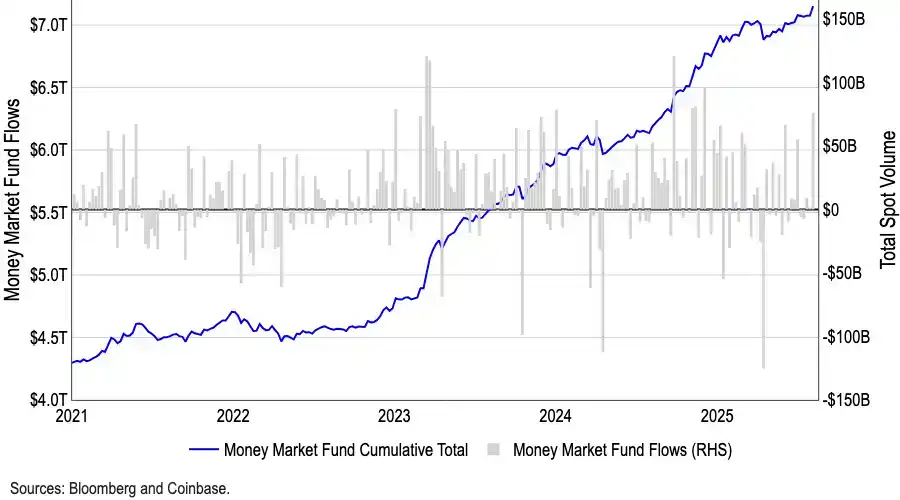
While many debated whether the September rate cut would lead to a short-term peak in the crypto market, from a funding flow perspective, this concern may be overblown. The US money market fund size has reached a record $7.2 trillion, with a large amount of funds trapped in low-risk instruments. Historically, outflows from money market funds have often been positively correlated with the rise of risk assets. With the rate cut in place, the attractiveness of their returns will gradually diminish, and more funds are expected to be unleashed into crypto and other high-risk assets. It can be said that this unprecedented cash reserve is the most powerful potential powder keg of this bull market.
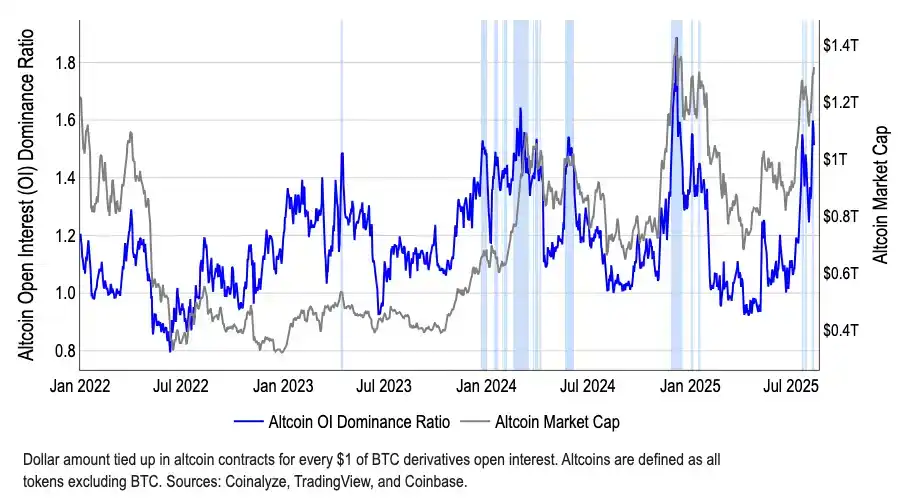
In addition, structurally, funds have begun to gradually move away from Bitcoin. BTC's market dominance has slipped from 65% in May to 59% in August this year. Meanwhile, the total market value of altcoins has grown by over 50% since early July, reaching $1.4 trillion. Although CoinMarketCap's "Altseason Index" remains around 40, far from the traditional Altseason threshold of 75, the divergence between this "low-index, skyrocketing market cap" precisely reveals that funds are selectively entering specific sectors, especially Ethereum (ETH). ETH has not only benefited from institutional interest with ETF sizes breaking $22 billion but also carried the core narrative of stablecoins and RWAs, possessing a funding appeal surpassing that of Bitcoin.
Related Read: "Coinbase Report: $7 Trillion in Cash Ready to Go, Altseason May Fully Arrive in September"
Summary
The logic of this bull market is entirely different from the past. With a vast number of projects, the market can no longer reproduce the past "all coins flying" scene. Investors' focus is gradually shifting towards value investment and structural opportunities — funds are more willing to flow into leading projects with real cash flow, compliance prospects, or narrative advantages, while assets in the long tail lacking fundamental support are bound to be marginalized.
At the same time, the overall market valuation is at a high level, and the risk of a "over-financialized treasury strategy" remains unknown. Once institutional or project-focused mass sell-offs occur, it can easily trigger a stampede effect, causing deep market impact. Coupled with global macro uncertainties (such as tariffs, geopolitics, etc.), investors cannot ignore the potential volatility.
Therefore, although we are optimistic about the performance of crypto assets in a rate-cutting cycle and favorable policies, it must be acknowledged that this is more like a structural bull market than a indiscriminate surge. Rational investment and carefully selecting the track are the keys to navigating the volatility.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles