Interview with Robinhood Co-Founder: Why We Need to Build Our Own Blockchain? | In-Depth Interview

Original Title: Vlad Tenev Wants to Tokenize SpaceX & OpenAI on Robinhood
Original Source: Bankless
Original Translation: kkk, BlockBeats
Editor's Note: On June 30th, Robinhood co-founder Vlad Tenev posted on X, stating that the company would make a major announcement related to its crypto business tonight at 11 pm Beijing time. This move aligns with Robinhood's current comprehensive expansion in the crypto and fintech field.
Today, as fintech gradually evolves towards "platformization" and "intelligentization," Robinhood stands at the intersection of traditional brokerages and the new order of crypto, outlining the possible form of future personal financial services through a series of product lines.
Robinhood is moving away from its positioning as a single trading tool to a "operating system" layout centered around the user's entire lifecycle. From private equity tokenization, integrating a CFTC-compliant prediction market, launching Cortex and Strategies covering AI strategy advisory and options strategy construction, to introducing "Cash Delivery" style Robinhood Banking and a unified multi-chain wallet architecture, the pace of its financial expansion far exceeds the traditional imagination of a FinTech company.
In this in-depth interview with Bankless, Tenev outlined for the first time the overall concept of Robinhood's expansion into the fields of crypto, AI, private banking services, and private equity opening. He emphasized that Robinhood is not the "antithesis of centralization," but is becoming a bridge connecting TradFi and DeFi: providing a more efficient and fairer financial access model through a pattern beyond a banking license; at the same time, he also responded to the controversy of being "Bankless," pointing out that Robinhood plays the role of a gateway service provider in the crypto business rather than a sovereign issuer.
Today's Robinhood is no longer just an entry ticket for U.S. stock retail investors but is trying to become a shared gateway for crypto-native users, AI wealth management users, and global asset investors.
This interview was published on March 31st, and the following is a compilation of the conversation:
Bankless: Welcome to Bankless, a program dedicated to exploring the forefront of internet finance. Today, my guest is Robinhood's CEO Vlad Tenev. As the platform's user base and asset under management continue to grow, Robinhood is accelerating its position as a leading player in the cryptocurrency field. In fact, they entered the cryptocurrency race early on: not only did they provide cryptocurrency trading functionality in the Robinhood App early on, but they also launched the Robinhood Wallet—a true non-custodial cryptocurrency wallet.
However, due to the former U.S. Securities and Exchange Commission (SEC)'s tough enforcement stance on the crypto track, Robinhood's further expansion into the crypto space was temporarily put on hold. Now that that phase has passed, my question is—after finally receiving SEC clearance, how will Robinhood advance its crypto product offerings? Coincidentally, just this week when I had this conversation with Vlad, Robinhood announced a series of blockbuster product lines, including the Robinhood Bank Strategic and Cortex. I also took this opportunity to have an in-depth conversation with Vlad about these new businesses.
However, for me, the most interesting and favorite part of the entire interview was the discussion about "the increasing threshold for private companies to go public in the traditional financial market" and "how this trend intersects with the tokenization movement." The most promising companies today, such as SpaceX, OpenAI, Anthropic, are all still private enterprises. Although their equities are traded in various ways in the private placement market, there is no true public market presence.
Vlad believes that tokenization can make a significant impact here—it can not only bring liquidity to these private enterprises but also provide investment opportunities for investors interested in accessing cutting-edge technology companies. This innovation is simply a perfect match, and if there is a platform best suited to carry this tokenization market, Robinhood naturally stands out as the most promising candidate.
Overall, I thoroughly enjoyed this interview with Vlad. Although Robinhood is not yet a fully "debanked" platform, they are constantly challenging the traditional financial system, forcing the old order to reform—a good thing for the entire industry. So, let's officially start today's episode. But before that, let's thank the sponsors who have made it possible for this show, known as the "wild west" of DeFi, to continue airing. That's why you should check out FRAC's Finance—an avant-garde protocol that is completely reshaping the stablecoin system.
Welcome to the Bankless Nation. Today, we have invited Robinhood's CEO Vlad Tenev. This is Vlad's third time on the show. Every time he comes, there are always some major updates about Robinhood. And every time Vlad appears, Robinhood delves further into the crypto space. This time is no exception. Vlad, delighted to have you back, welcome to Bankless.
Vlad Tenev: Thank you for the invitation, as always, thrilled to be here.
Bankless: You've recently just released a series of major product updates: Robinhood Strategies, Robinhood Banking, and Robinhood Cortex. The timing of our show airing aligns perfectly with these releases, although it's purely coincidental. We'll discuss these products shortly, but I'd like to start with some topics more focused on crypto-native issues, especially the recent changes in the U.S. domestic crypto regulatory landscape.
Under this new administration, the U.S. crypto industry has seen many new opportunities, especially for institutional investors who were previously hesitant due to regulatory uncertainties. With the new administration in place, what specific "doors" have been opened? What new capabilities does Robinhood have that were previously unattainable? Which door do you intend to walk through first?
Shift in SEC Regulatory Attitude
Vlad Tenev: I think the most direct change is that the U.S. has moved away from the "enforcement-over-regulation" approach. In simple terms, we no longer have to deal with a punitive stance across all aspects of our business. This shift has brought about significant improvements. For example, the SEC (U.S. Securities and Exchange Commission) announced the end of its investigation into Robinhood's crypto business, as well as the crypto businesses of several other companies in the industry. At that moment, we felt an immediate sense of relief – we can finally continue to move forward as a company, as an industry, without constantly battling against relentless pressure.
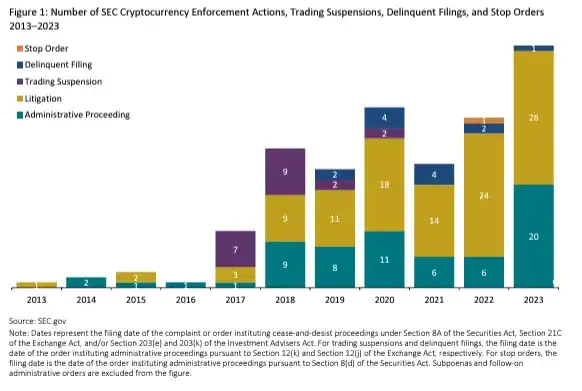
The previous administration had a very clear stance on crypto: they fundamentally believed crypto should not exist, let alone be deeply integrated with the traditional financial system. So, this policy shift is a huge positive development. Additionally, there are two key legislative directions that are also advancing. Of course, I must emphasize one point: the cessation of "enforcement-style regulation" in itself is already a significant turning point.
Another notable development is the clear regulatory stance on Meme coins. You may have seen that the SEC issued a memo regarding Meme coins, explicitly stating that such tokens are not securities. This isn't very controversial. From a legal analysis perspective, Meme coins do not fit the definition of securities, which is relatively clear-cut. But in the past, each project had to individually undergo this analysis to determine if it was a security.
Robinhood has always been one of the more compliant companies. We conduct thorough reviews and compliance analyses for every token, including assessing whether it constitutes a security. This process is both costly and cumbersome. Therefore, receiving official guidance and exemptions is immensely valuable, significantly reducing the operational burden on us and the entire industry.
Similarly, there is now a more precise definition of whether staking constitutes a security. This is a very positive development. Just think about it, the essence of staking is users contributing their computing power resources to support the blockchain. And the presence of staking service providers is to simplify this process.
Overall, this means that users can earn higher rewards, meaning more cryptocurrency flowing into their wallets. The previous lack of clear regulation in this area was actually harming American consumers because they were unable to receive their fair share of earnings on a more regulated platform.
So, having clear guidance now is a good thing. Currently, the US has two important legislative directions in progress: one is stablecoins, and the other is market structure. The stablecoin legislation is expected to pass first, which is certainly good news for the entire industry. But what we are truly excited about is the "market structure" legislation.
We believe this legislation is key as it will provide a clear roadmap for how we integrate cryptographic technology into traditional financial assets in the real world. For example, asset tokenization, interest-bearing stablecoins, and even prediction markets. We will be able to clearly define:
Which assets fall under Crypto Asset Security,
Which fall under Crypto Asset Commodity,
What compliance steps are needed as a platform to list crypto asset securities,
And as issuers, what conditions need to be met to offer these assets to the American public.
I believe these are the key issues, and legislation can help us address them one by one, which is the prerequisite for truly unlocking the potential of cryptographic technology. We are very excited about this.
You mentioned earlier that some companies are exploring using stablecoins to build banking services, meaning users' stablecoins can be staked or deposited into a pool to earn rewards. I think that the true implementation of such innovative products requires the coordination of "cryptocurrency market structure legislation," which would bring more competitors into the banking sector.
The current stablecoin legislation has not yet fully covered these "interest-bearing stablecoins," so it still cannot provide a solid legal foundation for this model. We do need more regulatory clarity to make these products more compliant and safer for the general public. But we remain optimistic and are actively involved in related legislative work in Washington. The current trend is positive, and we are confident about it.
Bankless: From what you're saying, I feel like there are actually many product lines that can be theoretically derived now, but we are still in an exploration or conceptualization stage. To truly enter the implementation and construction stage, relevant bills need to be passed by Congress as soon as possible. Am I understanding this correctly?
Vlad Tenev: Absolutely right. For example, a stablecoin that pays interest directly to the holders is essentially very similar to a money market fund. In fact, many stablecoins themselves hold government bonds, so from this perspective, they are not much different from money market funds. The regulatory treatment of stablecoins has always been somewhat different, but we believe this is exactly where regulatory clarity is needed.
Private Equity Tokenization
Bankless: Let's talk about "Asset Tokenization" in this area. I think this is a particularly hot topic, especially in the traditional financial sector. Because it is essentially a bridge between traditional finance and the crypto world: Can we put more assets on the blockchain to truly leverage the advantages of a public, permissionless blockchain? So, what role does Robinhood play in this trend of tokenization? I guess you are bullish on it. Will you become an issuer? Or a platform provider? Will Robinhood issue tokenized products itself? Or are you more inclined to be a trading marketplace for these products? Where do you position yourselves in this tokenization technology stack?
Vlad Tenev: For us, the definition of "Asset Tokenization" is: to create a mapping on-chain for a non-native crypto asset, allowing it to be freely traded. We actually have some examples of this, such as stablecoins. Stablecoins are actually tokenized government bond assets. There's also Paxos's tokenized gold product, which is another interesting example. We have also collaborated with Paxos and some other companies to launch USDG, the Dollar Global Network project, aiming to create a stablecoin that is global-facing and can provide attractive returns to holders.
Next, naturally, is security tokenization, which is a direction we are very much looking forward to. Because it allows global users to own shares of U.S. companies just like they use stablecoins. Just as stablecoin legislation is seen as a tool to promote the global dominance of the dollar, security tokenization could also become key to maintaining the dominance of U.S. companies in the global market.
Vlad Tenev: Currently, it is very difficult for foreign investors to invest in U.S. companies. Just as stablecoins have made it easy to obtain dollars, security tokenization allows global users to easily invest in U.S. stock companies. This is beneficial for companies, and for overseas investors as well, as they can access quality assets as a diversification tool against their depreciating currencies. This is also good for U.S. entrepreneurs and the capital market. If we can more easily finance companies through the global crypto market, we will see more interesting and potentially successful companies emerge. In fact, a few months ago, we published an op-ed in The Washington Post calling for the advancement of private securities tokenization.
Just think, how difficult it is now to invest in private companies like OpenAI or SpaceX. And blockchain technology is actually a solution. If we could tokenize shares of private companies, it would be beneficial for both the company and the investors. One absurd point to me is that now we already have a clear regulatory definition for meme coins, and people can freely invest in these fundamentally sound projects, but cannot invest in high-quality private companies like OpenAI or SpaceX.
Bankless: If I piece this information together, there already exists a "market" for SpaceX equity, but it is currently limited to the private market. Many individuals have acquired SpaceX shares through various means. Are you suggesting that we could tokenize these shares, use blockchain technology to make this market more standardized and structured, and create a truly regulated and deep market?
So, in this process, Robinhood could become a platform that provides a trading market. Are you saying that this is one of your roadmaps? And how far away is Robinhood from launching a tokenized product for companies like SpaceX?
Vlad Tenev: Yes, Robinhood is at the intersection of traditional finance and crypto finance. We have all the crypto technology while also possessing a full suite of traditional financial infrastructure, such as multiple broker-dealer licenses under our belt. This is where we can contribute to the ecosystem.
In the future, I think this might work like the issuance mechanism of an ETF. ETFs fundamentally hold a basket of securities and then issue ETF shares to the public. This can actually be seen as a precursor to tokenized securities. In the operation of ETFs, investors can exchange a basket of underlying assets for ETFs, or redeem ETFs to receive back those assets. This "creation/redemption" mechanism is essentially a contrasting model of tokenization logic in traditional finance. And blockchain technology can make this process more efficient and decentralized.
Bankless: Although we see that the number of IPOs has not experienced a cliff-like drop, the overall trend is indeed downward. The reason is simple: the cost of IPOs is just too high, making it increasingly challenging for many companies to surpass that threshold. Will this also drive the development of the "tokenization of the private market"? Or is this path too complex and difficult to implement from the perspective of regulatory compliance and traditional financial norms in various countries? How do you see it?
Vlad Tenev: I believe that this trend will drive "security tokenization" to become an alternative path to IPO. This scenario will inevitably unfold—even if the U.S. does not adopt it in the short term, other countries will begin to experiment. The nature of crypto is global. If you can tokenize a company's shares on the blockchain within a compliant jurisdiction, you can instantly tap into a market with growing liquidity, global participants, and a user base of over a billion. Therefore, I believe the U.S. will ultimately embrace this trend.
This tokenization serves two key purposes:
One is at the early-stage startup level, which is equivalent to a traditional IPO, known as primary market financing. The "seed capital" at this stage is crucial. As a founder who has started a company at the seed funding stage, I know that fundraising consumes a significant amount of energy and resources, which can be very tight for small companies. If you can quickly access a global funding pool to raise funds, this is a very attractive option. This will also give rise to more new companies and projects, providing investors with early-stage (although higher-risk) participation opportunities with greater potential returns.
Two is for later-stage private companies, such as OpenAI or SpaceX, where the founders have raised a large amount of capital and may even be planning an IPO. Tokenization may not be very appealing to founders at this stage, but it is very valuable to employees. Many large companies have thousands or even tens of thousands of employees, but these employees lack a clear expectation of IPO or exit liquidity, and there is no predictable channel for liquidity. At this point, they may hope to monetize, sell a portion of their shares, and achieve asset diversification. This creates a strong practical impetus for tokenization.
There are indeed some "employee equity secondary markets" now, such as EquityZen and Forge, which actively contact employees to help them transfer shares. However, the biggest issue with these platforms is that liquidity is fragmented. The platforms need to match buyers and sellers, creating an inefficient process. The advantage of crypto lies in interoperability. Once you put assets on the chain and turn them into freely tradable tokens, you can immediately access global liquidity. This is where tokenization shines as a powerful technological solution.
Bankless: Indeed, there are many trends pushing in this direction now. Star companies like SpaceX and OpenAI are private and clearly uninterested in going public. Many AI startups are also like this—they do not have publicly held equity, and they are not as massive as Meta or Google, where buying stocks poses the issue of equity dilution, making it difficult for investors to truly bet on the AI track.
Vlad Tenev: For ordinary investors, the investment options to bet on AI are very limited. You may only be able to buy NVIDIA (but its market cap has already exceeded a trillion), Alphabet (also in the trillion-dollar club), and Tesla. Of course, they are all too large, having already reflected most of the AI premium. But you can't invest in the truly core AI startups like OpenAI, Anthropic, or Perplexity.
Bankless: Indeed, just by looking at the current public market trend, it is clear that new investment opportunities are increasingly not appearing in the public market but are concentrated in the private market. Part of the reason for this, as I mentioned earlier, is because the compliance costs of IPOs are getting higher and the barriers are becoming harder to overcome. Meanwhile, crypto is offering a potential solution. I see many favorable winds driving this trend towards its culmination: tokenization of private market equity, which may eventually become some form of a "quasi-public market."
Alright, I also want to discuss prediction markets because I remember Robinhood recently also ventured into this area. Did you ever have a slogan like "Marketize Everything"? Or am I mistaken? Is this your formal strategic direction? Or is it just an external impression? Can you help me clarify?
Robinhood's Entry into Prediction Markets
Vlad Tenev: Actually, Robinhood has not formally used the slogan "Marketize Everything."
Bankless: So, this is indeed something I imagined.
Vlad Tenev: However, our parent company is called Robinhood Markets. You may have heard our mission slogan: Democratize Finance for All. This means that we believe in the power of the market, and if a market exists, we believe it should be facilitated and made accessible to traders. Especially for markets that were originally only open to institutions, if retail traders are interested, we believe retail traders should also be able to participate in a fair environment. This is actually one of our goals on the path of "building markets," and this certainly applies to prediction markets as well.
And personally, I believe prediction markets have an additional societal value: they are not just a trading venue; they can also bring about more accurate event predictions. We have already seen this in the presidential election—when the mainstream media was still hesitating, prediction markets had already given directional judgments hours or even days in advance. I believe that in the future, we will see this trend in more areas. So I think prediction markets are a "truth machine"; they are an evolution of traditional news—sometimes even able to "see the news" before an event happens, which is very interesting.
Bankless: Back then, like many others, I hosted a presidential election watch party. The mainstream media was playing on the TV, but most of my friends were in the crypto industry, so in addition to the mainstream media, we also had a Polymarket page open on the screen. As a result, everyone kept switching between the mainstream media and Polymarket to view the data—and Polymarket gave us a more "real-time," closer-to-the-truth feeling.
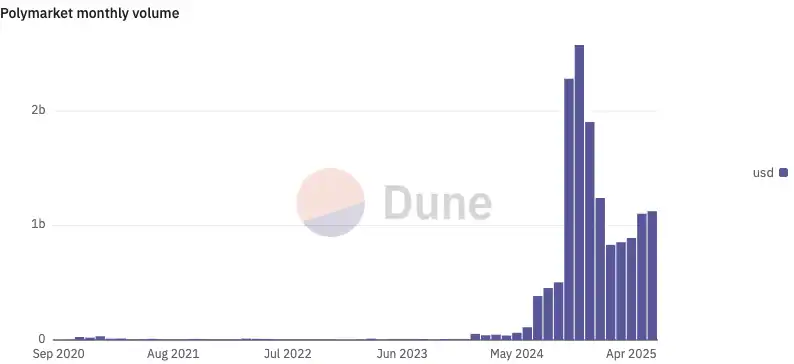
Recently, Robinhood also made a move regarding prediction markets. Let me read a press release to introduce this topic: Robinhood recently launched a prediction market section within its app, allowing users to participate in trading the outcome of global major events. At launch, the contracts available for trading included "Upper Limit of May Federal Funds Rate" and contracts related to the "Men's and Women's NCAA College Basketball Tournaments." It seems like two completely different types of markets. So, the first question, I already know the answer to—the purpose of launching the prediction market. But more noteworthy is that this product is supported by Kalshi. Could you introduce Kalshi's role in this collaboration?
Vlad Tenev: Alright, Kalshi is a DCM (Designated Contract Market), and its role is similar to an exchange in the stock market. For example, in the stock market, we have NASDAQ and the New York Stock Exchange. Robinhood, as a brokerage firm, would connect to these exchanges or market makers to match the buying and selling sides, and the trade matching is done on the exchange. In the stock realm, Robinhood is a brokerage firm, and we have introduced introducing brokers and clearing brokers, who would send orders to the exchange or market maker. In the futures market, regulated by the CFTC (Commodity Futures Trading Commission), the role of the DCM is to act as the exchange. In the case of Robinhood in this prediction market, our role is that of an FCM (Futures Commission Merchant). We interact with customers, provide interfaces, order placement channels, and then route orders to the DCM for matching.
You can think of Kalshi as the NASDAQ, and we are the traditional sense of a brokerage firm. For the presidential election-related contracts, we are connected to another DCM called ForecastEx, which is a subsidiary of Interactive Brokers. We can actually connect to multiple DCMs to provide users with access to different contract types. However, all the prediction market contracts we offer must be formally listed by the DCM before we can go live.
Bankless: So, essentially, Robinhood itself cannot launch its own prediction market; it can only integrate through a third-party DCM, right?
Vlad Tenev: That's correct. The main reason why Polymarket, as you mentioned earlier, cannot operate compliantly in the United States is that it's not a DCM. They have adopted a completely decentralized, cryptography-based approach to running a prediction market. But this is precisely one of the issues that the market structure legislation we mentioned earlier aims to address: to whom should prediction markets like Polymarket be regulated in the U.S.? Should they be managed according to the CFTC's commodity contract rules? Or should there be a new regulatory framework specifically for the "crypto version" of prediction markets? Currently, these questions have no clear answers, and only after legislation progresses can such markets legally operate in the U.S.
Bankless: I believe our podcast audience would definitely want to be able to legally use Polymarket in the U.S. as well. So, the final question about prediction markets: Robinhood has currently launched prediction markets for the "federal funds rate" and "college basketball games." What other new prediction-based trading products can we expect in the future? Can you reveal Robinhood's next steps?
Vlad Tenev: With the release of our latest batch of prediction market contracts, we have upgraded from only being able to launch one contract at a time to being able to introduce hundreds simultaneously. This involves the complexity of operations such as clearing, settlement, and the dependencies between contract structures, especially with series contracts like men's and women's NCAA basketball games, which greatly challenge our system. Next, we will soon have the ability to launch thousands of contracts at once, completely unlocking the diversity and potential of the prediction market.
We are excited about many areas, especially the development of artificial intelligence. There are some prediction markets centered around AI technology progress that are quite interesting and indeed provide insights, which our users are very interested in. But more importantly, I believe prediction markets should become a "newspaper of the future." For example, it should include a "front-page news" section (what everyone is most concerned about now), as well as "sports," "business," "entertainment and lifestyle" sections. The prediction market can be a microcosm of this information—a news form driven by real trading intentions.
Bankless: Yes, "Prediction markets as truth machines." I think this is why many crypto users are so fascinated by it. A very typical example was the conflict between Israel and Iran; when missiles started crossing borders, prediction markets on Polymarket provided cutting-edge, real information. These events not only involve sensitive geopolitical issues but are also very high-risk, impactful events. We are entering an increasingly turbulent global situation, and naturally regular people would want to better understand the likelihood of these possibilities. How do you see Robinhood integrating these global macro, geopolitically relevant prediction markets in the future?
Vlad Tenev: I believe that this is valuable for society as a whole. Currently, the CFTC has some guidance on "event contracts" (such as prediction markets), stating clearly that "prediction markets that are not in the public interest should not be listed for trading." However, this "public interest contradiction" is actually a very vague and broad concept. I think we should try to make this restriction more specific because I believe that the vast majority of prediction markets are inherently in the public interest.
Three Product Lines
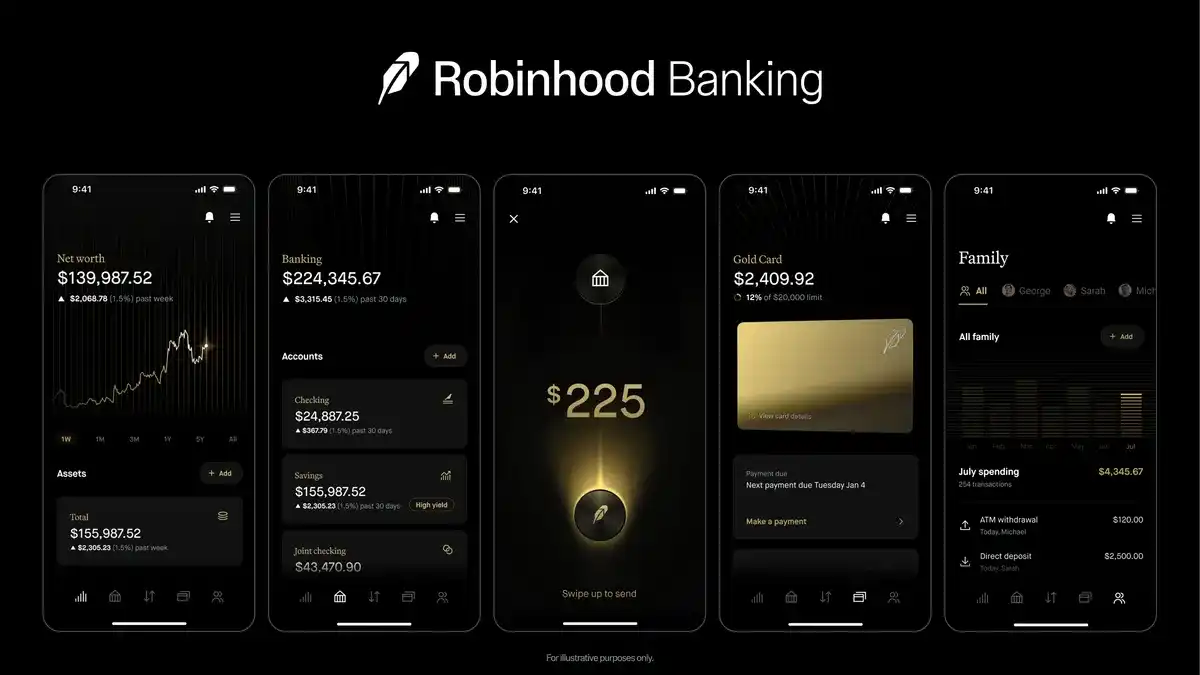
Robinhood Banking Product Line
Bankless: Going back to the theme of Robinhood. You recently held a large product launch event, similar to Robinhood's summit, introducing three major new product lines: Robinhood Strategies, Robinhood Banking, and Robinhood Cortex. Let's discuss them one by one, starting with the one I am most interested in: Robinhood Banking. What is the motivation behind this product? What were your initial thoughts?
Vlad Tenev: The core idea of this Gold event is: we want all users to have access to resources and services similar to those of high-net-worth individuals. High-net-worth clients typically have private banking advisors, investment advisors, research teams that can help clients find opportunities globally (whether in public or private markets). Technology now allows us to provide this "family office-level service" to regular users at a very low cost. This is exactly the direction we want to take—to put the financial team of a high-net-worth family into every user's pocket, with Gold members able to enjoy this service for just $5 per month. What we want to do is not just provide financial services but to use technology to create an "iPhone-like financial product"—an affordable and proud to own high-end product that anyone can use.
So the three products we launched at this Gold event are actually part of a complete logical thread: Strategies are your digital investment advisor; Cortex is your intelligent research assistant; and Robinhood Banking is your private banker. This is also Robinhood's first AI product launch. In the future, you will see more and more cutting-edge reasoning models, intelligent models gradually integrated into the product experience, achieving deep integration between products, truly achieving
"information interoperability," bringing an intelligent financial service experience.
Robinhood Cortex Product Line
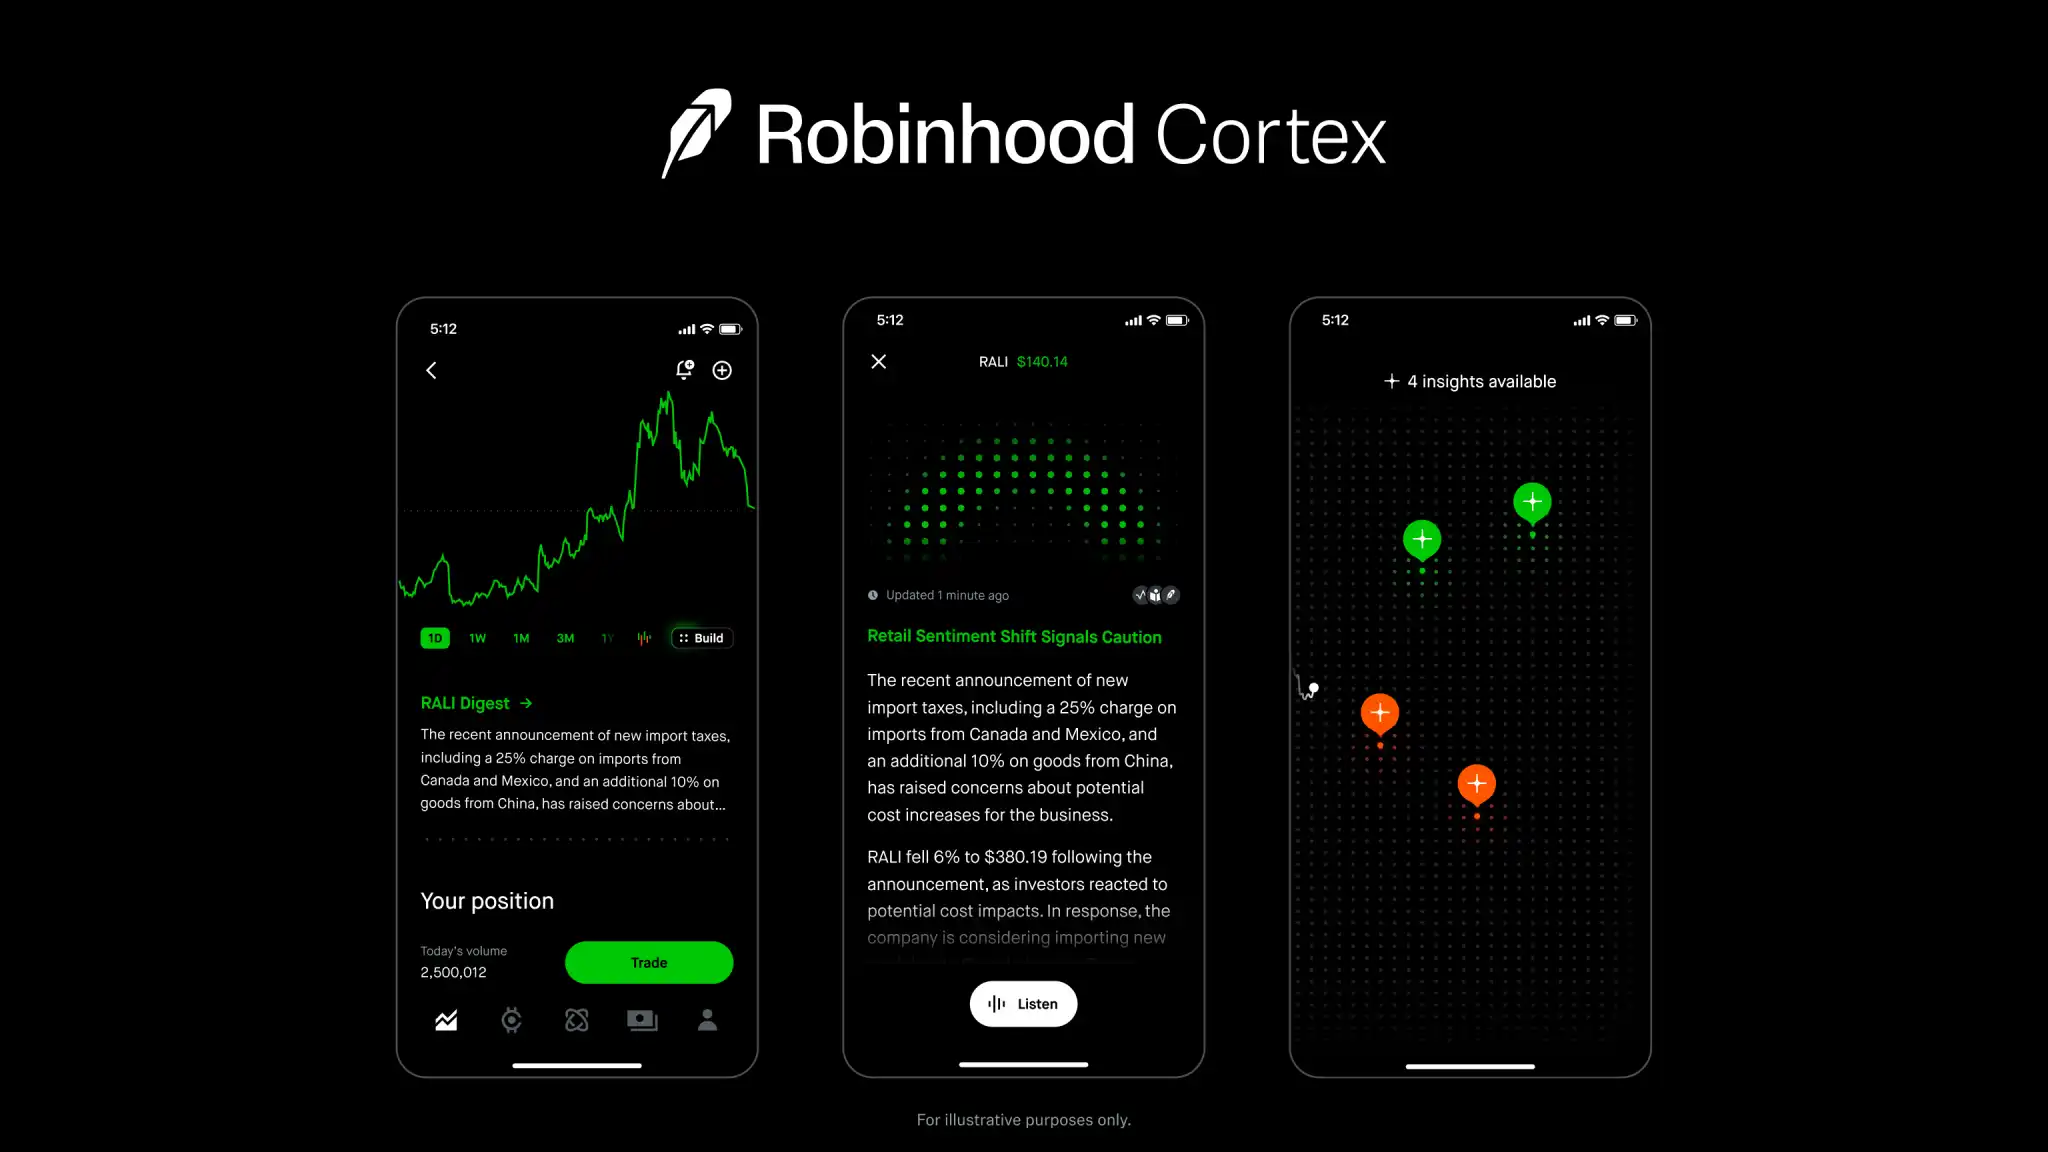
Bankless: When I saw Robinhood Cortex mentioned in the announcement, I initially thought you were launching an AI agent. It was only after reading further that I understood more. Could you give an example of how users actually use Cortex? My guess is that you have integrated it into Robinhood's mobile app, so is it like a finance-specific ChatGPT? Could you elaborate on what kind of product it actually is?
Vlad Tenev: Currently, within the Robinhood app, Cortex has two main use cases: The first one is to answer "What's happening with a particular stock right now." We often send users push notifications, such as a stock going up or down by more than 5%. Many users would then click to see what's happening with that stock. Cortex would then explain on the stock's detail page the reasons driving the current price fluctuation, providing a clear explanation as much as possible.
The second one is about options trading. Options are very complex for most people, especially when it involves multi-leg strategy combination trades, requiring a lot of professional judgment. Cortex, with the help of the Trade Builder feature, can automatically build a suitable options strategy combination for you based on your prediction of a particular stock's future trend, making the whole experience quite magical. We demonstrated this at the Gold event: Users select a stock, input their prediction, and then the system generates options strategies that can be traded directly, or enters our new feature—side-by-side option chain view, making it easy to simultaneously operate multiple options trades on one screen, which is very efficient.
Bankless: It sounds like this is the process: You express your trading intent in natural language, and AI receives and processes it to provide several suggested options combinations. Is it essentially translating human language into actionable strategy advice? Is that the logic?
Vlad Tenev: Yes, but we don't just match based on your language input. We also integrate various external data sources, such as real-time market data, technical indicators, news updates, etc., to help you better form the prediction itself. In other words, we not only provide strategies based on your existing prediction but also assist you in making more accurate predictions.
Bankless: Can you talk about the underlying structure of this LLM (Large Language Model)? I guess you didn't just wrap it around a ChatGPT, right? Does it have any special features in its data and training method that make it a truly Robinhood-centric financial AI?
Vlad Tenev: That's correct. Most general LLMs do not have real-time financial data; their data is often lagging. Therefore, they cannot tell you the "current" price of a stock, let alone provide a precise explanation of price fluctuations. What's more critical is that they are prone to financial illusions because of the lack of accurate data support in the financial domain. The AI layer we developed addresses both the illusion issue and real-time data problem, which are the two major shortcomings of traditional LLMs.
Bankless: Indeed, if AI in the financial domain experiences illusions, the consequences could be disastrous.
Vlad Tenev: Absolutely. But the advantage of finance is that we have a "data truth source." Unlike writing a history paper where it's hard to determine if there are illusions, financial data has clear standards. We can establish "guardrails" to accurately identify "illusions" and make corrections.
Bankless: And this may be the core competitive advantage of Robinhood in building a financial AI assistant: you not only have real-time market data but also user behavior data and all the contextual data in financial scenarios.
Vlad Tenev: Yes, this is a significant advantage. Another point is that we can also execute trades within the app. If we can make the Cortex "context-aware" of the user's behavioral context, it will become more valuable. We don't want to just put a chatbox in the app; that kind of thing is hard to use, leads to long outputs, and is prone to illusions. That's a very naive approach, and we deliberately avoid going down that path.
Robinhood Strategies Product Line
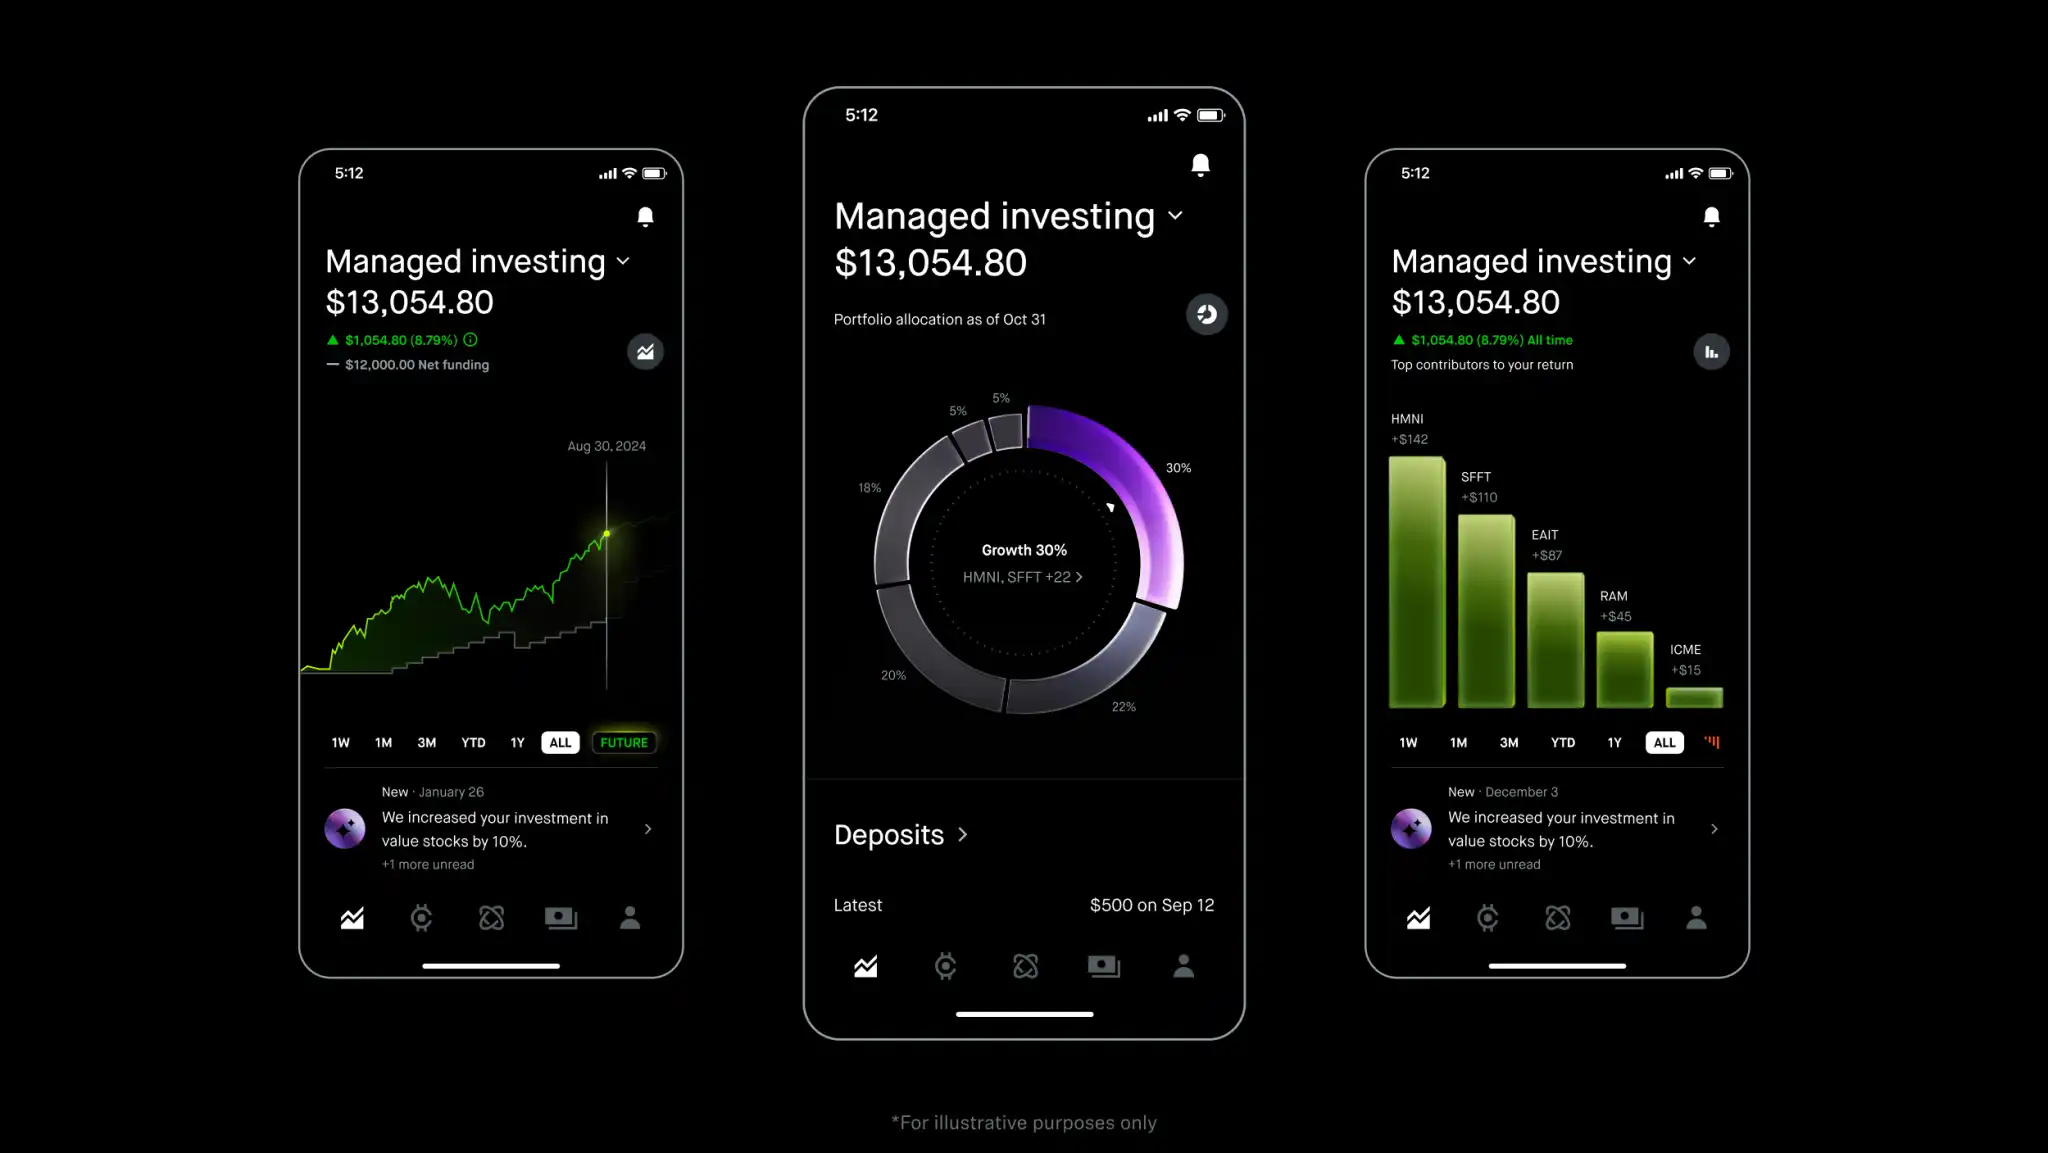
Bankless: Let's circle back to Strategies for a moment: are you considering expanding this product to include cryptocurrency assets in the future? Because all friends involved in crypto will be asked by people around them, "How should I buy coins?" "How should I allocate?" — but in reality, no one really knows how to answer. If Strategies could provide intelligent allocation advice for cryptocurrency assets, wouldn't that be particularly valuable? How do you plan to expand into this area?
Vlad Tenev: Technically, there are no issues at all. We have a long list of features at our disposal, with perhaps dozens or even hundreds of features under consideration. Currently, our main focus is on what users want the most. We chose to start with individual stocks because most digital investment advisory platforms only support ETFs, while our core supports both individual stocks and ETFs in a portfolio. Additionally, we have designed a beautiful interface, such as a pie chart displaying your asset allocation ratio and enabling automatic rebalancing, creating an "almost hands-off investment experience." As for cryptocurrencies, we actually considered adding them during the launch phase, and they will definitely be integrated gradually in the future. We are now live, and users can experience it directly. The feedback has been very positive, with many people starting to migrate their investment portfolios over.
Furthermore, our Strategies have a significant differentiating advantage: we have completely disrupted the traditional advisory platform's fee structure. Traditional advisors usually charge a fee based on the managed assets' percentage. Traditional advisors typically charge around 1%, while Robo-advisors, at the cheapest, charge 0.25%. This poses a problem: the more you invest, the fees increase linearly, but the service does not correspondingly improve. For example, a Robo-advisor managing one million dollars is not ten times more complex than managing a hundred thousand dollars. Yet, you are required to pay ten times the fee. This has made high-net-worth users increasingly dissatisfied. The strategy products we designed have a fee cap: at most, only $250. Regardless of your asset size, the fee no longer continues to grow. Consequently, the more assets a person has, the more cost-effective and satisfied they will be using Robinhood Strategies.
Bankless: Your Strategies have a fee cap of $250, so you are not charging based on AUM (Assets Under Management) anymore. Does this mean that Robinhood is more inclined to view this product as a "user-growth-driven" business? How does Robinhood benefit from the large-scale growth of Strategies?
Vlad Tenev: Yes, this fee structure is actually a significant incentive—it will attract users with a large amount of external assets to move their funds to the Robinhood platform. Robinhood can benefit in several ways: asset management fees, Robinhood Gold subscription fees.
Additionally, we have observed that once users become Gold members and transfer a significant amount of their funds, for example, $1000, they truly start to feel the value of this platform. Subsequently, they are more likely to use more of our services, such as credit cards, self-directed trading, and so on. This is the goal we hope to achieve—to "migrate" users' entire financial relationships to Robinhood, allowing them to conveniently manage all their funds. As the total funds on the platform increase, our income will also grow accordingly.
Cash Delivery Service
Bankless: Got it. I also want to ask about another thing regarding your new product — the Cash Delivery Service. When I saw this feature, my reaction was: Is this the "Uber Eats" of the cash world? Why did you decide to do this? How does it work?
Vlad Tenev: Yes, we did indeed enter the "logistics business" field, which is quite interesting to me personally. First of all, this is a high-end private banking service. Robinhood doesn't have physical branches, so we asked ourselves: How can we provide an uncompromised digital banking experience to customers without branches? While cash payments are declining, they still account for 16% of all transactions in the U.S., and many people still need cash. But if you're using a purely digital bank, you can only withdraw cash from 7-11 or CVS. Clearly, the idea of "going to a convenience store to get cash" is completely opposite to the "private banking experience."
We asked ourselves, can we reverse this — bring banking to your door? The current logistics platforms are very mature; you can get something delivered in 15 minutes, even an iPhone. So what we want to do is apply this model to cash services.
Of course, we won't build a full logistics system ourselves; instead, we will partner with professionals, and we will announce this partnership soon. Though complex, we believe this will bring tremendous value. I was a First Republic customer before, and they offered "cash delivery" services (albeit using armored vehicles for large cash amounts). We are thinking about how to standardize this "wealthy-exclusive service" enough to make it affordable for more people.
Bankless: I guess the minimum cash withdrawal amount you set wouldn't be something like $100, right?
Vlad Tenev: In the demo, we set the minimum amount at $200 for delivery. However, we are still in the exploration phase, and the specific minimum amount, user behavior, average withdrawal amount, etc., will depend on user feedback after launch. But we expect the average amount to likely fall within the range of a few hundred dollars.
Robinhood's Next Stop: Product Matrix and Ecosystem Layout
Bankless: Back to the crypto topic. Robinhood currently has few crypto assets listed. Do you have plans to expand to more coins?
Vlad Tenev: Yes, since the improvement of the regulatory environment, we have actually listed a lot of assets, such as Trump Coin. We listed it on the day of the inauguration, and it was very popular. Now, there are thousands of new coins being created every week. We also realize the need to rethink our asset listing strategy. You should expect to see the Robinhood Wallet (our on-chain wallet product) — currently somewhat separate from the main app — becoming more integrated with the main app in the future.
You will see: more on-chain features in the main app; smoother withdrawal and deposit processes in the Wallet; gradual integration between Custody and DeFi products. As the industry matures, our strategy will shift from "carefully selecting assets for listing" to "efficient optimization based on demand in the backend," allowing customers to choose for themselves. However, we must also establish filtering mechanisms to prevent the encouragement of speculative bubbles and prevent users from indiscriminately accessing high-risk meme coins in situations of information asymmetry.
Bankless: So now you have the Robinhood Wallet, the main Robinhood App, and the Robinhood Credit Card, which is Robinhood Banking, right?
Vlad Tenev: Yes, the Robinhood Credit Card has now been merged into Robinhood Banking.
Bankless: Is the division of labor among these three apps mainly due to compliance/regulatory considerations? Any thoughts on integrating them into a "super financial app"?
Vlad Tenev: Indeed, we initially wanted to create an "all-in-one app," but the issue was that the design of the homepage became too crucial. The expectations of active traders and users utilizing credit card/banking functions for the homepage are completely different. And indeed, most users mentally separate the "trading interface" and the "banking interface."
Therefore, when it comes to integration, I am open-minded. We can try to build a super app, but I am not fixated on "having to merge." What's more important is: unified KYC; seamless fund flows between accounts. Besides that, let the best interface win. Our main app may add more features, and we do not rule out the possibility of continuing to have different teams develop independent apps, even going back and forth like Uber and Uber Eats.
Bankless: Lastly, I'd like to talk a bit about freedom. You know, our show is called Bankless, advocating for "banklessness," emphasizing asset self-custody and self-sovereignty. However, Robinhood has many features that actually sound quite "bank-like," such as your upcoming bank products. Crypto has indeed challenged traditional finance, with banks like Wells Fargo offering only a 0.25% savings rate and showing little innovation. But Robinhood does provide a more high-quality option, yet you are not entirely "Bankless." So I want to ask:
Vlad Tenev: "How Bankless am I really?" Right?
Bankless: Right, how Bankless are you really? Which direction will Robinhood head in the future?
Vlad Tenev: Actually, in a literal sense, we are already Bankless; we do not have a banking charter. Sometimes people ask me, "Shouldn't you apply for a banking license?" because we are often compared to traditional financial companies with banking licenses. Having a license does have its advantages, such as direct access to systems like FedWire and Zelle, ability to issue loans, and perform clearing operations.
However, our current strategy is to collaborate with banks as a neutral platform. For example, in our credit card business, our partner bank is Coastal Community Bank, and other partner banks participate in our cash management program. In fact, many DeFi projects fundamentally also need a banking interface—because as long as you want to convert fiat to on-chain assets, the bank is part of the chain.
I believe that in the future, we will see more "crypto banks"—having certain licenses, accepting regulation but not being as heavy as traditional banks. These banks can manage liquidity pools, reserves, and other critical aspects, avoiding past collapse events like Terra Luna, Anchor, Celsius, and other projects that "look like banks but don't follow real rules." I am always a market person; I believe in free competition and fair regulation. These two worlds—traditional banking and cryptographic technology—will ultimately have to merge, not split apart.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles