Arthur Hayes Blog: Save the bank BTFP Global unlimited money printing

原文标题:《 Arthur Hayes 博文:拯救银行的 BTFP 全球无限的货币印刷 》
Original article by Arthur Hayes
GaryMa Wu says blockchain
Ever since the Fed started raising rates in March 2022, I have argued that the end result was always going to be major financial turmoil, followed by a resumption of money printing. It's important to remember that it's in the best interest of the Fed and all the other major central banks to keep our current financial system going (a system under which they can have power), so it's virtually impossible to cleanse the system of the staggering amount of debt and leverage built up since World War II. So we can almost certainly predict that they will respond to any substantial banking or financial crisis by printing money and encouraging a new round of the behavior that got us in danger in the first place.
I, like many other analysts, used to predict from our virtual pulpit that the Fed would keep raising rates until it broke something. No one knows for sure which things will fall apart first, but we're all sure they will. But don't jump to conclusions. Some people (including me) have been arguing that a rupture in some part of the U.S. financial system in 2023 will force the Fed to reverse the tightening cycle it has been on for the past year, and it looks like we're on that track.
I discussed the impact of the Federal Reserve's new Bank Term Funding Program (BTFP) with my favorite hedge fund manager. BTFP also means "Buy The Fucking Pivot"! I thought I understood the significance of what the Fed had just done, but I didn't fully appreciate the true impact of this policy. I'll get into the details of what I learned later, but it can be said that BTFPS, repackaged yield curve controls (Yccs) in a new, shiny, more acceptable form, are a very clever way to implement unlimited purchases of government bonds without actually buying them.
To fully understand why this BTFP program is so groundbreaking and ultimately disruptive to savers, let's review how we got here. We have to understand why these banks failed in the first place, and why BTFPS are a very elegant response to this crisis.
March of that year: The epidemic opened the floodgates
It all started in March 2020, when the Federal Reserve pledged to do whatever was necessary to ward off financial stress caused by the pandemic.
In Western countries (especially the US), the epidemic is a small China/Asia thing. The elite declared that all was well. All of a sudden, though, people started getting sick. The United States began to look like a lockdown, and the American market began to fall. The corporate bond market followed suit and soon froze. The sickness quickly spread and then eroded the US Treasury market. Backed into a corner of considerable importance, the Fed moved quickly to nationalise the US corporate credit market and flood the system with liquidity.
The federal government acted to create the largest deficit since the second world war in order to put money directly into people's bank accounts (in the form of stimulus checks). The Fed in effect cashed the government's check. The government had to issue huge amounts of new Treasury bonds to raise the money, which the Fed faithfully bought to keep interest rates near zero. It was a highly inflationary exercise, but it didn't matter then, because we were facing the pandemic of the century.
As expected, an unprecedented financial boom began. Everyone has stimulus checks to spend, rich and poor alike. At the same time, the cost of capital for asset speculators fell to zero, encouraging wild risk-taking. Everyone got rich, and everything became an exercise in pull-ups!
Bull market
Because the public had so much new money, banks were flooded with deposits. Remember, when we buy goods, services or financial assets, money doesn't leave the banking system, it just moves from one bank to another. As a result, most of the newly printed money ends up in a bank's deposit balance.
For systemically important banks such as JP Morgan, Citibank and Bank of America, deposit ratios have increased, but not by much. But for small and medium-sized banks, it's a huge increase.
America's weak banks, sometimes called regional banks, have never had so many deposits. When banks accept deposits, they use them to make loans. These banks need to find somewhere to park all this new money to earn a net interest margin (also known as a net interest margin). Given that yields are either zero or slightly above zero, parking money with the Federal Reserve Bank and earning interest on its excess reserves does not cover its operating costs, so banks must increase earnings by taking on certain credit and/or duration risk.
The risk that the borrower will not repay is called credit risk. The highest rated credit you can invest in (i.e. the credit with the lowest credit risk) is U.S. government debt, also known as Treasury bonds, because the government can legally print money to pay its debts. The highest credit risk you can invest in is the debt of companies like FTX. The more credit risk lenders are willing to take, the higher interest rates lenders demand from borrowers. Credit risk increases if the market perceives that the risk of companies failing to pay their bills is increasing. That would cause bond prices to fall.
Most banks are generally very credit risk-averse (ie, they do not want to lend money to companies or individuals they think are likely to default). But in a market where the most obvious and safest alternative - investing in short-term US government debt - is yielding close to 0%, they need to find some way to profit. As a result, many banks have begun to boost earnings by taking duration risk.
Duration risk is the risk that rising interest rates will cause the price of a given bond to fall. I won't go into the details of how to calculate the duration of a bond, but you can think of the duration as the sensitivity of the price of a bond to changes in interest rates. The longer a given bond matures, the higher its interest rate or duration risk. Duration risk also varies with the level of interest rates, meaning that the relationship between duration risk and a particular level of interest rates is not constant. This means that bonds are more sensitive to interest rates when interest rates rise from 0% to 1%, and less sensitive to interest rates when interest rates rise from 1% to 2%. This is called convexity or gamma.
In general, most banks limit credit risk by borrowing money from various parts of the U.S. government (rather than from venture firms), but increase their interest income by buying bonds with longer maturities (which carry more duration risk). That means they could soon lose a lot of money as bond prices fall as interest rates rise. Of course, banks can hedge their interest rate exposure by trading interest rate swaps. Some did, many did not. You can read about some of the very foolish decisions made by SVB management to hedge the huge interest rate risk embedded in its government bond portfolio.
Let's run it through. If a bank takes $100 in deposits, then they will buy $100 worth of US government debt, such as US Treasuries (UST) or mortgage-backed securities (MBS). So far, this asset-liability management strategy has worked fine. In practice, the ratio of deposits to loans should be less than 1:1 in order to maintain a safe enough balance to cope with loan losses.
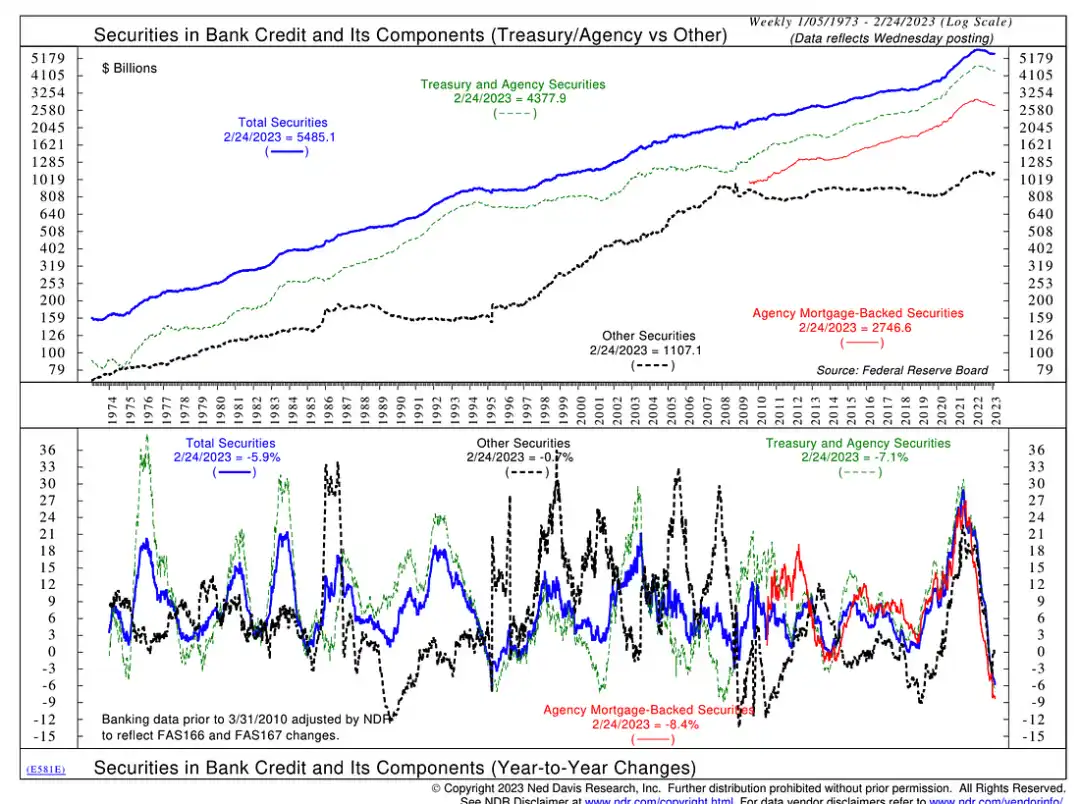
As the chart above shows, Bank of America bought a lot of Treasuries in 2020 and 2021. That's good news for the U.S. government, which needs money to back its stimulus checks. But not so good for banks, with interest rates at 5,000-year lows. Small increases in general interest rates can cause banks to suffer large losses in the market value of their bond portfolios. The FDIC estimates total unrealised losses at US commercial banks at $620bn as rising interest rates cause portfolios of government bonds to fall in value.
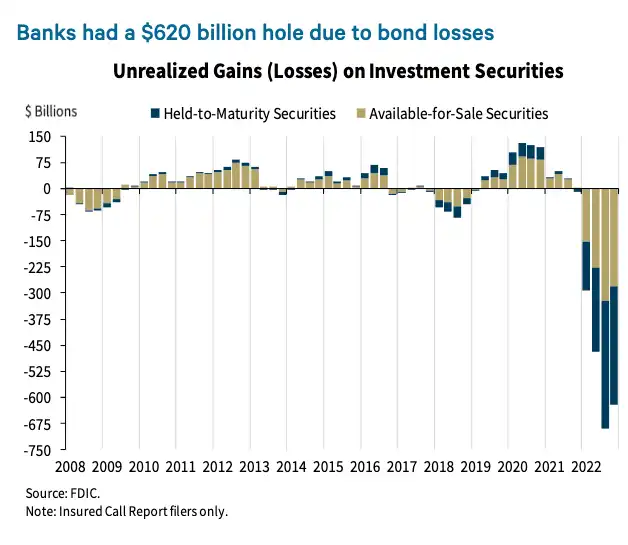
How can banks hide these huge unrealised losses from their depositors and shareholders? Banks hide losses by employing many legitimate accounting techniques. Banks that have made loans do not want to see their earnings fluctuate with the market value of their tradable bond portfolios. Otherwise, the whole world will see what they are up to. That could depress their share prices or force regulators to shut them down for violating capital adequacy requirements. Therefore, if the bank intends not to sell the bond before it matures, it is allowed to mark the bond as "held to maturity." This means they mark the bond with the purchase price until it matures. After that, banks can ignore unrealised losses regardless of the price at which the bonds trade on the open market.
Small banks are doing well. Instead of charging interest on customer deposits, they lend them to the US government at 1 to 2 per cent (UST) and to US home buyers at 3 to 4 per cent (MBS). That may seem small, but on tens of billions of dollars in loans, it's meaningful revenue. Thanks to these "great" earnings, bank shares soared.
KRE US -- SPDR S& P Regional Bank ETF
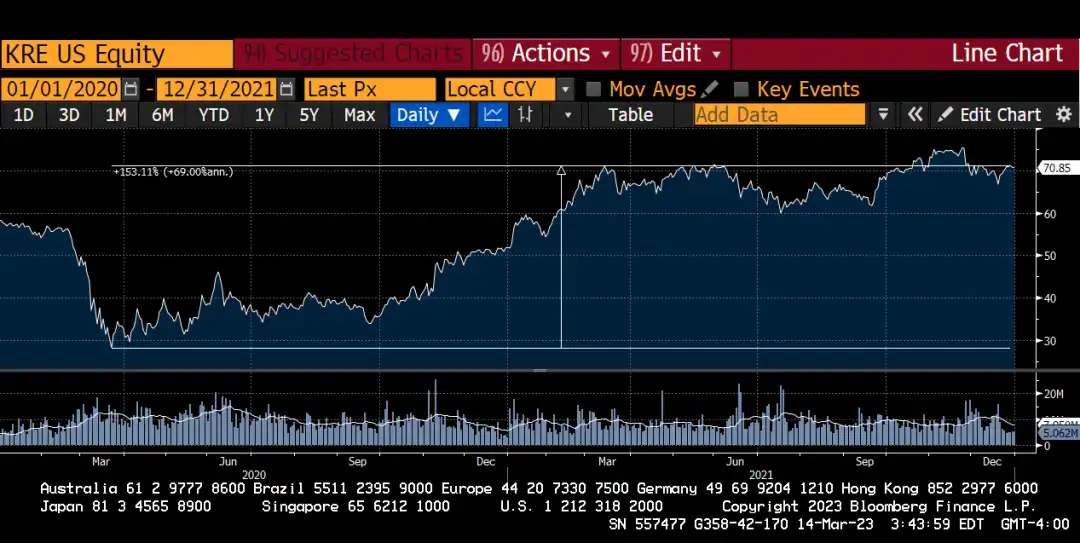
The ETF is up more than 150 percent from its pandemic low in 2020 through the end of 2021.
But then came inflation.
He's not Arthur Burns. He's Paul Volker
A short history lesson about a former Federal Reserve chairman.
Arthur Burns was chairman of the Federal Reserve from 1970 to 1978. Contemporary monetary historians are not impressed by Mr Burns. His achievement was to refuse to tackle inflation in the early 1970s.
Paul Volker was chairman of the Federal Reserve from 1979 to 1987. Contemporary monetary historians praise Mr Volker for his efforts to stamp out the inflation problems his predecessor faced. Mr Volker is described as brave and bold, while Mr Burns is described as weak and powerless.
Powell wants to be more like Volker than Burns. He was very concerned about his place in history. Powell is not in the job to get paid. He is probably a billionaire. He is all about cementing his position as a monetary reformer. That is why, when inflation rose to a 40-year high in the wake of the pandemic, he donned his best Volker and went into the Mariner Eccles building to do something big.
In late 2021, the Fed said inflation was a problem. Specifically, the Fed said it would begin to raise interest rates above 0% and reduce the size of its balance sheet. From November 2021 to early January 2022, risky asset prices peaked. The train of misery is ready to go.
This Fed tightening cycle is the fastest on record (ie, the Fed has raised interest rates faster than ever before). So 2022 is the worst year for bondholders in hundreds of years.
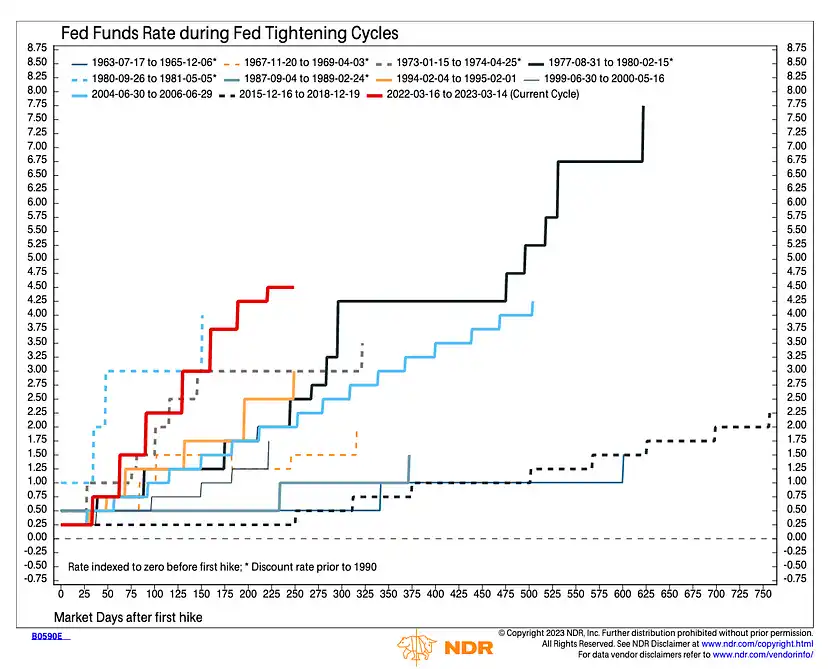
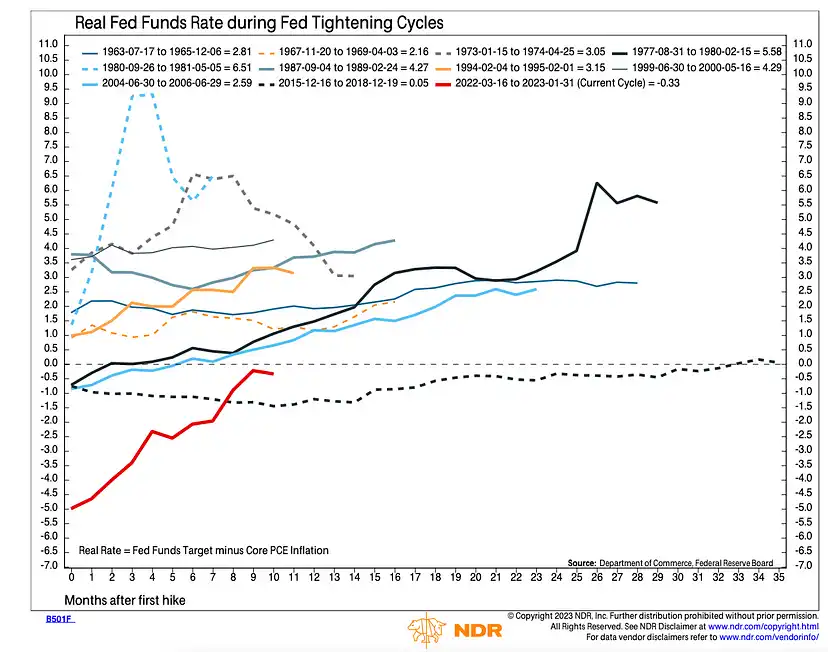
Powell felt he was doing what had to be done. The financial portfolios of the wealthy took a back seat to lower prices for most Americans (who had no financial assets at all). He is not worried about a hedge fund falling sharply for the year or bankers' bonuses being cut. So what... Eat the rich, the US economy is strong, unemployment is low. That means he can keep raising interest rates and dispel the notion that the Federal Reserve is only concerned with boosting financial asset prices to help the rich. What a hero!
But trouble is brewing in the banking sector.
insolvency
As a bank saver, you'd expect to get a higher rate on your money when the Fed raises rates. Wrong.
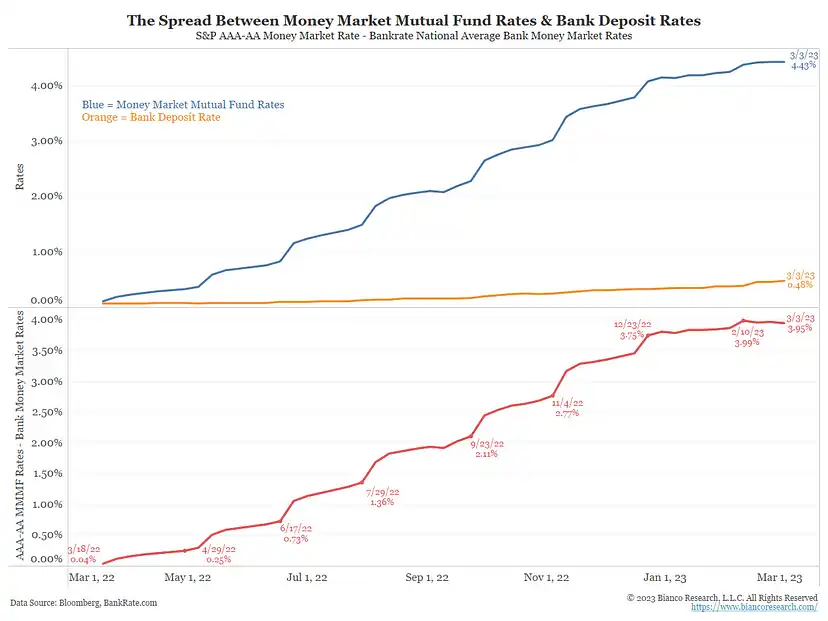
The chart above, from Bianco Research, shows that deposit rates significantly lag higher money market funds rates, which move in tandem with the Fed's policy rate.
The big "too big to fail" banks don't need to raise deposit rates because they don't really need deposits. They have trillions of dollars in excess reserves at the Fed. Moreover, their customers tend to be larger corporate customers whose deposits are sticky. The CFO of a Fortune 500 company is not going to give up JP Morgan for a regional bank based in a remote part of the United States just to earn a few extra basis points. Big companies also get other services from these big banks, such as cheap loans, in return for loyal depositors.
And those smaller banks can't raise deposit rates because they can't afford to. These banks pay lower interest rates on their Treasury and mortgage-backed securities than the current federal funds rate. This means that if they were to raise lending rates to match the Fed, they would have huge negative spreads. Instead, they just hope that depositors don't notice that they can earn an almost risk-free 5% return by withdrawing their money from the bank and investing it in a money-market fund. Clearly, this strategy is not working.
As a result, depositors fled small banks and found new homes in higher-yielding money-market funds.
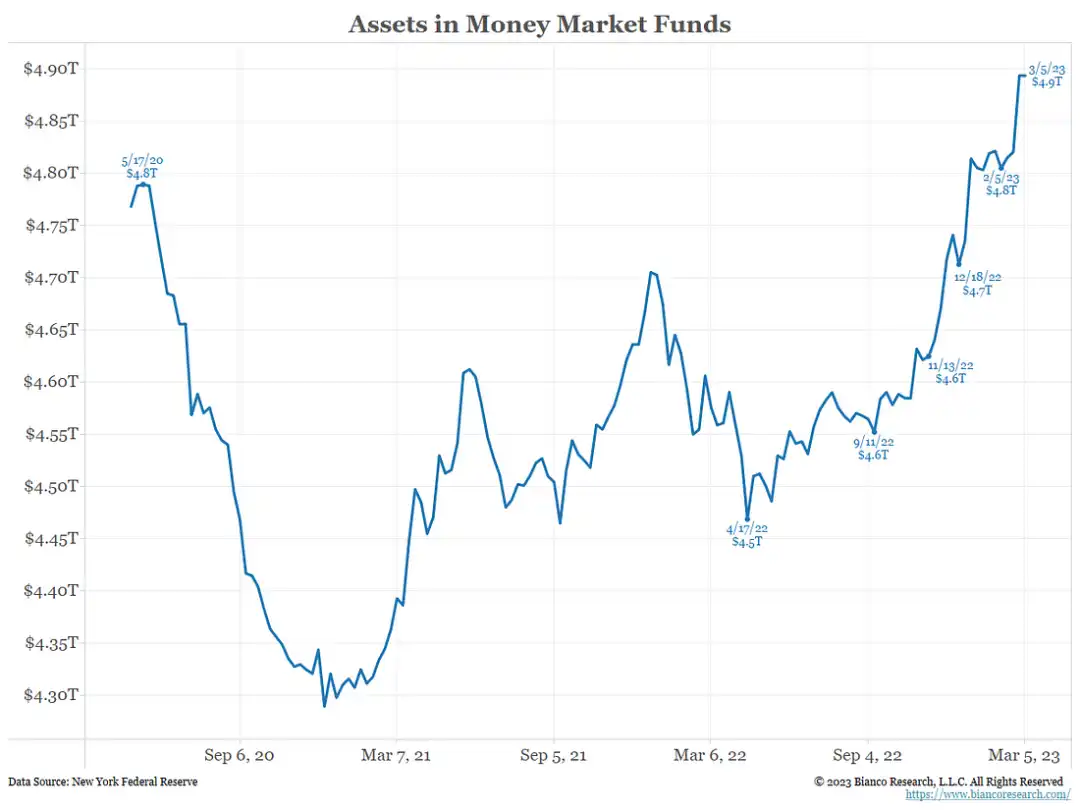
As deposits leave smaller banks, they have to sell the most liquid things on their balance sheets. Us Treasuries and mortgage-backed securities (MBS) are very liquid. However, because they were purchased in 2020 and 2021, the value of the bonds plunged when they were marketable in late 2022 or early 2023.
Game over
ps: "The canary in the coal mine" is a figurative metaphor referring to the first warning signal or sign in a dangerous or unstable environment.
The canary in the coal mine for banking is the failure of Silvergate. After becoming the most crypto-friendly bank, Silvergate went from a little-known California bank to the bank of choice for dollar banking services needed by all the largest trading platforms, traders, and cryptocurrency holders. Their deposit base ballooned and they invested depositors' money in the U.S. government, which is often one of the safest investments you can make. It's not like they're dealing with fly-by-night companies or individuals like Three Arrows Capital; They lent money to the richest and most powerful countries in the world.
Silvergate's cryptocurrency depositors decided to flee, and depositors didn't want to mess around and know if Silvergate was in any way contributing to (or even just aware of) suspicious and potentially illegal activity emanating from FTX. So they pulled out, and the bank had to sell its loans and bonds at a loss to pay the compensation. That's why Silvergate reported a staggering $754 million loss for 2022.
What happened next was a failed equity offering of SVBS. An equity offering is when a company works with an investment bank to sell shares to large institutional investors at a discount to the current market price.
The SVB share issue is notable because of the order in which it was executed. Goldman Sachs is both the bank bidding for SVB's underwater debt portfolio and co-ordinating the equity offering.
The question is, why did SVBS sell the bonds to Goldman before issuing the equity? Once an SVB sold the bonds, it had to recognise losses and was in clear breach of regulatory capital requirements. It must also disclose all this information to investors (i.e., people who might buy the shares). Why would you buy shares in a bank that, moments earlier, had announced huge losses and a potential breach of its capital ratios? Obviously they don't, and nobody does. After the rights issue fiasco, tech luminaries instructed their portfolio companies to immediately pull their money out of SVB, and days later, the bank collapsed.
The lesson of this sad tale is that the botched execution of the SVB rights issue drew further attention to unrealised losses on regional banks' balance sheets. Markets are starting to ask more questions. Who else could be in trouble?
As it turns out, problems similar to Silvergate and SVB exist throughout the U.S. regional banking industry. To summarize why these banks are in trouble:
1. Their deposit base swelled, lending money at a time when interest rates were at record lows.
2. As interest rates rose as the Fed raised policy rates, the banks had large unrealized losses on their bond and loan portfolios.
3. Depositors, hoping for higher interest rates than regional banks, began to leave and invest in higher-yielding products, such as money-market funds and short-term U.S. Treasury bills. Banks can't afford those losses because they can't pay depositors the federal funds rate because the interest they earn on average on their portfolios of bonds and loans is much lower than that rate.
4. The market always knew that this would eventually be a problem, but it took the failures of Silvergate and SVB to really realize the magnitude of the problem. As a result, every regional bank is now thought to be on its last legs.
Over the weekend, the world was watching how cryptocurrency and tech company deposits were affected by the Silvergate and SVB issues. Circle's USDC stablecoin also broke anchor, dropping below $0.90 due to its possible significant ties to Silvergate, SVB, and possibly Signature Bank. Many believe the issue is not about cryptocurrencies or technology, but about all banks that are not recognized as systemically important facing systemic problems.
So everyone knows that when the US markets open on Monday, many banks will be punished. Specifically, many fear there could be a nationwide bank run.
Emergency rescue
The Fed and the US Treasury did not let a good crisis go to waste. They designed a really elegant solution to solve some systemic problems. On top of that, they can blame poorly managed cryptocurrencies and technology-focused banks for having to step in and do something they would have done anyway.
Now, I'll detail the truly game-changing document that describes BTFP. (The references in the document are in bold and italics, with a detailed description of the actual impact below each reference.)
Bank term funding plan
The plan: To provide liquidity to U.S. depository institutions, each Federal Reserve bank would offer loans to eligible borrowers, using certain securities as collateral.
Borrower Eligibility: Any U.S. federally insured depository institution (including a bank, savings association, or credit union) or U.S. branch of a foreign bank that meets primary credit eligibility (see 12 CFR 201.4 (a)) may be eligible to borrow under this program.
It's pretty straightforward, you need to be a Bank of America to participate in the program.
Eligible collateral: Eligible collateral includes any collateral that qualifies as collateral purchased by the Federal Reserve Bank in open market operations (see 12 CFR 201.108 (b)), provided that the collateral is owned by the borrower as of March 12, 2023.
That means the financial instruments available as collateral under the program are largely limited to Treasury bonds and mortgage-backed securities. By setting an expiration date, the Fed limited the scope of the program to the total size of U.S. banks' holdings of Treasurys and mortgage-backed securities (about $4.4 trillion).
The amount of funding available: The amount of funding available will be limited by the value of the assets secured by the eligible borrower.
There is no limit to the amount provided. If your bank holds $100 billion in Treasurys and mortgage-backed securities, you can submit that total amount for financing using BTFPS. That means the Fed could theoretically lend to all the Treasuries and mortgage-backed securities held on U.S. banks' balance sheets.
The first two BTFP paragraphs are very important to understand. The Fed has just done $4.4 trillion of QE in a different way. Let me explain.
Quantitative easing is the process by which the Fed provides reserves to banks in exchange for the sale of their holdings of Treasury bonds and mortgage-backed securities. Under BTFP, instead of buying bonds directly from banks, the Fed prints money and lends against Treasuries and mortgage-backed securities that banks pledge. If depositors wanted $4.4 trillion in cash, banks would simply pledge their entire portfolio of Treasurys and mortgage-backed securities to the Fed in exchange for the cash, which would then be passed on to depositors. In both QE and BTFP, the amount of money the Fed creates and puts into circulation is growing.
Interest Rate: The interest rate for the term of the loan will be the one-year overnight indexed swap rate plus 10 basis points; The interest rate will remain unchanged from the date the loan is made.
Collateral valuation: The collateral will be valued at par value. The margin will be 100% of par value.
Fed funds are priced according to the 1-year interest rate. Since short-term interest rates are higher than long-term rates, this means banks will bear negative interest rates for most of the loan period. Bad though losses are, banks can swap undervalued bonds rather than admit losses and go bust. Everyone gets to keep their job, except for the unfortunate ones like Silvergate, SVB, and Signature.
Loan duration: Qualified borrowers can get loans for up to one year.
Program duration: Qualified borrowers can apply for loans under the program until March 11, 2024.
The program is supposed to last only one year. When has a government ever given back the power that the people have given them in a time of crisis? The programme will almost certainly be extended preventively; Otherwise, there will be enough turmoil in the markets about the need to print money that the programme will be extended anyway.
The impact of BTFP
It's bigger than the epidemic
The Federal Reserve printed $4.189 trillion in response to the pandemic. With BTFP, the Fed implicitly printed $4.4 trillion. During the pandemic, the price of bitcoin rose from $3,000 to $69,000. How will it behave this time?
Banks are bad investments
Unlike the 2008 financial crisis, this time the Fed won't bail out banks and let them participate in the rally. Banks have to pay a one-year interest rate. The 1-year rate is much higher than the 10-year rate (also known as the inverted yield curve). Banks borrow short-term from depositors and long-term from governments. When the yield curve is inverted, the trade must lose money. Similarly, any bank using BTFP would have to pay the Fed more than the deposit rate.
The 10-year Treasury yield minus the 1-year Treasury yield
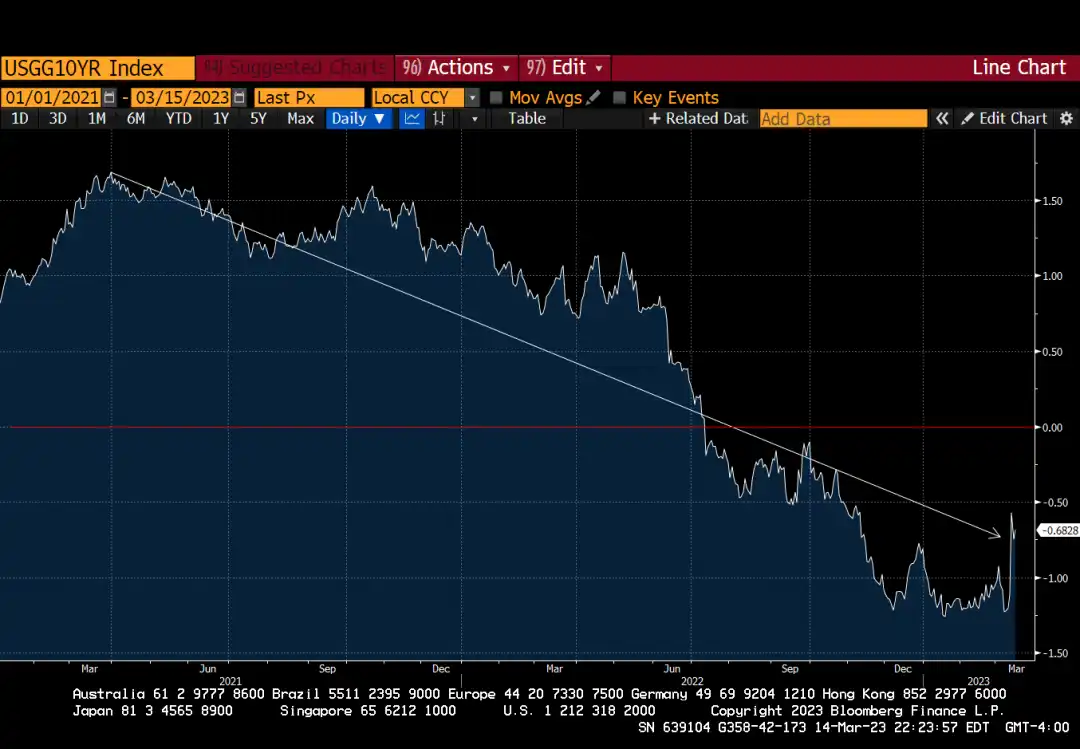
Banks will be negative on earnings until either the yield curve skew again or short-term interest rates fall below the mix of their loan and bond portfolios. The BTFP does not solve the problem that banks cannot afford the high short-term interest rates that depositors can get on money-market funds or Treasury bonds. Deposits would still flow to these vehicles, but banks could borrow from the Fed to fill the gap. From an accounting point of view, the bank and its shareholders will lose money, but the bank will not go bankrupt. Until their balance sheets are repaired, I expect bank stocks to severely underperform the general market.
Soaring house prices
The 30-year mortgage rate minus the one-year Treasury yield
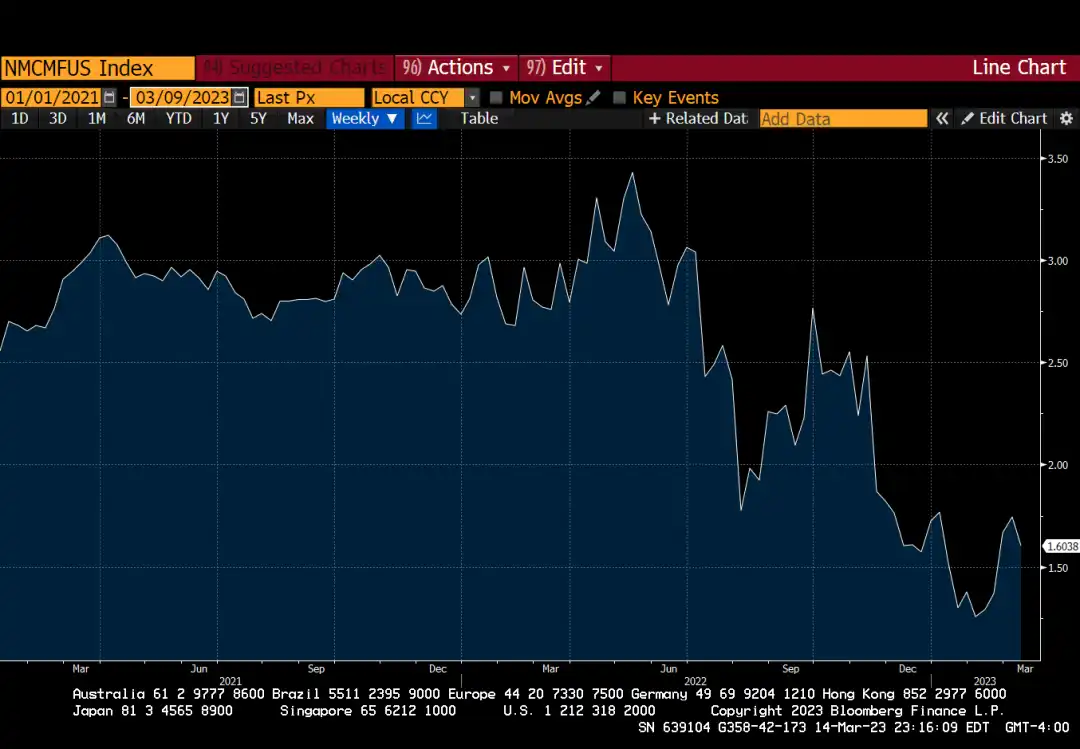
Buying mortgage-backed securities will still be profitable for banks because the spread over one-year rates is positive. As banks arbitrate the Fed, interest rates on mortgage-backed securities will converge to one-year rates. Imagine that the bank takes in $100 of deposits in 2021 and buys $100 of Treasury bonds. By 2023, the value of the debt had fallen to $60, making it insolvent for banks. Banks use BTFPS to borrow from the Fed and return their Treasuries to the Fed and receive $100, but must pay the Fed 5% interest. The bank now buys a government-guaranteed mortgage-backed security with a yield of 6%, making the bank a risk-free profit of 1%.
Mortgage rates will move in tandem with one-year rates. The Fed has enormous control over short-end yields. It can basically set mortgage rates wherever it likes and never have to "buy" a single mortgage-backed security again.
As mortgage rates fall, home sales will recover. In the United States, as in most other countries, real estate is an important industry. The increase in sales will help increase economic activity as financing becomes more affordable. If you think property is about to become more affordable, you need to think again. The Fed is back, pushing up house prices again.
The dollar gets stronger and stronger
If you have access to a U.S. bank account and the Federal Reserve has just guaranteed your deposits, why put your money in another banking system that doesn't have a central bank guarantee? Outside money will pour into the United States, which will strengthen the dollar.
As this process progresses, all other major developed country central banks must follow the Fed's lead and implement similar guarantees to stem the outflow of bank deposits and weaken their currencies. Central banks such as the European Central Bank, the Bank of England, the Bank of Japan, the Federal Reserve Bank of Australia, the Bank of Canada, the Swiss National Bank and others are likely to be delighted. The Fed has just implemented an unlimited form of money printing, so now they can do the same. The problems facing the U.S. banking system are similar to those facing other banking systems. Everyone has the same deal, and now - under Sir Powell's leadership - every central bank can respond with the same measures without being accused of triggering the hyperinflation of fiat money.
A few nights ago, Credit Suisse effectively failed. The Swiss National Bank had to provide SFr50 billion in covered loans to stem the credit drain. One large bank in each major advanced western country is expected to come close to failure, and I think in each case the response will be a blanket deposit guarantee (similar to what the Fed does) to avoid contagion.
The road to infinity
As outlined in the BTFP document, the program only accepts collateral that appears on banks' balance sheets before March 12, 2023, and ends a year later. But as I mentioned above, I don't believe the program will end, and I also think the amount of eligible collateral will be relaxed to cover government bonds that exist on the balance sheet of any authorized U.S. bank. How do we go from limited support to unlimited support?
Once people realise that there is no shame in using BTFPS, the fear of bank runs will disappear. At that point, depositors will stop stuffing their money into too-big-to-fail banks like JPMS and start withdrawing and buying money market funds (MMFS) and Treasury bills with a maturity of two years or less. Banks won't be able to lend to businesses because their deposit base is flowing into Federal Reserve repo facilities and short-term government bonds. That would be extremely depressing for the United States and all other countries with similar programs.
Government bond yields will fall from all sides. First, the fear that the entire U.S. banking system would have to sell their entire inventory of U.S. government debt to repay depositors disappeared. This has removed significant selling pressure in the bond market. Second, markets will start pricing in deflation because the banking system cannot regain profitability (and thus create more lending) until short-term interest rates fall enough to lure depositors back through rates that compete with repo facilities and Treasury bills.
I expect the Fed to either recognize this outcome early at its upcoming March meeting and start cutting rates, or a severe recession will force it to reverse course a few months later. The 2-year Treasury yield has fallen more than 100 basis points since the crisis began. The markets are crying out for bank-system-supported deflation, and the Fed will finally listen.
With banks once again profitable and able to compete with governments again to lure depositors back, banks will be in the same position as they were in 2021. That is, deposits will grow and banks will suddenly need to start lending. They will start underwriting loans for companies and governments at low nominal yields. Third, they think inflation isn't there yet, so they don't worry about future interest rate increases. Does this sound familiar?
Then came March 2024. The BTFP program is about to expire. But right now, things are worse than they will be in 2023. The combined size of banks' portfolios of bonds and securities underwritten by low interest rates to companies and governments is larger than it was a year ago. If the Fed does not extend the life of the program and expand the nominal amount of eligible bonds, then the same run of banks we are seeing now could happen again.
Since the Fed has no appetite for a free market in which banks fail because of bad management decisions, it can never remove their deposit guarantees. Long live BTFP.
While I'm sure this is anathema to all Ayn Rand followers (like Ken Griffin and Bill Ackman), the continuation of BTFP solves a very serious problem for the U.S. government. The U.S. Treasury has a lot of debt to sell, and fewer and fewer people want to own it. I believe the BTFP will be expanded so that any eligible securities (primarily Treasuries and mortgages) held on the balance sheets of US banks can be exchanged for freshly printed dollars at the one-year rate. This gives banks confidence that they can always buy government debt in a risk-free manner as their deposit base grows. Banks no longer have to worry about what will happen if interest rates rise, their bonds lose value and their depositors want their money back.
With the introduction of the newly expanded BTFP program, the U.S. government can easily finance a larger deficit because banks will buy whatever bonds are available. Banks don't care about the price because they know the Fed has their back. Investors who focus on real returns and price will scoff and not continue to buy trillions of dollars of U.S. government debt. The Congressional Budget Office estimates the deficit will be $1.4 trillion in 2023. The United States is also waging war on multiple fronts: the war on climate change, the war on Russia and the war on inflation. The war is characterized by inflation, so the deficit is expected to rise further. But this is not a problem because banks will buy all the bonds that foreigners refuse to buy.
This allows the US government to run the same growth strategy used by Japan, Taiwan and South Korea. The government implemented policies to ensure that the interest rate paid to savers was lower than the nominal GDP growth rate. The government can then re-industrialise by providing cheap credit to any sector of the economy it wants to promote, and make a profit. This "profit" could help the US government reduce its debt-to-GDP ratio from 130% to a more manageable level. While everyone may cheer growth, the entire public is actually paying an implicit inflation tax at the rate of Nominal GDP - government bond yields.
Finally, this solves an image problem. If the investing public thinks the Fed is spending money on the government, they might revolt and sell long-term bonds. 10-year term). The Fed would be forced to step in and repair long-term bond prices, an action that would mark the end of the western financial system in its current form. The Bank of Japan faced this problem before and implemented a similar program in which it offered loans to banks to buy government bonds. In this case, the bonds never appear on the central bank's balance sheet, only the loans, which in theory must be repaid by the banks but which, in practice, roll over permanently to the next instalment. Markets can be grateful that central banks are not moving towards 100% ownership of the government-bond market. Long live the free market!
WTI oil futures in the previous month
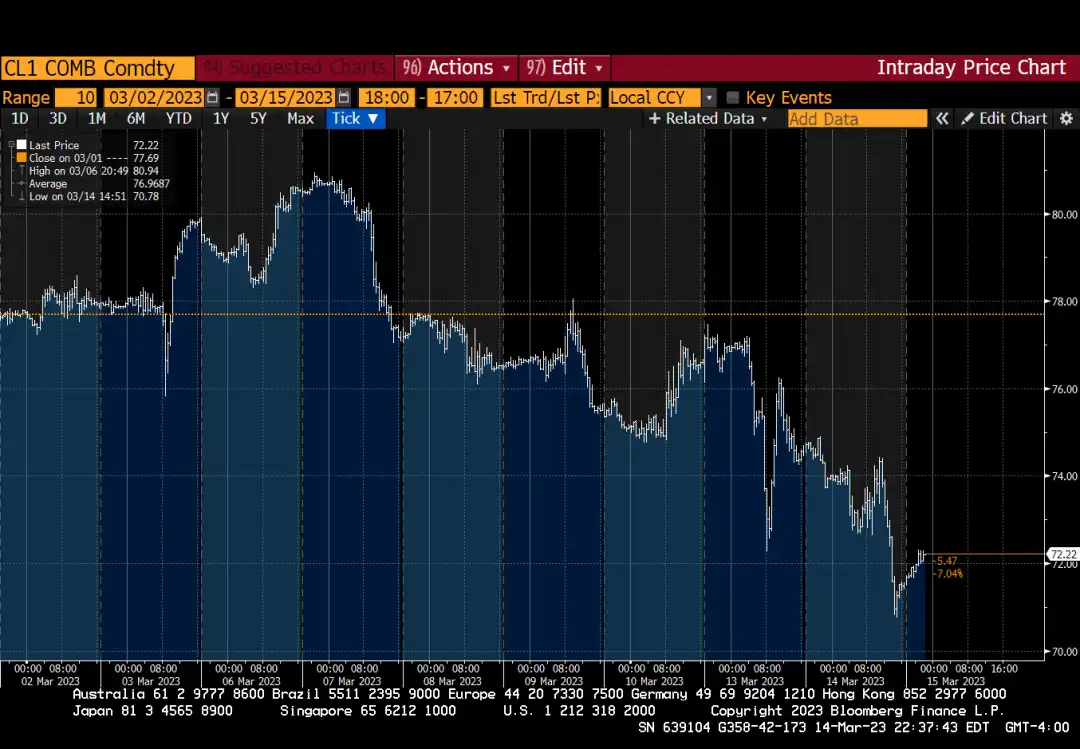
The broad fall in oil and commodity prices suggests that markets believe deflation is imminent. The reason for deflation is that little credit is being extended to businesses. Without credit, economic activity declines, and so the amount of energy needed decreases.
Falling commodity prices will help the Federal Reserve cut interest rates because inflation will fall. The Fed now has a reason to cut rates.
Capital outflow system
For the Fed, the most worrying outcome is people moving capital out of the system. After guaranteeing deposits, the Fed doesn't care if you move your money from SVBS into higher-yielding money market funds. At least your capital is still buying government debt. But what if, instead, you buy an asset that is not controlled by the banking system?
Assets like gold, real estate, and (obviously) bitcoin are not liabilities on someone else's balance sheet. If the banking system fails, these assets will still have value. However, these assets must be purchased in physical form.
By buying a platform-traded fund (ETF) that tracks the price of gold, real estate or bitcoin, you're not escaping the vicious effects of inflation. All you're doing is investing in the liabilities of one member of the financial system. You own a claim, but if you try to cash in your chips, you'll get legal tender notes, and all you're doing is paying another trustee's fees.
It is very difficult for Western economies, which are supposed to practise free-market capitalism, to impose widespread capital controls. For the US, it is particularly difficult because the world uses the dollar because it has an open capital account. Any explicit ban on various exits from the system would be seen as an imposition of capital controls, which would make sovereigns even less willing to hold and use dollars.
This is a controversial point. Rather than outright banning certain financial assets, the government is likely to encourage investment vehicles such as ETFs. If everyone panics about the inflationary impact of BTFP and puts their money into GBTC (Grayscale Bitcoin Trust), it will have no effect on the banking system. You must use dollars to get in and out of the product. There is no escape for you.
Be careful what you wish for. A true U.S.-listed Bitcoin ETF would be a Trojan horse. If such a fund were approved and sucked up a large supply of bitcoins, it would actually help maintain the status quo rather than give people financial freedom.
Also, watch out for products where you "buy" bitcoins but can't withdraw your "bitcoins" to your own private wallet. If you can only get in and out of the product through the legal banking system, then you have achieved nothing. You're just a fucking commission provider.
The beauty of bitcoin is that it's invisible. It has no external form of existence. You can remember the private key to Bitcoin, and whenever you want to spend money, you just use the Internet to make a transaction. Owning a lot of gold and real estate is heavy and obvious. Ostentatious saving and the associated display of wealth can easily invite looting by other citizens, or even worse, your own government.
Clearly, fiat money has its uses. Use it to its advantage, spend fiat money, stock up on cryptocurrencies.
To Da Moon
When I talked to the hedge fund man, I noticed how bullish I was on Bitcoin. This is the ultimate game. The yield curve control is already in place. BTFP brings unlimited currency printing around the world......
The media may also push the narrative that the banking crisis was caused by banks taking legal deposits from cryptocurrency people. It was so ridiculous that it made me laugh out loud. It is ludicrous to suggest that the crypto industry is somehow responsible -- banks' job is to handle legal dollars -- for accepting legal dollars from entities involved in encryption, following all banking rules, lending those legal dollars to the most powerful country in human history, and subsequently failing to repay depositors. This happened as the Central Empire raised rates and blew up the banks' bond portfolios.
Instead, cryptocurrency has once again proved to be a smoke alarm for the fetid, wasteful, fiat currency-driven Western financial system. On the rise, cryptocurrencies suggest that the West has printed too much money in the name of the pandemic. In the fall, crypto Free Market soon exposed a large number of overleveraged scammers. Even the diverse family of FTX does not have enough love to overcome the swift sanction of the crypto free market. The stench of these repulsive individuals (and the people they do business with) drives depositors to move their hard-earned money to safer (and supposedly more reputable) institutions. In the process, it has shown everyone the damage the Fed's policies have done to the US banking system.
For my portfolio, I've pretty much stopped trading stocks. What's the point of that? I usually buy and hold and don't adjust my position frequently. If I believe what I write, then I am setting myself up for failure. If there is a short-term trading opportunity and I think I can make some quick money and buy more Bitcoins at a profit, then I will do so. Otherwise, I would liquidate most of my stock portfolio and move it into cryptocurrencies.
If I own any ETFs linked to precious metals or commodities, I will sell them and buy and store commodities directly whenever possible. I know this isn't practical for most people, but I just want to make sure how deep my beliefs are.
The only exception to my disdain for stocks are companies related to nuclear power. The West may scoff, but rising nations are looking for cheap, abundant energy to provide a good life for their citizens. Sooner or later, nuclear power will create the next higher step in global growth, but individuals can't store uranium, so I'm doing nothing with my Cameco holdings.
I have to make sure my real estate portfolio is diversified across jurisdictions. You have to live somewhere, and if you can fully own your home or have as little debt as possible, that's the goal. Likewise, if you don't have to be attached to the legal financial system, so much the better.
Cryptocurrencies are volatile, and most goods and services require payment in fiat currency. And that's okay. I will hold the cash I need to earn the highest short-term yield possible. Right now, that means investing in dollar money market funds and holding short-term Treasury bonds.
My cryptocurrency + barbell portfolio with long term volatility will remain unchanged. Once I'm done readjusting, I have to make sure I adequately protect my downside risk. If I don't have enough exposure to instruments that do well if the government decides to unwind the leverage embedded in the system (rather than keep piling on more), I have to increase my exposure to my favorite volatility hedge fund. Beyond that, the only major risk to my strategy as a whole is if a new source of energy is discovered that is significantly denser than hydrocarbons. Of course, such energy already exists. It's called nuclear power. If policymakers were prodded by their citizens to actually build the infrastructure necessary to support a nuclear-powered economy, then all that debt could be paid off through an amazing burst of economic activity. At that point, I won't be making money on my cryptocurrencies or volatility hedges. But even if there is the political will to build this infrastructure, it will take decades to complete. I will have plenty of time to realign my portfolio for the nuclear age.
This is the most important financial event since the pandemic. In subsequent articles, I will assess whether the impact of BTFP matches my predictions. I realize that my extreme belief in bitcoin's upward trajectory could be wrong, but I have to judge events on their merits and adjust my portfolio when I find out I'm wrong.
The outcome was known in advance. YCC is dead, long live BTFP!
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles