Curve's battle to "wrap" liquidity. Is Yearn the winner?
原文标题:《 Curve 流动性的「包装」之战一览,Yearn 或成最终赢家? 》
DeFi Made Here
Deep Tide TechFlow
Curve Finance's veToken model allows users to lock in $CRV for up to 4 years, receive management fees (paid in stablecoins), and allow them to vote in favor of CRV allocations for the select pool.
Those seeking liquidity agreements may choose to bribe veCRV holders to funnel CRV distributions to their pools. This is another source of income for veCRV holders in addition to management fees.
But locking up a CRV for four years is not a very attractive option for the holder.
What's the solution?
Choose to Wrap your liquidity:
From Convex Finance;
sdCRV from Stake DAO;
yCRV from Yearn
Liquidity packaging allows CRV holders to collect fees or bribes without the need to lock in for four years and provides an opportunity to exit the position.
What is the difference between them?
cvxCRV
By pledging the cvxCRV, you earn 3crv fees plus the raised CRV earnings of the Convex LP and a 10% share of the CVX Token.
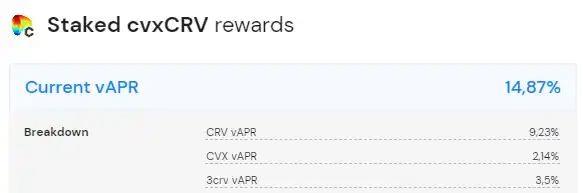
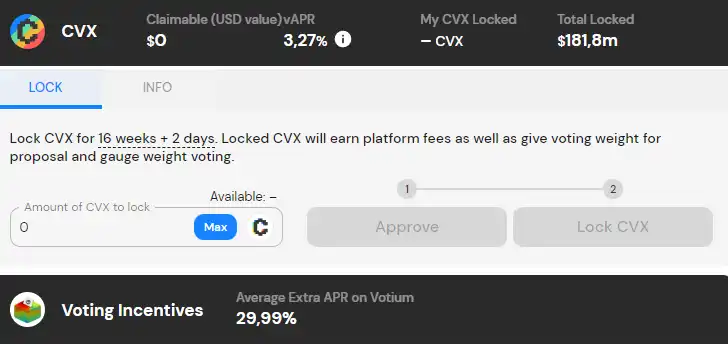
And the proceeds of bribery (votes that can be sold) are distributed to CVX who are locked up for voting.
Therefore, the normal income of a veCRV (fees + bribes) is divided between cvxCRV and CVX.
sdCRV
The sdCRV distributes the 3CRV fee and retains the voting rights with the pledgee.
Voting rights can be entrusted to StakeDAO, which combines market and OTC bribes for the best return.
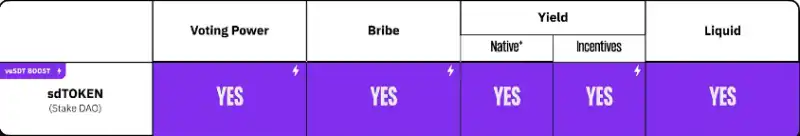
Or users can access bribes on Stake DAO directly from Paladin or Votium Protocol.
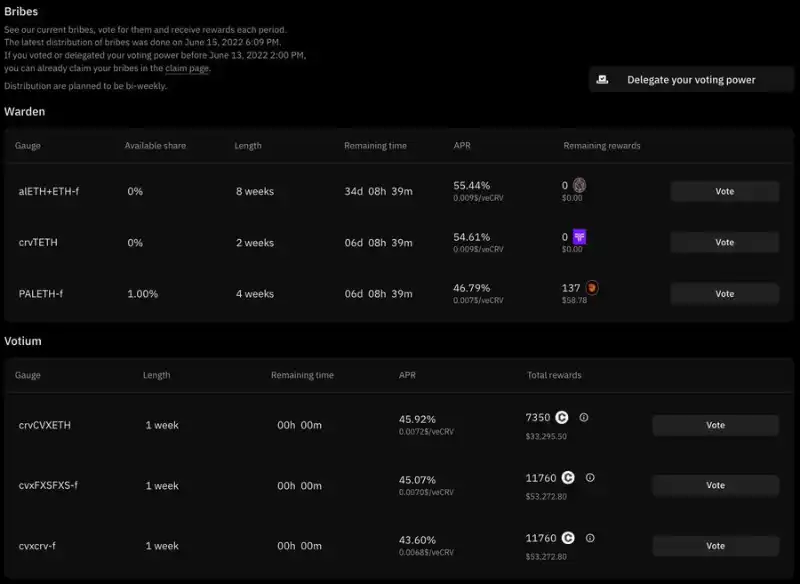
由于 StakeDAO 不在 sdCRV 和原生 Token 之间分割贿赂和管理费用,因此质押 APR 明显更高。
The pledgee receives 3CRV, CRV and a reward that is converted into SDT for bribery.
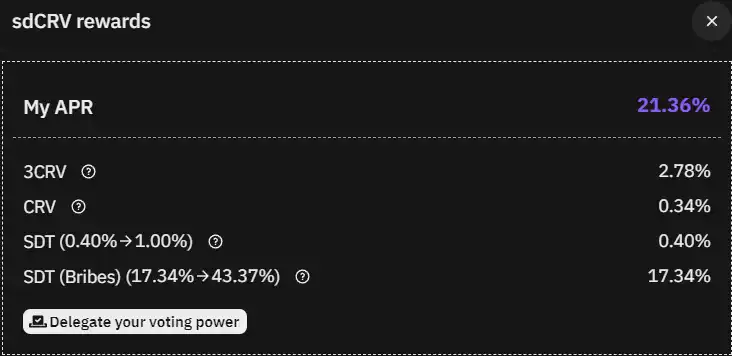
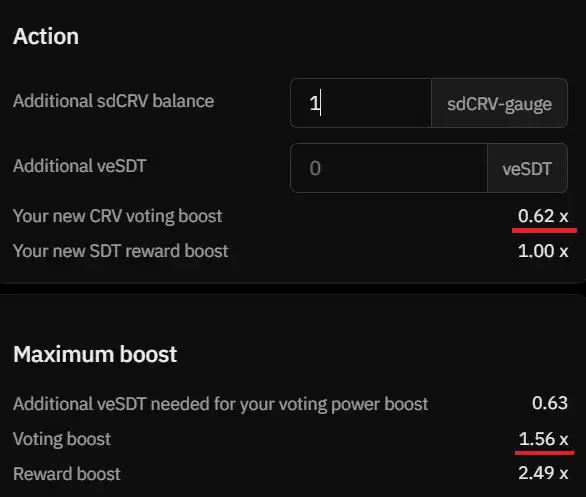
然而,为了获得最高的年利率,用户必须通过锁定原生 Token SDT。
In the case of veSDT elevation, sdCRV pledgor's voting power will be increased by 0.62 times and can be increased to 1.56 times based on veSDT balance and total veSDT pledgor.
yCRV
Of all the packages, pledged yCRV can get the highest yield.
However, the yield will fall because there are still rewards left over from traditional yvBOOST donor contracts.
Moreover, a quarter of all YCRVs are owned by the Treasury, which boosts the returns of all yCRV pledges.
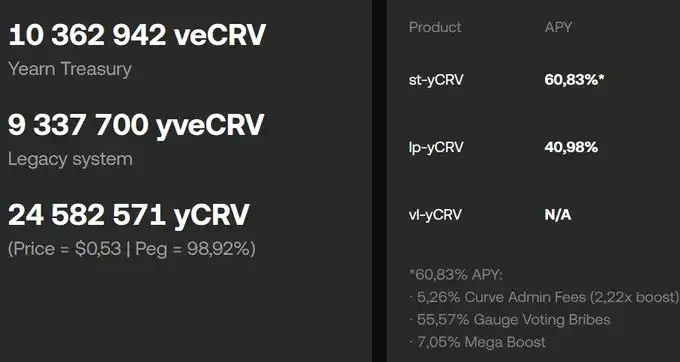
st-yCRV provides a "once and for all" user experience, and revenue comes from two sources:
Management feeThe management fees earned are automatically compounded into more.
bribe: 1 st-yCRV = 1 veCRV voting rights will be sold on the bribe market to further enhance earnings.
Unlike sdCRV, st-yCRV holders give up their voting rights, so the agreement cannot use it to vote for Curve.
vl-yCRV has voting rights and is in the final stages of development, but it will remove fees and bribes in favor of st-yCRV.
What are the trade-offs of packaging this liquidity?
Agreement fee
Voting right
Protective hook
The agreement fee is charged for the services provided by the Agreement (deducted from the displayed APR) :
cvxCRV 0%
sdCRV 16%
yCRV 10%
Voting rights:
The cvxCRV does not offer voting rights, nor does it share the proceeds of bribery;
yCRV does not offer voting rights but shares the proceeds of bribery;
The sdCRV provided voting rights and bribery income, but reduced it in favor of the veSDT pledgor.
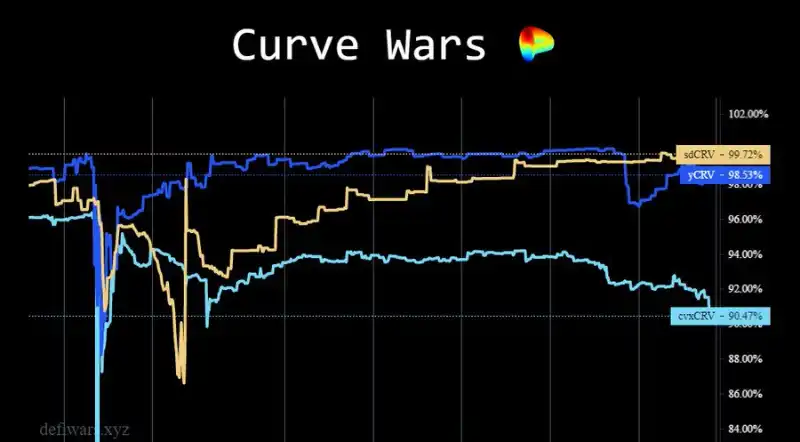
To maintain the hooks, all protocols direct the CRVS to their respective LPs.
在挂钩价格低于 0.99 时,Stakedao 会用贿赂收入购买 sdCRV 并分配给质押者(否则他们用从市场上购买的 SDT Token 支付)。
What is the best way to play CRV liquidity packaging?
首先,我必须说,我不拥有任何 CRV 或其包装物,我一直看跌 CRV Token 和终身现金流。
Although about 50% of CRVS are locked up forever, it still lacks the incentive to buy more than CRV emissions.
If all CRVS are locked in, yields will be heavily diluted.
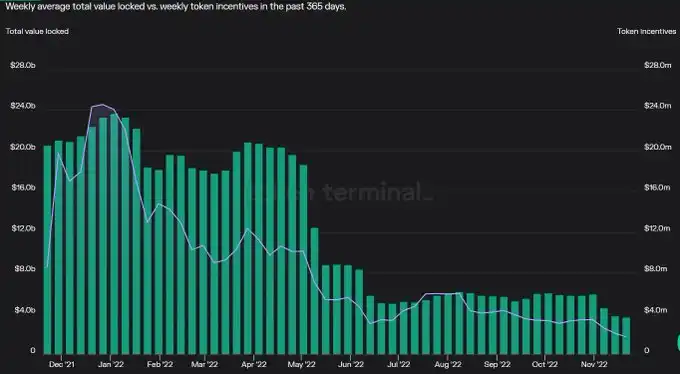
Since the price of CRV drops along with the TVL in Curve Finance, so does the value of the bribe.
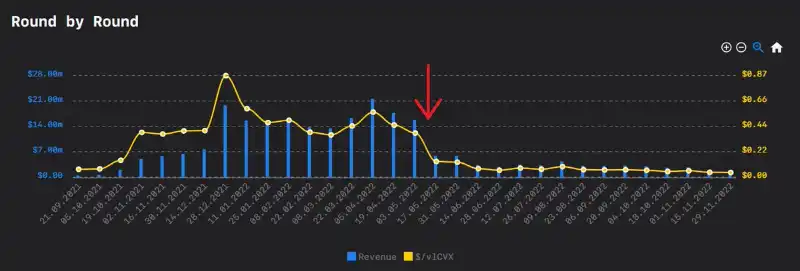
However, with the introduction of crvUSD, I see the potential of Curve. It could drive more volume and TVL back on the platform.
But only after the actual deployment will we see how it plays out.
In my opinion, yCRV is winning the war for Curve Liquidity packaging because it offers the highest revenue and simplest user experience.
If some users have veSDT, they may find the sdCRV solution more attractive because it votes to boost all user liquidity lock-in simultaneously:
sdCRV
sdBAL
sdFXS
sdYFI
sdANGLE
In this case, the absolute loser is cvxCRV. It has the lowest yields, no voting rights or bribe income, weak hook-ups and so on.
I expect the cvxCRV to depreciate further until it reaches equilibrium with the yCRV yield.
Convex's other problem is that it is unlikely that anyone will mint a new cvxCRV in the foreseeable future - there are 50m "cheap" ones on the market.
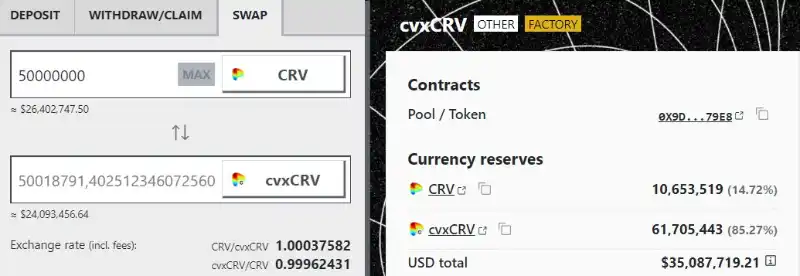
This means that the Convex's total ownership (%) in veCRV supplies is likely to be reduced further.
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles