The NFT-Fi Summer led by Sudoswap is here?
Original title: "IOSG Weekly Brief | NFT-Fi Summer led by Sudoswap is coming? #139"
Original source: Bryan, IOSG Ventures
This article will discuss the NFT-FI direction around NFT mortgage loans and derivatives have some interesting subdivision tracks/protocols, as well as current bottlenecks and possible future developments.
NFT AMM
The application scenarios of NFT AMM are mainly divided into blue-chip NFT and long-tail NFT. For blue-chip NFTs, one step before entering the AMM is to fragment them first.
NFTx
NFTx is an old NFT fragmentation protocol , the main reference is the old defi’s gameplay, that is, using the amm mechanism to provide liquidity mining after fragmentation, and Floor Dao provides a certain liquidity solution for fragmented NFTs, allowing users to use erc- 20 NFTs are converted into floor tokens, with high apy as rewards, the basic logic is consistent with the olympus dao of defi2.0. It is indeed a use case for adding erc 20 NFT, but it is not sustainable. Fragmented NFT will be conducive to price discovery. For example, the floor price on the NFT secondary market tends to be consistent with the price of NFT fragments circulating in amm. For example, if the transaction price of fragmented NFT is lower than the secondary trading market such as opensea, arbitrageurs can buy a complete NFT fragment from amm and redeem the NFT from the vault, and then sell it in the secondary trading market to achieve risk-free arbitrage.
Sudoswap:
Because of the direct transaction It is the entire NFT, and its positioning is closer to the secondary market such as opensea and superRare. The difference is that it can provide instant liquidity that is not available in the secondary market. Through the linear/exponential bonding curve setting (more curves will be introduced in the future to match different trading needs) to ensure that traders can know the established trading profits, and Have an instant trading experience. The pricing methods of the same NFT series are different, and risk-free arbitrage within the agreement can be achieved. The current traction is pretty good, the platform has reached 100,000 NFT transaction volume, and TVL is showing a good upward trend. A concern is mainly UX, because it is permissionless. At present, the same NFT series can have as many as 200+ pools, and the depth of each pool is different, and some depths are only single digits. Such liquidity dispersion may hinder this A possible bottleneck for the further development of the protocol. In addition, most of the NFTs traded on the platform are long-tail assets, and the penetration rate of series with high entry barriers such as blue chips is low.
Comments:
We believe that the main application scenario of the nft fragmentation protocol is in the blue-chip nft with a high floor price, which reduces the user entry threshold and improves liquidity through fragmentation. For long-tail non-blue-chip nft, its floor price is relatively lower, and there is no need for further fragmentation, and it can be traded directly. Although the transaction mode of both is AMM, the target NFT is not the same.
Is Constant product Amm an appropriate transaction model? constant product (x*y=k) is a common model in erc-20 swap (Uniswap, Bancor), but the uncompensated loss of LP is proportional to the volatility of the assets that provide liquidity, that is Say that the greater the asset price volatility, the higher the LP's IL. For fragmented nft, its price volatility is directly proportional to spot nft, so for LP, its IL is also a big risk exposure. (nftx has designed a new staking mode to reduce IL in this scenario—inventory staking, but it cannot fundamentally improve the problem of still existing IL). Currently, the most mainstream innovations in the market are bonding curves like sudoswap, which ensures that price fluctuations in the same pool are independent of the number of NFTs in the pool, and fixes price slippage to promote a better trading experience. The author's personal point of view is that AMM is one of the ways to improve liquidity/capital efficiency (mainly to promote the price discovery of NFT near the floor price), but AMM is not a suitable trading model.
NFT as collateral lending
In addition to direct In addition to trading NFT, lending agreements using NFT as collateral are also one of the means to promote NFT liquidity. NFT lending is mainly divided into two models: P2P/P2pool. P2P is the so-called peer-to-peer transaction, one borrower for one lender. The mode of P2Pool is that multiple lenders provide assets, not for a single borrower. The distinctive gameplay in P2P lending:
Flowty:
The lending agreement on the flow chain focuses on the pfp NFT collateral that is different from other chains, mainly including NBA Top Shot and Ballerz. The co-founders are early participants in nba top shot, and the platform is also more focused on A lending project for sports NFT scenes. One difference lies in its collateral—the brand effectiveness/events of nba top shot itself. For example, nba top shot regularly holds challenges. Participants can use their NFT portfolio to participate in challenges and get rewards. Flowty can help participants unlock additional funds At the same time, go to buy the required NFT. At the same time, there are a series of third-party platform references on the flow chain, such as the ranking system Moment RANKS just mentioned, and other analytical platforms such as Own the Moment (including historical sales data, price forecasts, trends), etc. , to help the lender to better judge whether to provide loans to the borrower. In general, there are many ways to play but the scalability is limited, and the ceiling depends on the flow/nba top shot ecology.
NFTfi:
NFT P2P Lending It is also the platform with the highest depth of pfp series Nft P2P lending and the best user experience on the market. In April of this year, the open loan positions reached 2k+, far exceeding other similar competing products. Some interesting findings: High-value NFTs, such as BAYC/Punk, generally have a longer duration - ranging from 30/90 days. The LTV of these high-value NFT series is also relatively high - (past month: BAYC-77%, Punk-53%, MAYC-58%, the collateral price is calculated according to the average transaction price in the past 30 days). For the general pawn shop LTV of 25-30%, it can be concluded that the barrier power of blue-chip Nft in the lending market is still relatively high. What is more friendly to the lender is that the loan history of the borrower will be displayed (such as the amount lent out, and whether there has been a default record, etc.), and other reference data include the floor price of the NFT series and the NFT by upshot/NFTBank The value estimates given are the basis to help the lender make reasonable judgments.
Exploring the comments generated by the P2P lending model:
P2P basic terms mode: The standard LTV of ntf P2P lending is close to the pawn shop in real life, fluctuating between [25-50%]. And the longer the Duration, the higher the risk of the lender, so short-term + low LTV is a more suitable choice for NFT P2P.
There are two interesting findings:
a. Lower, about 10% in quantity. There are also tiered differences in default rates among blue-chip NFTs. For example, bayc, punk, and mayc, which have the highest loan volume, have default ratios of about 1%, 3%, and 5% respectively. And blue chips with large price fluctuations, such as azuki, have a default rate of 30%. But this further shows that for blue-chip Nft loans, borrower is more about holding, rather than defaulting (that is, using the platform to cash out).
b. APY and duration data can also explain the difference in value preservation between different blue-chip NFT series in the eyes of lender. For example, the apr of punk is lower than that of other NFTs (14% on average, around 10% even in the recent period with severe fluctuations, while relatively speaking, the apy of BAYC has reached 40%), and the duration utilized (real repayment time/regulation repayment time), indicating that punk's lender and borrower have a higher degree of recognition for punk's asset preservation - even though the historical floor price of bayc is more stable than punk.
Development bottleneck:
a. terms- one of the current P2P protocols So the efficiency is low, the reason is that the process of reaching a deal is a process of multiple bids/counter-offers (an offer is valid for 7 days), how to formulate terms more accurately/quickly will be a P2P protocol that needs to be considered < br>
b. For some high-net-worth NFTs, due to their high risk, they need to rely on some liquidity solution providers such as metastreet to complete the loan.
P2Pool:
BendDAO: It is the mainstream NFT P2Pool loan on the market protocol. The gameplay is simple and clear, the lender lends eth, and the borrower mortgages the blue-chip NFT. The development is very fast, there are already 830 borrowers (NFT-fi has 1200+), considering such a number is only a few months after its launch. The reason for the rapid development is also very simple - the liquidity of P2Pool is higher than that of P2P, the mortgaged NFT is close to the floor price, and the agreement has a cold start subsidy in the early stage: 6% deposit apr and negative 16% borrowing apr. The collateral data is also good - in the past two months, mayc/bayc has stabilized at 300+ and 250+. The agreement currently has no liquidation of other NFTs except azuki. Recently, a large number of baycs have liquidation risks. More innovative protocols:
Defrag: A lending protocol that tries to control risk.
Borrower will buy a put option when mortgaging NFT (if the collateral price drops, the underwriting pool needs to Lock a certain amount of eth to redeem the Nft), the usage of eth in the underwriting pool- 1 . Convert to udtc and lend to users 2. Redeem NFT. Underwriting pool profit: premium fees for put option. If put option strike price 100 is now worth 80, then the put option is worth 20. The liquidation price is 70, and the user has not been liquidated, so the execute put option will not be executed (liquidation is the execute option). If the price drops to 60, then execute, the underwriting pool buys back the NFT, and the user gets 100-60=40+borrowing amount. underwriter is equivalent to mixing the roles of lender and option seller, but in fact the roles of the two are not consistent - As the counterparty of borrower, lender is short collateral, but as option The seller (short put) is also long collateral, which is a conflicting setting.

Astaria: Just announced the financing of 8m, the former sushi cto came out to do a NFT P2Pool lending project, No specific protocol has been designed yet. According to the existing information, its model is similar to maple finance, there is an intermediary (delegate/appraiser) to specify the terms-price/amount/rate of the pool, etc., and it has the function of last resort.
Comments on the P2Pool protocol:
The current NFT P2Pool protocol with higher tvl lacks innovation compared to the P2Pool of defi's erc20, and we expect that there will be more in this field More interesting protocol designs.
The points that distinguish different P2Pool protocols mainly include several points - liquidation mechanism, LTV, risk control.
There are two main liquidation mechanisms, time-based, price-based, and time-based are more friendly to borrowers, allowing them to repay within the specified time without the risk of liquidation, LTV Potentially a Trade-off. Moreover, in P2Pool, the liquidator acts as a key link to ensure the risk control of the agreement, but it is also a relatively independent participant relative to the agreement itself and the borrower and lender. The meaning and requirements of its existence: 1. Profitable 2. Have a certain understanding of the pricing of collateral. Regarding the point of profitability, in the case of insufficient liquidity of NFT itself, especially in extreme market conditions, the rapid decline in collateral prices may also cause these independent liquidators to choose not to participate in the liquidation, resulting in The pricing cognition of the product ensures that it will not sell the NFT at an irrational price, which requires some more reasonable pricing mechanisms. (The third-party valuation system is not mature enough, even for blue-chip NFTs, there is a big difference in the price of the same NFT) Risk control is mainly for whether the lender can be paid in time in the event of borrower default (such as a black swan event) The protocol mechanism in the case of .

Many people say that NFT is like real estate, but I don't quite agree. NFT is a product on the chain, with its own liquidity attributes that real estate does not have. Although the current NFT agreement is mainly about the direction of NFT as collateral (similar to the low liquidity of real estate), an interesting direction in the future is whether there is a lending agreement whose lending/borrowing targets are all NFT (such as mortgage bayc, lending crypto punk). A more positive signal in this direction is that the seaport protocol launched by opensea has opened a precedent for NFT trades NFT. It is not difficult to imagine the emergence of mortgage NFT and loan NFT in the future. In an efficient capital market, such as the btc lending market, the strength of both long and short sides of btc is evenly matched. The current NFT protocols are all NFT-as-collateral agreements (that is, Long NFT), which essentially promote the liquidity of erc-20 (erc-20 is borrowed). At the same time, the current development form of NFT is still dominated by pfp, and pfp itself does not have the characteristics of interest, so the demand of the borrower is very vague. This is also a very urgent question in this direction. Maybe for gaming NFT The NFT form of actual landing scenarios/production activity requirements is more appropriate. In any case, the next cycle belonging to NFT lending must have a great correlation with the bulls/bears of the large crypto/NFT market. In a bull market, such a lending agreement is a natural means of increasing leverage, which will greatly promote Protocol Development.
P2P or P2Pool? Logically speaking, P2P is more suitable for NFTs with higher net worth than the floor price, and p2pool is more suitable for NFTs with relatively low net worth and close to the floor price. P2P puts more emphasis on borrower's experience (customized terms), while p2pool puts more emphasis on lender's experience (multiple lenders spread risk while lowering entry barriers). P2P does not have the liquidation risk of collateral price fluctuations, and only needs to repay on time. The borrower in P2Pool may often receive margin calls. P2P LTV has a bar (even the average of bayc is about 80%), but the LTV of p2pool is relatively high - the highest LTV of BendDAO can reach 90%. Capital utilization is higher with P2Pool.
What is next?
Defi lending giant Aave expressed its intention to enter the NFT as collateral lending market about a year ago, but has not made any new progress. And compared to traditional finance, NFT lending is still a behavior with a higher risk coefficient, which requires risk hedging methods to diversify risks, including and not limited to NFT insurance, futures, options, and even structured products.
NFT futures:
NFTperp is a NFT futures based on vAMM model In the trading market, the vAmm model is designed by the perpetual protocol. Compared with amm, it needs lp to inject liquidity and limit the pool size. There is a funding rate mechanism to ensure the convergence of futures prices and underlying asset prices - the price of vAmm is analogous to perp The price difference between its price and the spot price fed by the oracle is the basis for the calculation of the funding rate. However, this vAmm mechanism, like the amm mechanism, requires a cold start of transaction volume and whether there is any LP reward, so there will be some resistance in the early project launch. NFTures launched by Synfutures is also a NFT futures contract trading market, which currently supports contract trading of four NFTs - PUNK, UJENNY, NFD, The Doge NFT. Its underlying asset price feed is unicly/NFTx. Synfutures' sAMM is also battle-tested, and its transaction volume is comparable to that of perpetual protocol/dydx.
For NFT futures, there are several bottlenecks:One is the price of the underlying asset. Bitting against btc futures, such as dydx/perpetual protocol, the price of the underlying asset is fed through the oracle machine for spot price (dydx uses the oracle of makerDAO, and the perpetual protocol uses chainlink). And for NFTs, there is a lack of a reliable price feed - essentially illiquidity. Perhaps when a trading platform that undertakes higher Nft trading volume, such as blur/sudoswap, has a certain amount of liquidity, its trading price can be used as a price feeding option. The second is needs. If you take btc futures as an example, one of its needs is as a hedging method for btc miners, but many NFT holders do not have such a need. This is an opportunity for gaming NFT - the gamer continuously obtains NFT in the process of upgrading in the game, and there is a need for hedging.
NFT option:
The main direction in NFT Option It is still from the perspective of NFT holder, that is, hedging the risk of holding NFT by buying Put option.
Putty is a platform that provides ntf put option, currently there are 11 orders transacted (including 3 BAYC put options) , the development of the platform is relatively early, and there is little activity. Support customized options (users who want to issue put option provide NFT, premium, strike price, duration), but the liquidity/trading volume of this option is not high in nature. Nifty options is also a platform that provides NFT put option. NFT holders can lock NFT on this platform or other mortgage lending agreements such as NFTfi, and initiate a put option at the same time. The counterparty needs to lock the eth of the strike price as well. The issuer can choose exercise/cancel at any time. The exercise is equivalent to selling the NFT to get the strike price, and the cancel will get back the original NFT. The counterparty will be rewarded with a certain interest rate anyway. The lowest interest rate here needs to be higher than the interest rate of mainstream lending agreements such as aave/compound, because the counterparty bears more risks. Traction is similar to putty. It is still in early exploration and has little usage. There is a solution similar to defrag, which is to buy this option while mortgaging Nft, which ensures that even if it is liquidated, the lender can get a certain value of assets anyway. Compared with defrag, option seller and lender are not a group, so this design will be more reasonable. Jpex.finance is an option platform different from the above two. NFT holders sell call options instead of buying put options. Equivalent to a covered call strategy. But liquidity is a problem - 1. The counterparty needs to pay to enter the pool 2. The European option is only cashed on the delivery date, and the counterparty cannot collect profits in the case of in-the-money.
For NFT option, there are several bottlenecks: Low liquidity. Whether it is ftx or binance, the option setting mechanism is very simple (strike price, expiration date, premium) - there are several fixed options for strike price on ftx, while binance directly uses futures price as strike price, both ftx and binance The premium is calculated automatically. As for the NFT options, they are completely filled in by the NFT holder, and the premium is also written in a brainstorming manner. Naturally, there are very few counterparties who are willing to trade. And the UI/UX aspect is far from satisfactory compared to professional trading platforms. Option Price. Option pricing is mainly determined by two factors - intrinsic value and time value. The time value is the reason why the price of NFT option is relatively high - because the volatility (historical & implied) is high. One method that can be considered to reduce the price of premium is to reduce the time window for exercise, and promote the betting of speculators on the Nft price in a smaller time window. NFT collection quantity. Especially in a bull market, the demand for calls is relatively high, and there are relatively few call sellers (compared to btc holders), which cannot well meet the leverage needs in a bull market.
NFT insurance:
For some high net worth/high scarcity For NFT holders, in addition to relatively indirect hedging methods, it is more direct to insure. Relatively speaking, the cost of borrowing will increase, but some risks will also be transferred. Even when users choose a P2P/P2Pool platform, if the agreement has internal insurance/cooperates with third-party insurance, this is likely to become a point of attraction for users.
NFT structured product:
NFT20 has an NFT index tracks the floor price of a series of NFTs, similar to s&p500 in tradfi. In the metaverse, land is used as an interest-bearing asset NFT (for example, users need to pay rent to produce activities on the land), which can refer to real-life mortgages as a financial derivative, such as CDS.
Some cash flow-based structured products, similar to element finance/solv in defi, can allow lenders to sell future cash flows in the form of bonds . Similar thing metastreet is doing. Secondly, there are some buy-now-pay-later products, similar to mortgages, with regular repayments, such as Cyan/Ape Now, which have potential arbitrage opportunities-stake in NFTx and other NFT fragmentation agreements. In addition, the same promissary notes are also a kind of gameplay.
Investment and financing events
 < /p>
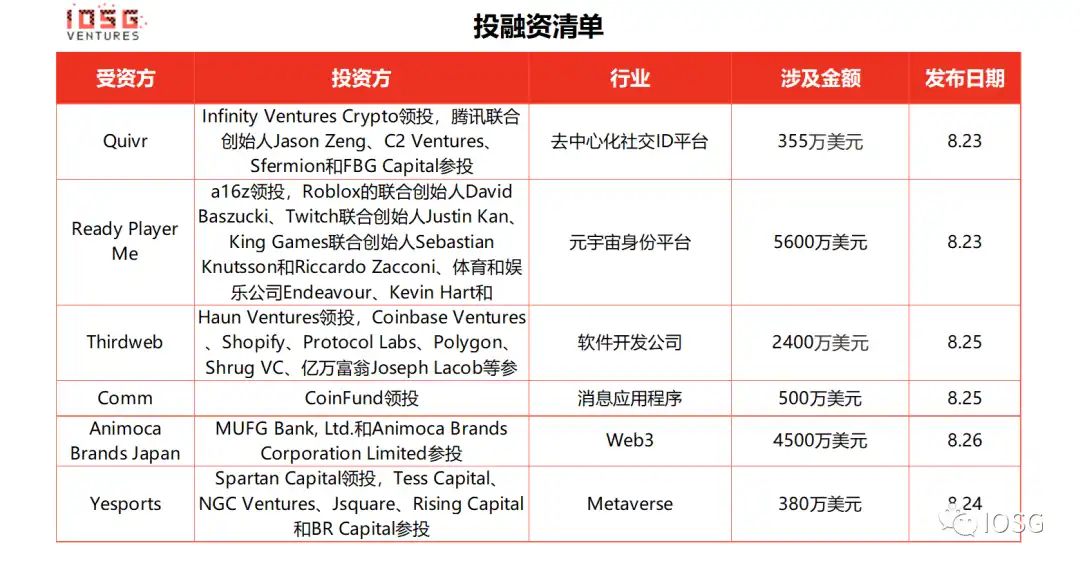
Quivr completed $3.55 million in seed round financing, Tencent United Create Jason Zeng
*decentralized social ID platform
Ready Player Me completed 56 million US dollar B round of financing, led by a16z
*Metaverse identity platform
Ready Player Me completed US$56 million in financing, this round of financing The round was led by a16z, with participation from Roblox co-founder David Baszucki, Twitch co-founder Justin Kan, King Games co-founders Sebastian Knutsson and Riccardo Zacconi, sports and entertainment company Endeavour, Kevin Hart, and Hartbeat Ventures. Ready Player Me aims to allow users to establish virtual identities in the metaverse through virtual products such as NFT. Currently, more than 1,000 project parties have used their products on the platform. Media conglomerate Warner Bros., fashion house Dior and sportswear brand New Balance are all working with Ready Player Me to integrate into the Metaverse in the future.
Thirdweb Closes $24M Funding Led by Haun Ventures
*Web3 Software Development Company
Thirdweb announced the completion of a $24 million financing at a valuation of $160 million, led by Haun Ventures, Coinbase Ventures, Shopify, Protocol Labs, Polygon, Shrug VC, billionaire Joseph Lacob and others participated cast. Thirdweb provides pre-built smart contracts and SDKs to help developers create various products, and also provides a dashboard for development teams to track and manage contracts on the chain. It currently supports Ethereum, Avalanche and Fantom, and plans to integrate into Solana (tentative end of September). This round of financing will be used to expand to public chains such as Cosmos, NEAR, and Flow.
Comm Completes $5 Million Seed Round Financing Led by CoinFund
*Messaging Application Program
Comm raised a $5 million seed round led by CoinFund. Comm currently has 4 full-time employees and about 12 part-timers working on the project. The Comm CEO plans to continue expanding his New York-based team after the raise, with a small number of employees working remotely. Comm aims to let community members host their own backend servers, with only users themselves able to access their data, and the consumer privacy startup is working on scaling end-to-end (E2E) encryption for chat apps like Signal or Whatsapp Messenger service and compete with encrypted community platforms such as Discord.
Animoca Brands Japan completed US$45 million in financing, MUFG and others participated in the investment
*Web3< /b>
Animoca Brands KK (Animoca Brands Japan), a strategic subsidiary of Animoca Brands Corporation Limited, announced the completion of financing of US$45 million at a valuation of US$500 million. MUFG Bank, Ltd. and Animoca Brands Corporation Limited participated in the investment . Animoca Brands Japan will use the new funds to continue licensing popular intellectual property, develop internal capabilities, and facilitate Web3 adoption with multiple partners, increasing the value and utility of its branded content while promoting the growth of Japan's NFT ecosystem.
Yesports completes $3.8 million in strategic financing led by Spartan Capital
*Metaverse < /b>
Polygon-based e-sports metaverse platform Yesports announced the completion of a new round of strategic financing of US$3.8 million, led by Spartan Capital, with participation from Tess Capital, NGC Ventures, Jsquare, Rising Capital and BR Capital . Yesports plans to use the new funds to grow its technology infrastructure and expand its esports team partnerships globally, having launched a customizable NFT membership solution. Esports teams that have entered into partnerships include Talon Esports, Falcon Andilex, Renegades, Team Empire, and more.
Microtraction’s second fund has completed US$15 million in financing and will invest in encryption and Web3 fields
*Fund Financing
Microtraction, an early-stage venture capital company, announced that its second fund, Microtraction Community Limited, has completed its first fundraising, with a financing amount of US$15 million. Ribbit Capital’s Micky Malka, a16z David Haber of Y Combinator, Michael Seibel of Y Combinator, and Alexis Ohanian of 776 are general partners (GPs) of the new fund. The fund’s investment targets include financial technology, SaaS, encryption, games and other markets. In the 10-35 million dollars.
Symbolic Capital completed a financing of 50 million US dollars, Polygon Lianchuang and others participated in the investment
*fund Financing
Web3 venture capital fund Symbolic Capital completed $50 million in financing, Polygon co-founder Sandeep Nailwal, Cere co-founder Kenzi Wang and other venture capital firms, encryption trading platforms, etc. participated in the investment. The fund has made about 15 investments so far, including Web3 game studio BlinkMoon, Polygon-based metaverse platform Mojo, and e-sports platform Community Gaming, among others.
Industry Pulse
Ethereum Mainnet The twelfth shadow fork is expected to be carried out on August 31
*Infrastructure
The twelfth Ethereum mainnet The configuration of the second shadow fork has been released, and the Total Terminal Difficulty (TTD) is expected to arrive around 14:00 CEST on August 31 (20:00 Beijing time), when the twelfth shadow fork of the Ethereum mainnet will be carried out .
The proposal to establish a foundation for Uniswap has been approved and will apply for a $74 million appropriation from the DAO treasury
* DeFi
Uniswap's proposal to establish the Uniswap Foundation has been approved to support open source development and community governance within the protocol. After the foundation is established, it will apply for $74 million from the DAO treasury, of which $14 million will be used to support the foundation's team and $60 million will be used for developer grants.
DeFi Kingdoms will completely break away from Harmony and launch the game part Serendale on Klaytn
< b>*GameFi
Chain game DeFi Kingdoms plans to spin off Harmony entirely and launch its game called Serendale on metaverse-focused blockchain Klaytn In addition, Crystalvale will remain on the Avalanche subnet DFK Chain.
Paradigm proposes the NFT issuance mechanism VRGDAs, the sales price fluctuates with demand
* NFT
Paradigm published the article "Variable Rate GDAs", proposing a novel token (NFT) issuance mechanism, variable rate GDAs (VRGDAs) designed for digital art Experimental Art Gobblers design and use in 0xMonaco. Raising prices when sales demand is high, and lowering prices when sales demand is low, VRGDAs provide a way to issue NFTs almost any time people want, while still allowing users to seamlessly buy at any time.
GameSwift and Polygon have reached a strategic cooperation to build a Web3 game ecosystem
*GameFi
Web3 gaming solution GameSwift (formerly StarTerra) announced a strategic partnership with Polygon Network to build a comprehensive gaming ecosystem. GameSwift has partnered with Polygon to launch its own chain based on the Polygon Edge framework. Tailor-made for gamers and gaming protocols in the Web3 gaming space, the platform helps address challenges that continue to hold back the field.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
 Related Articles