



 "Clumsy Dragon King" repeatedly questioned over on-chain operations—did trades really end in losses? What other arbitrage opportunities remain in the market?

BlockBeats news, November 16 - According to TradingBeats monitoring, trader Hanba Longwang (X: dotyyds1234) had fully closed a previously established ANT long position on November 12. On Hyperliquid alone, the on-chain loss for this trade was approximately $22,400. However, if following the on-chain position-building and reduction节奏, an equivalent reverse short position was simultaneously established on Binance, the simulated portfolio would have instead profited approximately $106,700.
Today, Hanba Longwang publicly stated that his Hyperliquid address "has no directional reference value," and that on-chain positions may be accompanied by hedges in other markets. Using BTC as an example, he explained that shorting on Hyperliquid might be trading its relatively expensive price versus Binance, rather than simply being bearish on BTC.
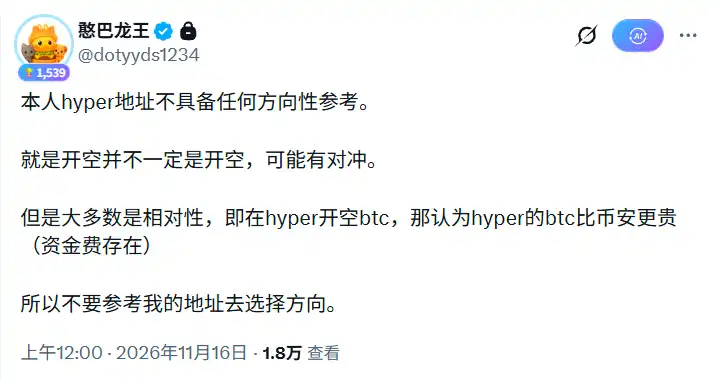
Because his Hyperliquid address has long been public, the market has repeatedly discussed his trading performance based on on-chain positions, closing records, and floating profit and loss. Some one-sided losing positions also sparked outside curiosity about his trading strategy. Although the trader has repeatedly explained that his operations involve cross-platform arbitrage and hedging, and that on-chain positions have no standalone directional reference value, the related explanations have always been difficult to verify through a single address because the other side of the trades was not simultaneously disclosed.
The recent ANT trade happens to provide a case for observing his cross-platform operating approach.
The address began building an ANT long position in batches starting October 30, with cumulative purchases of approximately $844,000 at an average price of $108.1; it exited in batches from November 11 to 12 at an average selling price of $105.2, including approximately $47.47 in fees and approximately $5.74 in net funding expenses, resulting in a final on-chain loss of approximately $22,430.
But if the possible other side of the trade is included: under the assumption that each time the on-chain long position was increased, an equivalent ANTHROPICUSDT short position was simultaneously established on Binance, and covered in the same proportion when the on-chain position was reduced, the simulation shows the Binance short position had an average price of approximately $1,641.6 and an average cover price of approximately $1,392.5, for a price profit of approximately $128,100, plus approximately $1,008 in funding income.
After offsetting the profit and loss on both sides, the simulated portfolio profit was approximately $106,700 (excluding Binance fees and slippage).
There are still questions worth asking about this trade: Over the nearly two weeks from position opening to closing, how did the price deviation between the two platforms change, and at what stage was the spread profit formed?
Further comparing the historical quotes, funding rates, and order book depth of the two markets, it can be found that during the closing period, the ANT composite spread had already converged significantly and was no longer worth continuing to execute. Currently, besides ANT, what other similar arbitrage opportunities are worth watching?

 Subscribe Now

 RelatedRecommended


