US Midterm Elections: Ten Issues Wall Street Really Needs to Watch
Original title: U.S. midterms: Ten questions investors should be asking
Original author: Peter Doralt, DWS (asset management company under Deutsche Bank)
TL;DR
Election results do not equal market direction. Market reactions depend on the deviation between actual results and existing expectations; even accurately predicting elections does not necessarily mean correctly judging asset price movements.
A divided Congress is not necessarily bullish for U.S. stocks. Political gridlock can limit major legislation, but it cannot eliminate uncertainty brought by government shutdowns, expanding fiscal deficits, and administrative policy adjustments.
AI investment faces local political variables. Data center approvals, power grid construction, and residential electricity prices may become important issues in state and local elections, directly affecting the costs and returns of AI infrastructure projects.
Midterm elections cannot automatically solve the U.S. debt problem. Regardless of who controls Congress, existing spending and debt interest will continue; U.S. Treasury investors need to watch fiscal deficits, debt issuance scale, and long-term yields.
Historical post-election rally patterns are not certain. U.S. stocks typically weaken before midterms and rebound afterward, but different cycles vary significantly; corporate earnings and the macroeconomic environment remain decisive factors.
On November 3, the United States will hold its 2026 midterm elections. At that time, all 435 House seats and 35 Senate seats will be up for election, including two special elections. Voters will also elect 39 state and territorial chief executives and decide the outcomes of numerous state legislatures and local offices.
For Wall Street, the truly important question is not simply whether Democrats or Republicans can control Congress, but how the election results will change market expectations for economic growth, inflation, corporate earnings, and the dollar's trajectory.
DWS, the asset management company under Deutsche Bank, noted in an October 26 report that accurately predicting political outcomes does not mean correctly judging market movements. Markets often trade not the event itself, but the difference between actual results and investors' prior expectations.
From historical experience, U.S. stocks often weaken before midterm elections and rebound after they conclude. But this pattern is not stable, and the bond market's reaction depends more heavily on the macroeconomic environment at the time.
DWS summarized the potential market impact of this midterm election into ten core questions.
Ten Questions
1. How much of the election expectation has the market already priced in?
The starting point for analyzing midterm elections should not be simply judging which party can win, but rather first understanding what political expectations the financial markets have already reflected.
DWS noted in its report that, as of the time of writing, relevant forecasts lean toward Democrats gaining control of the House, but the actual outcome remains uncertain. For investors, even if the final result aligns with prior judgments, it does not mean they can profit from it.
The 2016 U.S. presidential election is a typical case.
When Trump unexpectedly won the presidential election, financial markets initially fell. But as investors shifted attention to the possibility of corporate tax cuts, U.S. stocks quickly rebounded and recovered previous losses before the end of the next trading day.
This shows that the impact of political events on markets does not depend on the win or loss itself, but on how the market reassesses future policy and economic prospects.
The same logic applies to the 2026 midterm elections. Even if the final result meets market expectations, investors still need to judge whether the new Congress's policy mix will change the outlook for growth, inflation, and corporate earnings.
2. Could the real market surprise come from outside Washington?
Wall Street typically focuses on control of the House and Senate, but DWS believes some more noteworthy policy changes may occur at the state and local levels.
Governors, state legislators, and local officials can directly influence power supply, transmission line construction, land planning, and data center approvals.
For companies reliant on large infrastructure projects, these policies may have a more direct impact than changes in congressional seats.
For example, a company building a data center, even if not significantly affected by federal policy adjustments, may face rising costs and delays due to local governments changing power access rules or project approval requirements.
Therefore, a local election with almost no impact on the S&P 500 Index could still significantly alter the earnings expectations of relevant companies.
3. Can U.S. stocks still rely on the post-midterm election rally pattern?
Historical data shows that the U.S. president's party typically loses a certain number of House seats in midterm elections.
DWS points out that 2026 also has a rather special historical backdrop: Trump is undergoing his second non-consecutive presidential term. The only U.S. president with a similar experience in history is Grover Cleveland.
If we refer to the historical experience of serving two consecutive presidential terms, the midterm elections of the second term are often accompanied by a decline in support for the ruling party. This phenomenon is also known as the "Six-year itch."
Financial markets also have certain historical patterns.
The U.S. stock market often comes under pressure in the months before midterm elections and resumes rising in the period after the elections end. But the report emphasizes that these statistical results can only show what happened in the past and cannot prove that the gains were directly driven by the elections.
Economic conditions, corporate earnings, monetary policy, and valuation levels differ enormously across historical cycles, so future stock prices cannot be predicted simply based on historical average returns.
IV. Is a divided Congress really good for Wall Street?
There has long been a view on Wall Street that divided government may be beneficial to financial markets, because when the White House and Congress are controlled by different parties, large-scale legislation and policy adjustments become more difficult.
This political gridlock is believed to be able to limit government intervention, thereby reducing the policy uncertainty faced by businesses.
But DWS believes that historical data are not sufficient to support this simple judgment.
Research cited in the report found that during periods of unified government control, the average excess return of U.S. stocks was actually higher than during periods of divided government. More importantly, a reduction in legislative activity does not mean a decline in political uncertainty. Even if Congress is deadlocked, lawmakers still must agree on annual fiscal appropriations. If the two parties cannot compromise, the risk of a government shutdown still exists.
At the same time, a White House constrained by Congress may also rely more on other executive policy tools to advance its agenda.
Therefore, for investors, what needs attention is not only whether Congress is divided, but also how the government will continue to implement policy after political gridlock emerges.
V. Why might AI and data centers become important variables in the midterm elections?
This is one of the changes worth watching between this midterm election and past election cycles.
As the scale of artificial intelligence investment expands, the development of the AI industry is no longer just a matter of chips, software, and algorithms, but is increasingly dependent on physical infrastructure.
Data centers require continuous power supply, grid connections, transmission facilities, and local infrastructure support, and these projects are often regulated by state and local governments.
If election results reflect local residents' dissatisfaction with data center construction, rising electricity prices, or infrastructure strain, newly elected local officials may adopt stricter regulatory measures.
For example, raising approval requirements for data center construction, requiring developers to bear more infrastructure construction costs, or taking measures to limit the impact of data center expansion on residential electricity prices.
These changes could directly affect the cost of AI infrastructure investment, project construction timelines, and future profitability. For companies that have already invested substantial capital in building data centers, local politics may thus shift from a general regulatory issue to an important variable affecting financial performance.
However, DWS also emphasized that investors cannot focus solely on the political headwinds facing AI infrastructure.
If artificial intelligence can ultimately significantly improve overall economic productivity, the resulting growth effects may be more important than the political controversies surrounding data center construction.
In other words, the long-term valuation of the AI industry still depends on whether the technology can truly translate into productivity gains and corporate profit growth.
VI. Can Political Gridlock Improve the U.S. Fiscal Deficit?
Another common view is that if Congress is divided, the two parties will find it difficult to push through large-scale new fiscal spending, thereby helping the United States control its budget deficit.
But DWS cautions that political gridlock does not necessarily mean improved fiscal discipline. Even if new major fiscal programs are difficult to pass, existing federal spending may continue, and interest costs on government debt will continue to accumulate.
At the same time, political compromises reached around annual fiscal appropriations may preserve existing fiscal commitments or even increase some spending, without resolving the long-term debt problem.
This distinction is particularly important for the U.S. Treasury market. For Treasury investors, what needs to be assessed is whether election results will change future fiscal deficits, the scale of Treasury issuance, and what yield the U.S. government will need to pay to attract investors to purchase Treasuries.
Congressional gridlock can limit policy adjustments, but it cannot automatically change the basic structure of fiscal revenue and expenditure. Therefore, even if the midterm elections produce a divided government, one cannot directly conclude from this that long-term U.S. Treasury yields will decline.
VII. How Should Investors Interpret the Results of Election Night?
DWS advises investors to be cautious about early results on election night.
If Senate control ultimately hinges on one or two highly competitive districts, preliminary results could shift as more ballots are counted.
Exit polls are inherently estimates, and close elections may also involve delayed ballot counting, recounts, legal challenges, and varying state certification procedures.
But financial markets typically do not wait for final election results to be fully confirmed before they start trading.
Existing research shows that when markets reprice the likelihood of a certain political outcome, stocks, interest rates, oil, and the dollar can all experience volatility.
Therefore, investors need to distinguish between new information that genuinely changes policy expectations and short-term noise generated during the election counting process.
VIII. How exactly do election results translate into investment opportunities or risks?
DWS emphasizes that election results themselves do not directly provide trading instructions.
What truly affects asset prices is a longer transmission chain:
What the market's prior expectations were, what surprises the actual results delivered, how those surprises change policymakers' policy incentives, and how these in turn affect corporate earnings, inflation, interest rates, and risk premiums.
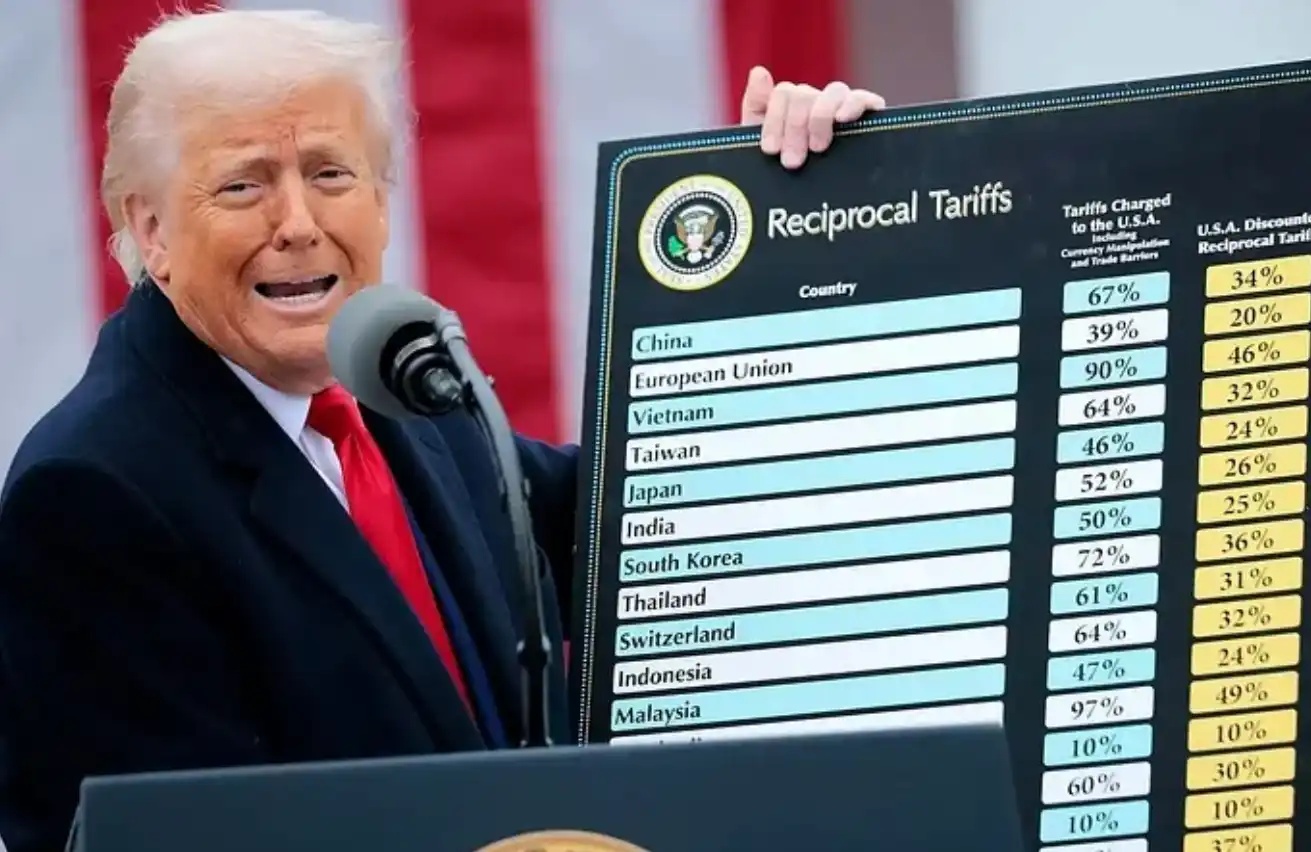
For the 2026 midterm elections, key policy variables include tariffs, fiscal spending, AI infrastructure regulation, and U.S. Treasury yields.
Investors need to further assess whether these policy changes are sufficient to alter the long-term pricing of assets.
The report argues that, compared with presidential elections, midterm elections typically do not produce the same degree of investment impact. Even if Senate control ultimately comes down to a single seat, its direct investment significance may be relatively limited.
DWS therefore expects that after short-term political volatility, financial markets may gradually refocus on conventional economic and policy issues.
Rather than who wins the election, the market may ultimately focus more on what specific policies the newly elected officials plan to implement.
IX. For U.S. equity investors, what is the most important judgment?
DWS believes that U.S. equity investors first need to distinguish between the overall market impact of elections and the impact on individual sectors and companies.
Historically, the S&P 500 has often shown some degree of weakness before midterm elections and recovered within a year after the election. But actual performance varies greatly across election cycles, and historical average returns cannot effectively predict market movements in any single cycle.
The report also compared U.S. stock market performance under different congressional control configurations during Republican presidential administrations since 1953. In these limited samples, the average annual return of the S&P 500 Index was positive regardless of which party controlled Congress. However, when Republicans simultaneously controlled at least one chamber of Congress, the average return was significantly higher than during periods when Democrats simultaneously controlled both the Senate and the House.
DWS also cautioned that the relevant sample size is small and that such historical differences cannot be directly regarded as a predictive basis for future market performance. For the U.S. stock market as a whole, corporate earnings, productivity, monetary policy, and valuation levels may still be more important than congressional control. But for specific companies and industries, the situation may differ.
If election results change the political environment for tariff policy, industry regulation, or AI infrastructure construction, they could have a more pronounced impact on the earnings prospects of some companies.
Therefore, what investors need to judge is not whether the election results are eye-catching enough, but whether they truly change the profits companies can earn in the future and the valuations the market is willing to pay for those profits.
X. What changes do U.S. Treasury investors need to watch?
For bond investors, election results are likewise only the starting point for analysis. The more important question is whether the new policy mix will change U.S. economic growth, inflation levels, government financing needs, and the future interest rate path.
Political uncertainty may also change the additional risk compensation investors require to hold long-term bonds, namely the term premium.
This means that the impact of midterm elections on the bond market may not be reflected all at once on election night, but may gradually emerge through subsequent changes in fiscal policy and macroeconomic expectations.
Investors need to watch the scale of future fiscal deficits, Treasury supply, and possible changes in inflation expectations and long-term U.S. Treasury yields.
The historical performance of the credit bond market also reflects a similar pattern. DWS analyzed six U.S. midterm elections since 2002 for which Bloomberg global high-yield bond spread data were available for observation, and found that election results did not have a stable, independent impact on high-yield credit spreads.
Instead, changes in credit spreads after elections were more driven by the credit cycle and the overall macroeconomic environment at the time. For example, the second round of quantitative easing in 2010, the oil market shock in 2014, and the Federal Reserve's monetary tightening in 2018 all had important impacts on credit markets.
Given the limited historical sample size, the report concludes that the more reasonable approach at present remains to focus on analyzing the macroeconomic outlook and credit risks in specific industries, rather than directly judging the trajectory of high-yield bonds based on election results.
Conclusion: What the market ultimately trades is not political outcomes, but economic expectations
The 2026 U.S. midterm elections could reshape the congressional power landscape and have varying degrees of impact on fiscal policy, trade regulation, AI infrastructure, and government financing.
But DWS's core judgment is that political changes do not necessarily correspond to a fundamental shift in the investment outlook.
For U.S. equities, corporate earnings, AI-driven productivity gains, valuation levels, and Federal Reserve policy will remain important drivers of long-term performance. For U.S. Treasuries, fiscal deficits, Treasury supply, inflation, and long-term interest rate expectations are more critical.
At the same time, local elections may have a more direct impact on specific companies and industries through data center approvals, power infrastructure construction, and local regulation.
Historical patterns can provide reference, but cannot replace analysis of current economic conditions.
For Wall Street, what truly matters is not accurately guessing which party will win, but identifying whether election results have changed the growth, inflation, earnings, and interest rate expectations already priced into the market, and how long these changes can last.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
 Related Articles