



Are the bookmakers always the winners? Delphi Digital interprets the speculative wave of the next decade.
Original Title: The House Always Wins: Why Speculation is the Theme of the Decade
Original Author: Jason Pagoulatos, Delphi Digital
Compiled by: Peggy, BlockBeats
TL;DR
Speculation is becoming a major investment theme for the coming decade. Historically, speculation has been driven by two forces: "build-oriented speculation" brought about by technological revolutions, and "lottery-style speculation" spawned by fiscal, monetary, and socioeconomic pressures. In the past, the two typically operated separately; now they are accelerating simultaneously.
AI is powering both speculation engines at once. On one hand, hundreds of billions of dollars in capital expenditure by tech giants is driving the buildout of computing power, electricity, and data centers, forming a technology investment boom reminiscent of the railway and internet eras; on the other hand, AI is also pushing up energy costs, intensifying fiscal and financing pressures, and dampening young people's employment prospects, indirectly reinforcing the motivation to seek high-risk, high-reward opportunities.
Cryptocurrency is becoming the infrastructure for speculative activity. If AI provides the rationale for speculation, then crypto technology provides the tools. Perpetual contracts, meme coins, prediction markets, and tokenized assets have dramatically lowered the barriers to creating and trading financial products, enabling a growing range of assets to trade around the clock and globally.
Speculative demand is crossing traditional asset classes. Sports betting, same-day expiry options, prediction markets, cryptocurrency, and social trading may appear to belong to different markets, but they actually reflect the same demand: investors want to convert their judgments about future events into tradable positions with potential returns. These activities are gradually converging onto the same set of trading platforms.
The core investment strategy is "buy the house, not the chips." Rather than betting on the next successful AI company, the next token to surge, or the next hot event, focus on platforms that can consistently generate revenue from trading activity. The report focuses on the business models and growth potential of trading venues such as Robinhood, Hyperliquid, Lighter, as well as Kalshi and Polymarket.
Trading platforms do not guarantee profits. Volume growth does not necessarily translate into profits; fee competition, regulatory risk, wash-trading incentives, and market cycles can all erode platform value. In particular, it is important to distinguish between trading platform equity and platform tokens: even if a token has a fee buyback mechanism, it is not equivalent to holding exchange shares.
The long-term opportunity lies in speculative infrastructure, not in any single market cycle. Historically, both the railway and internet bubbles caused massive capital losses, yet left behind infrastructure of lasting value. Delphi Digital believes that future speculative bubbles may still burst, but the matching, clearing, and distribution networks that survive are expected to become core assets that continuously capture trading demand.
The original text is as follows:
Speculation has historically been driven by two forces. Today, these two engines are running simultaneously with unprecedented intensity, and are being propelled by the same set of technologies.
In 1841, Scottish journalist Charles Mackay published Memoirs of Extraordinary Popular Delusions. The most widely circulated sentence in the book appears at the opening: "Men, it has been well said, think in herds; it will be seen that they go mad in herds, while they only recover their senses slowly, and one by one."
The book chronicled the Mississippi Bubble, the South Sea Bubble, the Dutch tulip mania, the witch hunts, the alchemists, and the Crusades. In the 185 years since, this sentence has been repeatedly used to describe one speculative frenzy after another—railway stocks, radio concept stocks, internet stocks, real estate, meme stocks, cryptocurrencies, and zero-day options.
Mackay's observation of herd behavior was accurate, but he misjudged its place in human society. He described group behavior as a brief frenzy that deviates from normal life, believing that people would fall into it and eventually return to reason.
But in markets, herd behavior itself is the norm. When no one knows what the future holds, prices are determined jointly by people who observe and second-guess one another. Since the birth of markets, this rule has never changed.
Financial journalist Edwin Lefèvre described this with less moralizing. In Reminiscences of a Stock Operator, his narrator, modeled on the legendary trader Jesse Livermore, said bluntly: "There is nothing new in Wall Street. There can't be because speculation is as old as the hills. Whatever happens in the stock market today has happened before and will happen again."
Financial instruments keep changing, but the human behavior surrounding them has remained essentially unchanged.
As long as people can buy and sell some kind of claim on future returns, speculation will exist. The real difference between eras lies in the intensity of speculation and in what people believe they are actually buying.
This article stems from a simple question: Is speculation a societal reaction to technological change, or a reaction to the decline of political and monetary order?
History shows that both factors can trigger speculation, and most famous speculative episodes have been driven primarily by one of these forces. Sometimes, a new technology makes future possibilities seem far broader than the present; sometimes, strained fiscal and political systems push the public into speculative trades designed and peddled by the system itself.
Today, these two forces are running at high speed simultaneously, and the same technology is powering both. This is precisely why we view speculation itself as an investable theme. Rather than betting directly on a speculative asset, it is better to hold platforms that provide matching and clearing services for these trades.
I. The Specter of Speculation
Benjamin Graham, Warren Buffett's teacher, learned the difference between investment and speculation at a painful cost.
From 1929 to 1932, the investment partnership he managed lost about 70%. For most of his subsequent career, he tried to stop people from casually applying the word "investment" to any asset they had just bought.
In 1934, Graham and David Dodd proposed a definition in Security Analysis that remains the classic standard for distinguishing investment from speculation: "An investment operation is one which, upon thorough analysis, promises safety of principal and an adequate return. Operations not meeting these requirements are speculative."
But Graham was well aware that Wall Street would never use these words strictly according to that standard. He later wrote: "In Wall Street's broad usage, everyone who buys or sells securities becomes an investor, regardless of what securities are bought or sold, for what purpose, at what price, or whether the transaction is for cash or on margin."
Still, Graham never regarded speculation as a sin. He wrote in The Intelligent Investor: "Pure speculation is neither illegal, nor immoral, nor fattening to the pocketbook for most people."
He further noted that a certain degree of speculation is both necessary and inevitable. After all, someone must bear the risks that cannot be fully eliminated through models. What he truly opposed was the confusion of concepts.
Wall Street trader Fred Schwed, who lost most of his wealth in the 1929 crash, summarized the distinction in two sentences in his 1940 book Where Are the Customers' Yachts?: "Speculation is an effort, probably unsuccessful, to turn a little money into a lot. Investment is an effort, which should be successful, to prevent a lot of money from becoming a little."
John Maynard Keynes himself speculated heavily with his personal funds. His focus was not on the moral attributes of speculation, but on its operating mechanism.
In Chapter 12 of The General Theory, Keynes compared professional investment to a beauty contest held by newspapers at the time: readers had to choose the six most beautiful faces from a hundred photos, and the winner was not the person who picked the objectively most beautiful faces, but the one whose choices came closest to the average choice of all contestants.
Keynes explained: "It is not a case of choosing those which, to the best of one's judgment, are really the prettiest, nor even those which average opinion genuinely thinks the prettiest. We have reached the third degree where we devote our intelligences to anticipating what average opinion expects the average opinion to be."
He added that some people even go to the fourth and fifth degrees of prediction. From this perspective, speculation is essentially about judging how others will judge, with asset cash flows being only one reference factor.
Yale University economist and Nobel laureate Robert Shiller later further explained how these expectations spread.
In Irrational Exuberance and Narrative Economics, he proposed that stories often spread faster than financial data. What truly drives asset prices is usually narratives about a "new era": housing prices can only go up; the internet will change everything; a currency that the government cannot arbitrarily print more of is better than fiat money.
Whether true or false, as long as a story is easy enough to retell, it has the potential to move prices.
George Soros, who rose to fame in 1992 by shorting the pound, built his career by trading on this feedback loop. He called this mechanism "Reflexivity."
In a 2009 speech, Soros noted: "Every bubble has two components: an underlying trend that prevails in reality and a misconception relating to that trend."
When the two reinforce each other, rising prices appear to become evidence supporting the original judgment. As Soros described it, the boom phase is "long and slow," while the crash phase is "short and steep, because forced liquidation of unsustainable positions further reinforces the decline."
Before the trend reverses, crowds are not as foolish as Mackay suggests. They are simply participating in a process that can continue to deliver returns for a period of time, and the returns are often quite substantial. Soros's own success is proof of this.
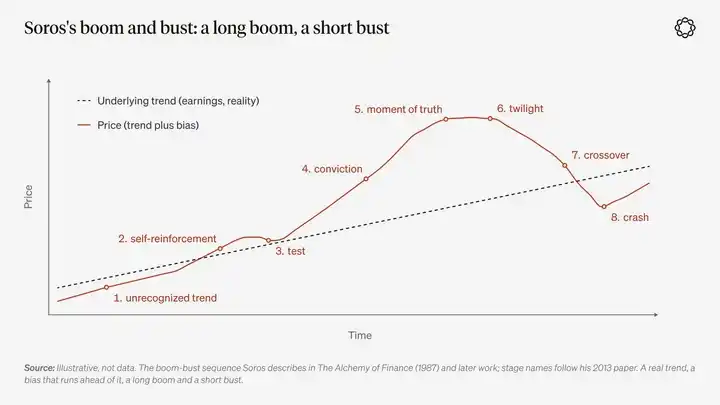
These four thinkers disagreed on many issues, but on crowd behavior, they ultimately reached conclusions that are closer to each other than their respective methodologies would suggest: short-term prices are determined by market participants' expectations of others' behavior. As long as this behavior continues to deliver returns, the crowd appears rational.
But none of them thoroughly answered one question: what initially drives crowd action?
II. Two Great Speculative Engines
A crowd needs a reason to act, and that reason usually comes from the gap between two worlds: the real world already reflected in asset prices, and the world that may emerge in the future.
Historically, this gap has formed mainly in two ways.
The first is technological change.
Railways dramatically reduced transportation and distance costs, electricity reorganized factory production, and today AI models capable of reading and writing are reshaping people's perception of the value of white-collar labor.
People disagree about when the change will occur and who will ultimately capture the new gains, and liquid markets are where these disagreements are priced and traded.
We can call this Construction Speculation.
Someone will eventually build an entirely new industrial landscape, and those who arrive first will gain status and returns, while capital often floods in rapidly but crudely. Fiber-optic networks were laid down exactly this way, and data centers are being built this way too. At the same time, a large amount of capital will also be destroyed in the process.
The second force comes from the political and monetary system.
When a country faces fiscal pressure, or when a policy regime has its own specific goals, it begins to sell some kind of bet to the public: converting war debt into corporate stock; buying real estate because homeownership is national policy; or holding any asset other than cash.
At the household level, this change manifests as: the normal path of life today no longer gives people confidence that they can have a decent life in the future. The real purchasing power of money seems to be declining faster than official data shows, and wage income can no longer be converted into a home at the same stage of life as it could for the previous generation.
We can call it Lottery Speculation.
At this point, patiently waiting sounds more and more like advice given by those who already own assets. The remaining option seems to be just a lottery ticket: if you hit an extremely low-probability huge payoff, life could change completely; and if you fail, the result is little different from the speculator's original state of life.
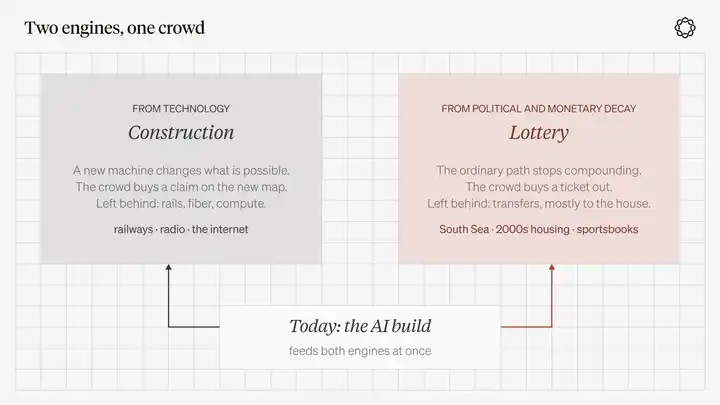
Chart description: These are two ways groups form a shared narrative. Similar behavior, yet different outcomes.
Neither concept is derogatory; they describe why people participate in speculation, not what assets they buy.
An 1845 railway stock mainly belongs to the construction narrative, but it also contains lottery-style dreams of sudden wealth. A sports parlay bet is essentially a lottery ticket, except it has learned to speak the language of financial markets. A stock index perpetual contract may belong to either of the two, depending on who the counterparty is and why they enter the market.
Mackay actually observed these two forces, but did not name them.
He opened his chapter on the Crusades by writing that every age has its own peculiar madness: "some scheme, project, or fantasy, by which people are drawn in because of the desire for profit, the need for excitement, or the sheer power of imitation. If none of these factors are present, then political or religious causes, or both together, will also drive people into some kind of madness."
The desire for profit around projects corresponds to construction speculation; the push of political forces corresponds to the second engine. Imitation is herd behavior itself, and it does not care which force originally started the whole process.
William Quinn and John Turner also proposed a similar division in their 2020 book Boom and Bust.
Their "bubble triangle" contains three elements: asset tradability, money and credit, and speculation. In addition, a bubble also needs a trigger, and this trigger is usually new technology or government policy.
According to their analysis, bubbles driven by bank financing usually cause the most severe damage, while bubbles triggered by technological progress are the most likely to leave something genuinely useful behind after they burst.
III. What Were Speculative Crowds in History Actually Doing?
If Lefèvre's "there is nothing new on Wall Street" is correct, then the most valuable way to study history is to identify the causes of each wave of speculative frenzy, examine what they ultimately left behind, and notice how rare it actually is for two major engines to run strong simultaneously.
Tulip Mania: An Emerging Trading Asset in a Wealthy Republic
The Dutch tulip mania of 1636 to 1637 is one of the most familiar financial bubble stories and one of the events historians have spent the most effort re-examining.
Historian Anne Goldgar found in her 2007 book Tulipmania that the main participants at the time were a small group of merchants and skilled craftsmen in Haarlem and Amsterdam, trading a luxury good among themselves.
She later said: "I didn't find anyone who went bankrupt because of it."
The damage from this frenzy was mainly concentrated at the level of trust and reputation. But three conditions did exist at the time: an emerging aesthetic consumer good, forward contracts on bulbs that had not yet been dug up, and a wealthy commercial republic with a well-developed legal mechanism capable of trading future promises.
Tulips were not a technological innovation, but novelty can be seen as a smaller branch of constructive speculation. A new commodity and a forward trading market were enough to spawn a speculative crowd in an environment where the political order was functioning normally.
Most phenomena called "bubbles" in normal bull markets are actually similar to this, and the actual damage caused is usually far less than later narratives have portrayed.
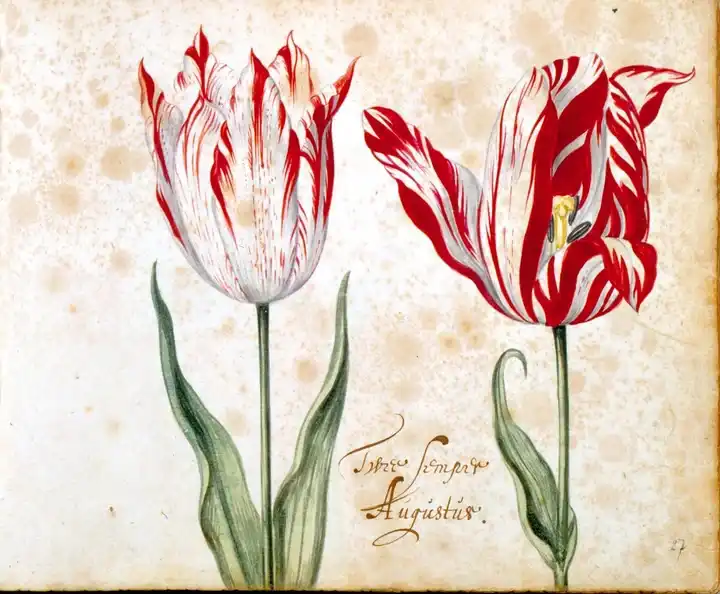
Caption: Semper Augustus, the most famous variety in the 1636–1637 tulip trade, image taken from a 17th-century tulip catalogue.
The South Sea Bubble and John Law: Packaging National Fiscal Debt as Stock
The situation in 1720 was completely different, and technology played almost no role. After the War of the Spanish Succession ended, both Britain and France were burdened with enormous debt that the existing tax systems could not easily service. Both countries tried to refinance their debt through trading companies.
In London, the South Sea Company proposed moving government debt off the public books through debt-to-equity conversion. Rising share prices made debt holders more willing to accept the swap, which further pushed up share prices and made the next round of debt conversion easier.
The South Sea Company's share price rose from about £128 in January of that year to around £1,000 in late June. During the summer suspension of stock transfer registrations, the market continued to trade through forward quotes. However, by autumn, the share price had given back most of its gains.
In Paris, John Law went further. He integrated a royal bank, a paper money system, and the Mississippi Company into a unified financial mechanism.
For several months, this mechanism appeared to have refinanced a country on the brink of fiscal collapse in the hands of a clever Scotsman. But ultimately, paper money must be redeemable for real value beyond paper itself, and cannot be sustained forever by issuing more paper money.
France suffered more severely from this crisis than Britain, because its monetary system was itself part of the entire speculative scheme.
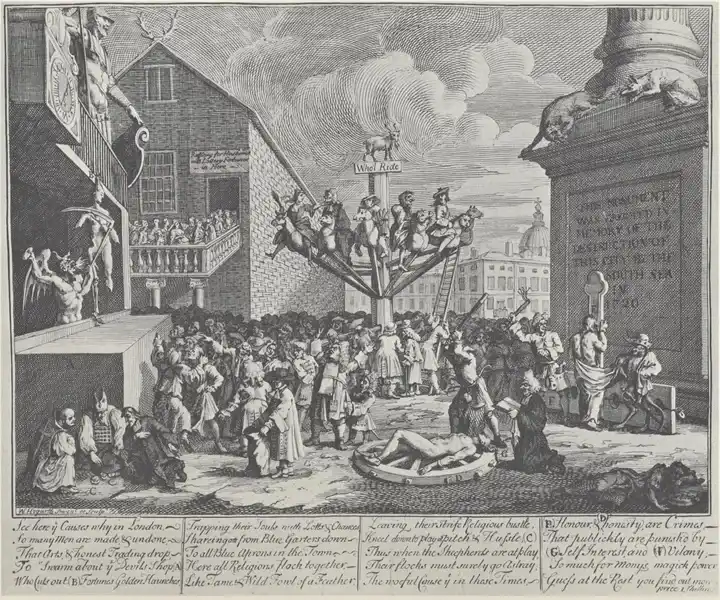
Caption: William Hogarth's "The South Sea Bubble" satirical print, created in 1721 and published in 1724. Speculators ride a carousel beneath a sign reading "Who'll go?", Evil whips Honor, Self-Interest binds Honesty to the wheel of torture, and the monument is rededicated to the damage the South Sea Company inflicted on the city.
This is the typical pattern of the second speculative engine. Public debt is converted into private profit opportunities, while the public is ultimately asked to bear the risk.
Housing policy in the 2000s enacted another version of this pattern through mortgages. The monetary narrative of cryptocurrency unfolds from the opposite direction: when official currency continues to depreciate, the market begins to rush to embrace another monetary unit.
Even without endorsing the quasi-religious narrative, it is not difficult to understand the structure behind it. When a group no longer trusts the official store of value, they will be willing to buy the story of a better alternative.
Railway Mania: Real Technology, Cheap Money, and a Permissive Parliament
Britain in the mid-1840s was the historical prototype for every subsequent technology speculation mania.
The steam locomotive was a real technology. As early as 1830, the Liverpool and Manchester Railway had already begun operating paid passenger services. Subsequently, money became increasingly cheap.
In 1844, the Bank of England cut interest rates from 4% to 2.5%; investors could subscribe for railway shares with only a small deposit; and the British Parliament approved new railways faster than engineers could complete route surveys.
Andrew Odlyzko, a mathematician who has long studied railway historical archives, found through statistical analysis that the mileage of new railways approved by the UK Parliament was 805 miles in 1844, increased to 2,700 miles in 1845, and further rose to 4,538 miles in 1846.
By 1847, the UK was spending approximately £44 million per year on railway construction, while the entire central government's annual budget at that time was only about £50 million.
In Dombey and Son, Dickens depicted an era saturated with railway elements: "Railway hotels, railway offices, railway lodging houses and boarding houses; railway plans, maps, landscape views, wrapping paper, bottles, sandwich boxes, and train timetables."
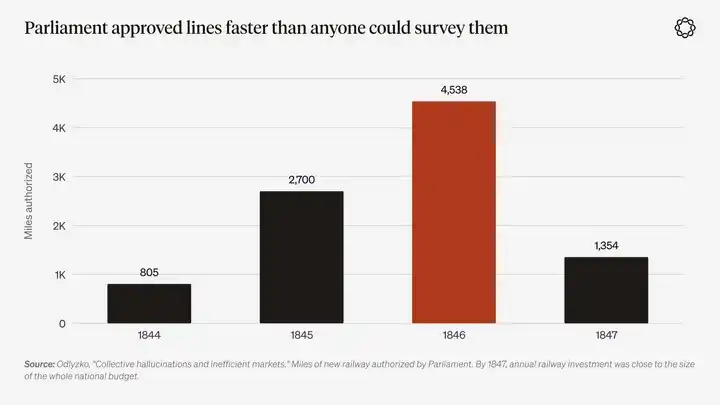
Chart caption: Mileage of new railways approved by the UK Parliament, data from Odlyzko's "Collective Hallucinations and Inefficient Markets." By 1847, annual railway investment had approached the entire central government budget.
Mackay's own role in this mania is a rather ironic episode in financial history.
Odlyzko re-examined the Glasgow Argus, which Mackay edited from 1844 to 1847, and found that the author of the most famous work on crowd madness was actually "one of the most enthusiastic promoters of Railway Mania."
In October 1845, when railway prices were near their peak, Mackay's newspaper was still telling readers: "Those who sound warnings are wrong; there is absolutely no reason to fear any legitimate railway speculation."
When Mackay revised his book in 1852, however, he mentioned the most severe speculative mania he had personally experienced in only a single footnote.
If someone who specializes in herd behavior could not see it clearly while in the middle of the herd, then others should not overestimate their own ability to identify crowd mania.
Odlyzko's other research conclusions are even more relevant today. In his words, railway shareholders ultimately "suffered extremely severe disappointment."
But the railway network was still built, and it left Britain with what Odlyzko calls "the best transportation infrastructure in the world." The waste of capital occurred mainly in the timing of investment and the choice of routes, rather than in creating worthless things out of thin air. This is precisely the classic form of constructive speculation.
For AI investment, the historical lesson is not that "railways ultimately succeeded, so one should buy AI labs."
The real lesson is: when a general-purpose technology, cheap money, and policymakers eager to provide political support for construction projects come together, they simultaneously create overcapacity and infrastructure networks that can be used for the long term.
The investment target you choose may become a winner, or it may ultimately go to zero, but the large-scale buildout itself will leave behind useful physical infrastructure.
The 1920s: A New Technology Boom Fueled by Borrowed Money
In the 1920s, the same speculative engine started up again, only with higher leverage.
Radio, automobiles, electrification, and mass industrial production were all real technological advances, just like railways. Radio Corporation of America (RCA) became the representative stock of that era's "new era" narrative. Today, a handful of memory chip and semiconductor companies, along with the frontier AI labs that support them, are playing a similar role.
Harvard economist John Kenneth Galbraith, when he wrote The Great Crash, 1929 a generation later, refused to attribute such a massive boom simply to a single Federal Reserve rate cut.
In his view, what mattered more was the social mood of the time: a widespread conviction that ordinary people deserved to become wealthy too. Decades later, he added two factors that had previously received little attention: "financial memory is extremely short," and "the false association of money with intelligence."
The fuel behind this frenzy was credit, and expensive credit at that. Brokerage loans exceeded $8.5 billion, and in March 1929, short-term call money rates briefly touched 20%.
People were willing to pay such high interest rates because they expected investment returns to reach several times the cost of borrowing. Investment trusts bought each other's shares and packaged this circular ownership as value creation.
Walter Bagehot, the Victorian-era editor of The Economist, had described the basic raw material of this phenomenon 70 years earlier: "At particular times a great deal of stupid people have a great deal of stupid money."
According to his explanation, this money begins searching for people who can devour it, a stage called "excess money"; when it finds its target, "speculation" takes shape; and when the money is ultimately devoured, it turns into "panic."
From September 1929 to July 1932, the Dow Jones Industrial Average plunged 89%.
Today, the equivalent of 1920s margin trading is a set of leveraged instruments that never call themselves loans: same-day expiry options, perpetual contract funding rate mechanisms, and ten-times leveraged positions that can be established with a few taps on a phone using collateral nominally belonging to cash.
After a bubble bursts, the official narrative usually needs to find a villain, whether short sellers, foreigners, or central bankers. Because admitting that the whole society was participating in a "beauty contest" is hard to reconcile with the notion that wealth can measure intelligence.
French thinker René Girard was particularly fascinated by mimetic behavior and built his theory of cultural mimesis around imitation and scapegoat mechanisms. Later, other scholars introduced this theory into economics.
Peter Thiel studied under Girard at Stanford University and became Facebook's first outside investor. He has also used Girard's theoretical framework to explain that investment. Boom-and-bust cycles fit this theory remarkably well.
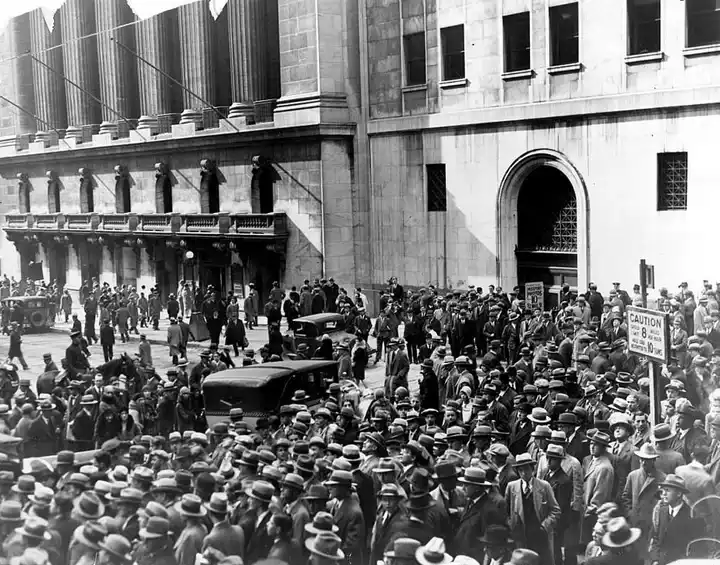
Caption: Crowds gathered outside the New York Stock Exchange after the 1929 crash.
The Internet Bubble and the Housing Bubble: Two Different Driving Forces
The Internet bubble of the late 1990s could be described as the railway mania entering the mouse era.
The Internet did permanently change the world, and the "new era" narrative described by Shiller drove Keynesian expectation games: market participants believed that others would also believe traditional valuation tools were no longer applicable.
From March 2000 to October 2002, the Nasdaq Composite fell 78%, and most listed companies eventually exited the market, but the fiber optic cables buried underground remained.
Amazon was a build-oriented project that successfully survived the lottery-style speculation phase. Pets.com was a lottery ticket sold using the same marketing rhetoric. During the bubble's development, the crowd could not distinguish between the two in real time. And this uncertainty is precisely the foundation on which the "beauty contest" can persist.
The housing boom that followed was driven by a different engine and continuously gained momentum through policy.
In Shiller's view, homeownership was shaped into a national development goal, a contagious social narrative that existed long before it was packaged into structured financial products.
After the dot-com bubble burst, the Federal Reserve eased monetary policy; government-backed mortgage institutions and political pressure combined to expand homebuying financing channels; banks and the shadow banking system took on substantial leverage.
From 2000 to the 2006 peak, U.S. national home prices rose about 85%, then fell 27%. This is the most typical case of Quinn and Turner's warning about bank financing bubble risks.
Crypto: Both Engines Present From the Start
As an asset, crypto has been driven by two speculative engines since its inception.
Bitcoin's founding narrative is essentially a protest against a monetary system that makes holding cash feel like continuously losing wealth. And stablecoins have become a way for residents of cities like Lagos and São Paulo to hold U.S. dollars without needing a U.S. bank account.
As early as May 2020, we noted: "The conditions for broad currency debasement are taking shape before our eyes."
By December of that year, we further called Bitcoin "arguably the asset with the most leveraged exposure to broad currency debasement."
Chainalysis in its latest annual report counted cross-border stablecoin fund flows at approximately $220 billion, up 78% year-over-year. Stablecoins now account for 96% of domestic peer-to-peer transfer value across countries.
And the underlying technology of crypto itself is also a build-out narrative. It carries approximately $300 billion in stablecoins and supports order-book trading systems that never close.
The same crypto asset ticker often carries both narratives. The debate over whether Bitcoin is a technology, a hedge, or a belief will never end, because the communities involved never need to choose among these explanations.
But for the core investment logic of this article, crypto's second role is more important: crypto itself is also a technology that manufactures speculative activity.
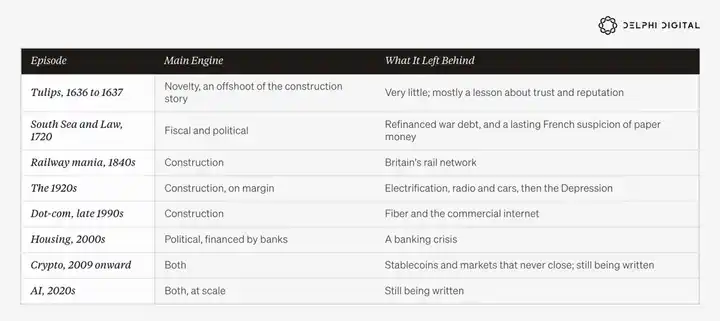
Looking back at the above history, each major speculative mania was primarily driven by one engine.
Tulips, railways, radio, and the internet were all build-out narratives occurring within generally functioning political and monetary systems. The boom of the 1920s relied on borrowed money to drive technological build-out and ultimately ended in a severe crisis.
The South Sea Bubble, John Law's financial system, and the real estate boom were all policy-driven narratives involving little in the way of major new technology.
In these cases, speculative opportunities were sold to the public from the top down, whether the state wanted to refinance government debt or the government wanted to raise homeownership rates.
Cryptocurrency is driven by both forces at once, but until recently its size relative to the overall economy remained small.
Today, two things have changed.
First, both engines are running strong simultaneously. Second, the political and monetary engines are no longer primarily driven from the top down; they are also being strongly driven from the grassroots household level, as more and more households no longer believe the traditional path of life advancement can work.
The second change is an important reason why speculative demand is so broad today.
IV. Two Speculative Engines Running Simultaneously
The Lottery-Type Engine: Housing, Debt, and Employment
After the 2008 financial crisis and again after the 2020 pandemic, policy sent two signals to an entire generation: the purchasing power of cash will steadily erode, and asset market declines will be treated as emergencies requiring public policy intervention.
Fiscal deficits are no longer an occasional condition but have become a normalized policy regime.
In fiscal year 2025, the U.S. federal fiscal deficit reached $1.8 trillion, about 5.8% of GDP, even though the U.S. economy was not in recession at the time. The Congressional Budget Office estimates that the fiscal deficit widened further to about $2 trillion in fiscal year 2026, which ends in September.
Annual net interest payments on U.S. federal debt have now reached about $1 trillion, exceeding defense spending.
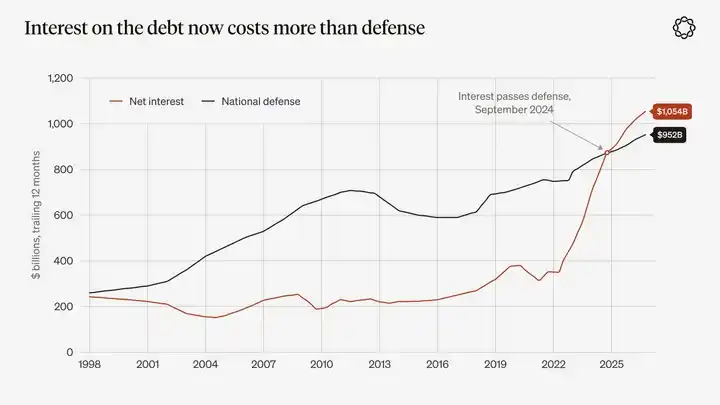
Chart description: U.S. federal government net interest payments and defense spending, trailing 12-month totals. Source: U.S. Treasury Monthly Treasury Statement. Net interest payments first exceeded defense spending in September 2024 and have remained above it since December 2024.
Throughout the 2010s, consumer prices remained broadly moderate, but excess liquidity flowed into asset markets: real estate, long-duration equities, and various scarce assets. After 2020, inflationary pressure appeared simultaneously in consumer goods and asset prices.
Land-use zoning restrictions and insufficient housing supply are important factors explaining the U.S. housing problem. Moreover, since 2008, real interest rates have not been near zero in every year.
But what this article really focuses on is: when wage income can no longer allow a family to buy their first home on the same timeline as the previous generation, what options do they have left?
The Pew Research Center's measurement method is the most intuitive.
From 1975 to 2000, for households headed by persons under age 40, the ratio of median home value to median household income remained at around 2.5 times for an extended period. This ratio reached 3.6 times at the peak of the real estate bubble in 2006, fell back to 2.9 times in 2019, rose again to 3.6 times in 2022, and still stood at 3.5 times in 2024.
The Harvard Joint Center for Housing Studies compared total household income with home sale prices and found that in 2024, the national median sale price of a single-family home in the United States was equivalent to 5 times the median household income. In San Jose, Los Angeles, San Francisco, and Honolulu, this ratio exceeded 10 times.
The latest survey by the National Association of Realtors shows that the share of first-time buyers in total home transactions fell to a record low of 21%, while the median age of first-time buyers rose to a record 40 years old.
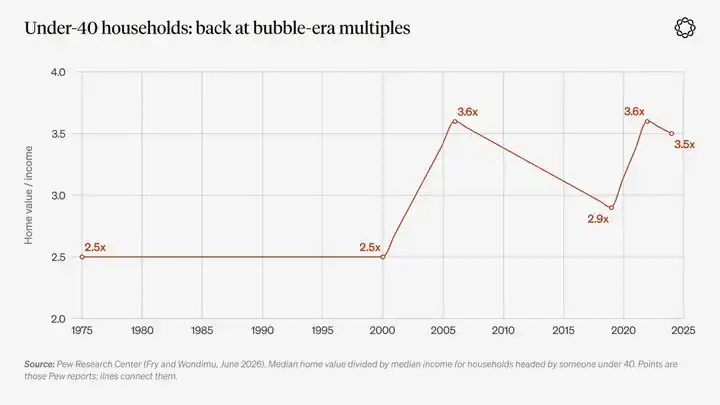
Chart description: Ratio of median home value to median income for households headed by persons under age 40. Source: Pew Research Center, Fry and Wondimu, June 2026.
At such price levels, the economic meaning of saving begins to change. For a family, zero dollars and $10,000 seem to make little difference, because in either case, it is not enough to pay a down payment. But between $10,000 and a home, there is still a huge gap.
In many ways, the old social contract of the past—work hard, accumulate savings, buy a home, and then grow wealth through asset appreciation—has been broken by political and monetary policy choices. This has also changed what ordinary people consider rational behavior.
Young people feel this most strongly, and among them, young men are flooding in large numbers into sports betting platforms, options trading apps, and prediction markets.
The Pew Research Center found that in the past year, 36% of men under age 30 participated in sports betting, compared with 22% of U.S. adults overall. A FINRA Foundation survey shows that among investors under age 35, 43% have traded options; among investors aged 55 and older, this proportion is only 10%.
Biological and cultural factors can explain some of the differences. Even before the current monetary system emerged, young men have always tended to take on higher risks. But the blockage of traditional asset accumulation paths is likely also one of the reasons for the rapid expansion of this behavior, alongside two other factors: the legalization of gambling and the proliferation of smartphones.
In May 2024, when the meme coin craze was at its peak, we described this phenomenon: a generation of young people "facing heavy debt, unattainable housing, and wages rapidly eroded by inflation" for whom "the only way to win this new wealth competition seems to be securing 100x returns."
When people are asked why they choose high-risk investments, their answers are quite direct.
A 2026 Northwestern Mutual study found that among Gen Z respondents attracted to high-risk assets, 80% said they participated because they felt their personal financial situation had fallen behind.
But this does not mean an entire generation has abandoned traditional wealth accumulation methods. The Urban Institute found that only 17% of Gen Z participated in sports betting over the past year, and most young people still use conventional methods to save.
However, this investment theme does not need to attract the vast majority. It only needs a minority of participants large enough, motivated enough, and all equipped with smartphones.
According to data from the American Gaming Association, legal sports betting wagers in the United States increased from $6.6 billion in 2018 to $166.9 billion in 2025.
In May 2018, the U.S. Supreme Court's ruling in Murphy v. NCAA changed the legal landscape for sports betting. Demand already existed, and the ruling provided a legal channel for that demand while creating a new source of tax revenue for state governments.
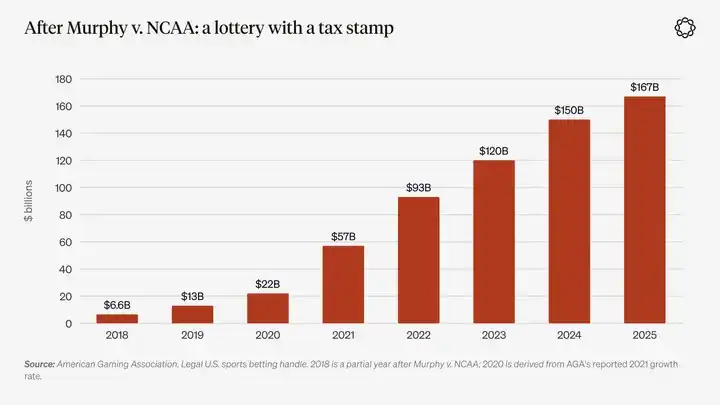
Chart description: Legal sports betting wagers in the United States, source: American Gaming Association. 2018 includes only partial-year data after the relevant ruling; 2020 data is estimated based on the association's published 2021 growth rate.
In the first half of this year, the monetary factor's push toward speculation weakened somewhat. But on August 19, the U.S. Treasury Department announced it would at least double the size of "liquidity support" buybacks of long-term Treasury bonds, reinforcing this factor once again.
On the day the news was announced, Delphi's Scott Freeman called the move: "The same consolidated balance sheet operation as quantitative easing, just executed through a different building."
In October 2025, a JPMorgan research report brought the term "debasement trade" into widespread circulation. A few days later, gold prices broke through $4,000 per ounce.
In fact, we had been discussing this trading logic since 2019. In our December macro outlook that year, we proposed that "a new round of global fiat currency debasement policy is in its early stages."
In January 2025, when gold prices approached $2,700 per ounce, we again called it "one of the most noteworthy charts right now."
In January 2026, gold prices peaked near $5,600 per ounce. Since then, gold has given back about a quarter of its gains, the Federal Reserve implemented its first rate hike since 2023, and the 10-year U.S. Treasury yield closed above 5.3% in early October, the highest level in more than two decades.
Holding cash can now once again earn a certain return, and those who interpreted the debasement trade as a one-way gold rally have also accepted the market correction.
But higher interest rates have not reopened the traditional ladder of wealth accumulation. For homebuyers facing home prices at 3.5 times household income, higher rates mean mortgages are even harder to afford.
Meanwhile, the U.S. economy is at full employment, yet the fiscal deficit remains close to 6% of GDP. The government now needs to refinance debt at higher interest rates, while rapidly expanding AI financing demands are competing for the same pool of savings.
Therefore, today's lottery-style speculation engine no longer relies primarily on gold, but is built more on housing, employment, and fiscal pressure. And AI is simultaneously affecting all three areas.
The Buildout Engine: The Largest Wave of Private Capital Construction in Decades
This decade's buildout narrative has a clear name: AI. Or should it now be called SI (Superintelligence)?
Regardless, Microsoft, Alphabet, Amazon, and Meta collectively spent approximately $416 billion in capital expenditures in 2025, up about two-thirds from 2024.
Based on the guidance issued by these four companies, their total capital expenditure for 2026 is projected to be between $720 billion and $745 billion, and that does not yet include Oracle's spending.
That scale is equivalent to roughly 2.3% of U.S. GDP, although some of the investment occurs overseas and a large amount of hardware must be imported. That ratio is more than double the roughly 1% of GDP seen at the peak of the telecom investment boom, and it is on the same order of magnitude as U.S. railway investment in the 1870s and 1880s. Today, what underpins this investment boom is mainly the balance sheets of four companies.
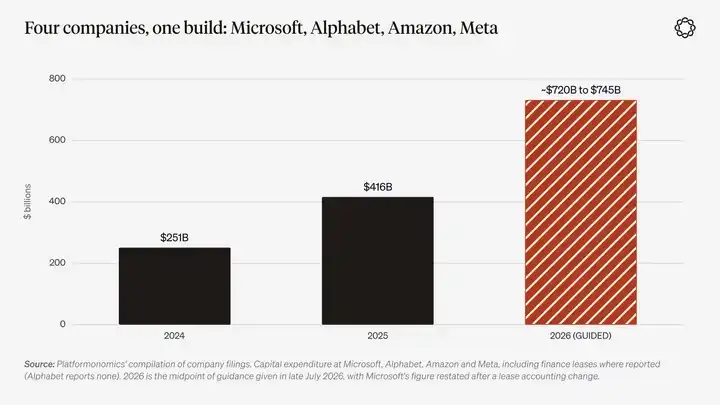
Chart note: Capital expenditure by Microsoft, Alphabet, Amazon and Meta, including disclosed finance lease spending. Data for 2024 and 2025 come from Platformonomics' aggregation of corporate financial reports; 2026 uses the midpoint of company guidance from late July of that year.
Economist Jason Furman calculated that in the first half of 2025, investment in information processing equipment and software contributed 92% of U.S. GDP growth. However, that figure is a gross contribution.
Because a large amount of hardware relies on imports, economists at Goldman Sachs and the Federal Reserve point out that after excluding imports, the net contribution is much smaller.
In any case, the scale of this construction wave is already large enough to force the entire economic system, the power grid and the government to allocate resources around it.
Soros might argue that there is indeed a real underlying trend here: the expansion of computing power and electricity infrastructure. But at the same time, there may also be a mistaken belief: the market believes that the relevant revenue will be realized on a timetable that matches asset depreciation.
Rising asset prices provide financing for more construction projects, and continuously increasing investment makes the original narrative look more credible.
In the end, most equity investments may prove as disappointing as railway stocks did in their day, but some of the infrastructure formed by capital expenditure will still remain for the long term, just as the railway network ultimately survived.
The most intuitive investment strategy is to directly hold the core assets in this construction wave, including power, chips, and ultimately the AI labs that survive.
From the perspective of what can remain after the boom ends, this approach is correct. We will also discuss this issue more directly in subsequent reports in our annual outlook series. But this strategy ignores the impact of the construction wave on all bystanders.
The more future possibilities a technology creates, the greater the demand for financial contracts that allow people to bet on different future outcomes.
Perpetual futures, same-day expiry options, and event contracts centered on chip stocks, interest rate decisions, and AI news are precisely how investors are coping with this uncertainty. After all, no one can know in advance which of the companies participating in AI infrastructure buildout today will become the next Amazon and which will become the next Pets.com.
Where Two Engines Intersect
In most speculative episodes of the past, the technology engine and the political engine largely ran on separate tracks. But today, the scale of the AI buildout wave is large enough to drive both simultaneously.
It works primarily through four channels: electricity bills, government, the bond market, and the job market.
The first channel is electricity bills.
In 2023, data centers accounted for about 4.4% of U.S. electricity consumption. Lawrence Berkeley National Laboratory currently projects that by 2030, this share will approach 12%.
The PJM grid covers 13 U.S. states and Washington, D.C., serving approximately 67 million people. The grid holds auctions every year to set prices for future generation capacity.
For the 2024/25 delivery year, the capacity market cleared at $28.92 per megawatt-day. For 2025/26, that price jumped to $269.92, and has since remained near the price cap of about $330.
PJM's independent market monitor noted that data centers alone contributed $9.3 billion in additional costs in the first round of sharp price increases.
Over the five years through March 2026, U.S. residential electricity prices cumulatively rose about 40%. Grid upgrades and fuel prices were the main drivers, with capacity market price increases accounting for a growing share.
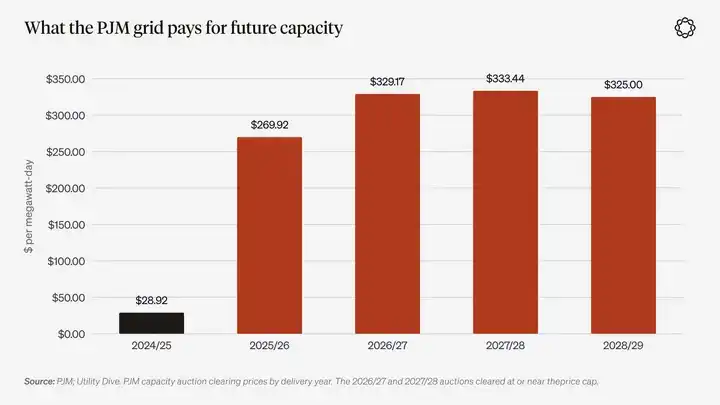
Chart description: PJM capacity market auction clearing prices by delivery year. The 2026/27, 2027/28, and 2028/29 years all reached the price cap. Source: PJM, Utility Dive.
The electricity bill issue quickly evolved into a political one.
In November 2025, New Jersey and Virginia elected governors who made electricity costs a core campaign issue. New Jersey Governor Mikie Sherrill pledged to declare a "utility cost emergency." Virginia Governor Abigail Spanberger pledged to require data centers to bear their own electricity costs.
In January of this year, the U.S. President posted that the American public should not "foot the bill" for this. Subsequently, Microsoft committed to fully covering its own electricity costs and reducing its use of local tax incentives.
In fiscal year 2025, Virginia's sales tax exemption for data centers cost the state $1.6 billion in tax revenue.
Local organizations opposing data center construction are found almost everywhere. According to Data Center Watch, in the first quarter of 2026 alone, data center projects that were blocked or delayed reached approximately $130 billion in scale.
On September 29, the U.S. Federal Energy Regulatory Commission (FERC) only partially approved PJM's backup proposal for procuring additional power for data centers and required modifications to the cost allocation mechanism.
The commission chairman stated that regulators "will not be forced to accept a procurement mechanism that is seriously flawed, hastily proposed at the last minute, and could have a multibillion-dollar impact on consumers."
The pattern that has emerged here is: the claim to returns belongs to private enterprises, but part of the costs of electricity, transmission lines, and even power plants ultimately enters public or quasi-public sector accounts and is paid through user electricity bills, tax breaks, and tax credits.
The narrative supporting this arrangement is that this infrastructure is necessary for national competition.
The South Sea Bubble was the exact opposite direction, packaging public debt into private equity and selling it to the public. But there is a clear family resemblance between the two: the private sector enjoys the potential returns, while the public sector's balance sheet provides support.
Real estate achieved this through mortgage loans, while AI has achieved a similar mechanism through the power grid.
Of course, this arrangement is encountering opposition. AEP in Ohio now requires large data centers to pay for at least 85% of their reserved capacity. Governors in the PJM region also want data centers to bear the cost of additional power supply.
Therefore, the current focus of debate is how much cost should be reallocated to data center operators.
The second channel is the change in the government's role.
The government is no longer just the regulator of the AI construction wave, but has begun to directly hold some of these assets.
In August 2025, the U.S. federal government acquired a 9.9% stake in Intel, with funding mainly coming from previously undisbursed CHIPS Act subsidies.
Nvidia and AMD agreed to pay the government a share of their China chip sales revenue in exchange for export licenses. The initial agreed ratio was 15%; when Nvidia's H200 was approved for export in December of that year, the ratio was raised to 25%.
The U.S. government described its "Genesis Mission" as "comparable to the Manhattan Project in urgency and ambition." The government also ordered an acceleration of approvals for large data centers.
In December 2025, the U.S. government began challenging state AI laws through judicial channels. Previously, the Senate had voted 99 to 1 to remove a provision pausing the implementation of state-level AI laws from the budget bill.
Meanwhile, an AI industry super PAC called Leading the Future was established, with initial funding exceeding $100 million. In just one House primary in New York State in June of this year, groups on both sides of the AI issue collectively spent more than $27 million.
When a government begins holding equity stakes in chipmakers and likens AI infrastructure buildout to the Manhattan Project, it is effectively sending a signal to the market: the government will not allow this round of buildout to fail.
This is almost equivalent to providing a policy put option protection for the construction-driven speculative narrative. At the same time, in every constituency with a data center, AI has become an issue that genuinely influences elections.
The third channel is the bond market.
As of early August 2026, large tech companies had issued approximately $220 billion in bonds that year, exceeding the full-year issuance volume of 2025.
Meta's $27 billion financing raised for the Hyperion data center is the largest private credit transaction in history, and it adopted a structure that is not recorded on Meta's balance sheet.
This autumn, as the U.S. 10-year Treasury yield rose above 5%, AI companies' borrowing demand became one of the factors cited by the market to explain the rise in yields.
In its May "Financial Stability Report," the Federal Reserve relayed market participants' concerns: "Capital expenditures are increasingly financed by debt, which is raising the leverage level of the financial system."
The private sector's AI investment boom and government debt are competing for the same pool of savings.
The fourth channel is wages and employment.
In August 2026, Erik Brynjolfsson of Stanford University and his co-authors updated their research paper "Canaries in the Coal Mine."
The study found that in occupations most exposed to AI, employment levels among young people aged 22 to 25 were 19% lower than they would have been had their employment growth kept pace with peers with lower AI exposure. The researchers emphasized that this is a descriptive finding, not proof of causality.
New York Fed data show that the unemployment rate for recent college graduates is 5.6%, compared with about 4.2% for all workers. This gap began widening as early as 2019, before the advent of ChatGPT, so AI is clearly not the whole story.
According to career consulting firm Challenger, Gray & Christmas, in the first nine months of 2026, companies cited AI as the reason for about 120,000 job cuts in layoff announcements, more than double the full-year total for 2025.
Of course, some of these companies were likely just repackaging routine layoffs as AI-driven restructuring.
In 2025, Anthropic CEO Dario Amodei warned that AI could eliminate half of entry-level white-collar jobs.
A Pew survey this summer showed that 73% of adults under 30 believe AI will mean fewer job opportunities.
No research has yet directly proven a link between AI-induced job anxiety and sports betting or same-day expiry options trading. Therefore, the connection proposed in this article is an argument built on multiple independent pieces of evidence, not a causal conclusion that has been directly confirmed.
Nevertheless, the evidence does point in the same direction.
On one hand, the AI buildout wave has given the market its grandest technology buildout narrative in decades; on the other hand, it is driving up household electricity bills, pushing governments to directly participate in equity investment and industrial policy, competing with the U.S. Treasury for savings funds, and leaving a 23-year-old worried about whether the entry-level jobs that should serve as the starting point of a career will still exist in the future.
In July this year, Delphi Ventures posed a question: who will bear the liabilities left behind by this aging and debt-laden world?
The answer they gave was: "The most obvious and most likely solution is a combination of currency devaluation and accelerated automation."
AI may be the first major technology boom in history to simultaneously power both lottery-style speculation and building-style speculation so directly.
Everything Converges on a Single Phone
One thing that was impossible in the 19th century was to place building-style investment bets and lottery-style speculation in the same venue. Railway prospectuses and betting shops existed in different buildings in different parts of the city.
But today, a 25-year-old can, between two phone notifications, bet separately on chipmakers, gold, football matches, and central bank rate decisions. In his experience, there is no essential difference between these four activities: all are about making a judgment on something and hoping that judgment ultimately pays off.
Financial products are also adapting to this demand.
In 2022, the Chicago Board Options Exchange (Cboe) completed the rollout of S&P 500 index options contracts expiring every trading day.
As a share of total SPX options volume, same-day expiring options (0DTE) rose from about 5% in 2016 to 45% in 2023, and reached 59% in 2025. In July 2026, that ratio set a single-month record of 66%.
According to Cboe's own estimates, individual traders contributed more than half of customer volume in such contracts.
Part of this growth is a mechanical result: when contracts expire every trading day, same-day expiring options naturally exist every day. But the reason Cboe added these expirations is precisely that there was sufficient market demand.
In June 2026, regulators also eliminated the $25,000 minimum account equity requirement for pattern day traders, further lowering the barrier to participation.
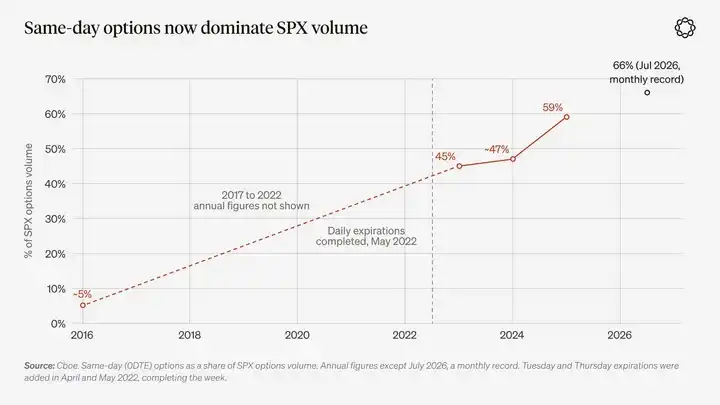
Chart caption: Same-day expiring options as a share of SPX options volume. Source: Cboe. Except for July 2026, which is a single-month record, all other figures are annual data.
Event contracts go even further.
In mid-2025, the combined monthly trading volume of Kalshi and Polymarket was about $2 billion. According to Pew Research Center's analysis of The Block data, by May 2026, the trading volume of the two platforms had reached $25.7 billion, rising to $47.7 billion in June and further to $53 billion in July.
This means that July 2026 trading volume was approximately 25 times that of the same period in 2025.
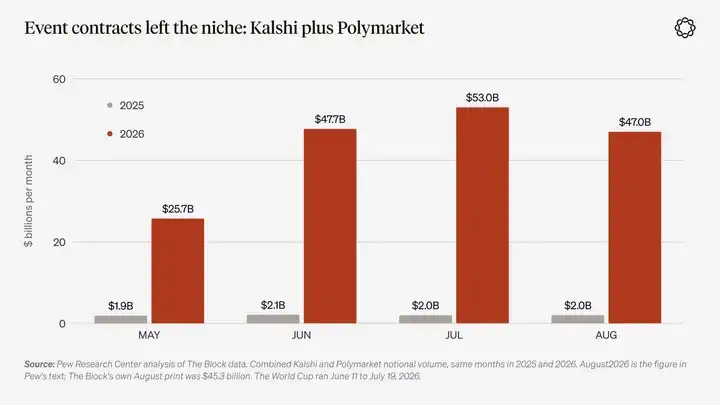
Chart description: Comparison of nominal trading volume between Kalshi and Polymarket in the same months of 2025 and 2026. Source: Pew Research Center, The Block. The 2026 World Cup was held from June 11 to July 19.
The latest generation of trading apps goes a step further, putting crowd behavior directly on users' screens.
Fomo, a crypto trading app launched in May 2025, is designed around showing other users' verified real trading activity. Users can follow other traders, view their buys, sells, and realized P&L, and trade directly within the same interface.
Fomo's perpetual futures trading is executed through Hyperliquid, the largest on-chain perpetual futures exchange. As a result, this social front end is already built on the infrastructure of an on-chain trading platform.
The company said that as of June 2026, its user base had surpassed 600,000, with cumulative trading volume exceeding $4 billion. That month, the company completed a $75 million funding round at a reported valuation of $550 million.
Its payment partner Crossmint said that approximately 68,000 first-time crypto buyers funded their accounts through the Apple Pay settlement channel.
Keynes's beauty contest asks participants to guess how others will choose. Social trading feeds, by contrast, let users see in real time what choices others are making.
Sports betting, casino apps, social trading, meme coins, and same-day expiry options are typically seen as five unrelated phenomena, each triggering its own moral panic.
But a more accurate way to understand them is as manifestations of the same demand across different products.
In an era when two major speculation engines are running simultaneously, people can turn any expectation into a trade with just a few seconds on their phone.
What has crypto brought?
If AI mainly gives people reasons to speculate, then crypto gives them the tools to speculate—and in the process continuously draws in new speculators.
First, the cost of initiating a speculative trade.
In the past, creating a new tradable asset required lawyers, an exchange listing process, and months of preparation. Today, on Solana ecosystem meme coin launchpad pump.fun, issuing a token costs less than $2.
Since January 2024, the platform has created over 19 million tokens. By late September this year, a typical trading day saw about 33,000 new token issuances.
But only about 1% of tokens manage to break past the platform's initial bonding curve trading phase, and most tokens stop trading on the day they are issued.
The process of creating trading markets for arbitrary assets is undergoing a similar transformation. Today, on Hyperliquid, anyone who stakes a sufficient amount of assets can create a perpetual futures market for virtually any underlying.
This supply expansion has far outstripped the crypto asset space.
According to TokenInsight data, monthly trading volume for equity, commodity, and forex perpetual contracts offered by crypto exchanges grew from about $52 billion in January 2026 to about $268 billion in June.
Binance alone has listed perpetual contracts on underlyings including gold, Tesla, the not-yet-public SpaceX, and the Brazilian real.
This summer, markets deployed by third-party builders accounted for between roughly a quarter and more than half of Hyperliquid's trading volume.
The tokenized equity market remains relatively small. According to rwa.xyz, its total value is about $3.2 billion, but it is growing.
Notably, these changes are occurring as total crypto market capitalization had shrunk by about half from its 2025 high by June this year. This suggests that market demand is not entirely for crypto itself, but equally for this trading structure.
Traditional finance is also evolving toward similar structures.
The Chicago Mercantile Exchange Group (CME) began offering 24/7 trading of crypto futures and options in May this year.
In the same month, the U.S. Commodity Futures Trading Commission (CFTC) approved Kalshi's bitcoin perpetual contracts and issued a policy statement on perpetual contracts.
After that, Kalshi launched gold and silver perpetual contracts in September, index perpetual contracts in October, and filed an application for single-stock perpetual contracts.
The Depository Trust & Clearing Corporation (DTCC) began offering round-the-clock clearing services on weekdays in June.
Nasdaq plans to launch overnight trading in December. In September, the U.S. Securities and Exchange Commission (SEC) opened an exemption channel for trading tokenized stocks on public blockchains.
These changes are all pushing traditional markets toward the models that crypto trading venues have offered for years.
Crypto is also constantly creating new speculators.
A survey jointly published by the CFA Institute and the FINRA Foundation in 2023 showed that 44% of U.S. Gen Z investors made crypto their first investment, a higher proportion than those who made individual stocks their first investment.
A Bank for International Settlements (BIS) study covering 95 countries found that rising Bitcoin prices attract new users to crypto trading apps, about 40% of whom are men under 35.
Airdrops play a similar role on a smaller scale.
A recent study found that wallets that received BONK airdrops were about 80% more active in trading on Solana than similar wallets that did not receive airdrops, and were more inclined to trade higher-volatility tokens.
Even if the tokens obtained from airdrops themselves depreciate, this behavioral change still persists.
Profits generated within the crypto market also often become the purchasing power for the next rally. From October 2023 to March 2024, SOL rose from about $20 to about $200. The Solana meme coin boom also developed alongside this rally.
This cycle also reinforces the trading platforms themselves.
Platforms distribute tokens to traders to attract users, traders pay fees, and the platforms then use fee revenue to buy back their own tokens.
In 2024, Hyperliquid distributed 31% of the HYPE tokens through an airdrop, attracting a group of traders. Since then, the fees paid by these traders have supported the platform in buying back more than $1.3 billion worth of HYPE.
However, the costs of speculative activity are equally obvious.
On October 10, 2025, the crypto market liquidated approximately $19 billion in leveraged positions within 24 hours, involving about 1.6 million traders, with the scale of liquidations exceeding that of the COVID crash by more than tenfold.
As of January 2025, only about 0.4% of pump.fun wallets had realized profits exceeding $10,000. Research by the Bank for International Settlements estimated that by the end of 2022, about three-quarters of retail users may have lost money on their first Bitcoin investment. Wash trading and volume farming for incentives have also inflated reported trading volumes in this sector.
CoinGecko data shows that the share of profitable wallets on pump.fun rose in 2026, but this statistic only counts realized trades and includes trading bots.
Meanwhile, the Federal Reserve's household survey still shows that U.S. crypto usage remains below 2021 levels.
Like sports betting, this investment logic does not depend on the majority of society, but on a minority group with strong motivation to participate. For them, crypto makes speculation cheaper, faster, and more global. And BIS data indicates that when prices continue to rise, this group will expand further.
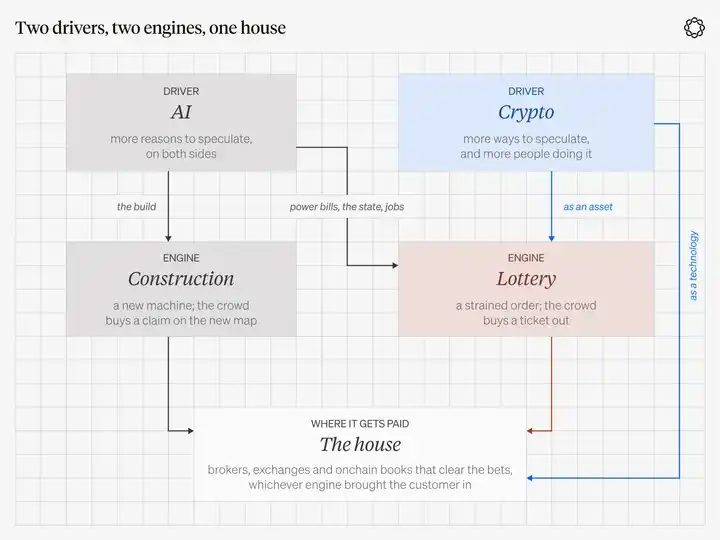
Chart caption: Two driving forces, two major engines, ultimately converging on the same type of trading platform. AI mainly provides the reasons for speculation; crypto provides the tools for speculation, as well as some new participants.
V. Invest in the "House," Not Betting on Winners
If speculation is society's response to a certain gap, and today two gaps exist simultaneously, then the objects people bet on will keep rotating.
What was a hot target in a construction-oriented investment story last year may become a lottery ticket next month.
The businesses that truly do not need to pick winners are the platforms that enable all these targets to be listed and traded.
Casinos need the roulette wheel to keep spinning. Whether players truly understand the odds of winning does not matter to the casino.
Exchanges need market disagreement, leverage, and a fee take rate that can be sustained amid competition. Whether the story behind the traded asset ultimately comes true is not that important.
Graham wanted the public to always remember whether they were participating in investment or speculation. For the house, it collects fees regardless of whether traders ultimately profit or lose.
Of course, a reasonable objection is that the "invest in the house" strategy sounds too simple. History supports this skepticism.
In the past, the United States had street-corner trading venues known as "bucket shops." Customers could bet on the rise and fall of stock and grain prices there without actually buying those assets.
In 1905, the U.S. Supreme Court ruled against them, allowing legitimate exchanges to cut off the market data sources these bucket shops relied on to operate. By the 1920s, state laws had ultimately put an end to this business model entirely.
In October 2026, Papertrade launched on Hyperliquid's HyperEVM, allowing traders to bet against a shared pool of funds on the platform. Critics have already compared it to the bucket shops of history.
Island was once an electronic order-book trading platform that helped break the quote-spread monopoly among Nasdaq's traditional market makers, but it was ultimately integrated into Instinet and then into the Nasdaq system.
FTX was also a house. Stock trading commissions ultimately were driven down to zero through competition.
Therefore, holding a trading platform is truly investment-worthy only under one condition: the platform must possess a franchise advantage that is difficult to replicate.
This means it must have distribution channels that competitors cannot easily take away; an order book that can remain open when other markets are closed; the ability to adjust its product mix as speculators' interests change without losing customers; and fees that can genuinely be collected on a sustained basis, rather than revenue disguised by subsidies and incentive programs.
Moreover, the house only makes money when traders continue to participate in the market. Trading platform revenue is cyclical.
In the second half of 2025, Hyperliquid's average monthly fee revenue was approximately $109 million, while its average monthly fee revenue so far in 2026 is approximately $71 million.
Robinhood's cryptocurrency business revenue fell 38% year-over-year in the second quarter.
Therefore, investing in the house also means bearing the risk of cyclical fluctuations in trading volume. Valuation matters equally. Even if the entire investment thesis holds, investors who buy a trading platform at a high valuation multiple corresponding to peak trading volume when volume peaks may still ultimately suffer losses.
What Does Investing in the House Really Mean?
Investing in the house means owning the matching engines, brokerage accounts, and distribution channels that turn market opinions into actual trades—rather than betting on those opinions themselves.
The easiest way to destroy this investment logic is to fill your portfolio with the speculative instruments listed on trading platforms: AI labs, memes, cryptocurrencies, or sports teams.
These are exactly what the speculative crowd bets on directly—and exactly what ultimately leaves the speculative crowd holding losses.
Right now, the house has another advantage: it doesn't care which speculative engine attracts customers.
A regulated brokerage can sell stock options to customers at 10 a.m., offer event contracts when a sports game kicks off, and provide crypto trading pairs on Sunday night.
It can earn revenue from both constructive speculation and lottery-style speculation without needing to distinguish between the two.
Likewise, an on-chain perpetual futures exchange can offer crude oil trading while traditional markets are closed, while simultaneously listing stock index, gold, and crypto contracts—serving speculators who are not bound by traditional trading hours.
This investment logic doesn't require predicting what the next hot narrative will be. It only requires believing that new market narratives will keep emerging—and that these narratives will always need a venue where they can be traded.
Delphi's expertise lies in crypto. Therefore, the analysis in the rest of this chapter will focus more on crypto markets, setting the stage for our upcoming annual outlook series.
But this investment theme itself is not confined to any single asset class—trading platforms in traditional finance should equally be included in the examination.
Cboe holds a competitive advantage in S&P 500 same-day expiry options.
CME provides the contracts powering FanDuel Predicts, which launched in all 50 U.S. states in January of this year.
DraftKings migrated its prediction product to its own exchange in June.
Coinbase offers prediction market trading through Kalshi. Since acquiring Deribit for $2.9 billion in August 2025, Coinbase also owns the world's largest crypto options exchange.
Interactive Brokers operates ForecastEx.
These companies all have relatively mature business models and strong competitive moats.
On-chain trading platforms are worth watching for a different set of reasons. They can list virtually any asset, operate 24/7, and serve global customers. Take Hyperliquid, for example: nearly all protocol fee revenue is used to buy back the platform token.
As a result, on-chain trading platforms offer investment exposure with higher beta to the same speculative demand—albeit with correspondingly higher risk.
Robinhood: How Diversified Trading Products Generate Revenue
In Q2 2026, Robinhood broke out event contracts as a separate revenue line for the first time.
The business generated $156 million in revenue for the quarter, surpassing equities trading at $129 million and crypto trading at $100 million.
Options remain the largest trading-related revenue source at $342 million. Total net revenue for the quarter reached $1.31 billion.
Just a year earlier, the event contracts business was generating only about $10 million in quarterly revenue.
Robinhood says that of its 28.4 million funded customers, nearly 2 million have used event contract products—a penetration rate of about 7%.
In September, when Morgan Stanley upgraded Robinhood's stock, it specifically highlighted the large gap between this penetration rate and the overall customer base.
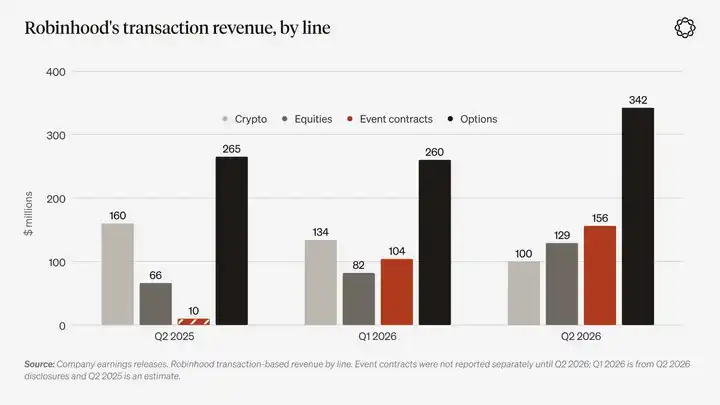
Chart description: Robinhood's trading-related revenue by business category. Source: Company filings. Event contracts were not separately disclosed until Q2 2026; Q1 2026 data comes from Q2 2026 earnings disclosures, and Q2 2025 data is estimated.
Customers want a place where they can express their market views and profit from them.
In the previous cycle, crypto played this role. For years, options had served a similar function. And in this cycle, event contracts have become the new vehicle.
If event contracts can continue to contribute about one-fifth of transaction-related revenue with customer penetration below 10%, there is still ample room to convert bystanders into actual traders.
If the cryptocurrency market strengthens again, related trading demand will also flow into the same batch of customer accounts.
In regulated financial markets, the value of a market maker comes from a portfolio of multiple trading products. Investors should hold this business portfolio precisely because no one can know in advance which type of product will be most active in the future.
However, legal disputes are a real and still-evolving risk.
In April this year, the U.S. Third Circuit Court of Appeals ruled in favor of Kalshi in its lawsuit with New Jersey.
But in August, the Ninth Circuit Court of Appeals reached the opposite conclusion. In the Kalshi case and the related case filed by Robinhood, the court determined that sports event contracts are not swaps, so Nevada can apply its state gambling laws to them.
In September, the Sixth Circuit Court of Appeals also ruled against Kalshi in cases involving Ohio and Tennessee.
Currently, both New Jersey and Robinhood have filed petitions with the U.S. Supreme Court requesting it to take up the relevant legal disputes.
Robinhood has stopped offering sports event contracts in Nevada and agreed to stop launching new sports event contracts in Michigan. In September, the Missouri Attorney General also sent cease-and-desist letters to six platforms.
If courts ultimately restrict the development of the event contracts business, the relevant customers will still remain within Robinhood's options trading and securities brokerage system. This would make the investment thesis more complicated, but would not completely overturn it.
In addition, the $156 million in event contracts revenue in the second quarter may also have partly benefited from the trading boom brought by the World Cup.
Robinhood will report third-quarter results on October 27.
Data in the coming quarters will help investors judge whether the current product penetration rate of about 7% means a new business is just getting started, or whether the popularity of a novelty product has already peaked.
Hyperliquid: A Trading Market Without a Listing Review Committee
The emergence of on-chain perpetual contracts is like railway prospectuses suddenly no longer requiring parliamentary approval.
Eleven days after the HYPE token launch, we published our "Year Ahead for Markets 2025" and listed Hyperliquid as one of our core investment themes.
At the time, we wrote that Hyperliquid "wants to become synonymous with what people think of as 'on-chain Binance.'"
In 2025, Hyperliquid's trading volume was approximately $3 trillion, with traders paying a total of about $972 million in fees.
According to DefiLlama, after deducting fees paid to ecosystem builders and other revenue shares, approximately $818 million of that constituted protocol revenue.
Nearly all protocol revenue flowed into the Assistance Fund, which used it to buy HYPE on the secondary market and remove it from circulation.
In the first nine months of 2026, platform fee revenue was approximately $643 million, growing at a slower pace than the second half of 2025. This serves as another reminder to investors that trading platform revenue will still fluctuate with crypto market sentiment.
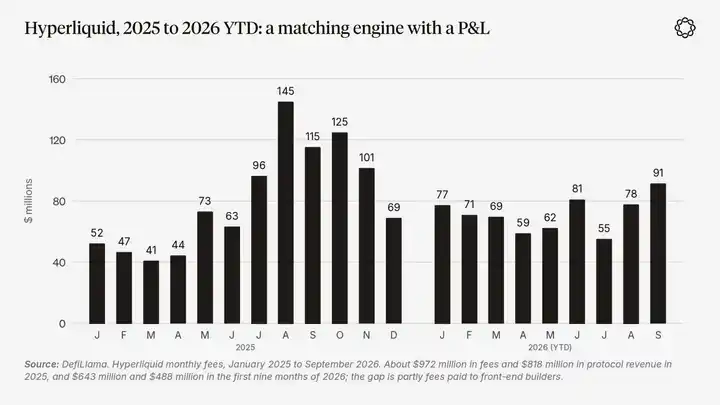
Chart description: Hyperliquid monthly fee revenue from January 2025 to September 2026. Source: DefiLlama. Fee revenue in 2025 was approximately $972 million, with protocol revenue of approximately $818 million; in the first nine months of 2026, they were approximately $643 million and $488 million respectively. The difference between the two comes partly from fees paid to frontend builders.
What truly fits the "two major speculation engines" logic of this article is HIP-3, not just Hyperliquid's original cryptocurrency business.
Since October 2025, anyone who stakes 500,000 HYPE can deploy their own perpetual contract market on Hyperliquid and retain up to half of the trading fee revenue.
The largest deployer currently is trade.xyz. The platform offers trading in crude oil, Brent crude, gold, silver, stock indices, individual stocks, and assets related to private companies.
According to statistics from various data tracking platforms, in the 30 days ending October 6, trade.xyz's trading volume was approximately $47 billion to $58 billion.
On Saturday, February 28, when the U.S. and Israel launched strikes on Iran, CME had not yet opened, but crude oil perpetual contracts on Hyperliquid were still trading.
JPMorgan later noted that the platform's single-day peak trading volume in crude oil had reached $1.7 billion.
Traders discovered that there was also an open crude oil trading market on Saturday and entered to trade. If this behavior persists, Hyperliquid's business cycle could change. Because cryptocurrency perpetual contracts primarily fluctuate with market risk appetite, while the activity of commodity and stock index order books is more influenced by news events and overall economic trading demand.
Of course, risks remain, and they are not complicated. Fee take rates could decline due to competition. HIP-3's growth model has already reduced fees for new markets by 90% or more to attract trading volume. Traders may wash trade to earn undetermined points rewards. A single deployer could also dominate the entire market. In Q2 2026, trade.xyz accounted for approximately 95% of HIP-3 trading volume. Regulation could also prevent U.S. customers from accessing these order books.
Moreover, even if a token is bought back using fee revenue, it is still not equity in the trading platform.
HYPE simultaneously sits on both sides of the first investment principle discussed later: on one hand, it represents indirect exposure to the trading platform's economic returns; on the other hand, for most holders, it remains an asset held by the speculative crowd, with its price fluctuating with crypto market sentiment.
Hyperliquid is worth highlighting in this article because it provides the clearest, already-operational case: a trade matching engine attempting to become a comprehensive exchange capable of trading virtually all assets—which is precisely the market form that the two major speculative engines operating together point toward.
Lighter: Why Can the Market Accommodate More Than One Trading Platform?
Only one trading platform succeeding might just be a story about a single company. But if multiple platforms succeed simultaneously, it indicates that real market demand exists.
According to DefiLlama's 30-day trading volume statistics from early October, Hyperliquid was approximately $203 billion, Variational was $66 billion, Aster was $60 billion, and Lighter was $56 billion.
Beyond that, there are plenty of smaller players. Some of that volume comes from incentive-driven wash trading. In October 2025, DefiLlama removed Aster from its rankings due to concerns about its volume data. But even after applying a meaningful haircut to that volume, the on-chain perpetual futures market is still large enough to support multiple winners.
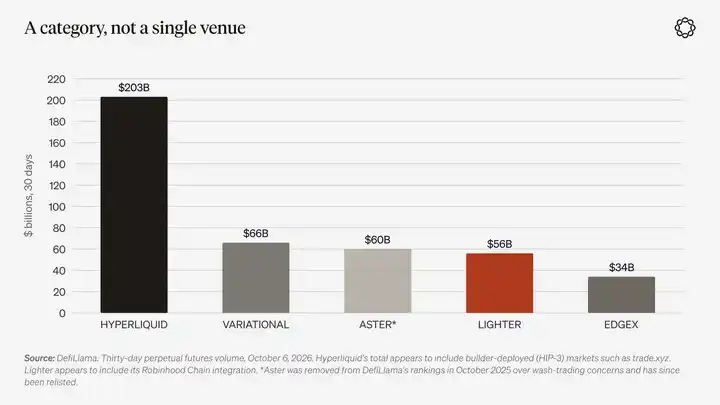
Chart caption: Perpetual futures volume over the past 30 days as of October 6, 2026. Source: DefiLlama. Hyperliquid's total volume appears to include markets deployed via HIP-3 such as trade.xyz; Lighter's data appears to include its Robinhood Chain integration. Aster was removed from DefiLlama's rankings in October 2025 amid wash-trading concerns, then relisted.
Lighter is currently the clearest second investment candidate.
It operates an order book whose matching results can be verified via zero-knowledge proofs, charges no trading fees on standard accounts, and offers equities, commodities, and FX trading beyond crypto.
Robinhood participated in Lighter's funding round in November 2025.
Since July of this year, the perpetual futures trading that Robinhood Wallet offers to users outside the U.S. has been executed through Lighter on Robinhood Chain under a revenue-sharing model.
Lighter's LIT token launched in December 2025.
Because retail users can trade for free, Lighter must rely on premium accounts, distribution partnerships, and the economic value the token can capture to generate revenue.
On September 20, a code commit titled "Binary options support" appeared in Lighter's proof-system codebase. The update added outcome-based positions and their settlement functionality.
Of course, a feature appearing in a code repository doesn't mean it has commercial value. That code only becomes truly meaningful once real liquidity shows up on the other side of the market.
But it at least shows where Lighter believes future market demand is heading.
Event Contracts: Financial Products Designed for the Smartphone Era
Prediction market contracts and options represent two different types of payoff claims.
In prediction markets, traders buy "Yes" or "No" contracts on a fact that will be verified on a specific date. The contract price can be understood as the market's pricing of the probability of the event occurring. Traders lose at most the cost of the contract they paid, do not bear funding rates, and do not face forced liquidation.
From a social function perspective, these products are very close to lottery-style speculative engines. People already form their own judgments about sports games, elections, inflation data, or asset prices, and prediction markets allow them to convert those judgments into potential returns before the facts are ultimately revealed.
Compared with many previous financial products, prediction markets are especially suited to mobile trading. Because the same account can hold long-term event judgments and also participate in a Saturday afternoon sports bet.
In January 2023, when we first wrote about prediction markets, Kalshi was still "preparing to launch" related products, while Polymarket had just paid a CFTC fine and stopped serving U.S. users.
Today, Kalshi has become a licensed prediction market trading platform in the United States. The company is reportedly seeking to raise funding at a valuation of approximately $40 billion.
Polymarket is a global prediction market platform that many people now even regard as a news source. The platform re-entered the U.S. market in late 2025.
Robinhood plays the role of distributor and has already found that revenue generated by event contracts can exceed its cryptocurrency business.
Together, these platforms prove that demand for prediction markets has far exceeded the cryptocurrency space.
The most common objection is that so-called prediction markets are actually just sports betting under another name.
The Pew Research Center analyzed trading volume data from July 2024 to April 2026. The results showed that sports-related contracts accounted for 80% of Kalshi's trading volume and 39% of Polymarket's trading volume.
This summer, the share of sports trading rose further. The Pew Research Center noted that this growth cannot simply be attributed to the World Cup.
If this trading structure persists, then prediction markets may in fact be merely a better-branded, federally regulated sports betting platform.
But even so, the "investing in the house" logic still holds. It's just that it will be an investment logic about gambling trading infrastructure, not about information markets.
The real test is: when the sports calendar is no longer dense, can political, macroeconomic, and corporate event markets continue to grow?
If not, investors should size their positions according to the logic of sports betting infrastructure.
The quality of market trading volume also deserves attention.
The Wall Street Journal reported that the CFTC is investigating allegations of wash trading at Kalshi. Kalshi denies the allegations and is terminating its volume incentive program.
This is another reminder to investors that some of the trading volume disclosed across the industry is actually bought through incentives.
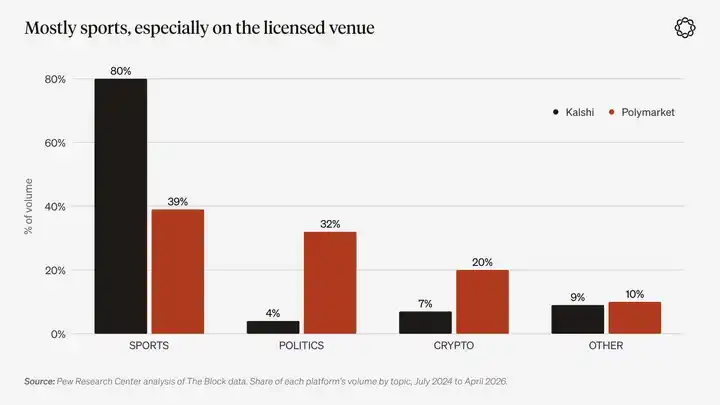
Chart caption: Share of trading volume by theme for Kalshi and Polymarket, July 2024 to April 2026. Source: Pew Research Center analysis of The Block data.
HIP-4 is Hyperliquid's market for event contracts, and is the implementation of such products in a permissionless on-chain environment.
It runs on Hyperliquid alongside the perpetual futures market, uses the same collateral, and typically settles on a 0 or 1 outcome.
On May 2, 2026, curated event markets officially launched. The first product was a daily-settled Bitcoin binary contract, settling at 06:00 UTC.
On August 29, HIP-4 opened market deployment to all users. Deployers must stake 500,000 HYPE. If builders create unreasonable markets or fail to complete settlement properly, validators can slash their staked assets.
Outcome, Skew, and trade.xyz were the first deployers.
As of early October, according to different data platforms, HIP-4's cumulative trading volume was approximately $317 million to $395 million.
In the 30 days through October 5, its trading volume was approximately $45 million. By comparison, Kalshi alone recorded about $53 billion in trading volume in the period through September 29 this year.
HIP-4 currently remains merely a foundational financial primitive. Directly analogizing its current trading scale to a second Polymarket is equivalent to describing a foundational financial instrument as an already mature commercial business.
The real innovation HIP-4 brings is the unification of the account system.
At 3 a.m., a trader can, within the same order book and under the same margin balance, simultaneously hold a long position in a Bitcoin perpetual contract and a long position in a binary contract that pays out when the same mark price falls below a specific strike price.
Other platforms are also moving in a similar direction. Polymarket added perpetual contracts outside the U.S. in September, while Kalshi has offered such products since June.
As prediction markets and perpetual contract trading platforms gradually converge, HIP-4's most likely long-term advantage is permissionless listing of new markets.
However, fees need to be shared with deployers. Therefore, if a single builder dominates the main contract templates, the Hyperliquid protocol may retain the brand but be forced to give up most of the fee revenue.
This is the same risk HIP-3 faces, only occurring in a different category of contract products.
Listed Options: A Volatility Market Not Yet Mature
Options are a financial product harder to build than event contracts.
An option has a strike price, an expiration date, Greek risk metrics, and a complete volatility surface. Someone must quote these contracts and be willing to stand on the other side of the trade as counterparty. This creates a liquidity challenge different from that of event contracts.
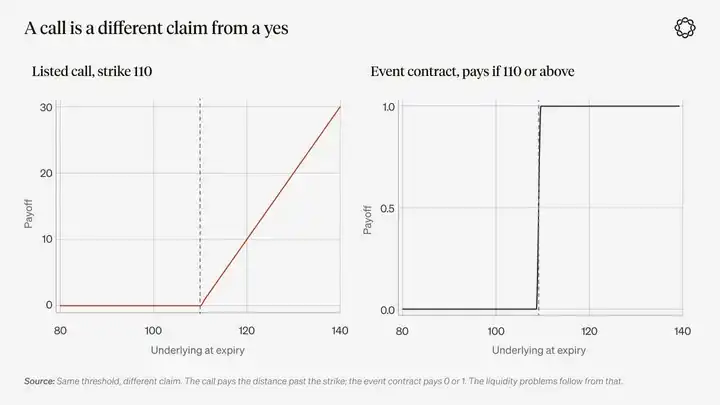
Chart description: The same price threshold corresponds to different payoff claims. The payoff of a call option depends on how far the underlying price exceeds the strike price, while the payoff of an event contract typically has only two outcomes: 0 or 1. The resulting liquidity problems also differ.
Retail investors have thoroughly demonstrated strong demand for financial products with limited downside but convex potential payoffs.
Whether it is same-day expiration options on the S&P 500 index or Robinhood's $342 million in quarterly options trading revenue, both illustrate this point.
Lottery-style speculative demand is willing to pay for convex payoff structures, especially when modern trading platforms have made such products highly accessible. But on-chain, option order books with real scale remain small.
Derive has become the leading platform for on-chain options trading. As of mid-September this year, Derive accounted for approximately 87% of total on-chain options premium trading volume in 2026. According to data from a disclosed trading day in September, Derive's options trading volume was $163 million. By comparison, Deribit's trading volume on the same day was $3.56 billion. Deribit is now owned by Coinbase and holds nearly 80% of global cryptocurrency options open interest.
Another platform, Paradex, was incubated by Paradigm's institutional trading network. In mid-September, Paradex integrated Paradigm's request-for-quote (RFQ) engine. Over the following four days, its options open interest grew 2.6x to $202 million.
Even when all on-chain options trading platforms are combined, their scale compared to Deribit remains so small as to be nearly negligible.
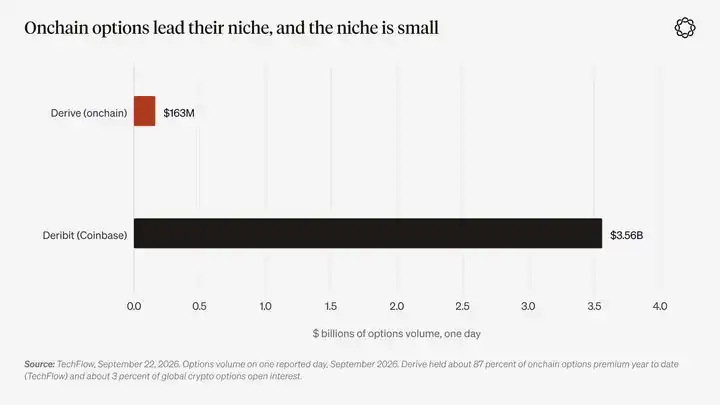
Chart caption: Options trading volume on a disclosed trading day in September 2026. Source: TechFlow, September 22, 2026. Derive accounts for approximately 87% of year-to-date on-chain options premium trading volume (Alea Research) and approximately 3% of global cryptocurrency options open interest.
The lack of liquidity in the volatility surface for on-chain options stems primarily from market structure itself.
For perpetual contracts, only one order book is needed per underlying asset. But for options, each underlying asset, each strike price, each expiration date, and each option type may require a separate order book. As a result, liquidity is fragmented across a large number of distinct contracts.
Until crypto trading platforms can make options trading as simple as same-day expiry options on the S&P 500 and build a volatility surface where people are genuinely willing to hedge risk, listed options will remain a niche market with real demand but thin order book liquidity.
A more reasonable way to understand Derive and Paradex is to view them as a low-cost call option on the future development of the options volatility surface.
Meanwhile, trading platforms have already been able to generate revenue through other means from the more easily achievable demand for convexity payoffs: regulated markets offer same-day expiry options, while other venues offer event contracts.
Hyperliquid may become one of the first platforms to attempt to solve this problem.
In early October of this year, Hyperliquid founder Jeff Yan said in an interview on Blockworks' Empire podcast that options are likely to be the platform's next direction of development.
He pointed out that HIP-4 has already provided ecosystem builders with a clear path to develop options protocols and inherit Hyperliquid's existing spot order book, portfolio margin mechanism, and the ability to Delta hedge through perpetual contract markets.
However, he did not provide a specific timeline.
If someone ultimately succeeds in developing this type of product, then the trading platform with the deepest on-chain perpetual contract liquidity is likely also the most suitable place to gradually build a complete options volatility surface.
How to build a portfolio?
A portfolio built around this theme can be divided into four parts.
Core holdings should be trading platforms that have real profits or fee income and control distribution channels that are difficult for competitors to seize.
Satellite holdings can be allocated to newer trading platforms whose business models and economics still need to be validated.
Early investment opportunities come from foundational financial primitives, such as on-chain options trading platforms. These products may play an extremely important role in the future, or they may ultimately be worthless.
As for private trading platforms that are not yet listed and cannot be invested in for now, they can first be placed on a watchlist.
Assets directly held by the speculative crowd, that is, AI labs, memes, cryptocurrencies, and sports teams listed on trading platforms, should be excluded from this portfolio.
Specific investment weights and conviction levels will be further discussed in our annual outlook report.
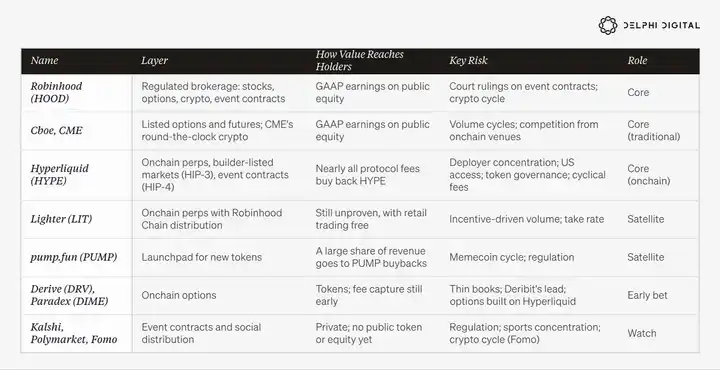
Managing this portfolio requires following five principles.
1. Manage the assets held by the house and the speculative crowd separately.
If a business earns revenue from fees charged on other people's speculative trading, then it is the house. If an asset itself is the object of speculation, then it is an asset held by the speculative crowd.
Certain assets, such as HYPE, may possess both attributes simultaneously. Therefore, when determining position sizing, this dual nature must be fully recognized.
2. Focus on fee take rates and revenue structure, not just trading volume.
What Bagehot called "foolish money" may inflate trading volume on a trading platform that offers products for free.
Hyperliquid's growth model, Lighter's mechanism of waiving fees for retail trading, and Robinhood's payment for order flow (PFOF) model are all different solutions to the same business problem. But each model has its own ways it could fail.
If massive trading volume ultimately cannot be converted into revenue that the platform can actually capture, then it is merely trading activity, not economic value that investors can capture.
3. Treat regulation as part of the business model.
A licensed trading platform, even with limited business scale, can still be a quality business—just like state lottery operations in the United States.
An unlicensed trading platform may be forced to relocate to offshore markets, yet can still continue operating while U.S. markets are closed.
If investors bet on only one of these models, they are effectively also betting on how the courts will rule.
4. Prioritize investment vehicles that are closest to equity in trading infrastructure.
Robinhood discloses earnings data that complies with U.S. GAAP. Hyperliquid discloses fee revenue and token buybacks.
The two are different types of investment vehicles, with different governance structures and tail risks. But they are still more similar in economic attributes to each other than either is to the speculative assets listed and traded on their platforms.
5. Size positions based on long-term cultural trends, not single-quarter performance.
As the gap between reality and the future gradually narrows, speculative culture will fade accordingly. For example, when wage income is once again sufficient to support home purchases, when entry-level jobs reappear, or when a new technology eventually becomes as ordinary and mundane as electricity, the forces driving speculation will weaken.
But until then, the wheel will keep spinning—only the speculative targets on the wheel will keep changing.
Where will this trend ultimately lead?
There are two main possible outcomes for this trend.
The first is that more and more things in life will become tradable objects: elections, interest rate decisions, weather, a company's next product launch, or an athlete's next game.
Each bet may become smaller in size, faster to execute, and more frequent, and an increasing number of trades will be completed automatically by software.
An AI agent executing tasks on behalf of a user could express the same market judgment through dozens of contracts across multiple trading platforms without the user ever needing to open a trading app.
This will further drive economic value toward the operators of trade-matching engines and settlement layers.
Following this path, the intensity of speculative activity will still rise and fall with market cycles, but the underlying infrastructure will continue to expand. Ultimately, the house will increasingly resemble a utility company providing basic public services.
The second outcome is what every historical wave of speculative mania discussed in this article has ultimately experienced.
Speculative activity on such a massive scale has, without exception in history, ended in a crash. There is no sufficient reason to believe this time will be different. What truly matters is what survives after the bubble bursts.
Railways are the most typical historical template: shareholders suffered severe losses, but the railway network survived.
Of course, the house is not entirely immune to shocks either. FTX ultimately went to zero, and when the speculative crowd exits the market, trading platform revenues will also drop sharply.
The market crash on October 10, 2025, was a smaller-scale stress test.
In the largest single-day liquidation event on record, the founder of Hyperliquid said the platform achieved 100% uptime and incurred no bad debt.
However, the exchange also had to activate its cross-margin auto-deleveraging mechanism for the first time in more than two years.
During a market crash, a well-operated trading platform may lose revenue, while the assets held by the speculative crowd may go directly to zero.
These two development paths are not mutually exclusive. In fact, the most likely outcome is that both will occur simultaneously: the speculative bubble will eventually burst at some point, but the related infrastructure will still survive after the crash and be held by certain companies.
Next, we will use the following indicators to determine which path the market is actually taking.
What indicators are we watching?
Over the next year, we will continue to track the following signals and gradually quantify them.
1. Market share.
Can on-chain trading platforms continue to capture perpetual contract trading volume from large centralized exchanges, or are they merely benefiting from the growth of the entire perpetual contract market?
2. The event contract market after the World Cup.
When the sports calendar is no longer dense, can event contracts continue to be a lasting source of revenue for brokerages? Can the business scope of prediction markets expand from sports events to more areas?
3. Trading traditional assets through crypto infrastructure.
Will stocks, commodities, and foreign exchange continue to migrate on-chain? At the same time, how quickly will traditional exchanges narrow the gap with crypto trading platforms through 24/7 trading and tokenized stocks?
4. Court rulings.
Will event contracts ultimately be classified as futures or as gambling? And will this legal characterization lead trading platforms in the United States and offshore trading platforms down different development paths?
5. The impact of AI on electricity bills and elections.
Will the cost of AI infrastructure construction continue to show up in household electricity bills and political elections? Can the entry-level job market recover?
What would prove our judgment wrong?
If real interest rates remain high for a long time while the housing market becomes more accessible again, the lottery-style speculation engine could weaken. The Federal Reserve's recent rate hikes and a U.S. 10-year Treasury yield above 5% are putting this judgment to the test.
If the AI construction wave ultimately leads the market to form a broad consensus rather than continuously generating new disagreements, or if AI capital expenditure itself begins to slow, the construction-style speculation engine will also weaken.
If trading platforms' fee take rates are driven down to zero amid competition, or if trading volume is sustained only by incentive programs, then even if there is still a lot of trading activity in the market, little truly worthwhile economic value will remain.
If the government decides politically to treat the entire industry as a vice that should be restricted and actually implements relevant regulatory measures, the market may ultimately be left with only a smaller number of licensed trading platforms. The U.S. Supreme Court may soon have an opportunity to push the market in this direction through relevant rulings.
Moreover, the analytical framework of the "two engines of speculation" itself has a problem. If every historical speculative event can be explained after the fact as either construction-type speculation or lottery-type speculation, then this framework appears too broad and lacks sufficient explanatory constraint.
Therefore, the real test should be more specific: speculators' traded assets constantly rotate, but can the platforms responsible for matching and clearing these trades consistently generate revenue?
The most likely mistake is holding assets that the speculative crowd is betting on while mistakenly believing you are investing in the house.
VI. Our Answer
Is speculation a societal reaction to technological change, or a reaction to the decline of political and monetary order? Our answer is: speculation is a reaction to a certain gap, and both of the above forces can create this gap.
Technological change opens this gap from above, offering the crowd a story about future construction and growth. A political and monetary order under pressure opens this gap from below, handing the crowd a lottery ticket.
Historically, these two forces have mostly operated separately. Moreover, when the policy engine starts, it is usually the state selling some speculative opportunity to the public from the top down.
But today, both engines are running simultaneously.
Lottery-type speculation is driven not only by government policy but equally by ordinary households from the bottom up. And the same technology is powering both types of speculative activity at once.
The market environment itself has also changed. In the past, participating in construction-type speculation required a securities broker, while participating in lottery-type speculation required a bookmaker. Today, both activities can be done through the same phone. They also share an unresolved legal status, with related disputes still ongoing in the courts.
Meanwhile, policy practices over the past fifteen years or so have gradually fostered a perception: accumulating wealth through traditional paths no longer compounds fast enough.
The objects people bet on will keep changing, and the names of hot assets will keep rotating. But the speculative crowd always needs a place to place bets.
And that is the part truly worth investing in.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia






