Can Bassant Save US Debt with a 'Soros-Style' Play?
Original Title: "Rescuing the U.S. Bond Market Soros-Style! From Exchange Rates to Interest Rates, Can Bessent Win the Market?"
Original Author: Long Yue, Wall Street News
Someone who once helped Soros break the Bank of England is now trying to defend the U.S. Treasury market using the same strategy?
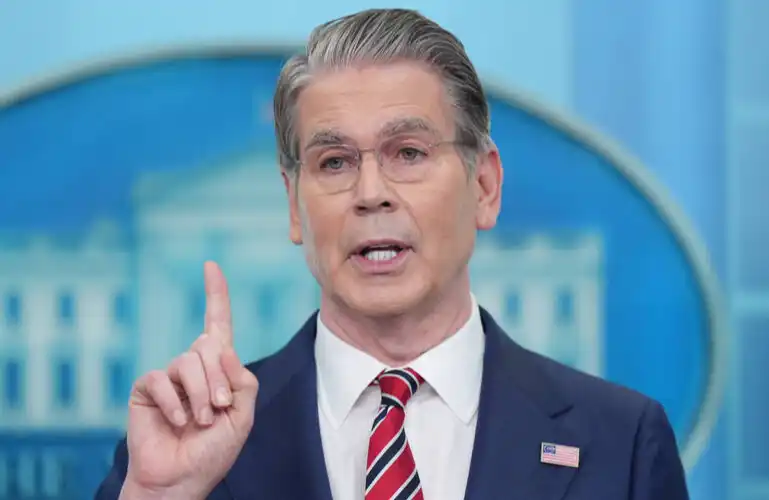
Since the beginning of this year, U.S. Treasury Secretary Scott Bessent has taken a series of unexpected market actions to bet his reputation on suppressing U.S. borrowing costs. According to Bloomberg, he has become the "most active Treasury Secretary in intervening in financial markets in decades".
Following the U.S.-Japan intervention to weaken the yen, Bessent's latest move is to expand U.S. bond buybacks. The Treasury Department announced that it will "at least double" the size of buybacks of 10 to 30-year Treasury bonds—this buyback plan was only announced just two weeks ago. On the day the news was released, the yield on the 10-year Treasury bond fell by approximately 6 basis points, the 30-year yield fell by nearly 9 basis points, and the U.S. dollar index also fell to a three-month low.
The market's reaction confirmed Bessent's judgment: he himself has publicly stated, "My job is to be the nation's top bond salesman, and the Treasury yield is the barometer of success."
From Pound Sterling Short to Bond Market Guardian
To understand Bessent's strategy, we need to go back to 1992.
That year, a young Bessent in his twenties was working at the Soros Fund, where he helped build a short position on the pound sterling. On "Black Wednesday," the pound was forced to exit the European Exchange Rate Mechanism, and Soros made a net profit of over $1 billion. According to media reports, a former advisor described Bessent at the time as someone who "could see market weaknesses that others couldn't."
Afterward, he returned to Soros as Chief Investment Officer, led a $1 billion yen short in 2013, and once again reaped substantial rewards. In 2015, he founded Key Square Capital Management with $4.5 billion and successfully bet on both Brexit and Trump's election.
This "find the crack, then push along the trend" hunter logic has run through his entire hedge fund career.
And now, he is using the same intuition to do the exact opposite—defend a market under pressure.
This Year's Intervention Blueprint: From Yen to U.S. Bonds
Bessent's moves this year have already formed a clear logical chain.
Step One, Yen Intervention. On July 31, the U.S. Treasury, in conjunction with Japanese authorities, intervened in the market to buy yen, marking the first direct intervention in the yen's exchange rate by the United States in nearly thirty years. According to data from the Peterson Institute for International Economics (PIIE), Japan used approximately $87 billion of its foreign exchange reserves to purchase yen in the last two days of July, with the U.S. Treasury "joining in the final stage, providing funds on a relatively limited scale but sending an important political signal of support." It is worth noting that the Treasury sold euros instead of dollars and did not inform Eurozone authorities in advance.
Behind this move lies an implicit thread: Japan holds around $1.1 trillion in U.S. Treasuries, making it the largest foreign holder. If Japan had financed the intervention alone, it might have been forced to sell U.S. Treasuries, further raising long-term yields. Washington's involvement allowed Japan to sell fewer U.S. Treasuries, indirectly preserving the yield curve that is of utmost concern to Bernette.
Step Two, Bond Supply Contraction Signal. Earlier this month, the Treasury hinted at a potential reduction in the issuance size of long-term bonds, signaling an expected tightening of supply to the market.
Step Three, Enhanced Repurchase. It was announced this week that the Treasury would at least double the size of its long-bond repurchases, providing direct support to prices from the demand side.
Bloomberg quoted Brad Golding, portfolio manager at Christofferson Robb & Co., as saying that this move is like a "classic 'screen clear' maneuver"—a hedge fund technique where orders are placed with multiple major dealers simultaneously, triggering significant market volatility.
Mark Sobel, a former U.S. Treasury official now working at the OMFIF think tank, told Bloomberg, "He is certainly a radical; this harks back to his hedge fund background." "He and this administration are clearly concerned about the rise in long-term yields."
Breaking the "Rules and Predictability"
Bernette's actions directly contradict the Treasury's traditional principles.
The U.S. Treasury has long adhered to a principle of "rule-based, predictable" debt management, avoiding surprises in the market. Bernette himself publicly endorsed this principle at a Treasury market event last November.
However, his recent actions have deviated from this commitment.
Gregory Faranello, head of U.S. Rates Trading and Strategy at AmeriVet Securities, told Bloomberg, "This goes against the 'rule-based, predictable' principle—but this is the world we live in." "The message is clear: prevent the rise in yields."
Ironically, Berniette's predecessor Yellen adjusted the debt issuance structure in 2023 to suppress yields. At that time, Berniette was one of the critics, accusing the move of being politically motivated. Former Trump Chief Economist Stephen Miran also co-signed a paper in 2024 criticizing the "Aggressive Treasury Issuance" (ATI).
According to Bloomberg, Miran and Nouriel Roubini wrote in the paper: "Once a party starts using ATI to stimulate the economy during an election season, all future administrations may follow suit."
Question: Can Intervention Solve Structural Issues?
The market had a short-term reaction to Berniette's operation, but economists' questions are more fundamental.
As of the first ten months of the 2026 fiscal year, federal net interest payments have reached $963.0 billion, approximately $3.18 billion per day, a 14% year-on-year increase. The 10-year Treasury yield is at 4.72%, and the 30-year yield is at 5.31%—a large amount of previously issued debt below 2% is now rolling over at higher rates. The deficit for the 2026 fiscal year-to-date is $1.8 trillion, up 5% from the previous year, with Social Security, Medicare, defense, and interest payments on the rise, while the Republican Party is still discussing further tax cuts.
Brookings Institution Senior Fellow Robin Brooks told Bloomberg: "This is not addressing the fundamental issues—reducing debt, shrinking the fiscal deficit, but attempting to manipulate the yield curve."
BNY Macro Strategist John Velis also stated: "Given the current spending policies and the war, alleviating pressure at the long end will be very difficult."
The effectiveness of yen intervention is also in doubt. After the USD/JPY hit a high of 163.98 on July 23, it fell back to 159.43 by August 17, but according to CNBC, the intervention did not stop the continued weakening of the yen. PIIE's Maurice Obstfeld directly stated that the intervention had minimal impact, saying, "Forex intervention is not a free lunch, it's not even a free piece of cake."
Zurich Insurance's Chief Strategy Officer Guy Miller told Bloomberg: "This approach can only work for a certain period. When the Treasury Department clearly states it will continue to intervene, it can indeed have a strong effect. But ultimately, this is unsustainable without addressing reckless fiscal policy."
Onepoint Bfg Chief Investment Officer Peter Boockvar was more direct: “He is simultaneously fighting a two-front war in the giant markets of bonds and forex, a very difficult battle.”
The Stakes of Reputation
Bridgewater's logic, as expressed in his own words, is quite clear. Referring to the Trump administration's holdings in tech and resource companies last month, he said: “What we are trying to do is create a market signal.” He told Fox Business: “Essentially what you’re doing is you’re saying to investors, okay, the puck is going there, skate there quickly.”
The challenge is that in 1992, shorting the pound found a systemic weakness to exploit. But now, he faces structural pressures driven by fiscal deficits, inflation expectations, and Fed policy—pressures that cannot be easily altered through repo operations or currency interventions.
According to Bloomberg, Mark Sobel, who served in the Treasury for nearly 40 years, believes Bridgewater is the most radical Treasury Secretary since the early 2000s. However, he also characterizes the yen intervention as unwise, arguing it sidestepped the fiscal consolidation that the U.S. truly needs.
Original Article Link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles