Hardcore Research Report: After a Stunning Start, Frame-by-Frame Breakdown of Robinhood Chain's Revenue Potential
Original Article Title: Robinhood Chain: Can It Move Robinhood's Bottom Line?
Original Article Author: ACJ, Blockworks
Original Article Translator: Azuma, Odaily Planet Daily
Key Takeaways
· Despite Robinhood's overall business reaching record highs, its crypto business is on the decline. In the second quarter of 2026, Robinhood's crypto business revenue declined by 38% year-over-year to $100 million, accounting for only 8% of the company's total revenue; retail crypto trading volume fell by 36% year-over-year, and the share of crypto assets in customer assets under custody (AUC) hit a historical low of 7%.
· Robinhood Chain is one of the recent strongest-performing Layer 2 (L2) network launch cases. The chain created $3.6 million in real economic value (REV) in July, accounting for 38% of all L2 network revenue tracked by growthepie, surpassing mature networks including Polygon and Base.
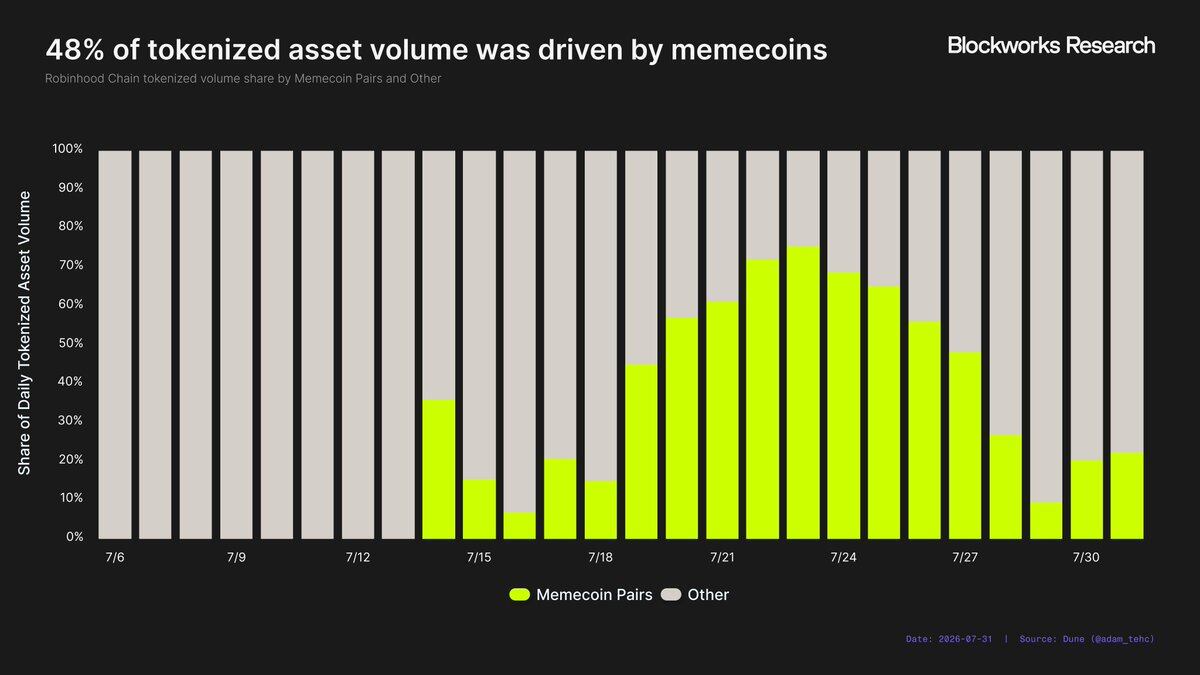
· What is driving early activity on Robinhood Chain is not Real World Assets (RWA) but rather Meme coins. In July, Meme coins accounted for 51% of the spot trading volume on Robinhood Chain, while RWAs only represented 5%. Additionally, 48% of the RWA trading volume came from a liquidity pool composed of RWAs and Meme coins.
· Robinhood's most tangible monetization opportunity is not at the infrastructure layer but at the application layer. Currently, the USDG stablecoin has been able to generate approximately $10.5 million in annualized interest income; Morpho's case also demonstrates the value of Robinhood's main application distribution capabilities. In comparison, Lighter only accounts for 0.2% of its perpetual contract total trading volume through integration with the Robinhood Wallet.
· Currently, Robinhood Chain has yet to significantly impact Robinhood's profits. The aggregate annualized scale of known Robinhood Chain revenue sources is only about $54.8 million, equivalent to 14% of Robinhood's crypto business's annualized revenue. For Robinhood Chain to become a significant business line, the company needs to scale USDG, commercialize main app traffic, or leverage the chain as an entry point for users into higher-value products.
Quote: Robinhood Crypto Business at a Crossroads
Perhaps no company represents the rise of retail investors more than Robinhood, which has become synonymous with retail investment and has seen rapid growth in its underlying business as a result.
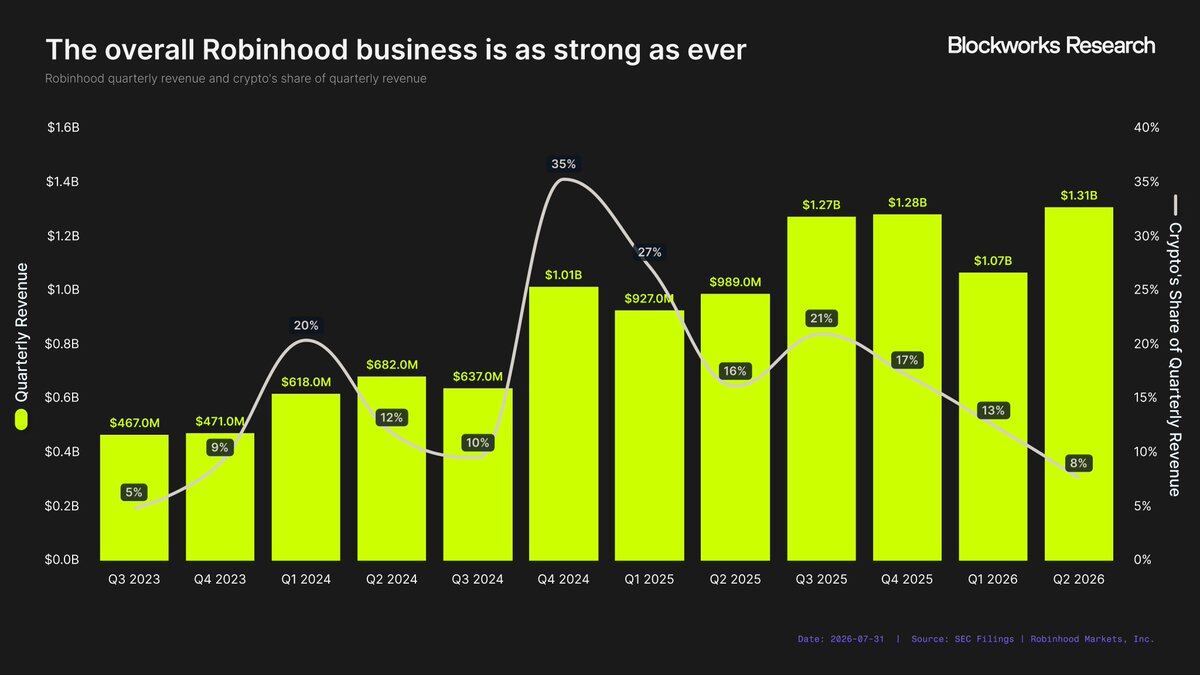
In the second quarter of 2026, Robinhood's quarterly revenue reached $13.1 billion, hitting a record high and growing 32% year-over-year, compared to a 92% increase from the second quarter of 2024. This growth has come not only from its core stock and options trading business but also from its expanding product ecosystem. Today, Robinhood has 13 business lines with annualized revenue exceeding $1 billion. In fact, in the second quarter of 2026, all of Robinhood's trading-based revenue business lines saw double-digit year-over-year growth...
Except for one—the crypto business.
Once responsible for over a third of Robinhood's revenue, the crypto business has now shrunk to a nearly negligible portion. In the second quarter of 2026, only 8% of Robinhood's total revenue came from the crypto business, the lowest level since the third quarter of 2023.
The importance of the crypto business in Robinhood's revenue mix has significantly declined—even the event contracts introduced just last year generated more revenue in the second quarter than the crypto business:
· Event Contracts Revenue: $1.56 billion;
· Crypto Business Revenue: $1 billion;
This weakness is not only reflected in the declining revenue contribution but also in the waning interest of Robinhood's core users in crypto assets. While this trend is not unique to Robinhood, the magnitude of its decline is still astonishing.
The most notable manifestation comes from trading activity. In the second quarter of 2026, retail cryptocurrency trading volume on the Robinhood App was only $18.2 billion, a 36% year-over-year decline and the lowest quarterly level since the third quarter of 2024.
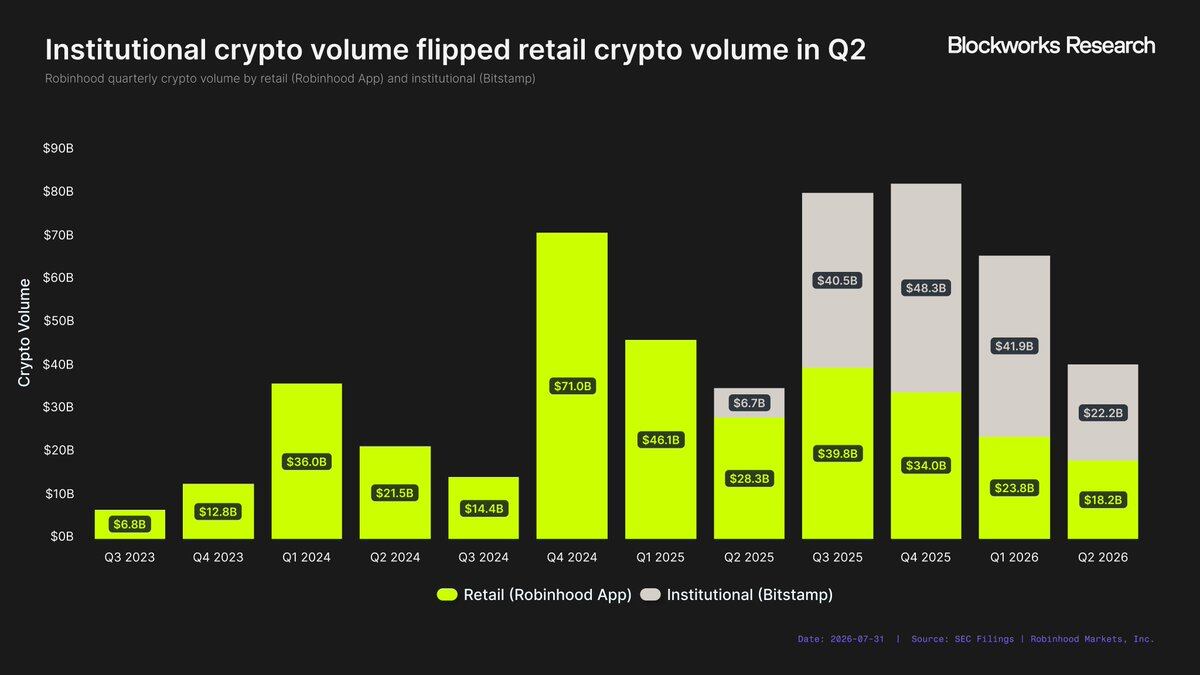
The decline is so significant that institutional trading volume on Bitstamp has surpassed retail trading volume on Robinhood for the first time, and even the institutional activity during this period was not particularly strong—Bitstamp's second-quarter volume was $22.2 billion, marking its second-lowest quarterly performance in history.
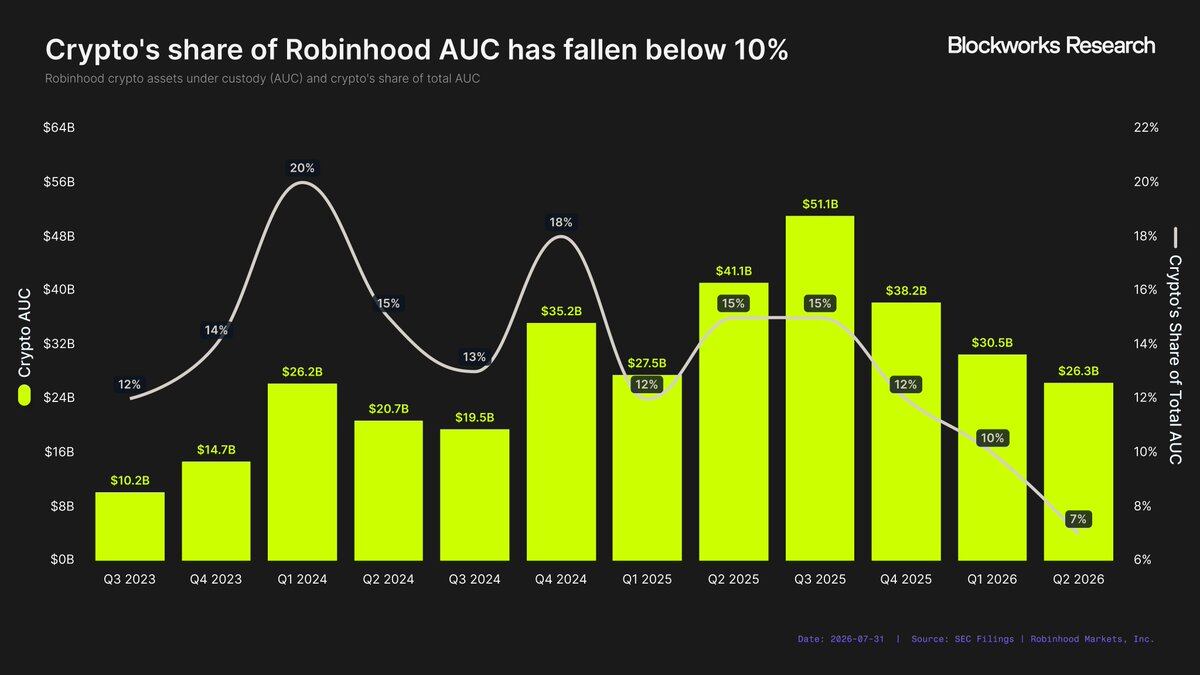
Transaction volume is not the only indicator that can demonstrate the contraction of the cryptocurrency business. In the first quarter of 2024, cryptocurrency assets under custody (AUC) stood at $26.2 billion, representing 20% of Robinhood's total AUC. Over two years later, cryptocurrency AUC remained almost the same at $26.3 billion, but its share of the total AUC was only 7%, marking the lowest quarterly percentage in history.
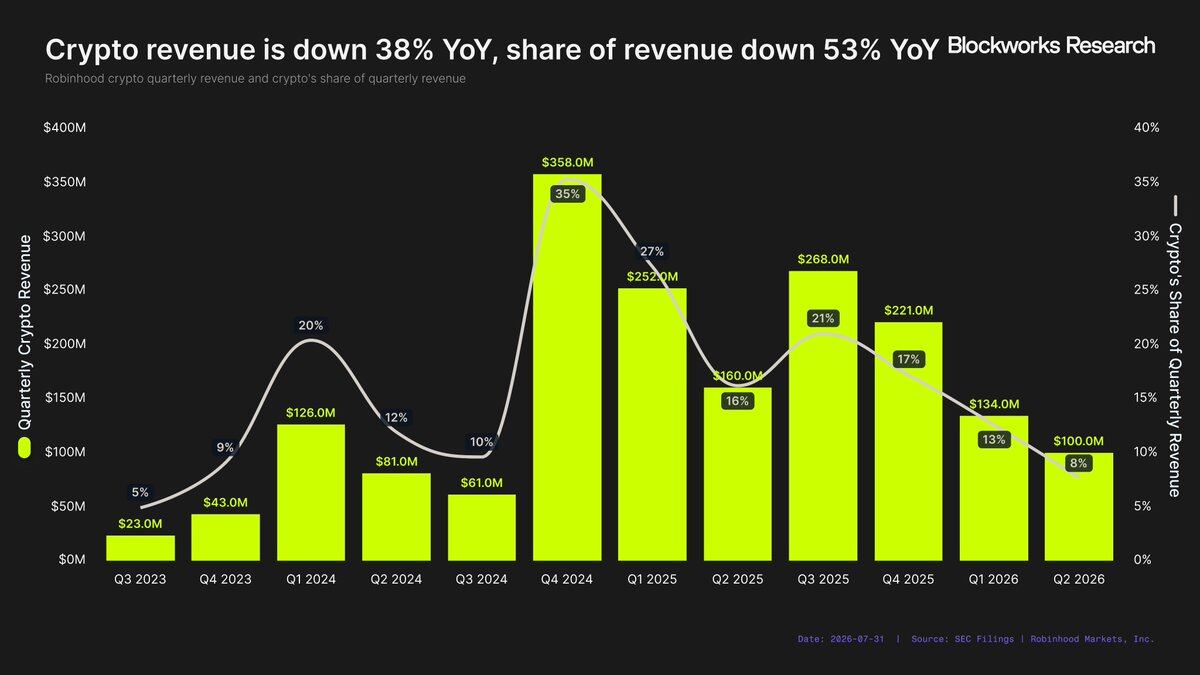
Against this backdrop, Robinhood's cryptocurrency revenue has taken a severe hit. Cryptocurrency revenue in the second quarter decreased by 38% year-on-year, with its proportion of total revenue dropping by 53%. In short, Robinhood is growing overall, but not its cryptocurrency business.
However, Robinhood has not retreated from the cryptocurrency field. On the contrary, it has launched Robinhood Chain, its largest cryptocurrency bet to date. Robinhood is no longer relying almost entirely on trading revenue but is attempting to build a broader, more enduring cryptocurrency business. The key question is, can Robinhood Chain make cryptocurrency a meaningful growth driver for Robinhood again?
What is the monetization potential of Robinhood Chain?
On July 1, 2026, Robinhood officially announced the launch of the Robinhood Chain mainnet at The World Is Flat event. This is a Layer-2 (L2) blockchain developed in-house by Robinhood, aimed at powering the company's growing on-chain ecosystem. Since its launch, Robinhood Chain has become one of the fastest blockchain launches in recent history.
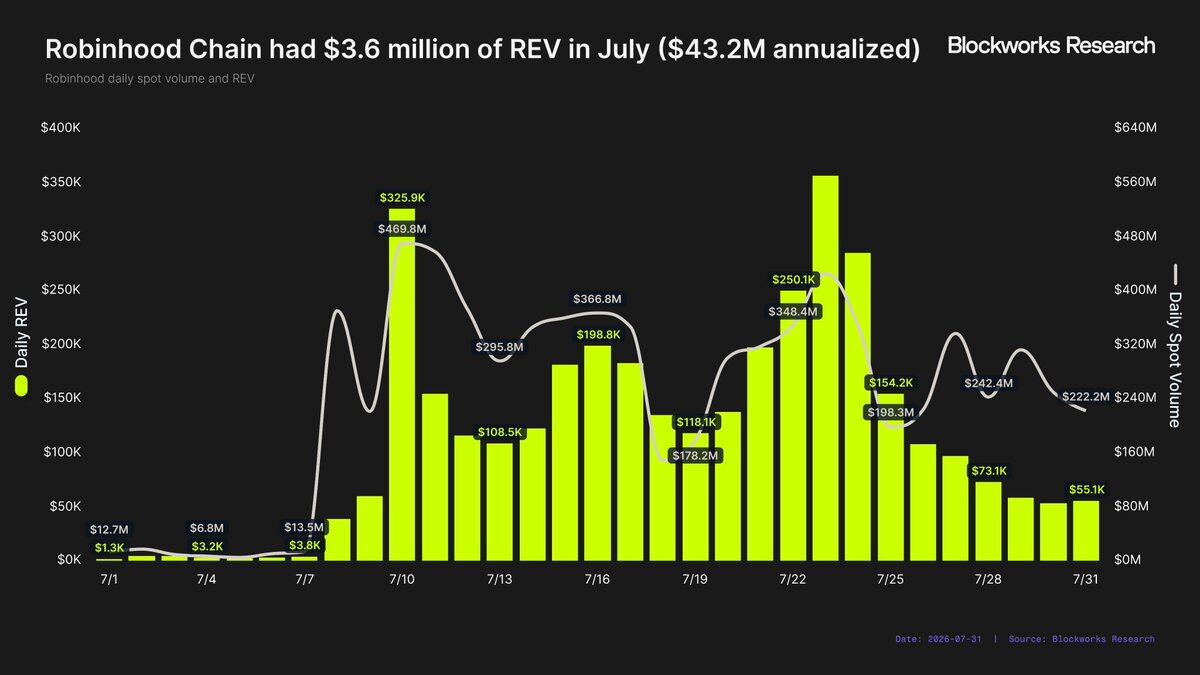
In the first month after the launch, Robinhood Chain created $3.6 million in Real Economic Value (REV). While it is still early to determine if this level of activity is sustainable, if we simply annualize based on the first month's data, Robinhood Chain's annualized REV is approximately $43.2 million.
This is a good starting point, but at this scale alone, it is still far from enough to reverse the downward trend in Robinhood's cryptocurrency business revenue.
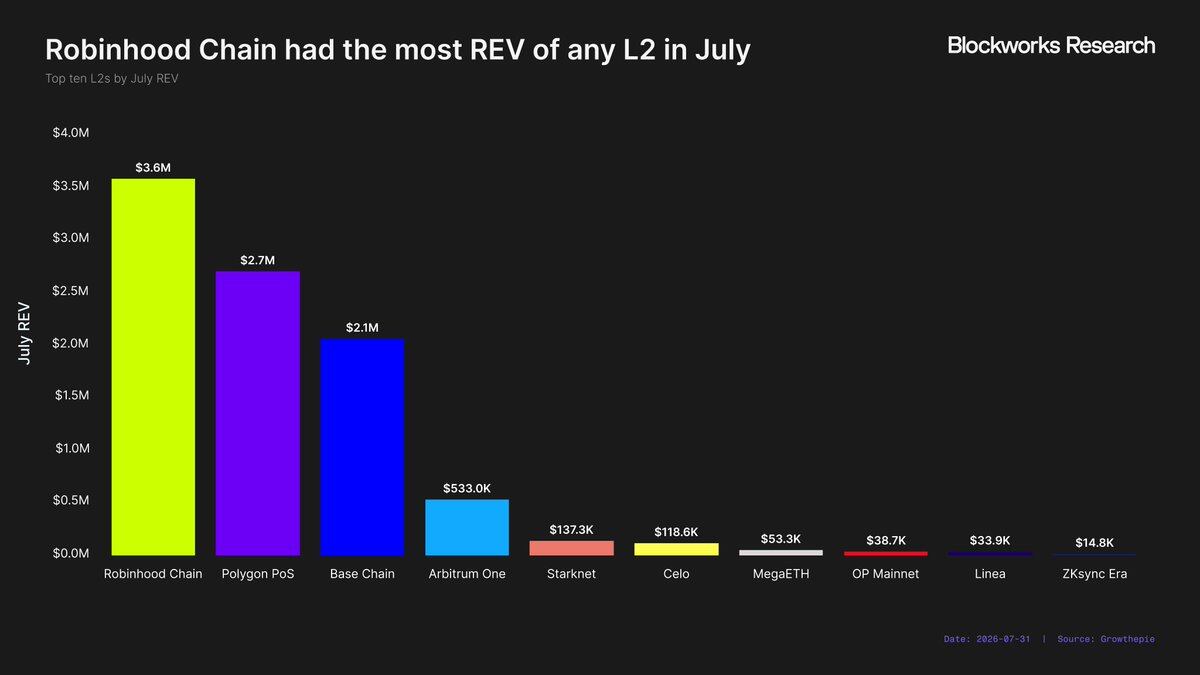
Nevertheless, Robinhood Chain's launch performance remains impressive. In July, Robinhood Chain ranked first in revenue among all L2 networks, surpassing many well-established networks that have been running for years, such as Polygon ($2.7 million) and Base ($2.1 million).
According to data tracked by growthepie, Robinhood Chain currently holds 38% of all L2 network chain revenue. In other words, Robinhood Chain is already the largest L2 in chain revenue, but 62% of the market share still belongs to other networks. Even if the total L2 chain revenue remains stagnant, Robinhood Chain can still achieve significant growth by capturing a larger market share.
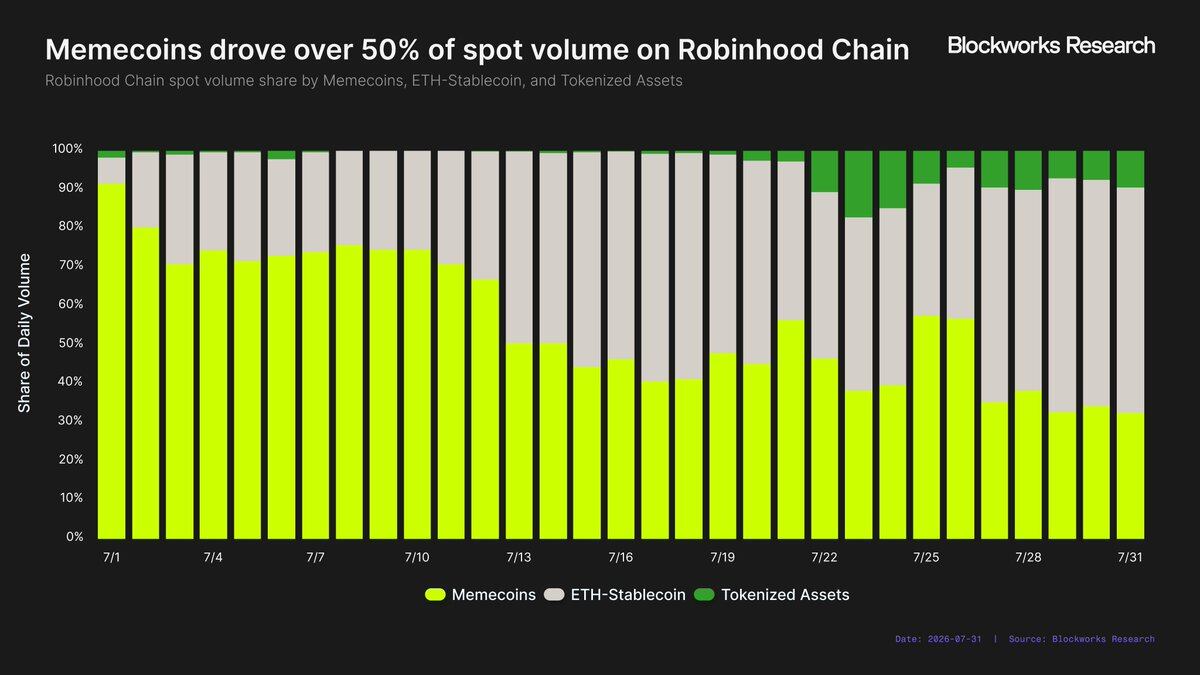
However, an important factor for the early success of Robinhood Chain is that most of the current activity is attributed to Meme coins, which have always been one of the main drivers of the REV blockchain. Robinhood seems to openly accept this, with founder Vlad Tenev expressing support for Meme coins on multiple occasions.
Nevertheless, the extent to which Meme coins are driving activity on Robinhood Chain is still quite remarkable. In July, the chain facilitated $69.3 billion in spot trading volume, with $35.5 billion (51%) coming from Meme coins. In contrast, RWAs — the core use case claimed by Robinhood Chain — accounted for only $313.2 million, or 5% of the total trading volume.
Furthermore, the direct proportion of Meme coins in Robinhood Chain's trading volume may still underestimate their true impact on network activity. For example, a strategy promoted by the Meme coin launch platform L()ng is to pair Meme coins with tokenized stocks or ETFs in a liquidity pool, linking the price movement of Meme coins to the underlying RWAs. If the underlying RWAs go up, let's say by 5%, the price of the Meme coin will also go up by 5% (assuming no trading activity). Therefore, a significant portion of the apparent RWA trading volume is actually being driven by Meme coins. From July 6th to July 31st, 48% of RWA trading volume occurred in liquidity pools paired with Meme coins.
While Meme coins have effectively driven on-chain revenue growth, historically they have rarely become a sustainable long-term revenue source. Meme coins are highly volatile, with Ethereum, Avalanche, TRON, and Base all experiencing their own speculative hype cycles, only to see funds and users move on to other networks eventually. Whether Robinhood Chain can retain this activity in the future remains uncertain. One month of data is not enough to prove that Meme coins will be a sustainable source of REV for Robinhood Chain, or if it is just another temporary stop in fund rotation that will ultimately return to Solana.
From a more macro perspective, relying solely on Robinhood Chain's REV is unlikely to rejuvenate Robinhood's crypto business. Across the industry, network revenue is currently experiencing a structural decline. The first-generation smart contract platforms once relied on block space scarcity to generate significant fee revenue, but as block space has become increasingly commoditized, new chains are finding it more challenging to generate substantial revenue solely through the infrastructure itself.
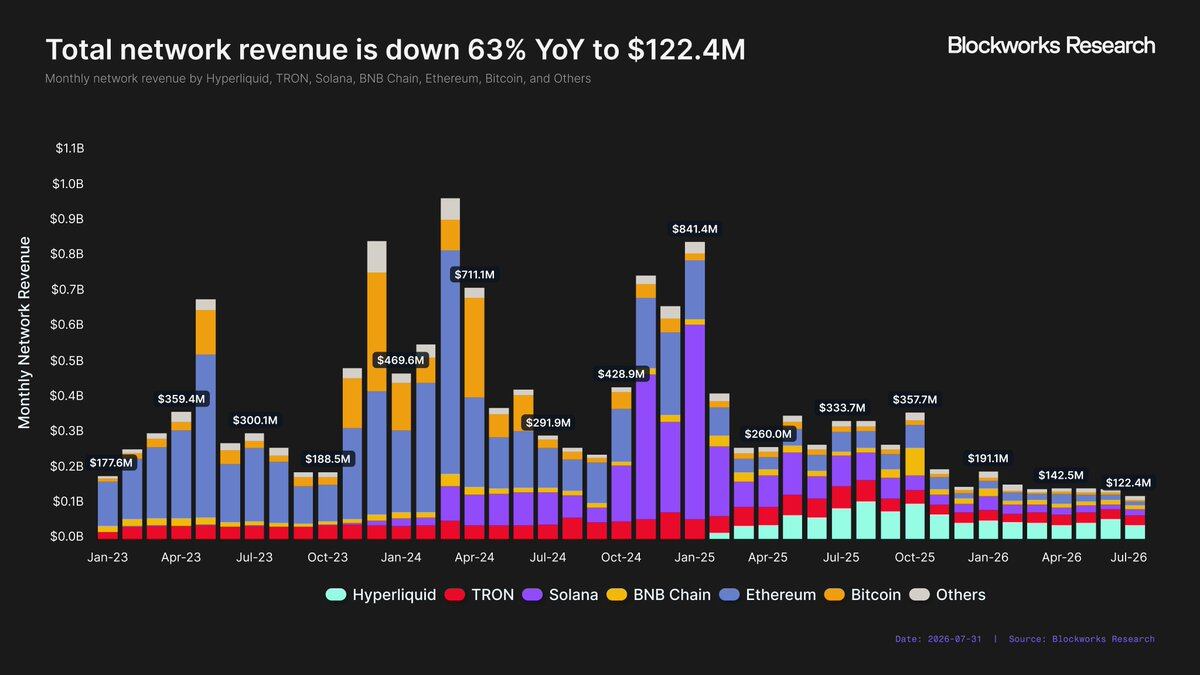
In July, the blockchains tracked by Blockworks collectively generated $122.4 million in network revenue, the lowest monthly total in three and a half years. In comparison, network revenue in July 2025 was $333.7 million, marking a 63% year-on-year decrease. This deterioration cannot be solely attributed to market cycles. In July 2023, during the previous bear market, chains still generated $300.1 million in network revenue.
As mentioned earlier, Robinhood already has 13 business lines that have achieved at least $1 billion in annualized revenue, and relying solely on network revenue, it is difficult to imagine Robinhood Chain joining these ranks. Even if Robinhood Chain continues to capture a larger share of the L2 activity, its chain revenue will ultimately hit a market ceiling of around $100 million in annualized revenue.
To break through this ceiling, Robinhood needs to onboard its existing user base onto the chain. However, as Robinhood's user base is predominantly in the U.S., in the current regulatory environment, most of them cannot access Robinhood Chain through the Robinhood app, which could take time.
If Robinhood wishes for Robinhood Chain to become the next billion-dollar business line in the near term, the company needs to move beyond a mere network revenue model.
Commercialization at the Application Layer
The value capture in the crypto industry is gradually shifting from the infrastructure layer to the application layer, with Solana being a prime example.
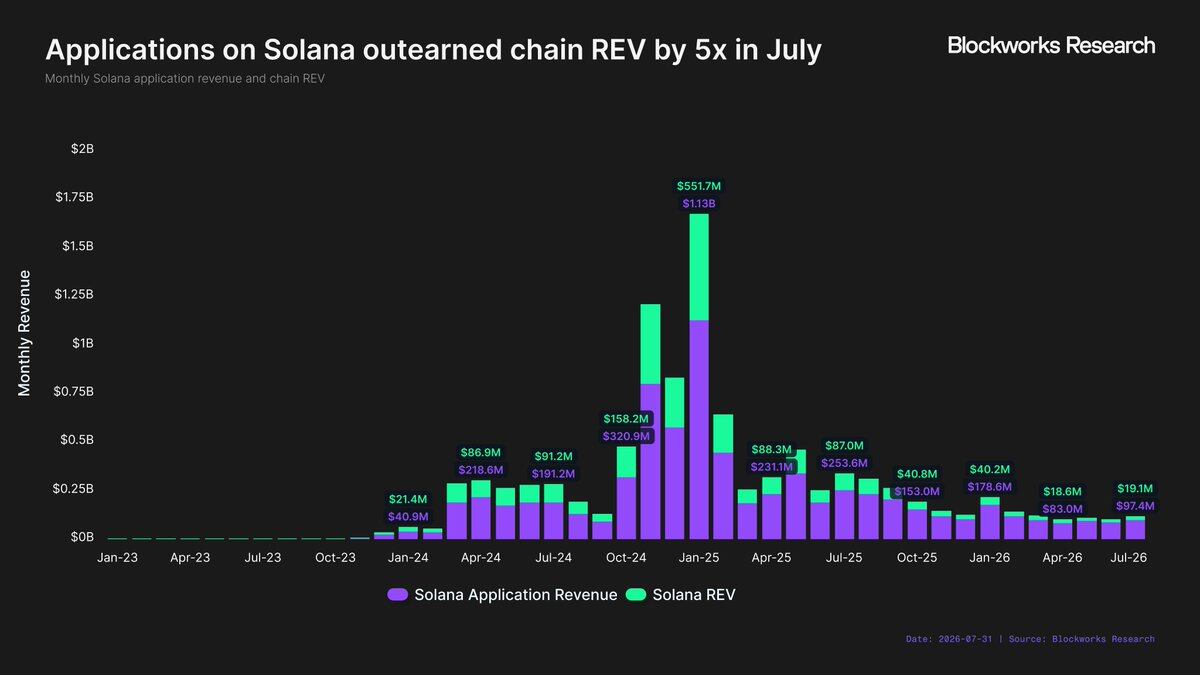
In January 2024, during Solana's early recovery, Solana applications collectively generated $40.9 million in revenue, while the Solana network was able to generate $21.4 million in REV. The application revenue was approximately 1.9 times the network revenue. By January 2025, at the peak of Solana's bull market, its application revenue reached $1.13 billion, with Solana REV at $551.7 million, maintaining a ratio of about 2. However, this gap has further widened since then. In July 2026, for every $1 of revenue generated by Solana's ecosystem applications, the network itself could only capture about $0.2.
In other words, the application layer is capturing an increasing amount of value, while the proportion of value obtained by the underlying blockchain is declining. If Robinhood aims for Robinhood Chain to become the next $1 billion business line, it must directly engage in the commercialization of on-chain applications. Although Robinhood has not officially announced this strategy, its early moves have already pointed in that direction.
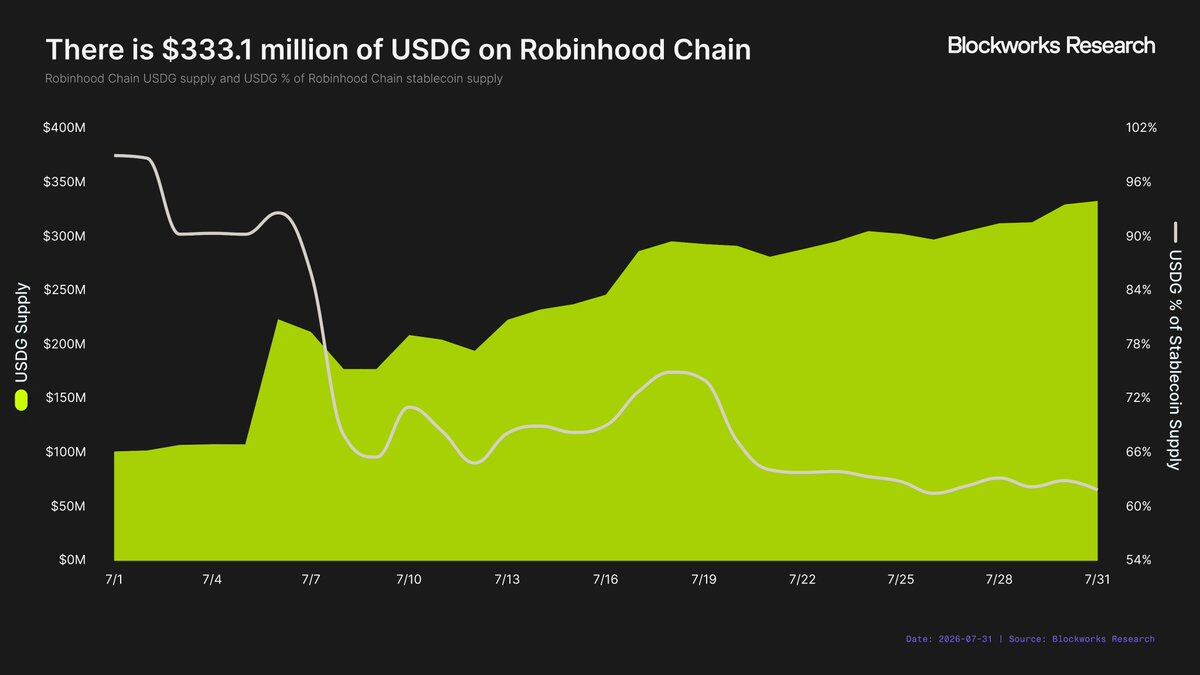
The most prominent example to date is Robinhood's stablecoin strategy. Unlike most blockchains that primarily rely on Circle's USDC or Tether's USDT, Robinhood has designated USDG as the native stablecoin of the Robinhood Chain. This has created an additional revenue stream for Robinhood—interest income generated from the underlying reserves of USDG. As of the end of July, the market value of USDG on the Robinhood Chain was $333.1 million. Assuming an underlying reserve yield of 3.5% and 90% of the related interest income going to Robinhood, USDG will generate approximately $10.5 million in additional annualized revenue.
It should not be challenging for Robinhood to further increase the supply of USDG, creating a sustained income stream. If the USDG supply reaches $1 billion (a reasonable target considering stablecoins on 11 existing blockchains have a supply of at least $1 billion), it would generate $31.5 million in annualized revenue, nearly on par with the current chain revenue of the Robinhood Chain.
Robinhood Chain seems to be expanding its application layer beyond stablecoins. Lighter has launched its Perp DEX with a customized deployment on the Robinhood Chain and will share a 50/50 split of trading fees with Robinhood. As part of the collaboration, the Robinhood Wallet—a self-custodial wallet separate from the main Robinhood app—will directly display Lighter perpetual contracts within the app.
Additionally, it is rumored that Morpho also paid a fee to Robinhood for integration into the Robinhood app. If true, this would represent a notably different business model from the traditional blockchain ecosystem. It has typically been the blockchain incentivizing app deployment to attract applications, but Robinhood is attempting the reverse, with apps paying fees to gain access to Robinhood's user distribution channel.
How Much is Robinhood's Distribution Worth?
The feasibility of the entire application layer strategy ultimately depends on the value of Robinhood's distribution channel. If protocols are willing to pay to access Robinhood users, then Robinhood can monetize this traffic asset.
From the current cases, protocols on the Robinhood Chain can mainly acquire users through two channels:
· The Robinhood main app, such as Morpho;
· Independent Robinhood Wallets, such as Lighter.
While the distribution capability of the Robinhood main app is well known in the market, the value of distribution through the Robinhood Wallet is far from clear.
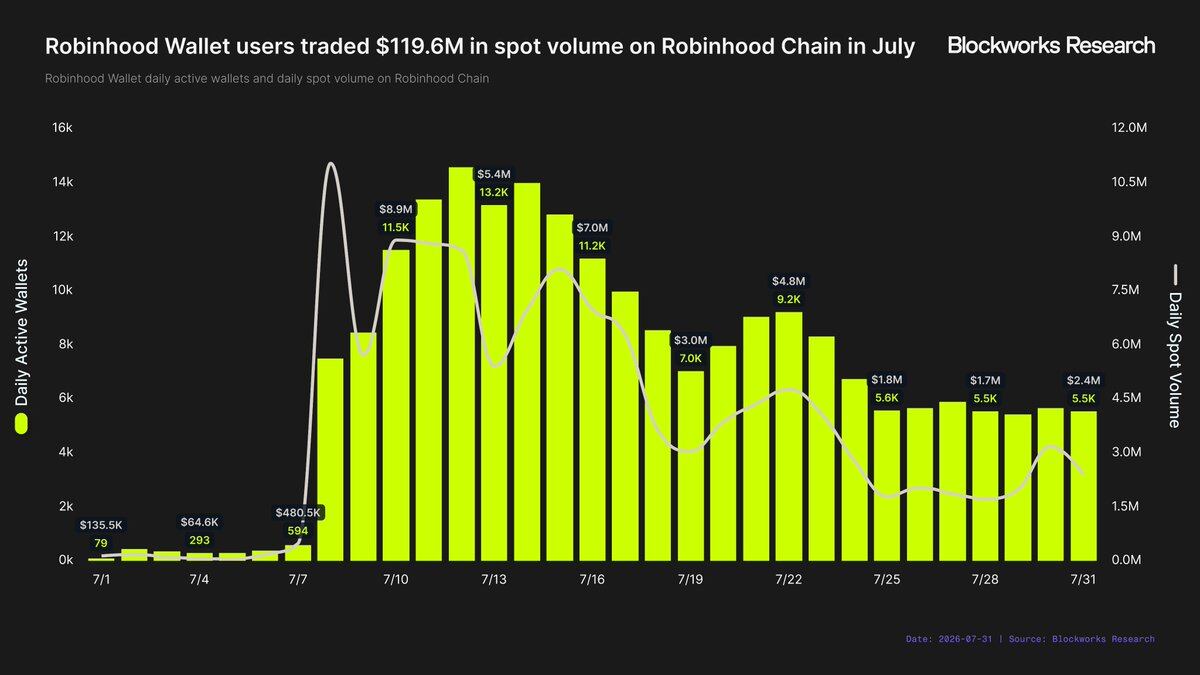
Looking solely at the activity on the Robinhood Chain, Robinhood Wallet users generated $119.6 million in transaction volume in July. Daily transaction volume peaked at $11 million on July 8, and by the last week of the month, it had declined to a daily average of $2.1 million. The average daily active wallet count for Robinhood Wallet in July was just under 7,000. This analysis does not account for wash trading, so the actual number of independent users may be lower.
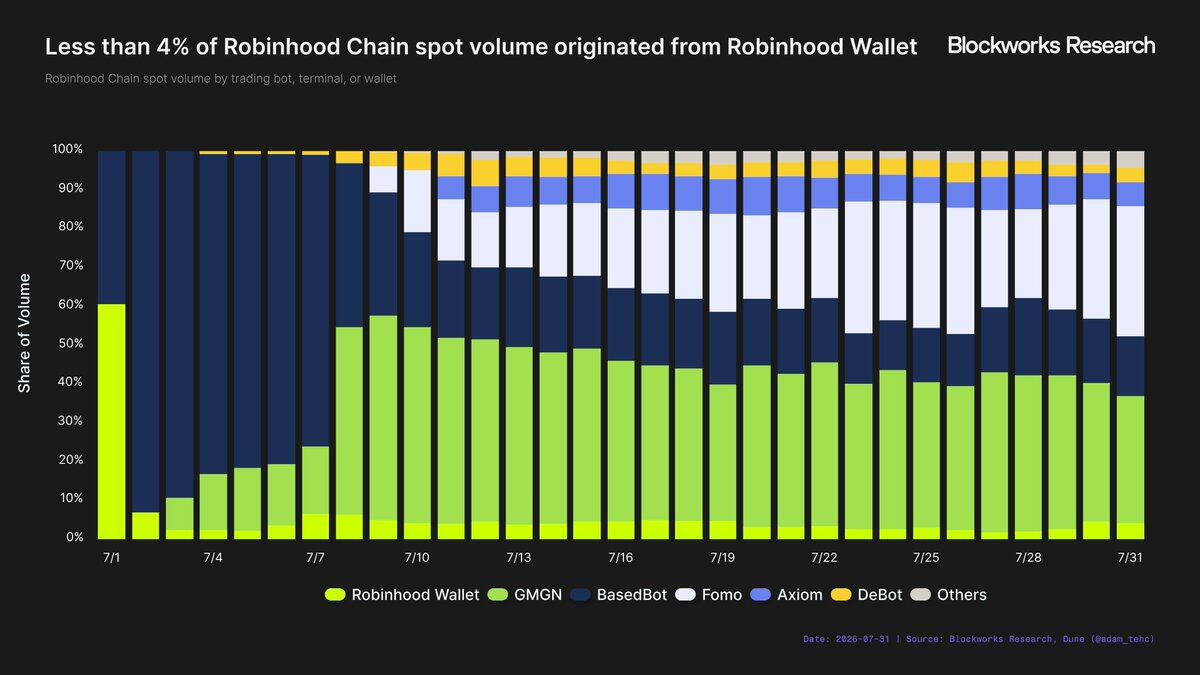
Compared to the broader wallet and trading app ecosystem on the Robinhood Chain, the Robinhood Wallet remains a relatively small player. Tracked wallets and trading apps generated a total trading volume of $30.8 billion in July, with Robinhood Wallet accounting for $1.196 billion, holding less than 4% market share. However, the transaction volume of these apps is mainly driven by power users. Robinhood Wallet ranks fourth in daily active wallet count but sixth in transaction volume.
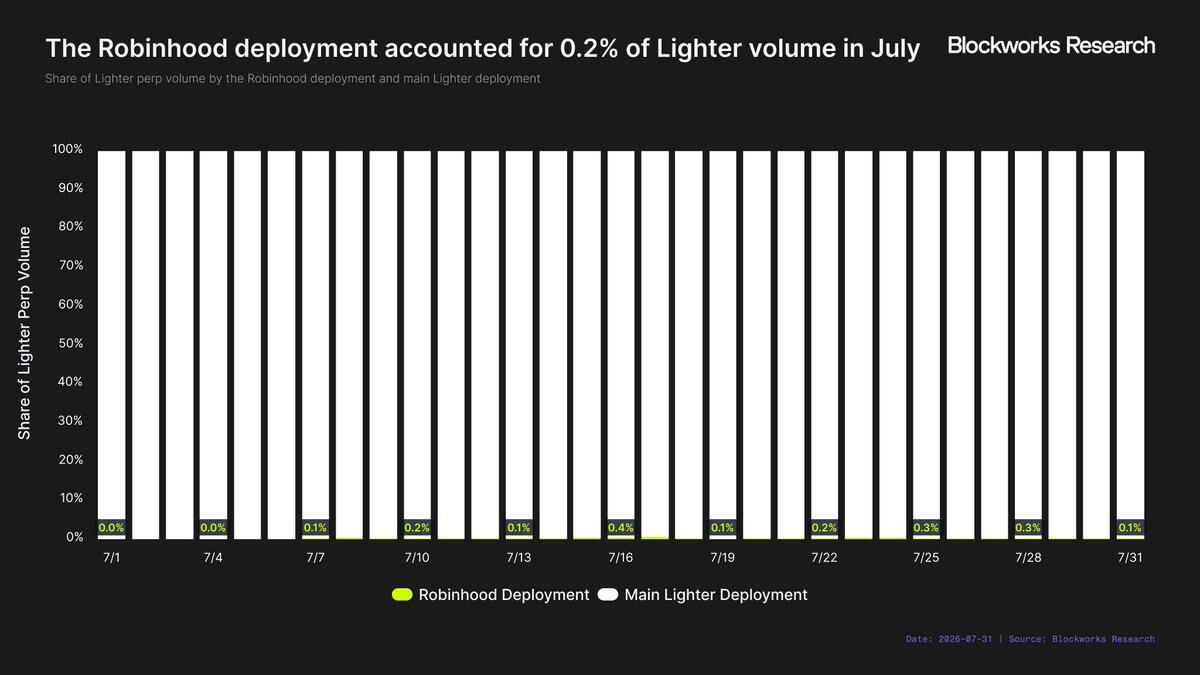
Lighter's integration further highlights the limited distribution value of the Robinhood Wallet. Since integration with the Robinhood Wallet, Lighter's trading volume through Robinhood accounted for only 0.2% of its perpetual contract total. In July, this figure was $86.8 million, lower than the spot trading volume generated through the Robinhood Wallet that month.
More concerning perhaps is that Lighter is directly incentivizing perpetual contract trading through the Robinhood Wallet, allocating 11 million LIT tokens, currently valued at around $25 million. Even the current limited trading volume is incentive-driven, and it may be even lower without these rewards. At present, it is challenging to determine how much revenue can be solely attributed to Robinhood Wallet distribution.
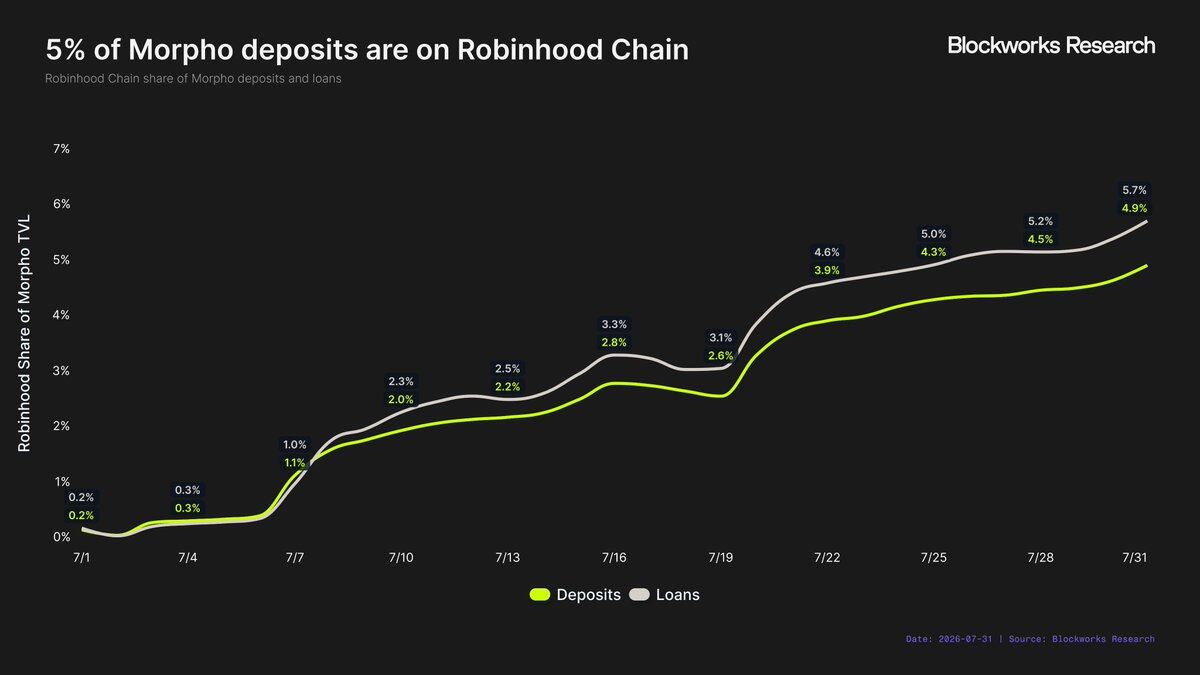
While the distribution value offered by the Robinhood Wallet may be limited, the situation is completely different for the main Robinhood app. Morpho provides the clearest example, where Robinhood users can directly deposit stablecoins into Morpho through the main app and earn a incentivized 7% APY. By the end of July, the market deployed by Morpho on the Robinhood Chain accounted for 5% of Morpho's total deposits and nearly 6% of all loans. In just one month since launch, Robinhood Chain has become Morpho's third-largest TVL market.
It must be acknowledged that this TVL is also incentivized. Nevertheless, the difference between distribution through the Robinhood main app and Robinhood Wallet is still significant. Although not a perfect apples-to-apples comparison, the share of the Robinhood Chain market in Morpho's total deposits is 25 times greater than the share of the Robinhood-deployed market in Lighter's perpetual contract total trading volume.
Therefore, early conclusions regarding the distribution value of Robinhood are mixed. For protocols able to secure direct integration into the Robinhood main app, the distribution value seems significant; however, distribution solely through the Robinhood Wallet is far less appealing. Unless Wallet integration can serve as a stepping stone to ultimately reach the main app, it is difficult to understand why a protocol would sacrifice meaningful economic upside for this.
Indeed, this conclusion is based on just two early cases. Robinhood has not formally designated in-app distribution trades as a broader strategic priority, and it is unclear to what extent the company plans to push forward with such partnerships. But the differences observed so far are notable. The true value of Robinhood's distribution capability does not come from being "associated with the Robinhood brand" or "deployed on the Robinhood Chain," but rather from being able to directly reach users in the Robinhood main app.
Can Robinhood Chain Revitalize Crypto Business
This report began with a core question—can Robinhood Chain make crypto a meaningful driver of Robinhood's growth?
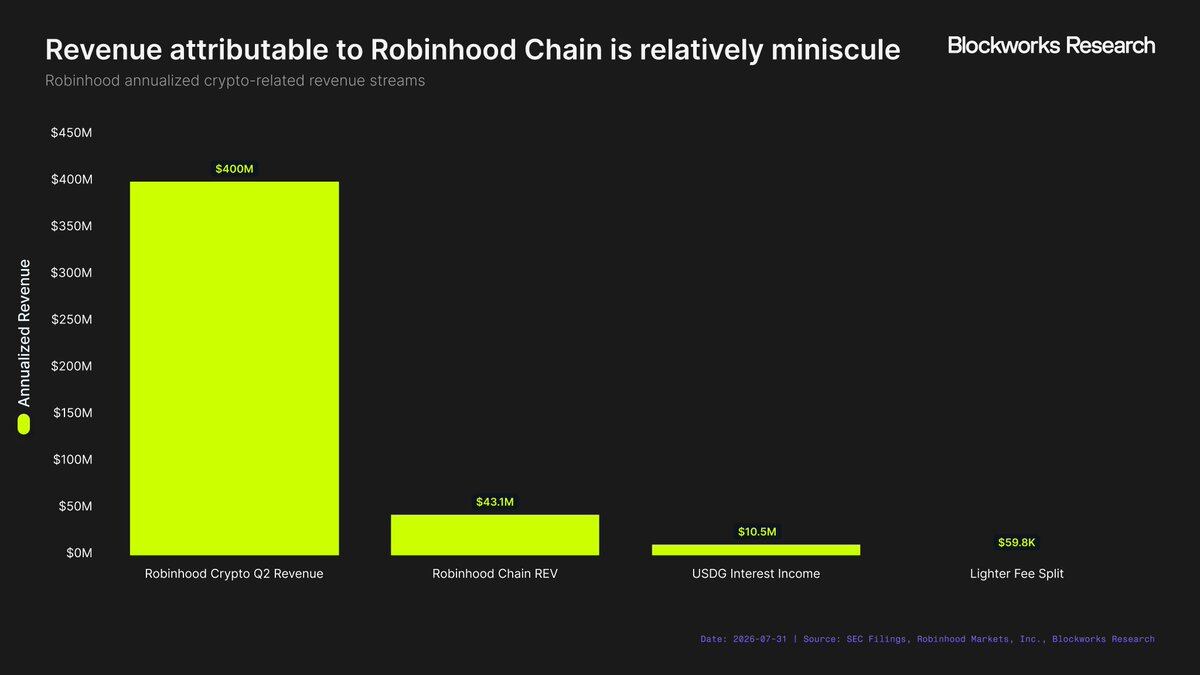
Early data paints a fairly clear picture. Robinhood Chain has achieved remarkable success as a blockchain but has not yet become a meaningful contributor to Robinhood's business. Robinhood's second-quarter crypto revenue was $100 million, annualizing to about $400 million. In comparison, the known, quantifiable revenue streams related to Robinhood Chain (chain REV, USDG interest income, Lighter fees shared with Robinhood) amount to only $54.8 million annually, approximately 14% of Robinhood's crypto business annual revenue. Admittedly, this comparison only annualizes the first-month data of Robinhood Chain and should not be mistaken for its long-term revenue potential.
Frankly, relying solely on network revenue, Robinhood Chain will never make a substantial impact on Robinhood. The block space is already too commoditized, and the entire L2 revenue market is too small. If Robinhood Chain is to make crypto a meaningful driver of Robinhood's growth, the company needs to monetize economic activity above the infrastructure layer.
Stablecoins Provide the Clearest Path. Tether and Circle have already demonstrated how lucrative stablecoin reserve interest can be. Calculated at a 3.5% yield, every $1 billion USDG in supply would generate $35 million in annualized revenue for Robinhood (assuming it retains all related interest income). With a supply of $10 billion, this figure would increase to $350 million annually, almost on par with Robinhood's current annualized crypto revenue. This won't happen overnight, but considering the scale and magnitude of Robinhood's business, achieving this goal is not unthinkable.
App Distribution is Another Compelling Opportunity. Robinhood possesses something almost all other blockchains lack—direct access to a large retail investor base. If on-chain protocols are willing to pay for access to these users or share revenue with Robinhood, Robinhood can monetize its distribution capabilities, not solely relying on fees generated by the chain itself. Early results suggest that when protocols integrate into the Robinhood main app, this strategy does work, although the value of the Robinhood Wallet distribution itself is marginal.
There is another possibility that Robinhood does not see Robinhood Chain as a standalone revenue-generating business. Instead, it might view this chain as a user onboarding and conversion channel. Robinhood Chain could serve as a traffic acquisition tool, allowing users to interact with tokenized assets before trading stocks, options, crypto, and other products within the broader Robinhood ecosystem. In this scenario, the chain's value may not lie in network revenue but rather in higher engagement and revenue in other areas of the Robinhood business.
Currently, the answer to the question posed at the beginning of this report is still "No." Robinhood Chain has not yet become a meaningful driver of Robinhood's growth, and it will never achieve this solely through network revenue; to eventually turn the answer to "Yes," Robinhood needs to expand the USDG scale or commercialize the user distribution capabilities of the Robinhood main app. Otherwise, Robinhood Chain is likely to only have indirect financial value, serving as a traffic acquisition tool for the high-value products already driving Robinhood's business.
Original Post Link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles