



Bernstein Deciphers SpaceX's First Earnings Report, How Was the $239 Price Target Justified?

TL;DR
· SpaceX's second-quarter revenue was $7.81 billion, a year-over-year increase of 92%. Bernstein maintains an "Outperform" rating and a $239 price target.
· Bernstein's model still assumes a long-term price decline to around $10/W, with Musk's proposed $30 to $50/W not yet fully reflected in the price target.
· Connectivity provides the current profit base, AI computing determines revenue elasticity, and full reusability of Starship will determine whether long-term costs can truly decrease.
SpaceX's first post-IPO quarter performance presents a more aggressive growth story to the market: The Connectivity business continues to contribute to profits, AI computing revenue is growing rapidly, Musk has advanced the target year to achieve $1 trillion in annual revenue from 2031 to 2030, and suggests it could potentially be achieved as early as 2029.
According to SEC filings, Space Exploration Technologies Corp.'s Class A common stock is trading under the ticker symbol SPCX on the Nasdaq and Nasdaq Texas exchanges. Following the release of the second-quarter results ending June 30 on August 4, Bernstein maintained an "Outperform" rating and a $239 price target. Based on the closing price of $125.33 on August 4 as stated in the research report, this corresponds to approximately 91% potential upside.
However, the $239 price target is not based on the full realization of the $1 trillion revenue target. Bernstein's own revenue forecast for SpaceX in 2031 is $554 billion, significantly below the management's vision; its AI computing price model also still assumes a long-term decline to around $10/W. In other words, the higher computing prices and more aggressive revenue targets represent potential upside beyond the current valuation.
On August 5, SpaceX's stock price fell further to $108.27, a one-day decline of 13.6%. This indicates that the market is not only considering this quarter's performance, but also weighing AI capital expenditures, stock supply pressure from the post-IPO lockup expiration, and whether Starship can enter a high-frequency, low-cost launch phase.
Revenue Soars by 92%, Connectivity Remains Profit Backbone
In the second quarter, SpaceX's revenue reached $7.814 billion, a 92% year-over-year increase. While Axios cited S&P Visible Alpha's consensus at $6.9 billion, Bernstein's report used a market consensus of $6.546 billion. Despite different data sources, both point to the same conclusion: Revenue for this quarter significantly exceeded expectations.
In the second quarter, the company reported a diluted loss per share of $0.09, which was better than the market's expected loss per share of $0.24. The combined operating loss of the three business segments was $143 million, significantly outperforming Bernstein's expected $1.73 billion, mainly due to the narrowing of the AI business's loss and a higher-than-expected Connectivity profit margin.
Looking at each segment, the most stable one currently remains the Connectivity business centered around Starlink. By the end of the second quarter, Starlink's user base reached 12 million, an increase of 1.7 million from the first quarter, with average monthly user revenue remaining at $66.
Connectivity's quarterly revenue was $4.291 billion, with an operating profit of $1.656 billion, corresponding to an operating profit margin of approximately 38.6%, higher than Bernstein's expected 37%. It is also the only business segment of SpaceX that is currently profitable, providing crucial support for the company's continued investment in AI and Starship.
The Space segment completed a total of 38 launches in the second quarter, including 10 customer launches and 28 internal launches, with a total Mass to Orbit (MTO) of 485 tons. This segment generated $0.962 billion in revenue, higher than the market's expected $0.874 billion, but due to increased investment in Starship development, it still incurred an operating loss of $0.542 billion.
The AI business has both the highest revenue elasticity and funding requirements. By the end of the second quarter, SpaceX's nominal computing capacity reached 1.4GW, up from 1.0GW in the first quarter, and is expected to exceed 2GW by the end of 2026. The AI segment's quarterly revenue was $2.561 billion, a 247% year-on-year growth, with AI solutions and infrastructure revenue reaching $2.194 billion.
The operating loss of the AI business was $1.257 billion, corresponding to a negative operating margin of 49.1%, but significantly narrower than the $2.469 billion operating loss in the first quarter; adjusted EBITDA for the segment changed from a $0.609 billion loss in the first quarter to a $1.146 billion profit.
Meanwhile, the AI business's capital expenditure in the second quarter reached $15.828 billion, up from $7.723 billion in the first quarter. SpaceX's total capital expenditure in the second quarter reached $18.369 billion. Whether this massive investment can translate into sustainable revenue and cash returns remains one of the market's key concerns.
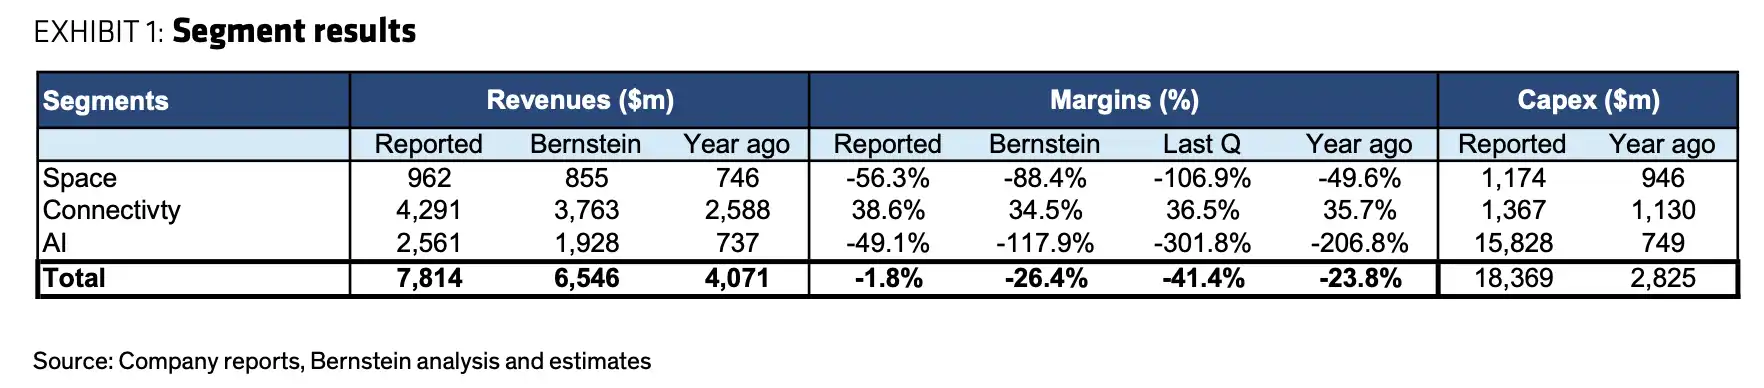
SpaceX Second Quarter Performance by Division. Connectivity contributed the majority of the profit, with AI business capital expenditures reaching $15.828 billion. Source: Bernstein
AI Computing Expands Revenue Potential, Trillion-Dollar Revenue Not Solely Relying on Satellite Internet
The most notable change in this earnings call was Musk advancing the target year to achieve $1 trillion in annual revenue from 2031 to 2030, with a possibility of reaching it as early as 2029. The management also mentioned an expected run rate of at least $100 billion in annual revenue, but the Bernstein research summary did not clearly specify the corresponding timeframe.
To approach this goal, SpaceX evidently cannot rely solely on Starlink user growth. Connectivity needs to further expand individual, enterprise, and government customers; the AI business needs to transform massive computing capacity into long-term contracts and stable revenue; and Starship needs to reduce satellite deployment and orbital data center construction costs.
Among these, the price of AI computing is the most critical variable.
Musk stated that the computing service price may remain at $30 to $50 per watt, indicating this assessment aligns with the deal prices SpaceX reached with Anthropic and Google. In contrast, the Bernstein current model still assumes the final computing price will drop to around $10 per watt.
This means that the $30 to $50 per watt is not a base assumption already factored into Bernstein's $239 target price but is a potential upside to the model. If SpaceX can maintain a higher price while expanding computing capacity, its long-term revenue and EBITDA could significantly surpass Bernstein's current estimates.
However, the sustainability of this price range remains uncertain. Factors such as contract terms and cancellation clauses, supply and demand in the AI computing market, semiconductor supply, and competitors' capacity expansions could all impact the actual transaction price.
The capacity expansion target is equally ambitious. At the end of the second quarter, SpaceX's nominal computing capacity was 1.4GW. The company expects to exceed 2GW by the end of 2026, reach close to 10GW by the end of 2027, and move towards 20GW in 2028. If this pace is achieved, SpaceX's business structure will no longer be limited to rocket launches and satellite internet but will further extend to large-scale AI infrastructure.
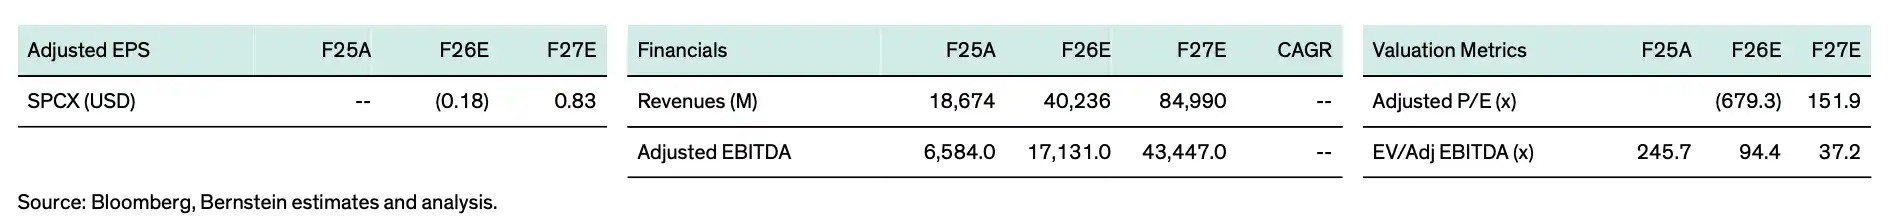
Key Financials and Valuation Forecast Table. Bernstein expects SpaceX's revenue for the years 2025 to 2027 to be $18.674 billion, $40.236 billion, and $84.99 billion, respectively, with the EV/Adjusted EBITDA multiple decreasing from 245.7x to 37.2x.
The Premise of High-Frequency Launches is Starship Achieving Full Reusability
In SpaceX's valuation framework, Connectivity answers "Is there a current profit base," AI computation answers "How fast can revenue still grow," and Starship answers "Can long-term scale be achieved at a low enough cost."
If SpaceX is to approach nearly $1 trillion in annual revenue by around 2030, relying solely on Starlink user growth will not be sufficient. The launch frequency, payload capacity, and full reusability of Starship will directly impact the deployment cost of the next generation of Starlink satellites, orbital data center construction, and the expansion of other space businesses.
The management team has currently set very aggressive schedule goals. The company plans to continue advancing Starship orbital flights and V3 satellite deployment, and attempt more complex first and second stage recovery maneuvers. Its long-term goal is to be close to launching once per day by the end of 2027 and operate five launch pads, two in Texas and three in Florida.
To achieve this frequency, SpaceX not only needs to reuse boosters but also must address the second stage recovery of Starship. Bernstein believes that a durable heat shield is key to full reusability of the second stage. Musk has indicated that the 13th flight may have already solved the heat shield issue, but related analysis is not yet complete and further flights are needed for validation.
Regulatory approvals, launch pad construction, flight accidents, and review cycles may also affect the speed at which Starship transitions from high-frequency testing to industrialized operations. Therefore, full reusability remains the most important and also the most uncertain part of Bernstein's valuation model.
$239 Price Target Depends on Three Key Themes Converging
Bernstein bases the 2031 EBITDA of SpaceX's various businesses, calculates the 2030 enterprise value using a sum-of-the-parts valuation and long-term EV/EBITDA multiples, and then discounts the valuations of each segment to mid-2027 to arrive at a 12-month target price of $239. Connectivity and AI each use a 25% and 35% late-stage venture risk discount rate, respectively.
Of note, the Bernstein model projects SpaceX's revenue in 2031 to be $554.0 billion, significantly below the management's proposed $1 trillion target. Its long-term pricing assumptions still assume a drop to around $10 per watt, rather than Musk's proposed $30 to $50 per watt.
Therefore, the $239 price target does not require SpaceX to fully achieve all aspects of the management's vision, but it still incorporates strong business expansion assumptions. It requires at least three components to come together: continued growth in Connectivity profits, AI computing transitioning from high capital expenditure to scale revenue, and Starship completing full reusability validation as planned.
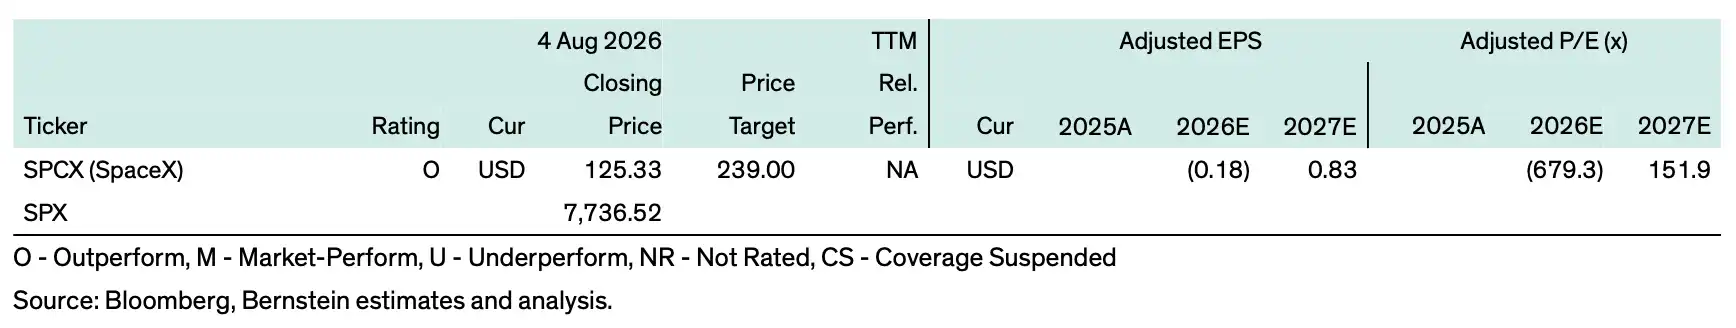
Following SpaceX's post-IPO stock price decline, Bernstein maintains a $239 price target and Outperform rating. Source: Bernstein
This also explains why SpaceX's second-quarter revenue and earnings per share exceeded expectations, yet the stock price plummeted post-earnings. A single-quarter performance can only prove that current growth remains robust, but it cannot directly eliminate market concerns about AI investment returns, stock unlock supply, and Starship execution risks.
If AI computing prices can sustain at $30 to $50 per watt for a longer period, Starship achieves full reusability as planned, Starlink's individual and enterprise customer base continues to grow, Bernstein's current model still has room for upward revision. Conversely, if compute contract realizations, semiconductor supply, or Starship progress fall short of expectations, the $239 price target itself will face pressure.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia





