



The Fintech 4.0 era is coming, and a deep understanding of users will become a core competitive advantage.
Original Article Title: Specialized Stablecoin Fintechs
Original Article Authors: Spencer Applebaum & Eli Qian, Multicoin Capital
Translation: Peggy, BlockBeats
Editor's Note: Over the past two decades, financial technology innovation has primarily focused on the distribution layer, improving user experience without changing the underlying logic of fund flows. This has led to industry homogenization, high costs, and slim profits. The emergence of stablecoins is reshaping this landscape. Through open, programmable on-chain infrastructure, the costs of custody, settlement, credit, and compliance have significantly decreased, enabling fintech companies to build products directly on-chain without relying on banks and card networks.
As infrastructure becomes inexpensive, specialization becomes possible. The future of fintech will no longer pursue scale but instead will deeply serve specific groups, creating products that truly meet their needs. The competitive core of Fintech 4.0 will shift from "who can reach the customer" to "who truly understands the customer."
The following is the original article:
Over the past two decades, fintech has changed how people access financial products, but it has not changed how funds actually flow. Innovation has mainly focused on cleaner interfaces, smoother onboarding processes, and more efficient distribution, while the core financial infrastructure has remained largely unchanged. For much of this time, the tech stack has been resold rather than rebuilt.
Overall, the development of fintech can be divided into four stages:
Fintech 1.0: Digital Distribution (2000–2010)
The earliest wave of fintech made financial services more accessible but did not significantly improve efficiency. Companies like PayPal, E*TRADE, and Mint digitized traditional systems (ACH, SWIFT, and card networks established decades ago) through internet interfaces, packaging them as existing products.
Settlements were still slow, compliance still relied on manual processes, and payments were still made on a fixed schedule. This era moved finance online but did not change how funds flow in a completely new way. It changed who could use financial products, not how these products operated.
Fintech 2.0: Neobank Era (2010–2020)
The next breakthrough came from smartphones and social distribution. Chime offered early wage access for gig workers; SoFi focused on refinancing student loans for upwardly mobile graduates; Revolut and Nubank reached underserved global consumers with a user-friendly experience.
Every company tells a more vivid story to a specific audience, but fundamentally sells the same product: checking accounts and debit cards running on existing rails. They rely on sponsor banks, card networks, and ACH, just like their predecessors.
These companies succeed not because they built new payment rails, but because they better reach customers. Branding, account opening experience, and customer acquisition capabilities are their strengths. Fintech companies of this era have become efficient distribution layers stacked on top of banks.
Fintech 3.0: Embedded Finance (2020–2024)
Around 2020, embedded finance emerged. APIs enable nearly any software company to offer financial products. Marqeta enables card issuance for businesses through APIs; Synapse, Unit, and Treasury Prime offer Banking as a Service (BaaS). Soon, almost every app can offer payment, card, or lending services.
But beneath this abstraction layer, the core remains unchanged. BaaS providers still rely on the same sponsor banks, compliance frameworks, and payment rails. The abstraction layer has shifted from banks to APIs, but economic and control ownership still flows back to traditional systems.
Commoditization of Fintech
By the early 2020s, the cracks in this model were evident everywhere. Almost all major neobanks relied on the same small group of sponsor banks and BaaS providers.
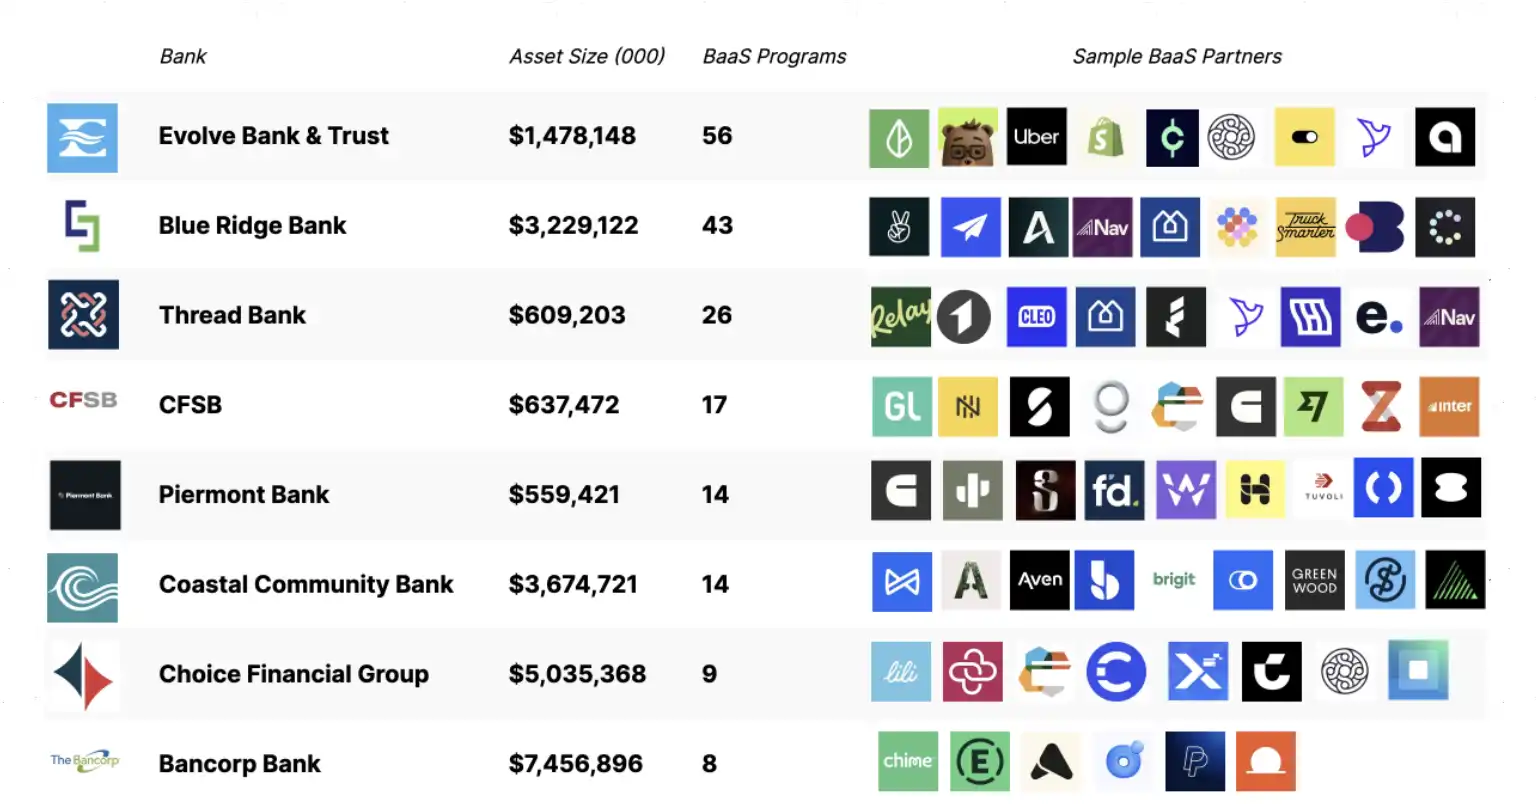
As a result, customer acquisition costs soared, companies engaged in fierce competition through performance marketing, profit margins were squeezed, fraud and compliance costs escalated rapidly, and infrastructure became almost indistinguishable. Competition evolved into a marketing arms race. Many fintech companies tried to differentiate themselves through card colors, sign-up bonuses, and cashback gimmicks.
At the same time, risk and value capture concentrated at the banking level. Giant institutions like JPMorgan Chase and Bank of America, regulated by the OCC, retained core privileges: taking deposits, issuing loans, and accessing federal payment rails (such as ACH and Fedwire). Fintech companies like Chime, Revolut, and Affirm lacked these privileges and had to rely on chartered banks to provide services. Banks earn spreads and platform fees; fintech companies rely on interchange fees for revenue.
With the surge of FinTech projects, regulatory scrutiny on the sponsoring banks behind them is increasing. Regulatory orders and elevated supervision requirements are forcing banks to allocate significant funds towards compliance, risk management, and overseeing third-party projects. For example, Cross River Bank entered into a regulatory order with the Federal Deposit Insurance Corporation (FDIC), Green Dot Bank faced enforcement action from the Federal Reserve, and the Federal Reserve issued a cease-and-desist order against Evolve.
Banks are responding by tightening their account opening processes, limiting the number of supported projects, and slowing down product iteration. Models that were once allowed to be experimental now increasingly require scale to demonstrate the reasonableness of the compliance burden. FinTech is becoming slower, more expensive, and inclined to develop broad-use products rather than specialized products.
In our view, the three main reasons why innovation has remained at the top layer of the tech stack for the past 20 years are:
The funds flow infrastructure is monopolized and closed. Visa, Mastercard, and the Federal Reserve's ACH network leave little room for competition.
Startups require a significant amount of capital to build financially core products. Launching a regulated banking application requires millions of dollars for compliance, fraud prevention, fund management, etc.
Regulatory restrictions hinder direct participation. Only licensed entities can hold funds or transfer funds via the core rails.
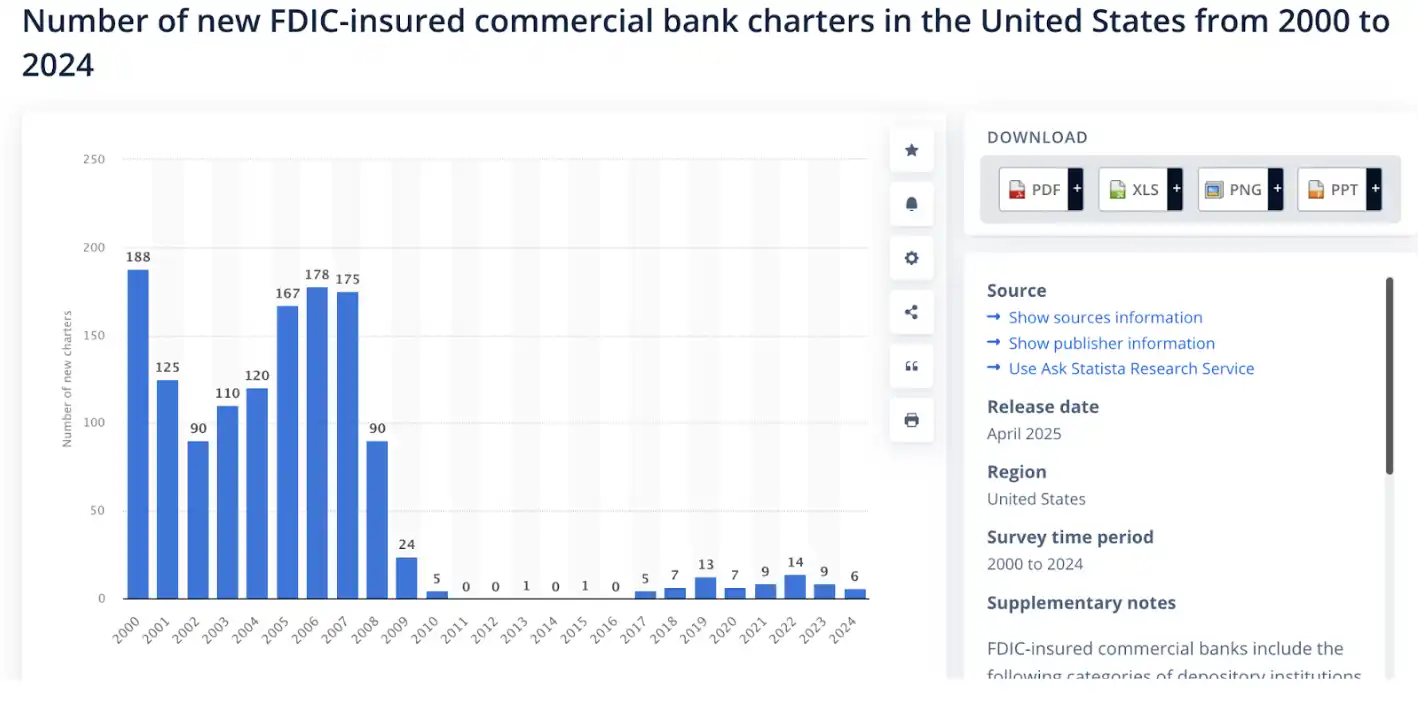
Within these limitations, building products seemed more reasonable than challenging the payment rails themselves. As a result, most FinTech companies are merely a fancy wrapper around bank APIs. Despite two decades of innovation, this industry has hardly created truly new financial primitives. For a long time, there have been hardly any viable alternatives.
Cryptocurrency, on the other hand, has taken a completely opposite path. Builders first focused on foundational primitives. Automated market makers, bonding curves, perpetual contracts, liquidity pools, and on-chain credit emerged from the ground up. Financial logic became programmable for the first time.
Fintech 4.0: Stablecoins and Permissionless Finance
Although the first three FinTech eras brought about a lot of innovation, the underlying pipes remained largely unchanged. Whether the product is delivered through a bank, neo-bank, or embedded API, funds still flow in closed, permissioned rails controlled by intermediaries.
Stablecoins disrupt this pattern. The stablecoin-native system no longer layers software on top of banks but directly replaces critical banking functions. Builders interact with open, programmable networks. Payments settle on-chain. Custody, lending, and compliance shift from contractual relationships to software logic.
Banking as a Service (BaaS) has reduced friction but has not changed the economic structure. FinTech companies still need to pay compliance fees to sponsor banks, settlement fees to card networks, and access fees to intermediaries. The infrastructure remains expensive and limited.
Stablecoins have completely eliminated the need for rented access. Builders no longer make API calls to banks but instead write directly to an open network. Settlements occur directly on-chain. Fees belong to the protocol, not intermediaries. We believe the cost baseline will significantly decrease: from the millions of dollars required to build through a bank or the hundreds of thousands of dollars required through BaaS to only a few thousand dollars to use smart contracts on a permissionless chain.
This transformation has already manifested at scale. In less than a decade, stablecoins have grown from almost zero to around $300 billion in market capitalization and have surpassed traditional payment networks (such as PayPal and Visa) in processing real economic transaction volumes, even excluding exchange-to-exchange transfers and MEV. A non-bank, non-card rail has emerged and is truly operational on a global scale.

To understand the practical significance of this transformation, one must first look at how FinTech is built today. A typical FinTech company relies on a vast vendor tech stack:
- User Interface / User Experience (UI/UX)
- Banking and Custody Layers: Evolve, Cross River, Synapse, Treasury Prime
- Payment Rails: ACH, Wire, SWIFT, Visa, Mastercard
- Identity and Compliance: Ally, Persona, Sardine
- Fraud Prevention: SentiLink, Socure, Feedzai
- Credit / Lending Infrastructure: Plaid, Argyle, Pinwheel
- Risk and Fund Management Infrastructure: Alloy, Unit21
- Capital Markets: Prime Trust, DriveWealth
- Data Aggregation: Plaid, MX
- Compliance / Reporting: FinCEN, OFAC Checks
Launching a FinTech company on this tech stack entails managing contracts, audits, incentives, and failure modes across dozens of partners. Each layer adds costs and delays, and many teams spend almost as much time coordinating infrastructure as they do building products.
The native stablecoin system then compresses this complexity entirely. What used to require six or seven vendors to complete can now be converged into a small number of on-chain primitives.
In the world of stablecoins and permissionless finance: banks and custody are replaced by Altitude; payment rails are replaced by stablecoins; identity and compliance are still necessary, but we believe it can be achieved on-chain and kept confidential and secure through technologies like zkMe; credit and lending infrastructure will be restructured and migrated on-chain; capital market companies will lose relevance after all assets are tokenized; data aggregation is replaced by on-chain data and selective transparency, leveraging technologies like Fully Homomorphic Encryption (FHE); compliance and OFAC checks are completed at the wallet layer (e.g., if Alice's wallet is on a sanctions list, she will be unable to interact with the protocol)
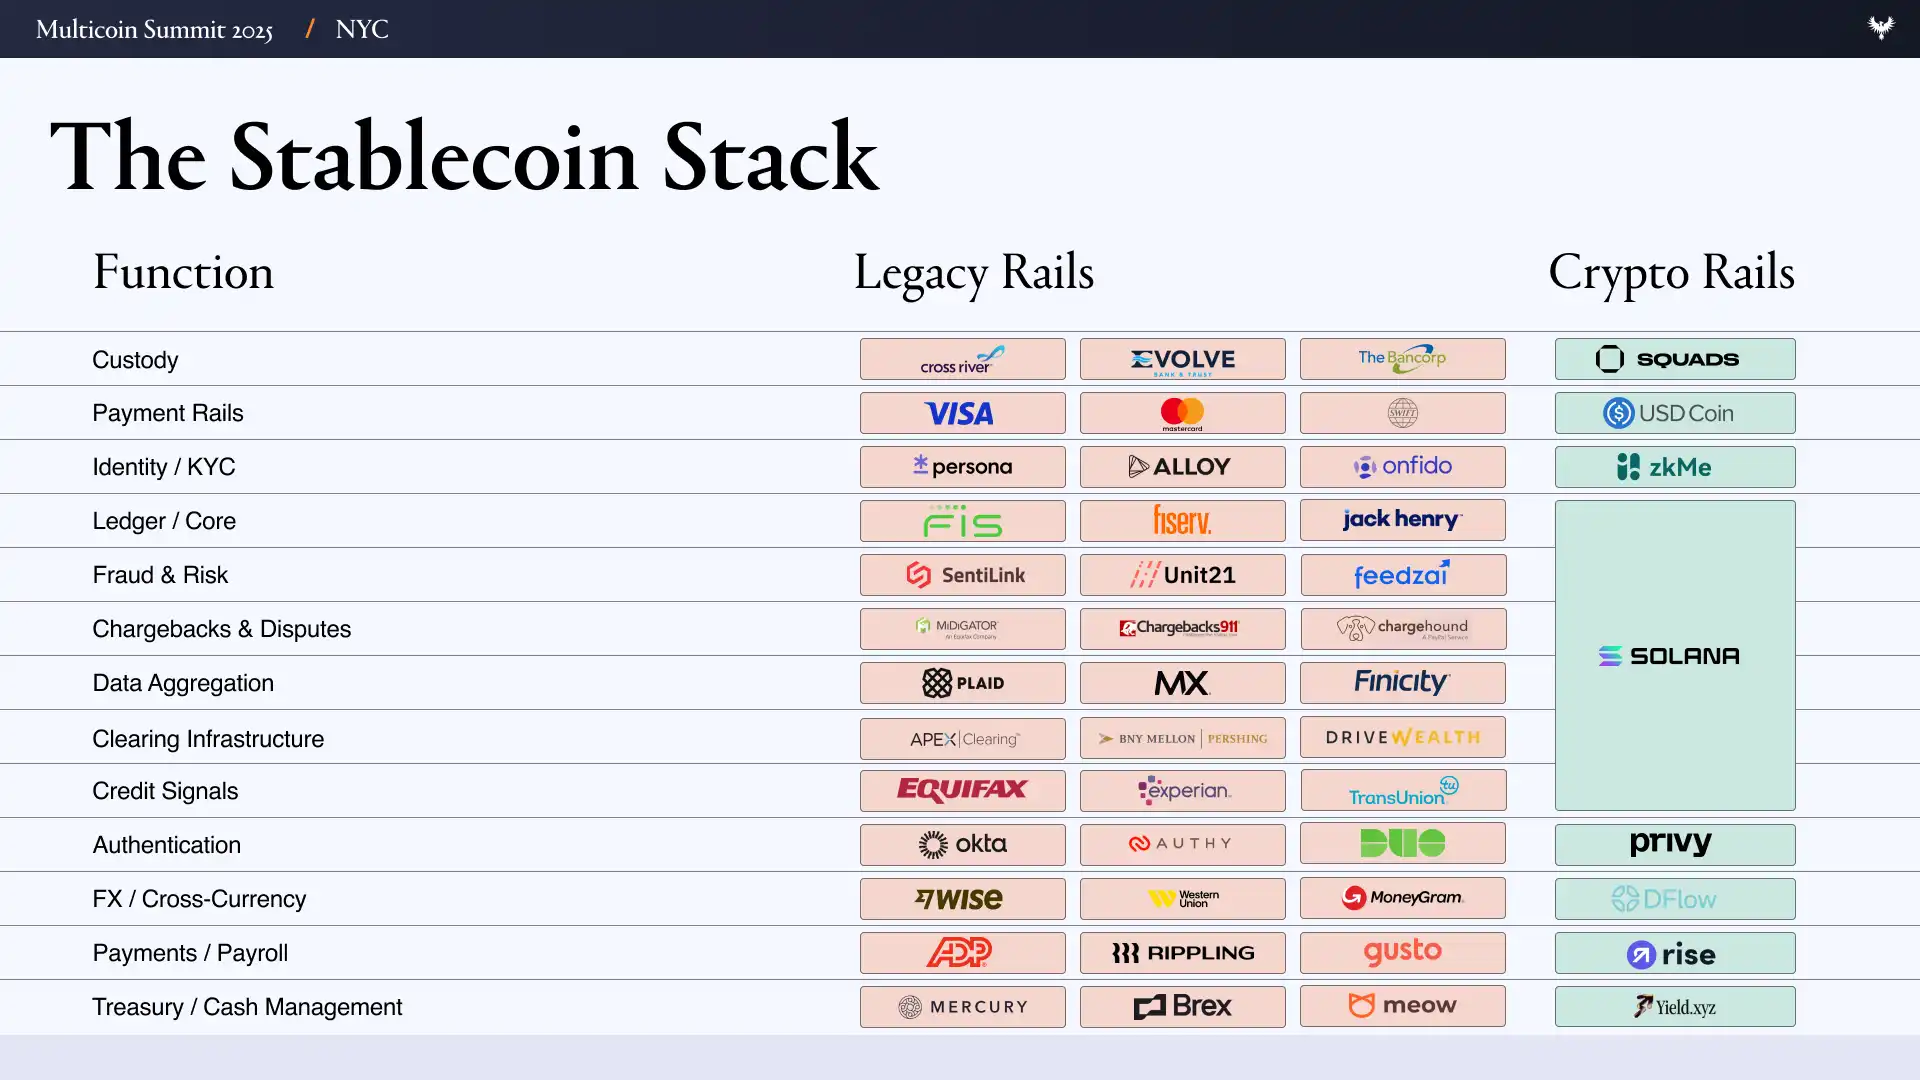
This is the true difference of Fintech 4.0: the underlying pipes of finance are finally changing. People are no longer just building an app that quietly "asks the bank for permission" in the background but are directly replacing large chunks of banking functionality with stablecoins on an open rail. The builders are no longer tenants; they are starting to own the "land."
Opportunities for "Specialized Stablecoin Fintech"
The first-order effect of this shift is straightforward: far more financial technology companies can exist. When custody, lending, and money transfer are nearly free and instantaneous, launching a fintech company starts to look like launching a SaaS product. In a stablecoin-native world, there are no sponsor banks to integrate with, no card issuing intermediaries, no multi-day settlement windows, or repetitive KYC audits to slow things down.
We believe that launching a "finance-first" product will see its fixed costs drop from millions of dollars to thousands once infrastructure, customer acquisition cost (CAC), and compliance hurdles disappear. Once these costs vanish, startups will be able to profitably serve smaller, more specific communities through what we call the "specialized stablecoin fintechs" model.
There is a clear historical parallel here. The last generation of fintech started by serving specific customer segments: SoFi for student loan refinancing, Chime for early wage access, Greenlight for teen debit cards, Brex for entrepreneurs without traditional business credit. However, this specialization did not become a sustainable operating model: interchange capped revenue, compliance costs grew with scale, reliance on sponsor banks forced teams out of their initial niche markets. To survive, they were pushed to expand horizontally, adding products that were not strong user demands but rather to make the infrastructure scale viable.
Due to the significantly reduced barrier to entry enabled by the crypto-native space and permissionless financial APIs, a new wave of specialized stablecoin-native banks is poised to emerge — each catering to specific demographics akin to early fintech innovators. With markedly lower operational costs, these banks can focus on narrower, more specialized markets and maintain a niche focus: such as adhering to Islamic finance principles, catering to the lifestyle of crypto "power users," or serving athletes with unique income and expense patterns.
The second-order effects are even more pronounced: specialization improves the unit economics. Customer Acquisition Cost (CAC) decreases, cross-selling becomes easier, and Customer Lifetime Value (LTV) increases. Specialized fintech can precisely match products with marketing to efficiently convert niche audiences and leverage stronger word-of-mouth referrals within specific demographics. These ventures can achieve a clearer path to "more value per customer" while managing lower overhead costs compared to the previous generation of fintech.
As anyone can launch a fintech company within weeks, the focus of the question will shift from "who can reach customers?" to "who really understands them?"
Exploring the Design Space of Specialized Fintech
The most attractive opportunities often arise where traditional rails fall short.
Take adult creators and performers, for example: they generate billions of dollars in revenue annually but are often excluded by banks and card networks due to reputational and chargeback risks. Funds are delayed by days, temporarily withheld for "compliance reviews," and require payment through high-risk gateways (such as Epoch, CCBill) with fees ranging from 10 to 20%. We believe that payment based on stablecoins can offer instant, irreversible settlements, programmable compliance, enabling practitioners to self-custody earnings, automatically route a portion to tax or savings wallets, and receive global payments without relying on high-risk intermediaries.
Now, consider professional athletes, especially individual sport players like golfers and tennis players, who face unique cash flow and risk structures. Income is concentrated in a short career window, often needing to allocate among agents, coaches, and teams; taxed across multiple states and countries; and prone to abrupt halts due to injuries. A stablecoin-native fintech can help tokenize their future earnings, facilitate team payments via multi-signature wallets, and automatically withhold taxes by jurisdiction.
Luxury goods and watch dealers represent another market underserved by traditional financial infrastructure. These businesses often conduct high-value cross-border transactions using wire transfers or high-risk payment processors for six-figure deals, waiting days for settlements. Operating capital is often locked in inventory in safes or showcases rather than bank accounts, making short-term financing both expensive and hard to obtain. We believe that stablecoin-native fintech can directly address these constraints: instant settlement of large transactions, credit lines secured by tokenized inventory, and programmable escrow embedded in smart contracts.
When you see enough examples, you'll notice a recurring constraint: banks are not good at serving those with globally diversified, uneven, or unconventional cash flows. But these groups could be a profitable market on the stablecoin track. We believe attractive examples of "specialized stablecoin fintech" theory include:
1. Professional Athletes: Income concentrated in the short term; frequent travel and relocation; may need to declare taxes in multiple locations; team payments involve coaches, agents, trainers, etc.; may want to hedge against injury risk.
2. Adult Creators and Performers: Excluded by banks and card networks; audiences scattered globally.
3. Unicorn Company Employees: Cash-strapped, net worth highly concentrated in illiquid equity; high tax burden on option exercise.
4. On-Chain Builders: Net worth concentrated in highly volatile tokens; difficulties with fiat on/off-ramps and tax handling.
5. Digital Nomads: No need for traditional passport-bank relationships; automatic forex conversion; automated tax based on location; frequent travel and migration.
6. Remittances for Inmates' Family/Friends: Difficult and expensive to remit funds to them through traditional channels.
7. Sharia-Compliant Finance Followers: Avoiding interest.
8. Gen Z: Distrustful of traditional banking services; investment through gamification; socially-driven financial experiences.
9. Cross-Border Small and Medium Enterprises (SMEs): High forex costs; slow settlements; frozen working capital.
10. Crypto Heavy Gamers (Degens): Payment and credit experiences around high-risk preferences (such as managing bills with a "casino" mentality).
11. Foreign Aid: Slow flow of aid funds, multi-layered intermediaries, and opacity; costs, corruption, and misalignment leading to significant "leakage."
12. Tandas / Rotating Savings Groups: Naturally cross-border for global families; collective savings earn interest; potential to use on-chain records to accumulate income history for credit.
13. Luxury Goods/Watch Dealers: Working capital tied up in inventory; need short-term loans; often conduct high-value, cross-border transactions; often transact through chat apps like WhatsApp, Telegram, etc.
Summary
For much of the past two decades, fintech innovation has been focused on the distribution layer rather than the infrastructure. Companies have been competing on branding, onboarding experience, and fee-based customer acquisition, but the funds themselves still flow along the same closed loop. This has indeed expanded financial services' accessibility, but it has also led to product homogenization, rising costs, and inescapable thin margins.
Stablecoins are poised to change the economic logic of financial product construction. By transforming functions such as custody, settlement, credit, and compliance into open, programmable software, they have significantly reduced the fixed costs of launching and operating a fintech company. What once required reliance on the capabilities of sponsor banks, card networks, and a large vendor stack can now be built directly on-chain, with a greatly reduced overhead.
As infrastructure becomes cheaper, specialization becomes feasible. Fintech companies no longer need millions of users to be profitable; instead, they can focus on underserved niche groups that are not well-served by "one-size-fits-all" products. Communities such as athletes, adult creators, K-pop fans, or luxury watch dealers already share context, trust, and behavioral patterns, making products easier to spread through organic adoption rather than paid marketing.
Equally important, these communities often have similar cash flow characteristics, risks, and financial decision-making. This consistency allows products to be designed around how people actually earn, spend, and manage money, rather than based on abstract demographic categories. Word-of-mouth spreads not just because users know each other but because the product genuinely aligns with how that group operates.
If our vision becomes reality, this economic transformation will be significant. As distribution becomes community-native, customer acquisition cost decreases; as intermediaries exit, profit margins increase. Markets that once seemed too small or uneconomical will become sustainable, profitable businesses.
In this world, the advantage of fintech will shift from "scale and marketing spend" to "true contextual understanding." The next generation of fintech will not win by trying to serve everyone but by building infrastructure that matches the actual flow of funds while providing exceptional service to a specific group.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia






