Solana Meme Platform Battle: Did Raydium Emerge as the Biggest Winner Instead?
Original Article Title: "Why is Raydium Considered the Biggest Beneficiary of Letsbonk.fun's Rise?"
Original Article Author: Azuma, Odaily Planet Daily
Letsbonk.fun has recently completed a data-level comeback against the race track "big brother" Pump.fun.
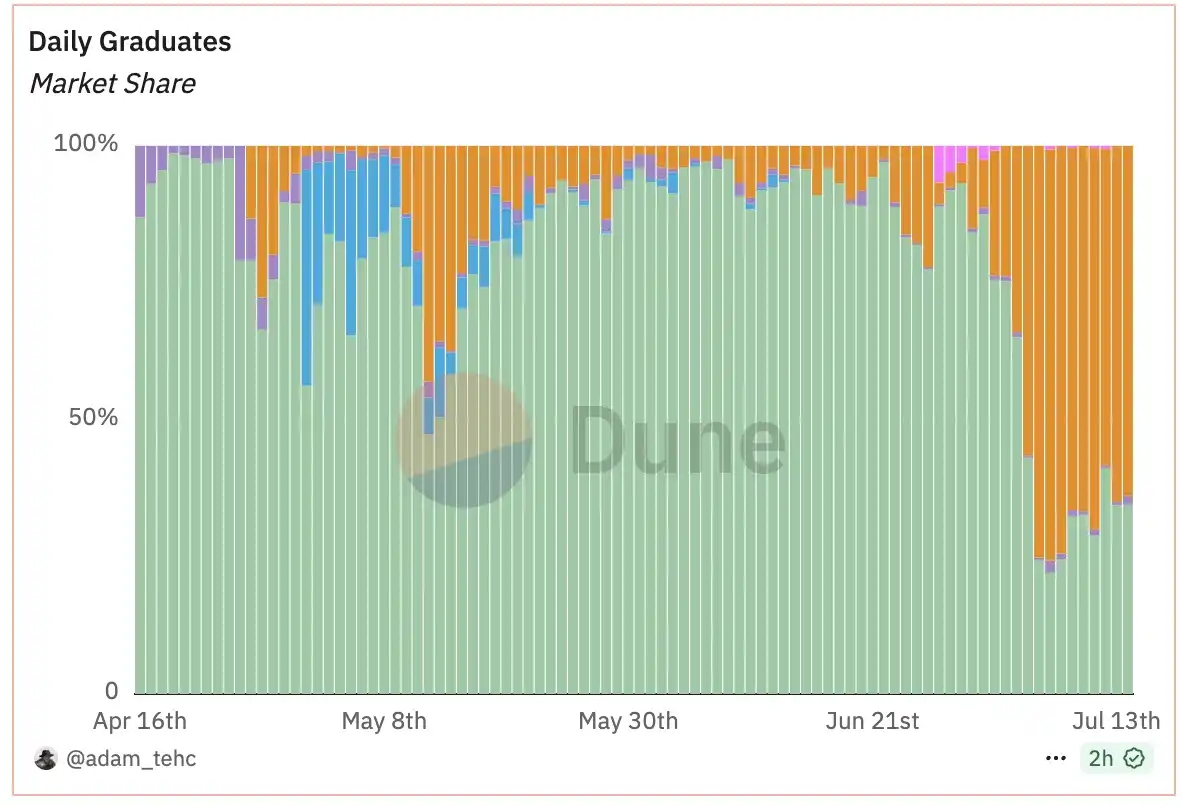
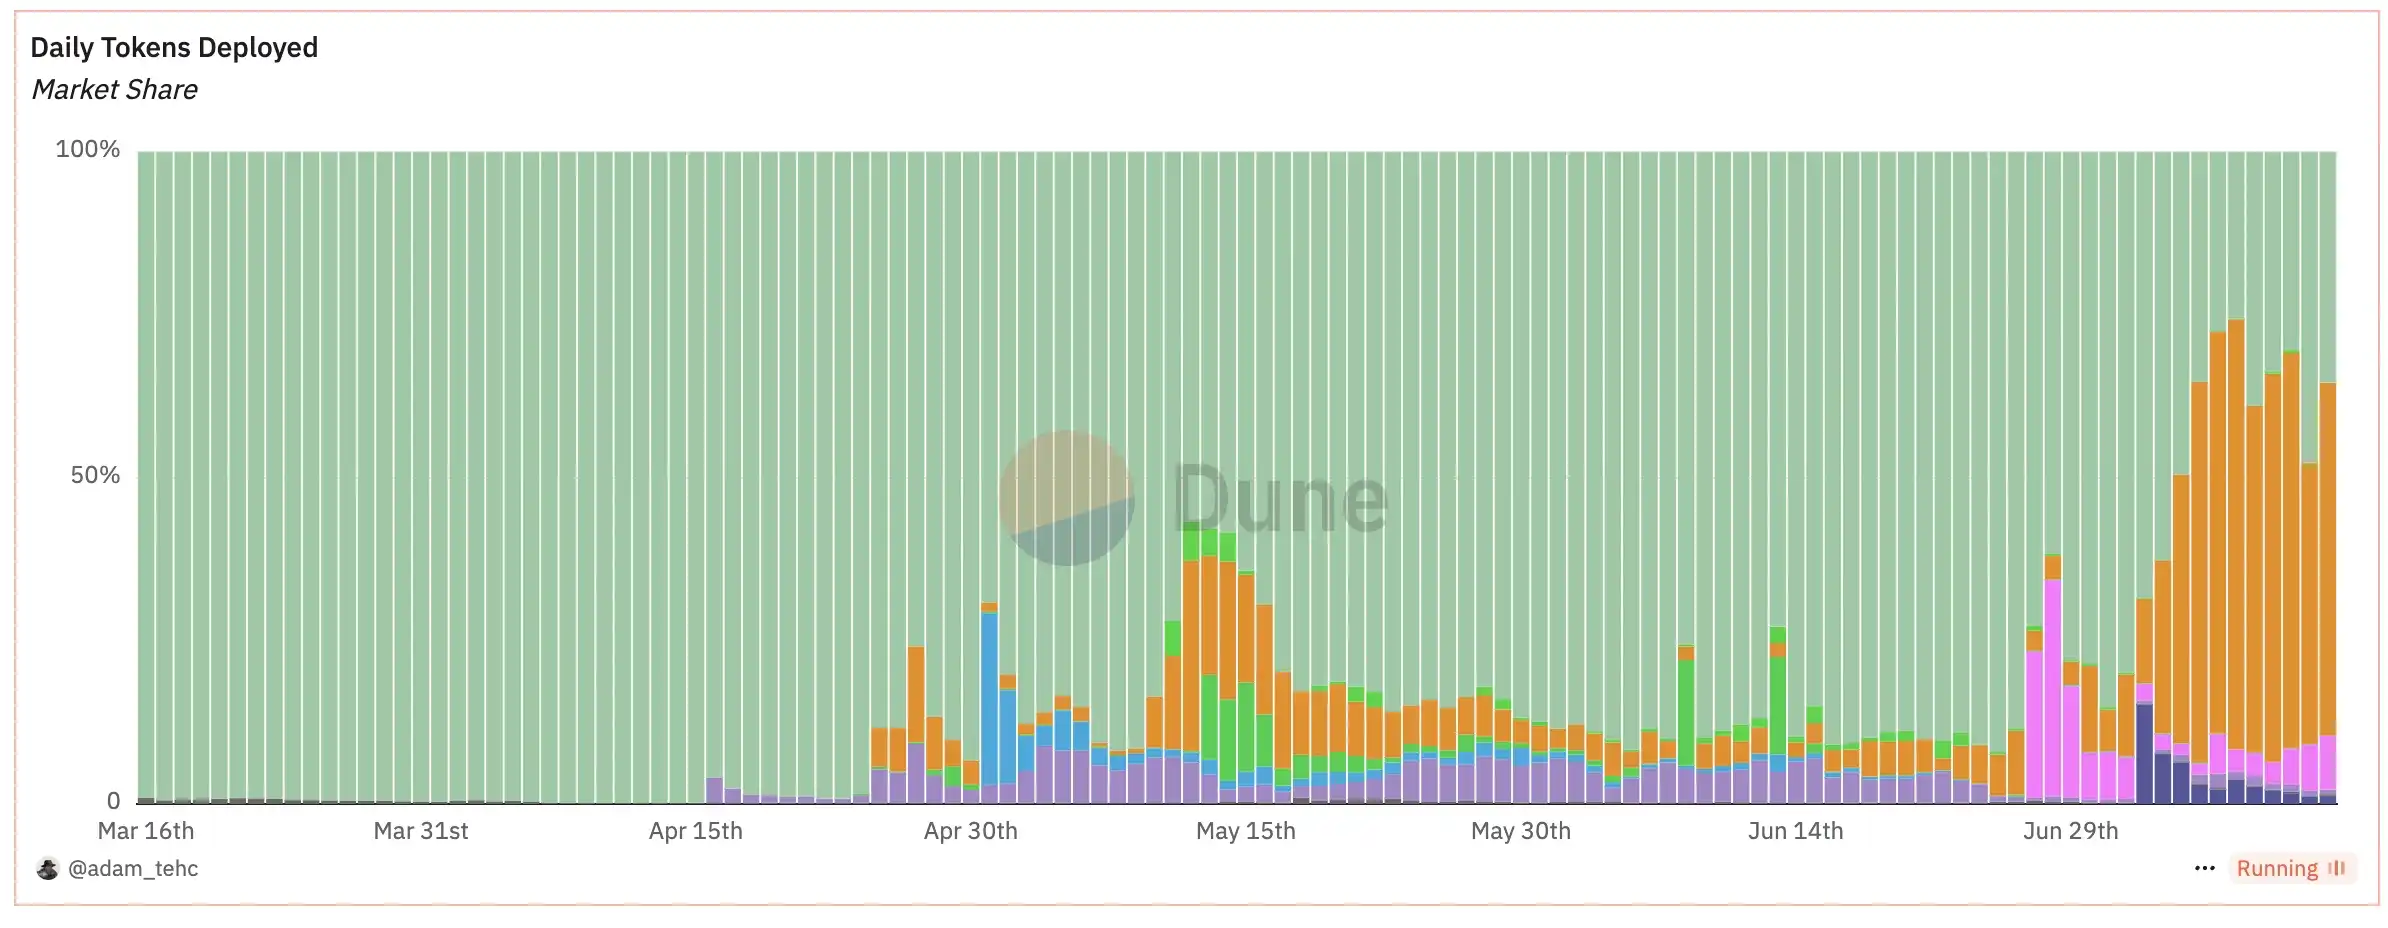
On-chain analyst Adam's data dashboard on Dune shows that recently Letsbonk.fun (orange section in the image below) has surpassed Pump.fun (green section in the image below) in both daily token deployments and daily token graduations, making it the most popular Meme token launch platform in the current market.
With Letsbonk.fun's strong rise, more and more people have started to explore potential wealth secrets on this platform. However, many have overlooked another major winner after Letsbonk.fun's data surge—Raydium.
Why is Letsbonk.fun's rise beneficial for Raydium? The story begins with the feud between Pump.fun and Raydium.
Pump.fun's Betrayal, Raydium's Counterattack
In a nutshell, in Pump.fun's early design, token issuance went through two stages: "internal pool" and "external pool." After token issuance, it would first enter the "internal pool" trading phase, relying on Pump.fun's own Bonding Curve for matching. Once the trading volume reached $69,000, it would enter the "external pool" trading phase, where liquidity would migrate to Raydium, pools would be created on this DEX, and trading would continue.
However, on March 21, Pump.fun announced the launch of its self-built AMM DEX product, PumpSwap. Since then, when Pump.fun's token enters the "external pool," liquidity will no longer transition to Raydium but instead to PumpSwap— this move directly cut off Pump.fun's flow path to Raydium, thereby reducing the latter's trading volume and fee revenue.
In response, Raydium announced on April 16 that it has officially launched the token issuance platform LaunchLab, allowing users to quickly issue tokens through the platform and automatically migrate to the Raydium AMM once the token liquidity reaches a certain scale (85 SOL). Evidently, this is Raydium's direct response to the surging Pump.fun.
So, what does this have to do with Letsbonk.fun?
Value Flow: Letsbonk.fun - LaunchLab - Raydium
While LaunchLab's token issuance functionality is similar to Pump.fun, its main feature lies not in the issuance process itself—LaunchLab's architecture supports third-party integration, allowing external teams and platforms to create and manage their own launch environments within the LaunchLab ecosystem. In other words, third parties can rely on LaunchLab's underlying technology and Raydium's liquidity pools to launch independent token sale frontends.
The protagonist of this article, Letsbonk.fun, is precisely a third-party launch platform developed by the BONK team based on the LaunchLab framework.
As a third-party platform developed based on LaunchLab, Letsbonk.fun adopts LaunchLab's fee mechanism. For all Meme tokens issued through Letsbonk.fun, LaunchLab will charge a 1% joint curve issuance fee, with 25% of it going directly to RAY buyback; furthermore, after the token breaks out of the "seed" round, Raydium will also charge based on the liquidity pool fee rules and allocate a portion of the fee to RAY buyback.
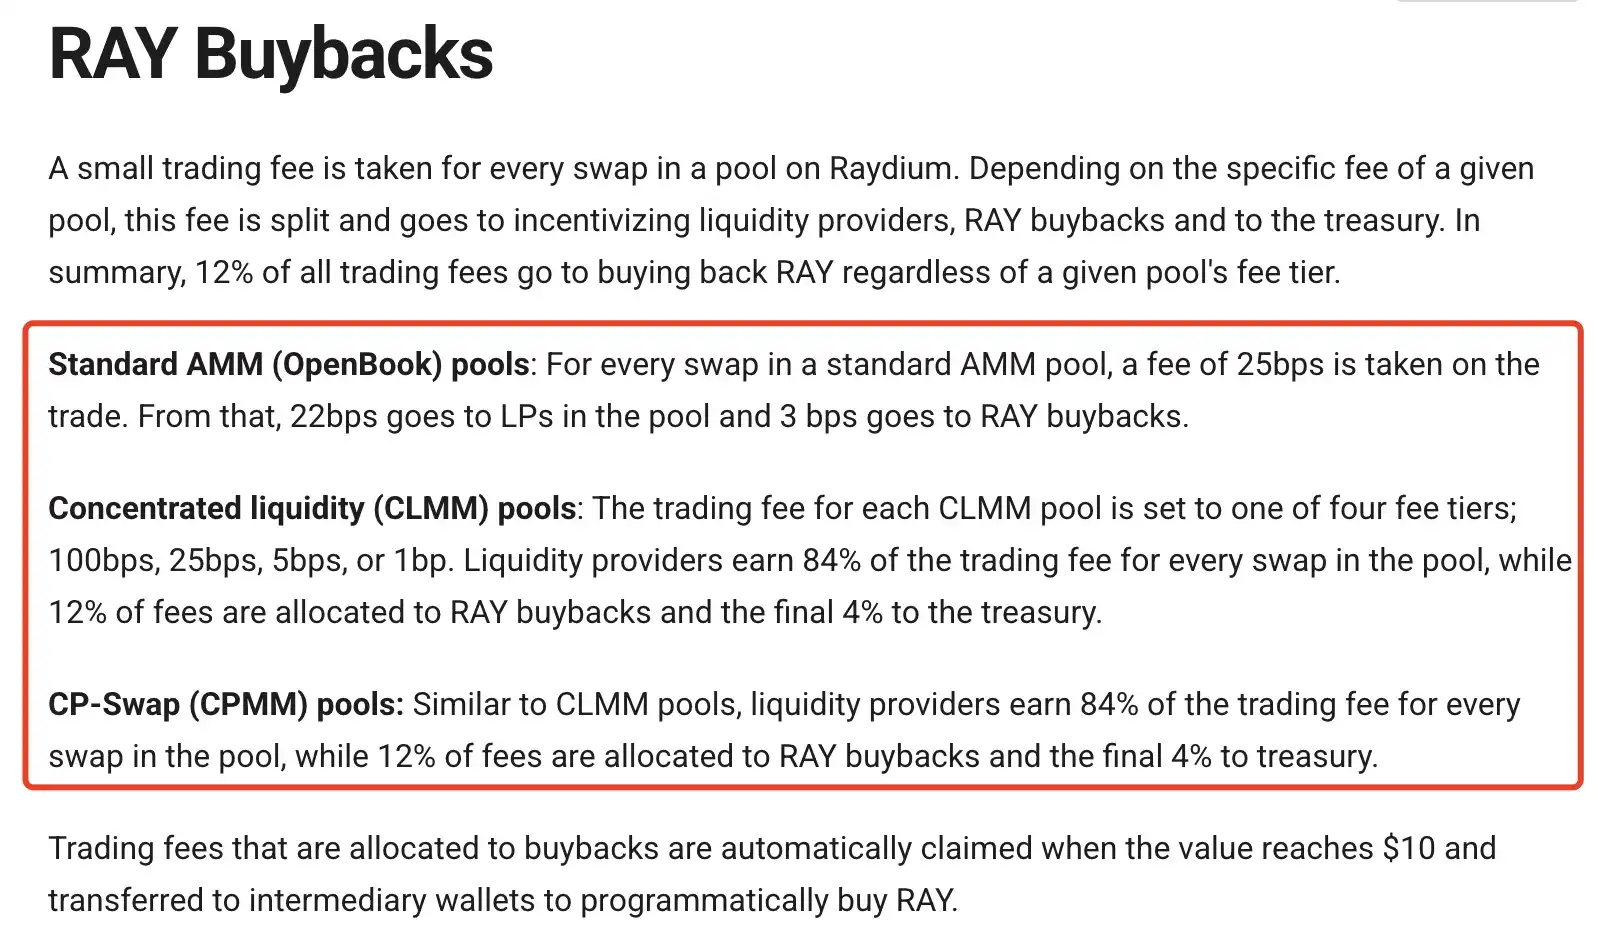
Odaily: Raydium's fee buyback ratio for different types of liquidity pools.
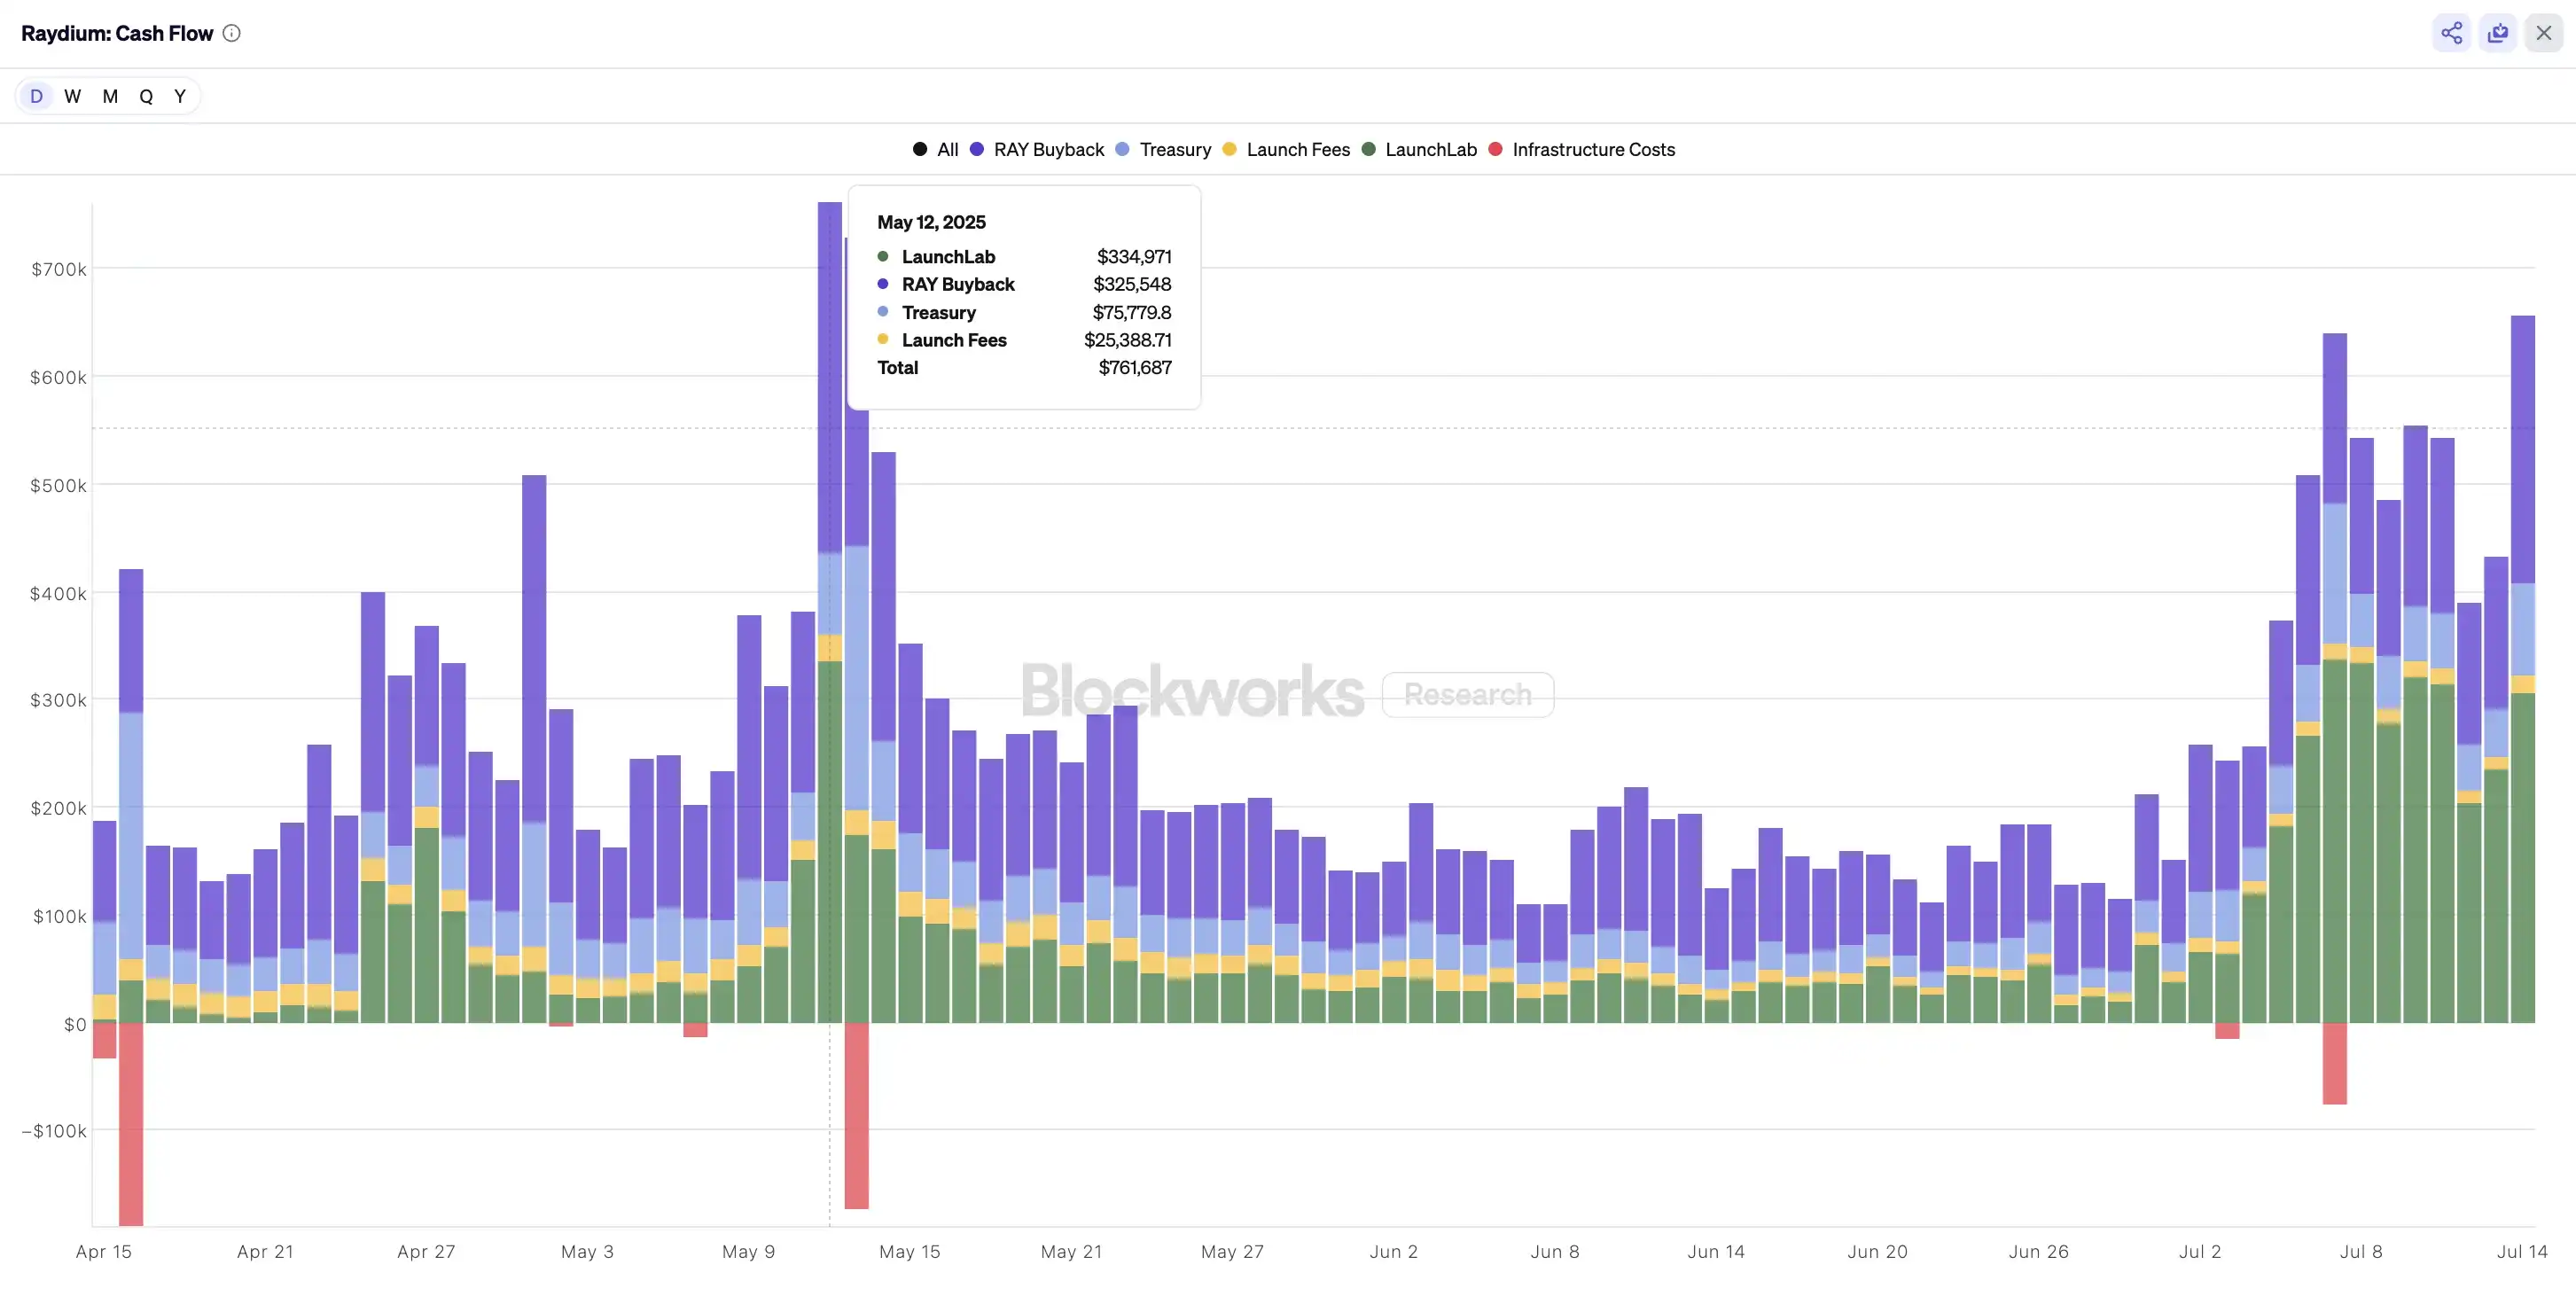
Blockworks data shows that since LaunchLab went live on April 16, Raydium's protocol revenue and RAY buyback volume have both seen significant growth, with their growth trajectory highly overlapping with the data fluctuations of LaunchLab-related platforms— on May 13, LaunchLab-related platforms surpassed Pump.fun in token graduation count for the first time, with Raydium hitting a recent buyback peak of $325,000 that day; additionally, with the recent surge of Letsbonk.fun, Raydium's protocol revenue and RAY buyback volume have once again seen a significant increase.
Of particular note is that previously, Raydium's protocol revenue mainly came from the exchange fees of the liquidity pools (purple part in the diagram below), but recently, LaunchLab's issuance fees revenue (yellow part in the diagram below) has gradually surpassed it, becoming Raydium's new main source of revenue, and 25% of these fees will be directly used for RAY buyback.
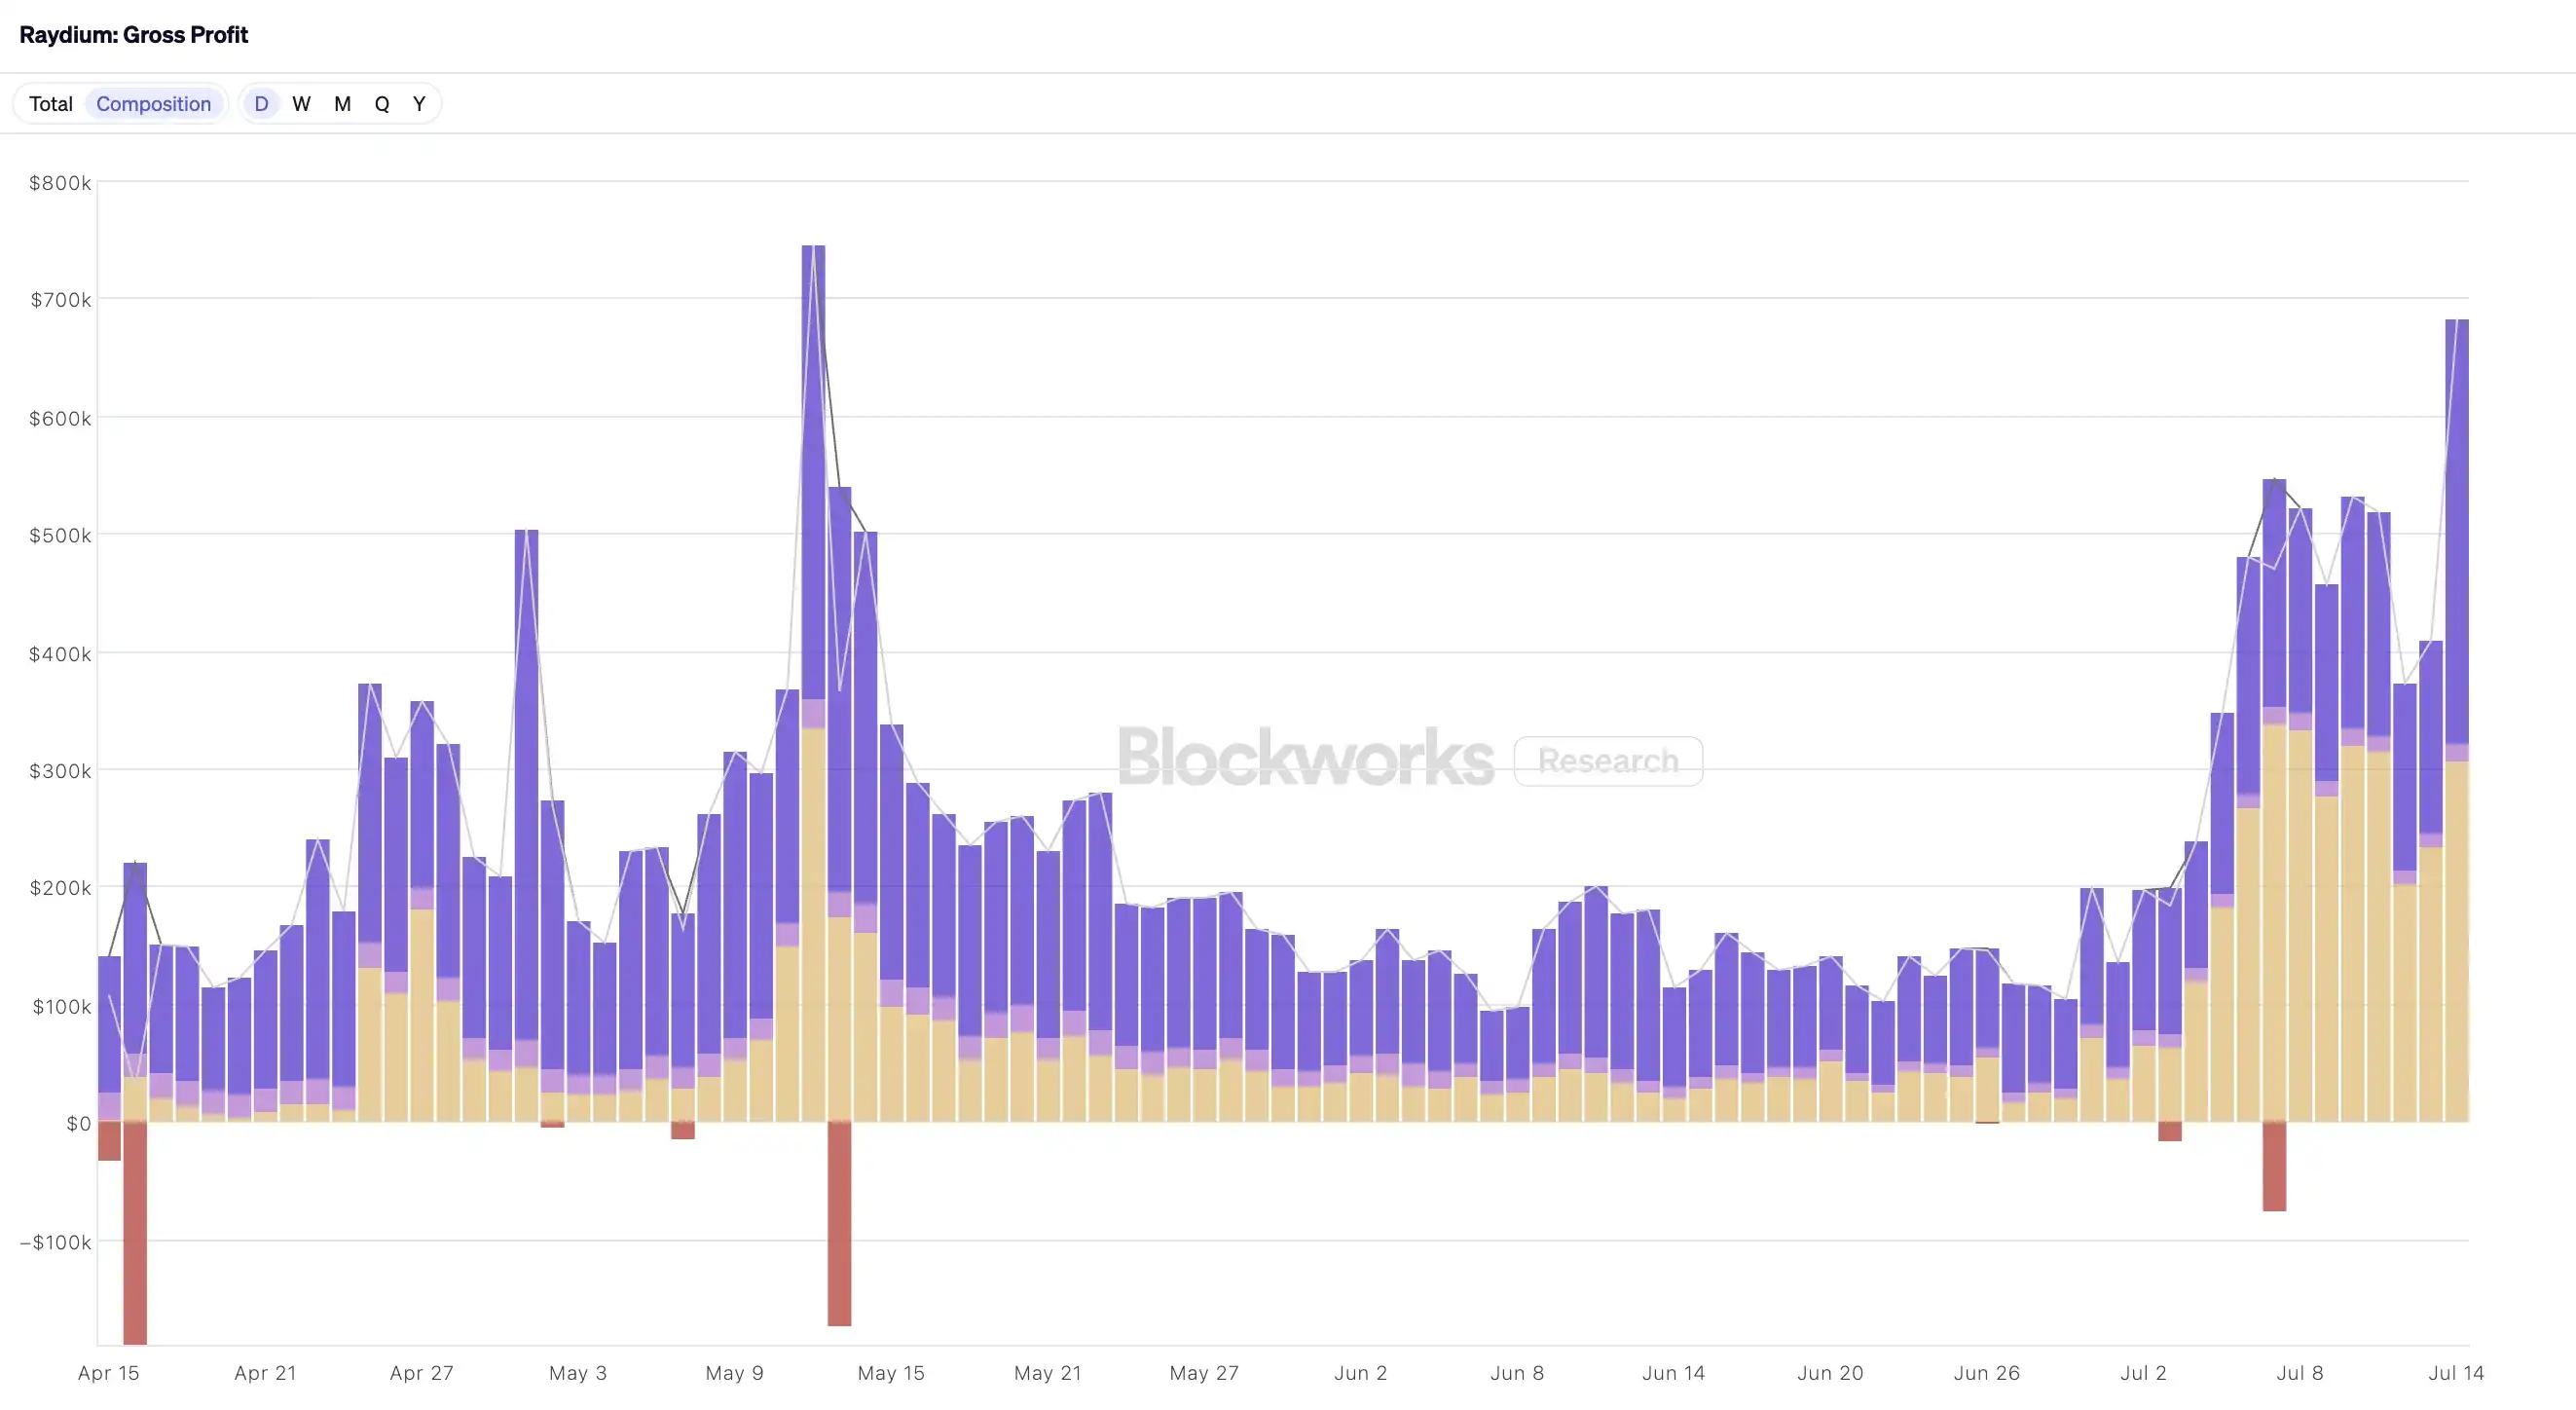
Based on yesterday's $249,000 buyback data, Raydium will be able to allocate approximately $90.88 million annually for RAY buyback, while the current RAY's circulating market cap is about $749 million, meaning that 12% of RAY's market cap will be repurchased annually, forming significant ongoing buying pressure.
Beyond Meme: Stock Tokenization
In addition to the continuously growing LaunchLab fee revenue, the equally hot trend of stock tokenization is also expected to boost Raydium's protocol revenue.
Previously, Kraken's stock tokenization platform xStocks officially launched and issued a series of popular US stock tokenized certificates on Solana, with most of these stock tokens already deployed in Raydium liquidity pools. Although the current trading volume is still limited and the fee contribution is not significant, considering the market trend of stock tokenization, this sector also has strong revenue growth expectations.
Looking ahead, if Letsbonk.fun can continue to maintain its current market share (even without considering the growth of LaunchLab and other third-party platforms), Raydium is poised to maintain its current protocol revenue level and buyback intensity, coupled with the potential growth in stock trading, this data is expected to achieve further breakthroughs.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles