



In 2018, why did Web2 investor Ron Conway bet on Circle and its stablecoin unicorn?
Original Article Title: "Conversation with Circle Investor Lei Ming: Continuously Achieving High Returns Behind Projects, Striving to Capture the Beta of the Era"
Original Article Author: Stone Jin
On the evening of June 5, 2025, Beijing time, Circle Internet Group (hereinafter referred to as "Circle") officially listed on the New York Stock Exchange with the stock code "CRCL," becoming the "world's first stablecoin stock." Two trading days later, Circle's stock price had risen by 247.42% from the offering price, with a market value of about $24 billion. In fact, during this IPO issuance, Circle had successively increased the number of shares issued and the offering price, raising a total of $1.1 billion and receiving over 25 times oversubscription.
Behind the most talked-about large IPO in 2025 to date, there are several Chinese-background investors. Among them, Lei Ming, a former investor at Huaxing New Economy Fund, invested in Circle in 2018. Along with Circle's listing, these early investors also reaped high returns on their investments. Lei Ming stated that his two core investment judgments of Circle were: first, blockchain technology will create significant commercial and social value in the future; second, investment is about investing in essence, and the essence of finance is licensing capability, which Circle happened to be the most licensed at the time.
Furthermore, Lei Ming pointed out that blockchain was a significant Beta of the era in 2017-2018. To achieve good fund performance, one must seize the biggest Beta of the investment period. In addition to Circle, Lei Ming also seized opportunities in the era at the time, including NIO in the new energy vehicle sector, as well as popular choices among the post-95s such as Dewu and Bubble Mart, maintaining a very high investment success rate. Of course, the largest Beta of today's era is undoubtedly AI, robotics, and globalization, which has almost become a consensus. In mid-2023, Lei Ming, as a founding partner, established Winsight Ventures and began the formation of an ecological fund.
Currently, Winsight Ventures has invested in companies such as "Magic Atom" in embodied intelligence, "Surge Future" in pool robots, "Thousand Secrets Technology" in embodied large models, "Atomic Reshape" in consumer-grade 3D printers, and "Tantou Technology" in smart short-distance travel.
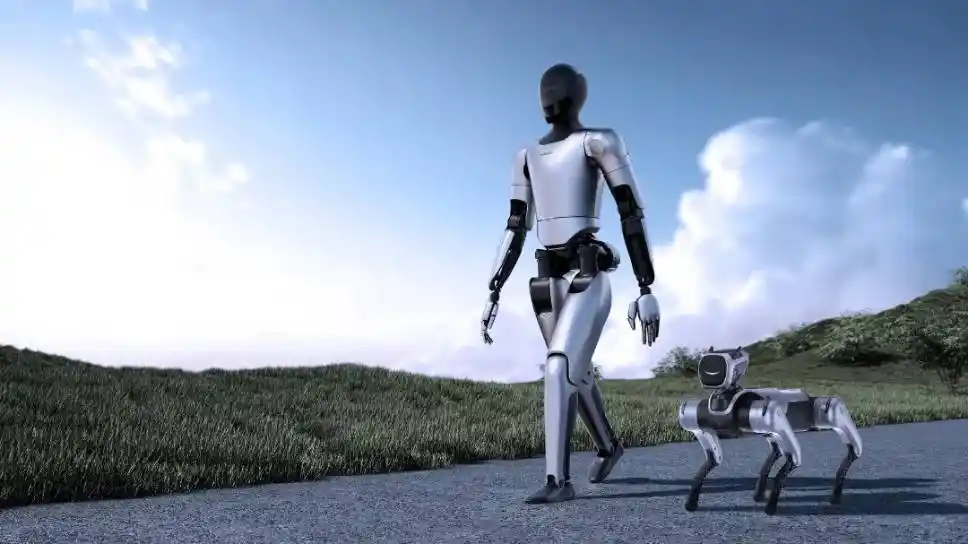
Magic Atom's humanoid and quadruped robots
Lei Ming emphasized that the core competitiveness of the Quest Ecology Fund comes from empowering the Quest incubation ecosystem: on the one hand, Quest can use optimal valuation to prioritize investment in projects incubated in the Quest ecosystem, ensuring the stability and high growth potential of the projects; on the other hand, leveraging the industry insights of the Quest ecosystem, the fund can also expand its investment to high-quality external projects to achieve ecosystem synergy. According to Lei Ming, he and his team are now also raising a USD fund and are consistently emphasizing the "China to Global" concept to USD LPs, meaning leveraging China's comprehensive capabilities in various fields and believing that Chinese people have the strength to "achieve success" globally.
It is worth adding here that in August 2024, Quest Ventures announced the establishment of the industrial venture capital fund and completed the first close of the RMB fund. It is reported that within six months, the fund was oversubscribed, achieving an MOIC of 2.5 times, with 100% of the projects in the fund achieving a valuation of at least double.
Lei Ming said, "Our next important direction is to invest in globalization—viewing it from the perspective of a Chinese team, we are reverse recruiting some overseas teams in countries such as the United States and the United Kingdom to gradually enhance our capabilities in this area and truly achieve 'China to Global.'" On the occasion of Circle's official listing on the NYSE, Lei Ming shared his core logic for investing in Circle seven years ago and some reflections and prospects after founding Quest Ventures with "IPO Early Access."
Below are selected excerpts from the conversation between Lei Ming and "IPO Early Access":
Investment is about investing in the "essence"
Q: You invested in Circle seven years ago. What was the judgment logic at that time?
Lei Ming: In 2018, I had just joined Huaxing, and blockchain was one of the tracks I covered at the time. I personally recognized the underlying logic of blockchain and believed that blockchain technology could create significant business and social value in the future. But frankly, at that time, blockchain was still in its early stages of development, many laws and regulations were unclear, so we tried to choose projects that we believed were compliant and met risk control requirements as much as possible for investment, considering the eventual listing exit.
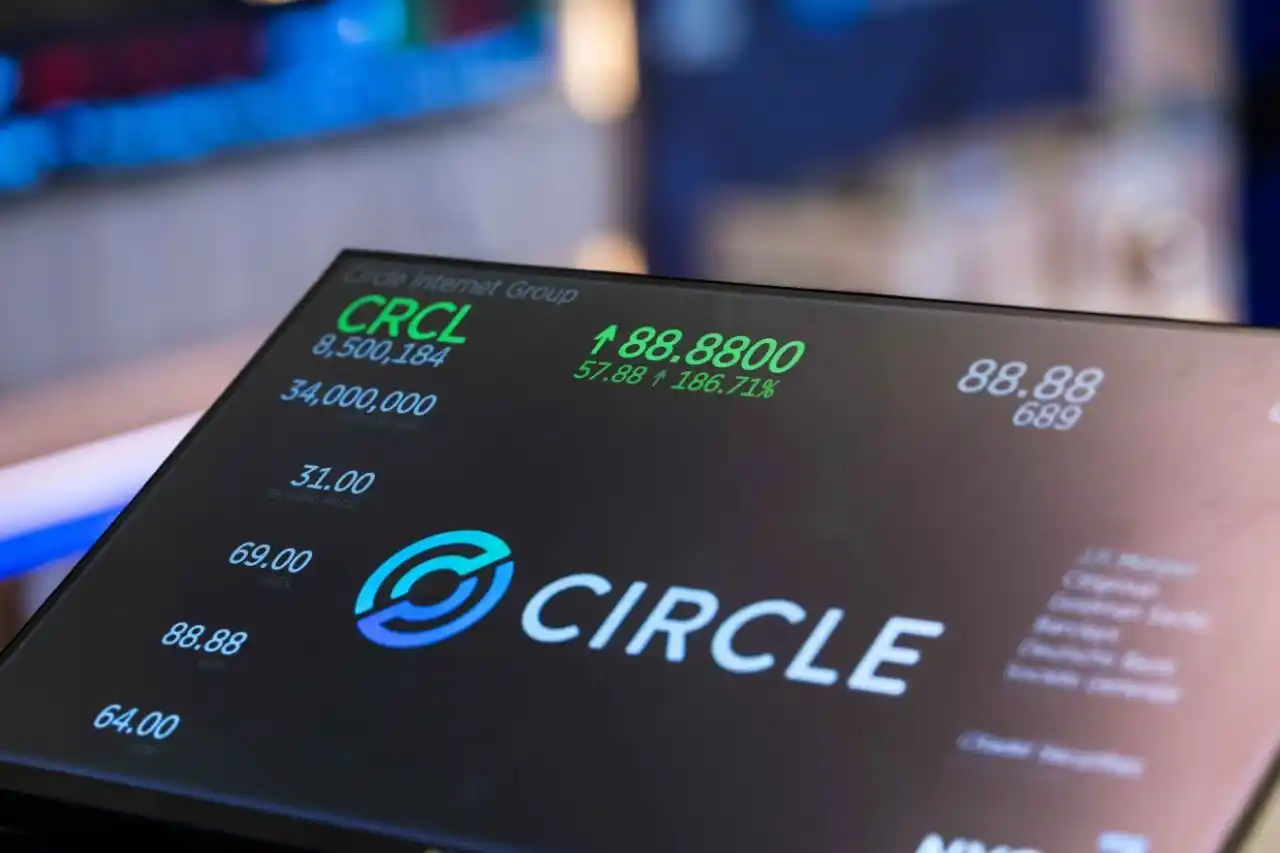
Q: Circle reaching a market value of over $200 billion today must be somewhat unexpected.
Lei Ming: Frankly, there is a certain element of luck—back then, Circle's main business was not yet stablecoins; they had just started this business. In addition, when Circle conducted this IPO, it coincidentally aligned with the United States and Hong Kong sequentially introducing legislation regarding stablecoins, directly leading to the success of Circle's IPO. Of course, its future potential is also very great, which was not present seven years ago.
However, at that time, we had a basic judgment, which was also our consensus—fundamentally, finance is still a licensing business. When a new thing emerges, regulation may not have caught up yet, and during the era of rapid growth, anyone could potentially make some achievements. But in the long run, the financial industry will definitely become more compliant. It will definitely need to operate in compliance with regulations in order to survive in the long term. Therefore, the ability to obtain licenses becomes particularly crucial. This was something we were very convinced of at that time, and Circle was the one with the most comprehensive licenses.
Q: Circle's project is relatively niche, at least to traditional investment institutions. From this project, have you summarized any experiences that can be reused in subsequent investment processes?
Lei Ming: I roughly summarized it into four points:
First, when making investments, we should try to embrace the opportunities brought by new technologies. Investing in blockchain within traditional financial institutions, I should consider myself part of the first wave to "try something new." So, when these disruptive technologies emerge, we need to keep a long-term focus, follow them for an extended period, continuously learn new things, and explore new directions.
Second, even when seeing something new in an industry, we still need to return to the underlying logic. Ultimately, the core of investment is to invest in the essence. As I just mentioned, the success of the Circle case was still due to us seeing through and seizing the essence of the financial industry, which is "licensing."
Third, adopt a global perspective. Seven years ago, not many peers were promoting "globalization," but at that time when I talked with the Circle founders, I felt that they had a global mindset. For a company to truly stand out, it must embrace globalization in various aspects, including globalizing funds, markets, supply chains, talent, etc. I believe that a strong belief in globalization was also a major factor in the success of this case.
Lastly, invest in founders who have faith and conviction. When a new thing appears, there will definitely be many changes, and the market will be quite volatile. At this point, you need to invest in founders within this space who are very certain and have strong faith in what they are doing. If these founders lack faith and are frequently changing, the probability of building an excellent company is low.
Seize Major Opportunities of the Era as Much as Possible
Q: Earlier, you mentioned that "fund performance fundamentally depends on whether you can capture the era's biggest beta." You invested in NIO at that time, which can be considered one of the biggest era opportunities, but can Circle also be considered? How do you find projects beyond these major era opportunities?
Lei Ming: I don't think so. I believe that blockchain can also be considered a significant beta of 2017-2018. Blockchain is a huge track, and to this day, many applications have not yet emerged. In fact, blockchain technology has the potential to be applied in many, many areas.
Q: Did you also consider the items invested in 2020 as era beta?
Lei Ming: The biggest beta of the items lies in: at that time, we conducted a survey on the post-95s population and judged that the era opportunity was an investment opportunity targeted at the post-95s population. My logic at the time was, if you want to seize the opportunity of a major era change, simply put, it boils down to "people, products, and market," among which the "people" variable is definitely the largest. So at that time, we conducted an in-depth study on the "Z Generation," and I took the team to 8 cities, covering different cities from first-tier to fifth-tier. After studying this generation, we screened out a series of investment themes based on the post-95s generation. Therefore, when the valuation was relatively low, we invested in items, and today, the volume and influence of items are already very significant.
At the time of investing in items, the mobile internet wave had gradually receded, and after 2018, there were very few enterprises like items. Overall, I think we still need to try to find those relatively significant era beta opportunities, which may not necessarily be the largest, but there are still some significant investment themes, such as blockchain and the post-95s generation.
Q: The current era opportunities are AI, robotics, and globalization.
Lei Ming: In fact, this is the core of our venture creation today. The next biggest era opportunities revolve around AI, robotics, and globalization. In other words, truly valuable projects, projects that can make investors money, are actually those that significantly increase social productivity and production efficiency through technological innovation. For example, AI and robotics are driving the improvement of human productivity, making it the biggest era opportunity.
Vision Seeker Ecosystem Fund
Pursuing "China to Global"
Q: Today, almost all institutions are emphasizing their investment in AI, robotics, and globalization. As a newly established institution just over 2 years old, how do you ensure that you can establish yourself in the market, and even stay ahead?
Lei Ming: Our positioning is the Vision Seeker Ecosystem Fund, so a significant advantage lies in the deep industrial accumulation and a well-established innovation incubation system of Vision Seeker—over the years, Vision Seeker has accumulated systematic capabilities and entrepreneurial methodologies through successfully building mature categories. We can leverage this system and methodology to globally seek opportunities across industries and regions, especially those related to robotics, and then proceed with the relevant incubation. Here, I want to emphasize that I have fully realized that the organizational management model and methodology established by Vision Seeker are ahead of the current era, perhaps the external perception is not so strong, and it may take some time to gradually appreciate. We will open up these systematic capabilities to our incubated enterprises.
In fact, we have recently incubated many projects—on one hand, we can invest with a low valuation in projects incubated by Vision Seeker Ecology; on the other hand, these projects, compared to external projects, currently have a much higher success rate in our view. Several projects have a growth curve of reaching 3 to 5 billion in revenue in the first year and 10 billion in revenue in the second year, and all projects strive to make product performance globally leading from the beginning, achieving profitability in the first year without burning money, which is what we internally emphasize as "global premiumization."
So, the stability of these projects is very high, and they can achieve very rapid growth relying on Vision Seeker's established global channels, making their growth prospects quite remarkable.
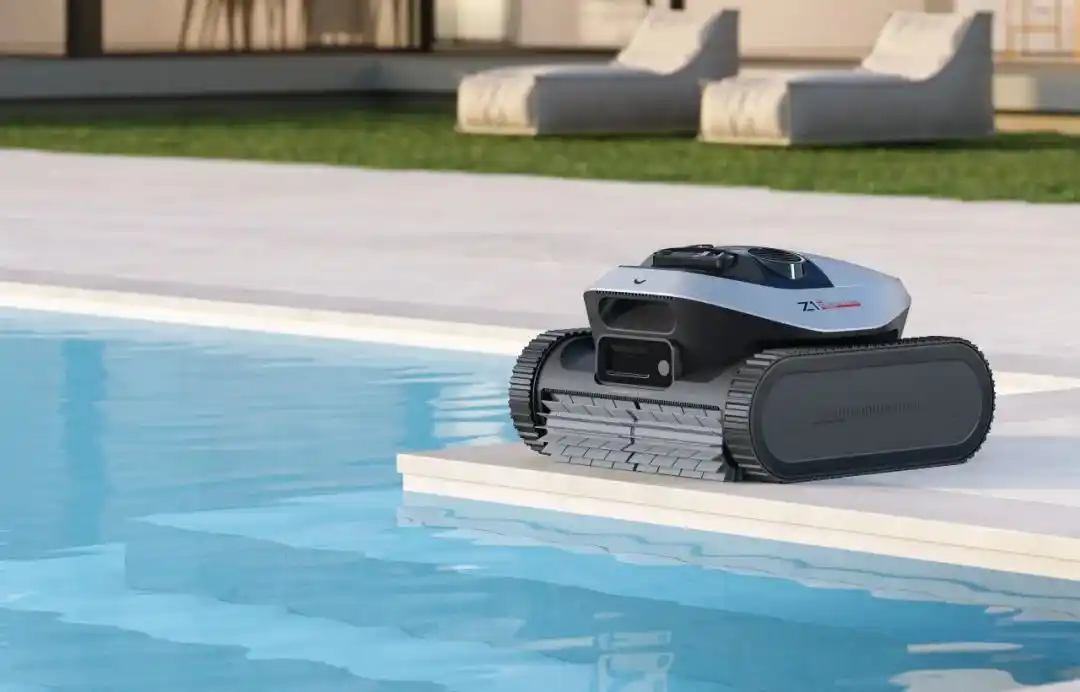
A wireless swimming pool robot product developed by Surgetide Future
With the perspective of the entire Vision Seeker ecosystem, we can also extend our investment beyond Vision Seeker incubated projects. For example, we can invest in some upstream projects, and at this point, we can consult with Vision Seeker's business team. For example, "Will they use these upstream technological platforms?" is a more precise and intuitive judgment dimension.
Furthermore, we can also leverage ZHUIYUE's global perspective to invest in projects worldwide. We have already reserved some projects in Silicon Valley, the UK, and so on. On one hand, our fund has teams overseas that can actively seek out projects. On the other hand, we can also be recommended projects by ZHUIYUE's sales team.
We are now also raising a USD fund, but fundraising today is different from before. The previous fundraising logic was that USD investors were very bullish on the Chinese economy and basically went all in on China, handing the money directly to top Chinese GPs to invest. However, the external environment today may have changed somewhat. Therefore, we have been emphasizing the concept of "China to Global" to USD LPs, which means leveraging various capabilities in China, including supply chain capabilities, engineering R&D capabilities, operational capabilities, etc., to achieve a global presence.
Fund Returns and Ecosystem Synergy Can Be Achieved Together
Q: Positioning a fund as an ecosystem fund, how do you prioritize financial returns and ecosystem synergy?
Lei Ming: From the fund's perspective, we definitely prioritize financial returns. Ecosystem synergy is actually a natural thing. For example, during the RMB fund raising process at ZHUIYUE, we have a collaborative relationship with our business team—because the best location for each project may vary, the business team comprehensively considers factors such as supply chain support, labor costs, transportation convenience, etc., to select a few locations most suitable for implementation. Then we proceed to discuss the establishment of a fund in these selected locations with businesses that are suitable for landing.
If it were us raising the fund first and then forcing the business team to cooperate with landing and reinvestment, this model would not be sustainable. Fundamentally, both sides have a mutually beneficial relationship, and we also help companies secure favorable investment policies. Overall, we decide on which incubation projects the fund will invest in, at what stage, and at what valuation. The key point here is to maximize returns while minimizing risks and ensuring that LPs make money. At the same time, the business team can achieve some impressive results, so everything just falls into place. Fund returns and ecosystem synergy are not contradictory and can be achieved together.
Q: In the past two years, you have achieved a good return on investment. In which aspects do you think ZHUIYUE has done well? What are some areas that can be iteratively improved in the future?
Thunderous Applause: Over the past 2 years, our relatively good performance is largely attributed to the exploratory incubation model, entrepreneurial methodology, and a reusable organizational management incentive system. The success rate of these incubation projects is naturally higher, which is evident. Building on this foundation, we have also invested in some promising companies in the upstream industry, whether they are components or fundamental algorithms. An important direction for our future self-iteration is to invest in globalization — we stand from the perspective of a Chinese team, and actively recruit overseas teams in countries such as the United States and the United Kingdom, gradually enhancing this aspect of capability, truly achieving "China to Global."
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia







