



Let Gamers Proof: How KGeN is Redefining User Onboarding
1. Introduction
Today, the scale of the gaming industry has surpassed that of movies and music, with overall growth still ongoing. However, in recent years, the industry has been facing serious challenges. After experiencing record growth during the pandemic, in 2023-2024, the industry faced waves of layoffs and consolidation, skyrocketing development costs, while investments saw a significant reduction.
Furthermore, game publishing and distribution have become increasingly difficult. With AI-generated content flooding the market, platform saturation, and players favoring established IP, new projects struggle to stand out, making acquiring highly engaged users an unprecedented challenge.
Nevertheless, the industry still holds tremendous opportunities. Gen Z and Gen Alpha, as digital natives, have grown up in virtual worlds like "Roblox" and "Minecraft," and their spending power will continue to drive market expansion.
Simultaneously, the long-overlooked "Global South" markets are experiencing explosive growth. With the proliferation of smartphones, improvements in internet infrastructure, and rising incomes, these regions will become key incremental markets for the gaming industry in the next decade.
The first part of this report will explore the latest challenges in game publishing and analyze the high-growth opportunities in the "Global South." The latter part will focus on KGeN—a blockchain-based gaming network aimed at reshaping the incentive mechanism between publishers and players. We will also assess the feasibility of Web3 task platforms and analyze the structural changes in the distribution of value in the gaming industry.
2. Challenges in Publishing
It is well known that one of the biggest challenges the current gaming industry faces is publishing. Changes in consumer habits, regulatory policy adjustments, lowering market entry barriers, and the ongoing saturation of game content have made it more challenging than ever to successfully launch a game to millions of users.
Players tend to spend most of their time playing games they are familiar with or series they follow, making it difficult for new titles to break through. In 2023, the top ten games ranked by average monthly active users (MAU) all had release dates of over seven years, and players still spent 60% of their gaming time on those annual series releases.
In 2024, despite Steam seeing a record 19,000 new game releases, those games released that year accounted for only 15% of total player gaming time.
The mobile gaming market once had a more mature publishing model. The rise of early mobile ad networks like Facebook and Google, combined with the widespread adoption of smartphones, helped many games achieve over a billion users and generate billions of dollars in annual revenue. However, in 2021, Apple and Google made significant privacy policy changes that directly affected how publishers could reach their target users.
While these changes have not ended mobile advertising, they have indeed had a significant impact on User Acquisition (UA) strategies and the business models of mobile games. Many publishers have found new ways to scale on mobile, but the market is increasingly favoring well-funded companies, putting small teams under greater competitive pressure.
Looking ahead, the industry environment seems challenging to improve. While AI can make UA campaign management more efficient, it also lowers the barrier to market entry, resulting in a significant increase in content volume. UGC platforms like Roblox and Fortnite Creative have become common proving grounds for indie developers, yet they themselves face challenges in content curation and promotion, with the proliferation of AI only further exacerbating these issues.
This brings us to the Web3 gaming market, where development teams must overcome a series of additional hurdles. In addition to the aforementioned challenges, Web3 games must adhere to stricter policies on mobile, Steam (the largest PC game distribution platform), and console platforms. Furthermore, Web3 games are even directly prohibited in key markets like South Korea and China.
Of note, the distribution landscape for Web3 games on consoles is gradually changing. The recent release of "Off The Grid" has set a precedent for Web3 games entering this once-"off-limits" market, and we look forward to more games following this path in the future.
Moreover, the Web3 gaming market remains a niche subsector of the overall gaming industry, with approximately 6 to 7 million active wallet addresses engaging with over 3000 on-chain gaming protocols. However, it is important to note that this data does not rule out the significant presence of bot accounts in the Web3 space, and roughly only about 200 protocols truly have over 100 active on-chain accounts.
For such a relatively small-scale market (global gamers totaling over 3 billion), its challenges have been further exacerbated over the past two years by the rapid growth of the emerging Web3 gaming ecosystem. Data from Game7 shows that although the average number of new Web3 games has declined by 45% since 2021, the average number of new networks has grown by 187% over the same period. In 2024 alone, there were 104 new networks/ecosystems announced, while only 263 new Web3 games were released.
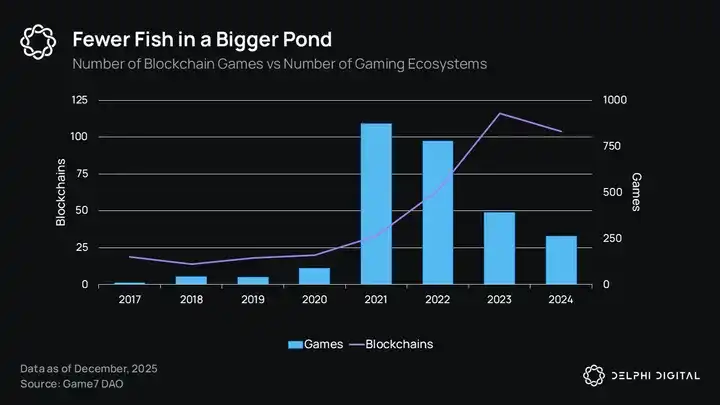
The issue lies in the fact that most of these emerging networks have failed to attract new players successfully. All of these issues have ultimately led to a phenomenon we have detailed in multiple reports—the battle for player liquidity. As the competition in the entire gaming market intensifies, Web3 projects are competing around the same limited wallet users, with hardly any effective means to break this limitation and achieve scalable growth.
Amidst significant challenges, a group of Web3 companies is exploring a new User Acquisition (UA) model based on blockchain. Innovative incentive mechanisms and on-chain reputation systems are becoming potential avenues for these companies to gain a competitive edge through Web3 integration.
Many Web3 companies have demonstrated significant Product-Market Fit (PMF) in emerging markets. Compared to the increasingly saturated T1 markets dominated by Web2 giants, enterprises that can leverage a global payment network enabled by blockchain to truly tap into emerging markets may have enormous growth opportunities.
One of the regions where growth rates have consistently been above average and where a high level of recognition for blockchain applications has been demonstrated is the Global South.
3. Global South
The Global South is a term used to describe countries and regions with relatively lower levels of economic development, usually located south of industrialized nations. Due to rapid improvements in internet infrastructure, high smartphone penetration rates, and growing disposable incomes, this vast region is often seen as an underdeveloped yet highly potential gaming market.
Key characteristics of the gaming market in the Global South include: a massive player base, heavy reliance on mobile devices for gaming, and overall lower willingness to pay. Historically, these markets have been used by game publishers for soft launch user acquisition testing and front-end data optimization.
However, the youth in these regions are the first generation to grow up with smartphones, and they have a strong preference for gaming content (including games, video content, and esports). As this generation ages and benefits from economic development and increased incomes, many believe they will become the next generation of paying players, propelling the gaming industry to new heights.
Below are some key market characteristics of certain Global South regions to demonstrate their significance in the future gaming industry.
India
Despite a relatively slow start, India is rapidly emerging as the largest gaming market in the Global South. In 2017, the country had only 44.9 million gamers, but that number has now grown to approximately 466 million, expected to surpass 640 million by 2027.
Market revenue is expected to grow by 13.6% in 2024 (reaching $9.43 billion) and surpass $10 billion in 2025, projected to reach $14 billion by 2028, with a 5-year Compound Annual Growth Rate (CAGR) of 11.1%. This growth is primarily driven by the improvement in user in-app purchase habits and the growth in average revenue per user (ARPU) due to the increasing national disposable income.
The Indian market has a strong preference for mobile gaming, largely due to being one of the fastest-growing 5G nations globally and having a widespread digital payment infrastructure—the Unified Payments Interface (UPI). UPI transaction volumes have grown from 10.78 billion in 2019 to 83.75 billion in 2023, showcasing the rapid rise of the digital economy. Additionally, internet penetration has significantly increased from 14% in 2015 to the current 52%, although lower than other major global southern gaming markets, indicating significant growth potential in the future.
These technological advancements are supported by robust macroeconomic fundamentals, including a 7-9% average annual economic growth rate over the past three years and rising income levels of the young and expanding middle class.
India's gaming preferences exhibit a unique pattern compared to other major markets:
· Mobile games dominate, contributing 77.9% of total revenue;
· PC games and console games only account for 14.5% and 7.7%, respectively.
In terms of revenue composition, the revenue distribution of different game types is as follows:
· Real Money Gaming (RMG) is the largest subsegment market, with an annual revenue of $2 billion;
· Casual and Hyper-Casual games follow closely, with a total revenue of $700 million;
· The market size of other game categories is approximately $400 million.
Southeast Asia (SEA)
Southeast Asia (SEA), consisting of Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam, is one of the most mature gaming markets in the global south. According to Niko Partners data, the region's gaming revenue reached $5.1 billion in 2023, growing by 8.8% year-on-year, and is projected to reach $7.1 billion by 2028, with a 5-year compound annual growth rate (CAGR) of 6.7%. In 2023, Southeast Asia had 277 million gamers, expected to increase to 332 million by 2028, with a 5-year CAGR of 3.7%.
According to Sensor Tower's H1 2024 report:
· Indonesia had the highest mobile game downloads, reaching 2.4 billion (41% of the region's total downloads);
· Thailand had the highest in-app purchase (IAP) revenue, reaching $400 million, followed closely by Indonesia at $300 million.
While there are differences among the countries in this region, community and a culture of competition are common traits. Word-of-mouth is the primary source of information, and the best-performing games usually have social features.
Similar to most global South regions, the widespread adoption of smartphones and the development of broadband infrastructure are key drivers of market growth. Southeast Asia stands out in particular:
· By 2022, the smartphone penetration rate in all major countries exceeds 80%;
· Average penetration rates are expected to reach 90.1% by 2026.
Latin America (LATAM)
Latin America (LATAM) is another major market of interest, with a large population and a strong gaming culture, especially in the esports field. In 2022, the region is estimated to have 316 million gamers, with the majority of players concentrated in Brazil, which had 101 million players that year, generating $27 billion in game revenue.
The Brazilian market shows a strong preference for mobile games:
· 60% of players have played a mobile game at least once in the past six months;
· Smartphone penetration is expected to reach 83% by 2025, indicating significant growth potential in the mobile gaming market.
In terms of monetization, the Brazilian market exhibits a strong payment habit: 43% of players engage in in-game spending, with main motivations including unlocking exclusive content (39%), character customization (35%), and game progress (30%). This suggests that a mature market is moving beyond basic monetization models. These spending patterns indicate that the market is maturing, gradually evolving from fundamental monetization models to more complex game economies.
The Brazilian market is set to continue leading the growth of the Latin American gaming industry in the future, mainly due to: 140 universities nationwide offering over 4,000 game-related courses, 1,042 game studios throughout Brazil with a total revenue of approximately $251.6 million, the recent passage of a legal framework officially recognizing game development as a profession, and providing incentives such as tax breaks.
Africa
The African gaming market is at a crucial stage of development, with revenue expected to surpass $1 billion by 2024, showing steady growth from $863 million in 2022. The core driver of this market is mobile gaming, which holds nearly 90% market share, reflecting both the infrastructure reality and consumer preferences.
A domestic study shows that 92% of African gamers use their mobile phones to play games, while the adoption rates of computers (51%) and gaming consoles (31%) are relatively low. This mobile-first approach has been partially validated; however, the research sample size was only 2588, making it difficult to comprehensively represent the entire continent's market situation.
Main Challenges: High data costs (42%) are the biggest obstacle, followed by hardware prices (31%) and network connectivity issues (31%).
Payment systems are both a challenge and an opportunity: Although 63% of players engage in in-game purchases, payment methods vary by region. Kenya leads in mobile payments, with 67% of players using mobile wallets for game consumption. Credit cards (45%) and mobile payments (40%) are the most common payment methods across Africa.
Middle East and North Africa (MENA)
The MENA (Middle East and North Africa) region is the fastest-growing game market globally, with revenue projected to grow by 4.7% in 2023, reaching $7.1 billion, far exceeding the global market's 0.6% growth. High-speed growth is expected to continue in the future, with a projected Compound Annual Growth Rate (CAGR) of 9.4% from 2024 to 2030.
By 2027, the MENA-3 (Saudi Arabia, UAE, Egypt) core market revenue in this region is expected to reach $2.9 billion with a CAGR of 8.3%; market drivers include a high percentage of young population driving gaming market activity, significant internet penetration in Qatar and the UAE, and widespread adoption of new technologies.
The region's gaming landscape is dominated by three strong markets—Saudi Arabia, UAE, and Egypt—referred to as MENA-3. They have shown remarkable performance, growing by 7.8% year-on-year to $1.92 billion by 2023, and are predicted to reach $2.9 billion by 2028 with a five-year CAGR of 8.3%. Saudi Arabia leads the way, accounting for 60.6% of total game revenue and 30.3% of total gamers in the Middle East and North Africa, demonstrating the country's dominant position in the regional ecosystem.
4. What is KGeN
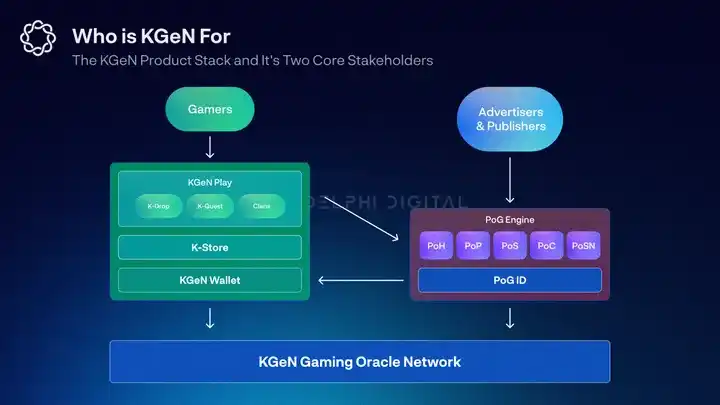
KGeN is a blockchain-driven gaming network that leverages on-chain and off-chain data, an incentive-based task platform, and a decentralized reputation system to drive user engagement across different games. Unlike other User Acquisition (UA) platforms and networks, KGeN returns funds from publishers to users, fueling its growth flywheel.
At the core of KGeN is a decentralized player data network spanning millions of micro-game communities (KGeN Tribes). The network adopts a novel data model called Proof of Gamer (PoG) engine, creating a cross-chain player reputation layer and providing publishers with a highly engaged target user base at a cost far lower than many existing networks.
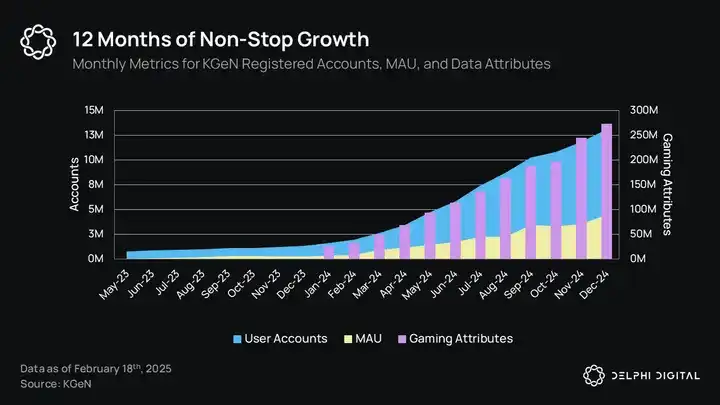
As more players join KGeN and the PoG dataset grows, more game studios and publishers have been able to establish partnership relationships. This has further driven the ecosystem rewards, increasing the value of participating players. Since January 2024, this growth flywheel has shown significant results, with the total number of registered accounts growing by over 700%, monthly active users (MAU) growing by 1333%, and total data attributes growing by 992%. This has made KGeN the most active Web3 task and player reputation network in the market.
The KGeN ecosystem is currently undergoing gradual decentralization, protecting the PoG engine through a distributed oracle network and providing higher transparency to all core stakeholders. This oracle network and the KGeN store are both powered by the KGEN token.
4.1 Grassroots Growth
At the core of KGeN's growth is its grassroots tribes and tribe leader network, which is also key to its continued expansion in the Global South. Tribes represent thousands of micro-communities that have joined the KGeN ecosystem, such as colleagues, esports organizations, influencers, and game-centric social groups. As of December 2024, KGeN self-reported a total of 2,525 tribes, with 152 tribes having over 100 members.
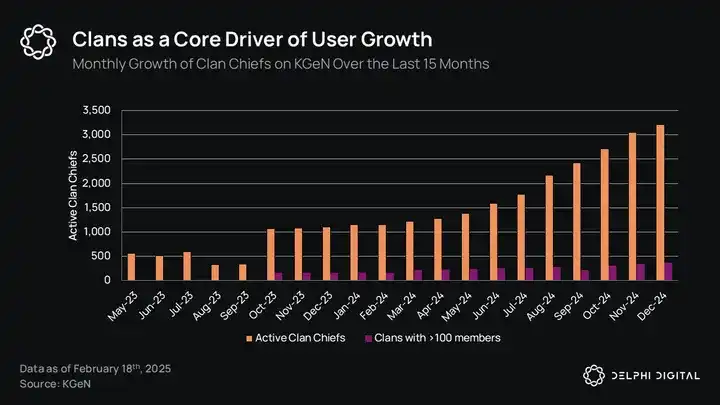
Tribes are one of the core ways KGeN drives recommendation-based user acquisition. When creating a tribe, tribe leaders invite up to five tribe members and have them complete at least one task to earn points. These points contribute to the KGeN leaderboard, which is one of KGeN's primary reward systems (further details will be provided later). This incentive-driven funnel mechanism has proven to be very effective, with approximately 1.7 million KYC-verified KGeN accounts (39% of MAU, 13% of total registered accounts) being acquired through tribes.
Tribe leaders are incentivized not only to onboard new members but also to coordinate tribe activities and maintain community engagement if they wish to maximize earning potential. This is because a portion of the tribe's total earnings will flow back to the tribe leader, making it a key growth incentive mechanism in the ecosystem.
India is currently KGeN's largest market, benefiting from the company's origins and its strong influence in the micro-gaming community in the region. However, over 30% of independent active wallets and transactions occur on Kaia, the proprietary blockchain of the LINE messaging app. LINE's major markets are Japan (86 million users), Thailand (47 million users), Taiwan (21 million users), and Indonesia (13 million users), indicating KGeN's strong growth potential in Asia.
In order to replicate India's success in other global Southern markets, KGeN is encouraged to adopt a similar grassroots growth strategy. Collaborating with local gaming micro-communities such as schools, internet cafes, small-scale esports organizations, and online communities will gradually expand its coverage while creating opportunities to deepen social dynamics, further driving user engagement and retention.
Another potential issue is the relative lack of community social features in the KGeN PC portal and mobile app. As we will discuss in detail in the report, enhancing social features is one way to increase ecosystem participation. The more time users engage in the ecosystem, the richer the user data becomes, providing more opportunities for user interaction with the K-Quest and K-Drop features and greater monetization potential.
4.2 Incentivizing Participation through KGeN Play
KGeN Play is the front-end interface where most ecosystem players engage, and all reward tasks are posted here. This typically marks the beginning of the user journey and will be the main gateway for users to interact with the KGen network while also building their own PoG reputation score.
KGeN Play can be accessed through the PC portal or mobile app. Users will have the best experience through the PC portal, but the mobile app provides a quick solution for users on the go and will play a significant role in the expansion to the global South.
Upon account creation, a blockchain wallet is automatically created in the background, storing all user assets and the non-fungible player reputation NFT. Once the minimum withdrawal threshold is reached, users will be prompted to verify their phone number via OTP and take full control of their wallet—a crucial step directly feeding into the PoG engine. The KGeN wallet has limited functionality but offers a seamless onboarding process, supports multi-chain and gasless transactions, and executes its three main functions (check balance, view transaction history, and withdraw) with low friction.
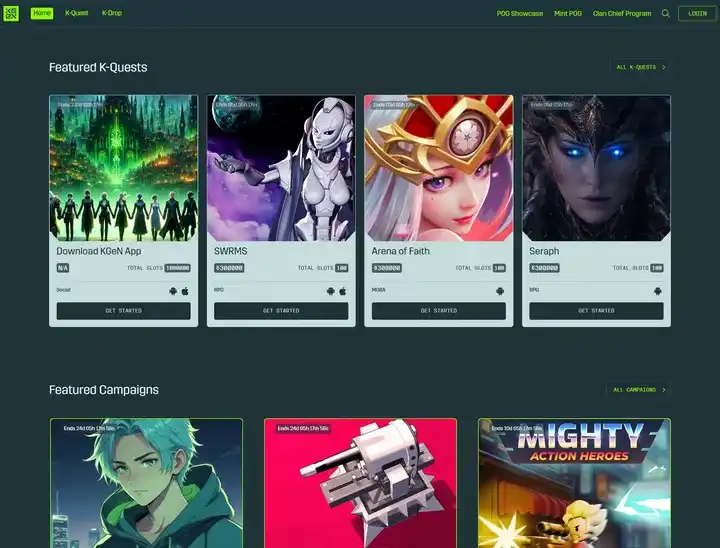
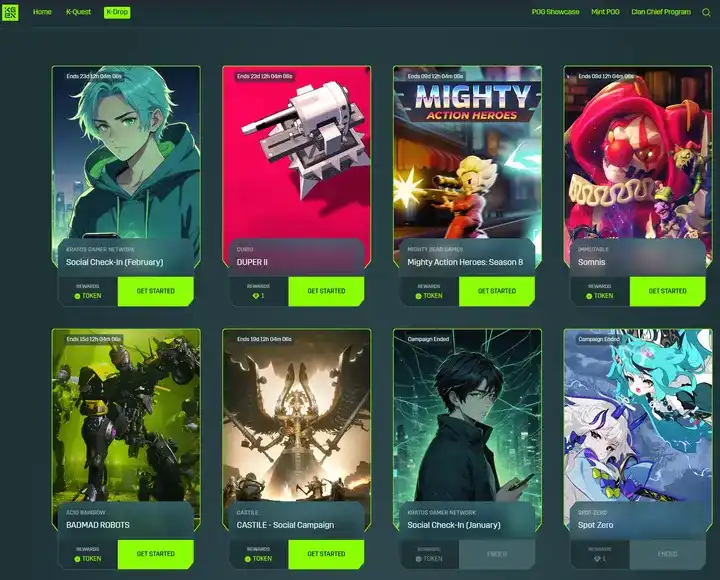
Before users realize they have a blockchain wallet, they first need to start earning rewards. To do this, users need to participate in various activities posted on the KGeN Play portal. Task activities are divided into K-Drops and K-Quests.
K-Drops and K-Quests are both limited-time, limited-quantity activities rewarding participants with K-Points, leaderboard-based achievements, K-Cash, or tokens. The core difference between the two is that K-Drops provide real-time automatic validation through endpoint API integration, while K-Quests undergo a manual validation process.
Unsurprisingly, the completion rate of task platforms leveraging real-world financial incentives, especially those targeting global Southern users, is higher than the average level. The uniqueness of KGeN lies in its combination of KGeN Play with the PoG engine, providing high conversion rate target activities.
4.3 PoG Engine
The PoG Engine is a decentralized player ranking system hosted by a distributed node network. PoG consists of five core pillars, each pillar containing five to ten attributes. These data points track player skills, 'humanization', engagement, wealth, and social network to build a multifaceted cross-chain reputation system.
Ultimately forming a PoG vanity score, benefiting from the inherent composability of blockchain technology, players can showcase their player ID in different ecosystems. Meanwhile, publishers and advertisers can leverage the PoG engine to access a globally competitive, highly engaged player base.
The five core pillars are divided into 'Proof of Humanity' (PoH), 'Proof of Play' (PoP), 'Proof of Skill' (PoS), 'Proof of Commerce' (PoC), and 'Proof of Social Network' (PoSN).
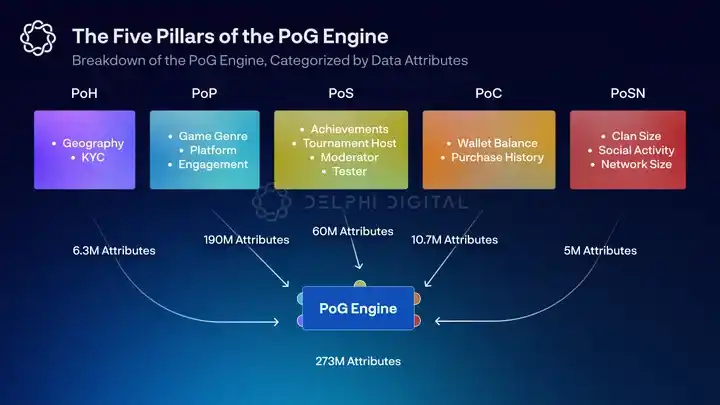
PoH, as the name implies, tracks various data points to reduce the likelihood of users being bots. This may include KYC status or the number of connected social apps, making it one of the most valuable attributes in the eyes of publishers. In addition to tracking 'humanization', PoH further segments the user base based on platform preferences and geographic location. This pillar not only aids user targeting but also enhances trust in user quality and the entire network.
PoP determines player engagement with the KGeN network and the types of games they have played. It tracks metrics related to retention, game modes, preferences, and user habits. This pillar improves targeting by further segmenting different user types and is another set of attributes highly valued by publishers.
PoS recognizes player ability, competitiveness, engagement, and growing achievements over time. It gathers data from in-game achievements, tournaments, and ecosystem activities to rank players. This pillar highlights the most active players and provides them with social capital.
PoC identifies users' monetization potential, which may come from direct purchases, on-chain transactions, on-chain history, or net assets. This not only increases the efficiency of targeting and UA activities but also showcases different ways users add value. In addition to early activities such as game testing, PoC will ultimately become the most valuable dataset for publishers in the post-IDFA era.
The PoSN scales users' social profiles and establishes their social graph within the KGeN network. This pillar filters out non-gaming data, tracks social accounts, tribe activities, and network scale to understand their social preferences, influence, and impact within the gaming community.
The PoG Engine currently consists of over 270 million data attributes sourced from over 13 million registered accounts and 4.4 million MAU. Since January 2024, the PoH, PoP, PoS, PoC, and PoSN cohorts have grown by approximately 214%, 1320%, 777%, 384%, and 487%, respectively. The notable growth in PoP and PoS-related data specifically highlights how ecosystem participation has steadily increased over time.

Using the PoG Engine, KGeN is spearheading an alternative UA framework called "effective Customer Acquisition Cost" (eCAC). KGeN does not charge for simple impressions or top-of-funnel installs but only charges for active users reaching the middle or bottom of the user funnel.
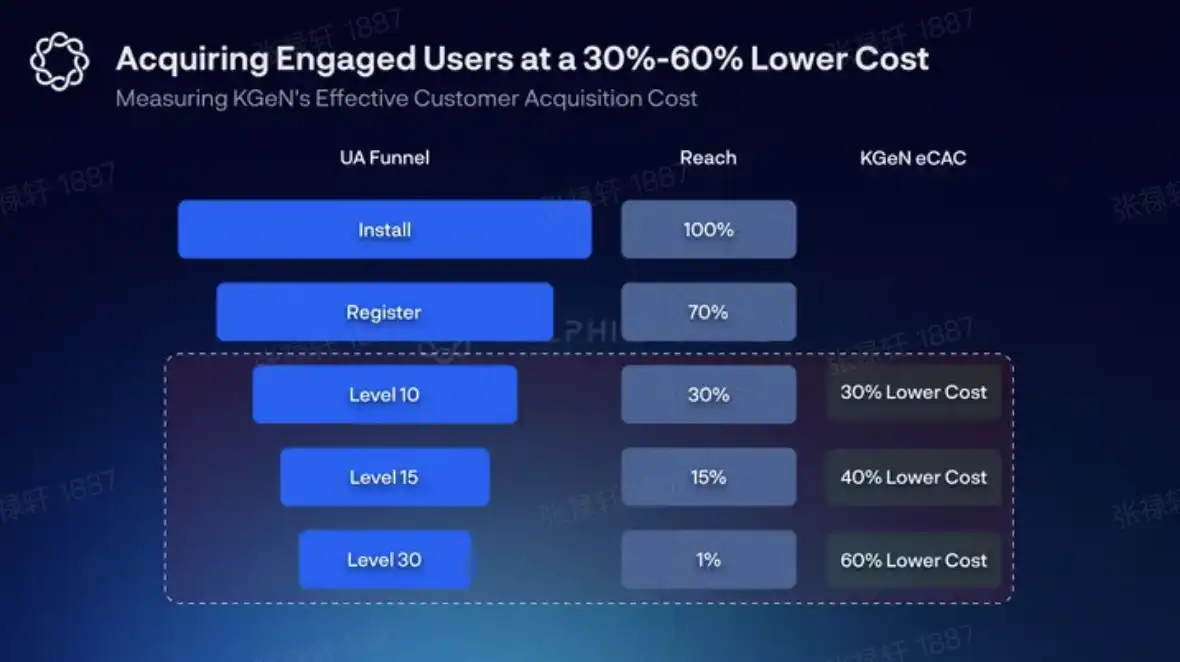
For example, in collaboration with Karate Combat, KGeN reports a nearly 40% reduction in eCAC while charging no fees for top-of-funnel installs and achieving a 5% bottom-of-funnel conversion rate. In a four-week mission event with Game7, KGeN states they facilitated the introduction of 50,000 PoH verified users with an eCAC 55% lower than competitors. User registrations, wallet connections, and avatar creation events are all free, meaning customers only pay for users completing at least four tasks and minting an SBT (estimated conversion rate of 20%).
The PoH and PoP cohorts are particularly valuable as these data points offer relatively higher engagement ROI for commercial clients. This is crucial for Web3 projects utilizing financial incentives, which often face challenges from bad actors and bots. However, these data points are not foolproof and even KYC could be manipulated.
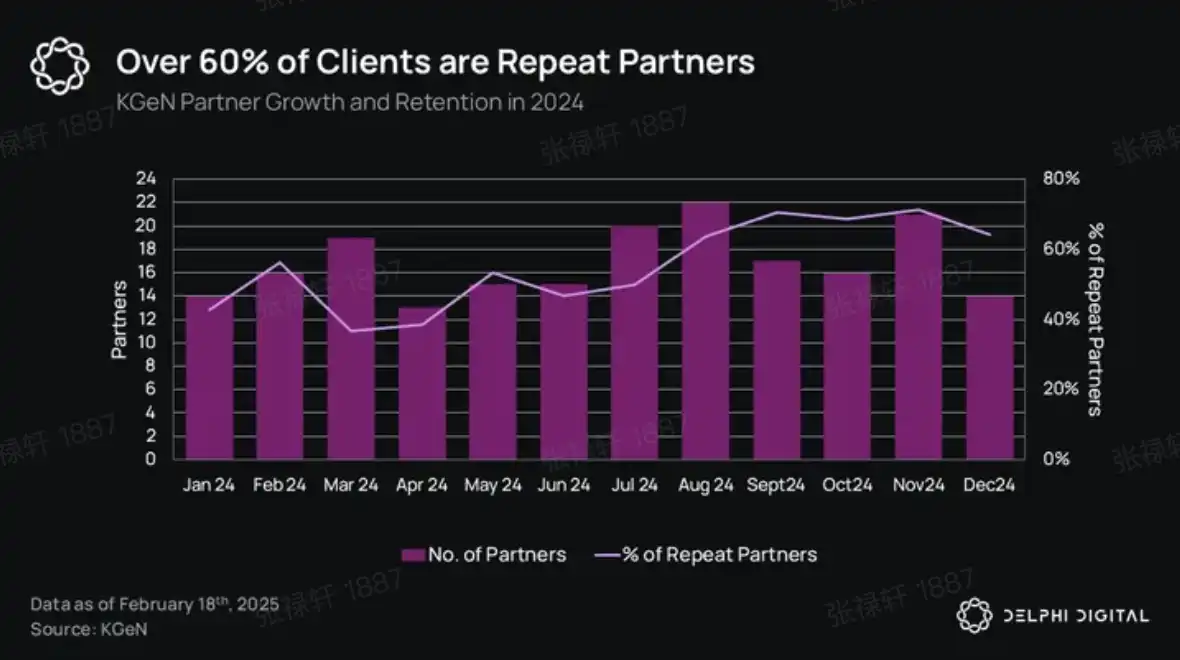
Nevertheless, KGeN's ability to highly ascertain user quality has brought significant added value to its partners. As detailed in our upcoming report, ad fraud has led to approximately $840 billion in digital ad spend waste. This is also a key reason why over 60% of KGeN partners have become repeat customers since August 2024.
Over time, the growth flywheel crucial for KGeN's future expansion will gain momentum. As long as there is a demand for positive PoG scores, engagement with KGeN Play will increase (this can be further accelerated through PoG-score-based financial incentives). This activity will drive the PoG engine, increase the total number of attributes, and enrich KGeN's user database. Subsequently, more publishers will be attracted to the ecosystem, increasing the product variety on KGeN Play and KGeN Store, thus attracting more users.
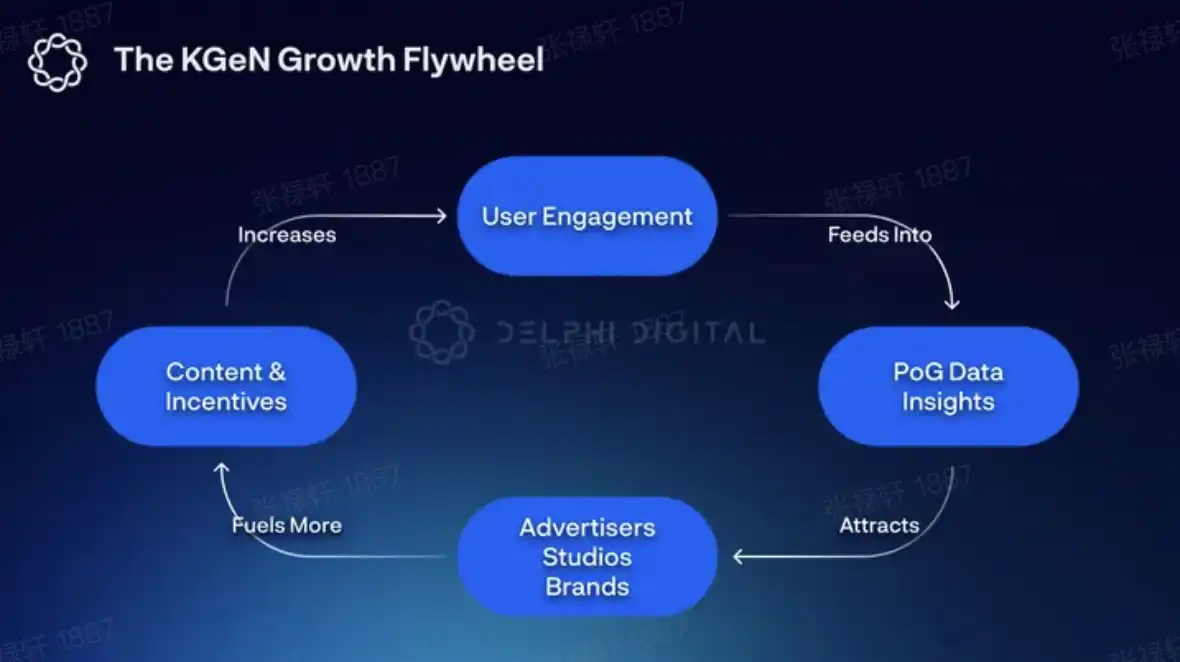
The PoG score is at the core of KGeN's business model and is key to its ability to offer customers a competitive low-cost eCAC. A key question is, what drives this user behavior?
As long as the incentive is financial in nature, the platform will undoubtedly show promising results. However, this creates an external motivational force that dictates how users interact with the platform and its partners.
Users driven by external motivation are less likely to continue playing games they were initially attracted to because of rewards. Furthermore, research suggests that providing external rewards for behavior that was originally driven by intrinsic rewards will diminish intrinsic motivation—an effect known as the overjustification effect.
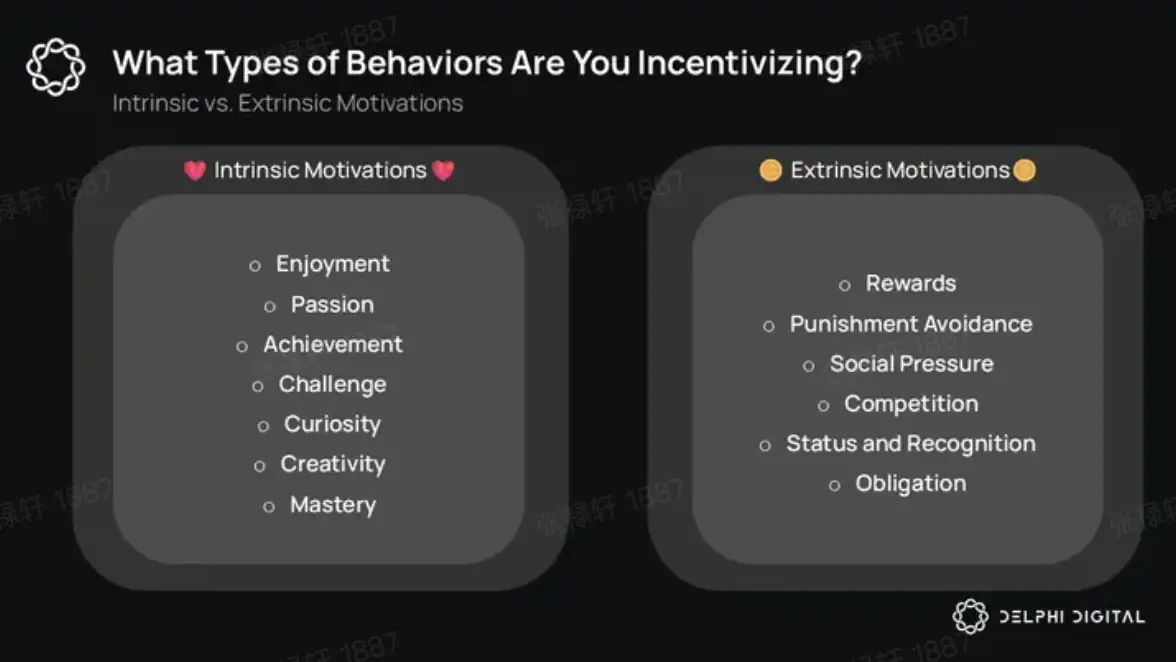
Users with intrinsic motivation seek value in things they enjoy, such as social interaction, recognition and respect, progress and fun. If, over time, strong network effects can transform the core value proposition of the PoG score into something rooted in social capital and enjoyment, motivation will gradually internalize, thereby increasing the potential value provided to partner publishers.
4.4 KGeN Tokenomics
KGeN's economy will consist of two core assets: KCash and KGEN tokens. KCash has been live for some time, primarily serving as the off-chain reward currency but can also be purchased directly with fiat. KCash's primary use is within KStore, where it can be used for in-app purchases (IAP), gift cards, or participation in VIP tournaments and missions.
Driving the growth flywheel of the KGeN ecosystem is the KGEN token. This is a utility token, with a community allocation of 40% (of which 8% unlocks at Token Generation Event (TGE)), with a four-year lock-up for the team and investors. 12.6% of the total token supply will unlock at TGE, excluding the circulating supply locked with market makers or exchanges.
Recently announced, ahead of the TGE, KGeN will conduct a K-Points -> rKGEN airdrop event. rKGEN allocation is based on a user's total K-Points, time on KGeN, and engagement. Once the token is live, rKGEN can be converted to KGEN tokens at a 1:1 ratio. However, some users will be able to start staking rKGEN for additional token rewards before the TGE.
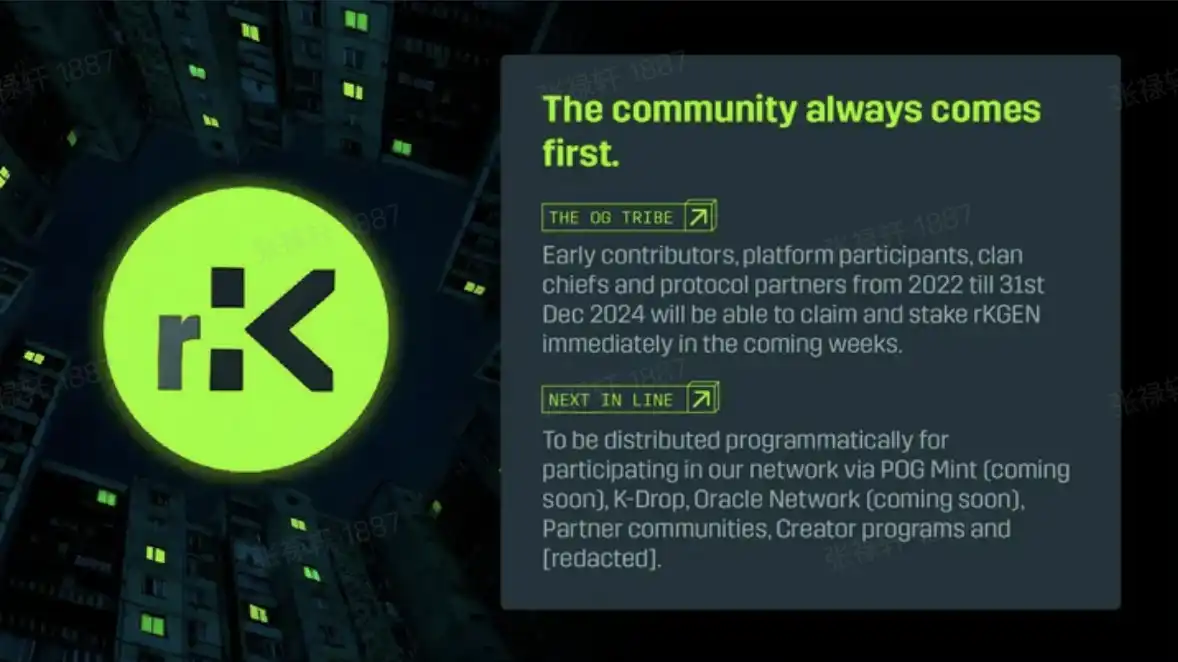
K-Points -> rKGEN Airdrop model prioritizes transparency and clear communication to maximize community sentiment and token distribution ahead of the TGE. If executed successfully, this could help build momentum at launch and ensure additional CEX listings, but it comes with its own risks.
A fuzzy rewards system has been shown to increase participation across various domains. While pure points-based airdrop events offer lower transparency, they provide teams with greater flexibility in token airdrop distribution. This design concept raises a question: post-TGE, will the KGeN Play activity utilize the K-Points -> KGEN rewards system, or opt for direct token payments?
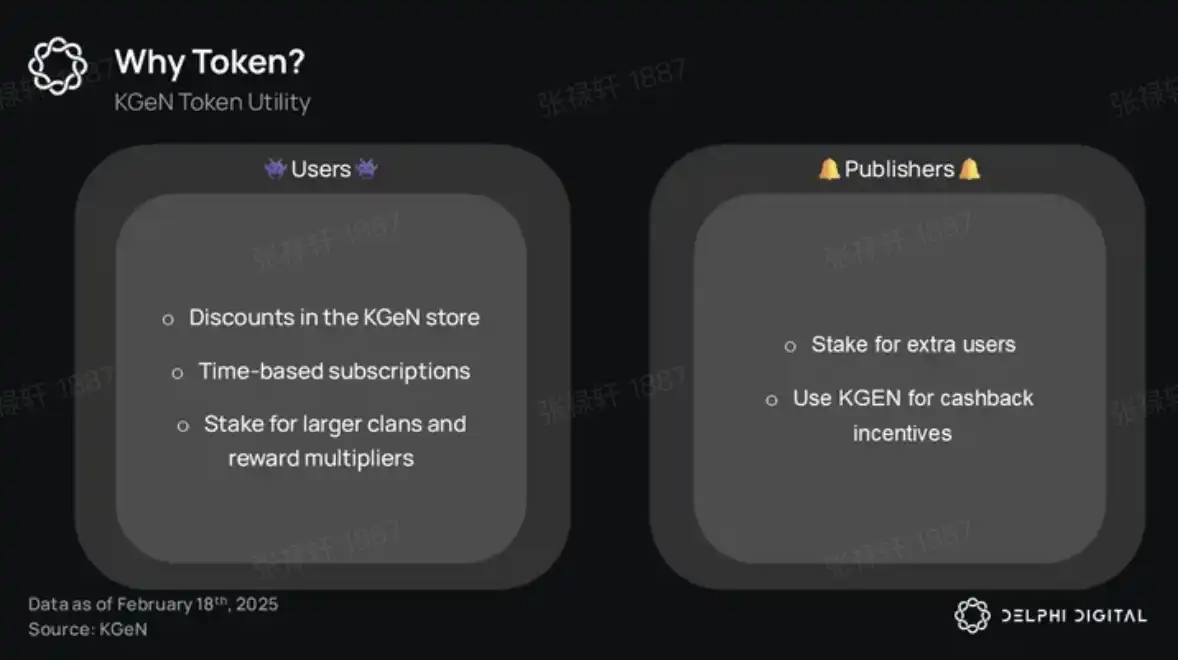
At launch, we assume the KGEN token will primarily be used for incentives. However, over time, as the network matures, we anticipate more users will use the token in the KGeN Store to enjoy discounts more favorable than fiat purchases.
Another potential form of token consumption could be subscription fees. As users increasingly rely on the network to host their reputation scores, game achievements, and social touchpoints, KGeN might decide to limit the number of tasks available to free users. This would effectively curb much of the revenue potential on the network and serve as an additional bot protection measure.
Nevertheless, unless non-financial rewards hold significant intrinsic value for users, many will not spend tokens unless they can achieve a positive return on investment. To prevent this from becoming an inflationary consumption (i.e., more tokens released than removed), KGeN should offer third-party token, KCash, or NFT. Ultimately, the most sustainable consumption is driven by internal motivations (such as entertainment and social capital).
In addition to direct token consumption, there will also be token staking. Apart from users seeking simple staking rewards, tribe leaders can stake tokens to increase their member cap and gain additional platform tools. Issuers can also participate in layered staking schemes to acquire more free top-of-the-funnel users in their UA activities—we expect this feature to gain more attention as the platform continues its current growth trajectory.
Typical token staking is an inflationary model that ultimately dilutes the token supply in exchange for deferred selling pressure. Despite potential short-term benefits, it is encouraging to see KGeN incentivize non-inflationary staking for tribe leaders and issuers.
4.5 Oracle Network
The KGeN Oracle Network is a distributed network composed of permissioned nodes that together form the backbone of the PoG Engine. Each oracle's task is to store PoG data, calculate PoG scores (and collectively validate their accuracy), and submit these scores to the Aptos blockchain for settlement. As a reward for providing this service, oracle operators will receive a fixed amount of KGEN token rewards based on revenue predictions, as well as stablecoin rewards tied to the amount invested in the oracle.
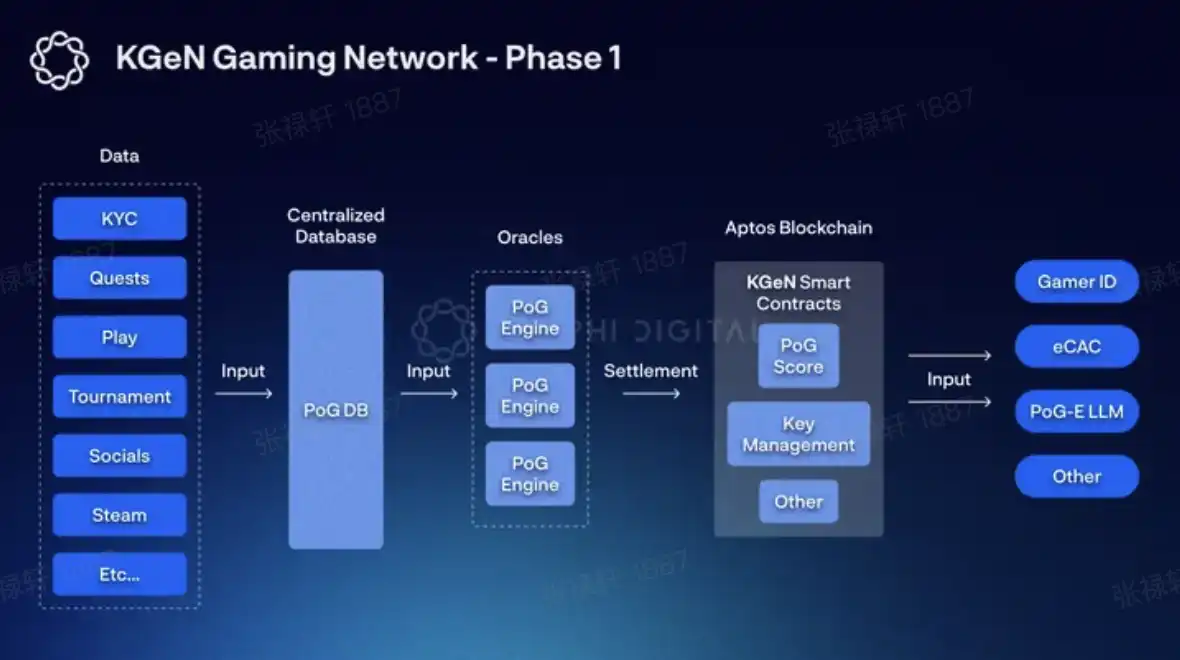
The Oracle Network will ultimately decentralize a process that is typically done in a centralized manner. This will be a gradual process, expected to take at least three years. In the first stage, oracles will primarily retrieve PoG data from centralized servers and participate in computation, validation, and settlement—the decentralized storage of PoG data will begin in the second stage.
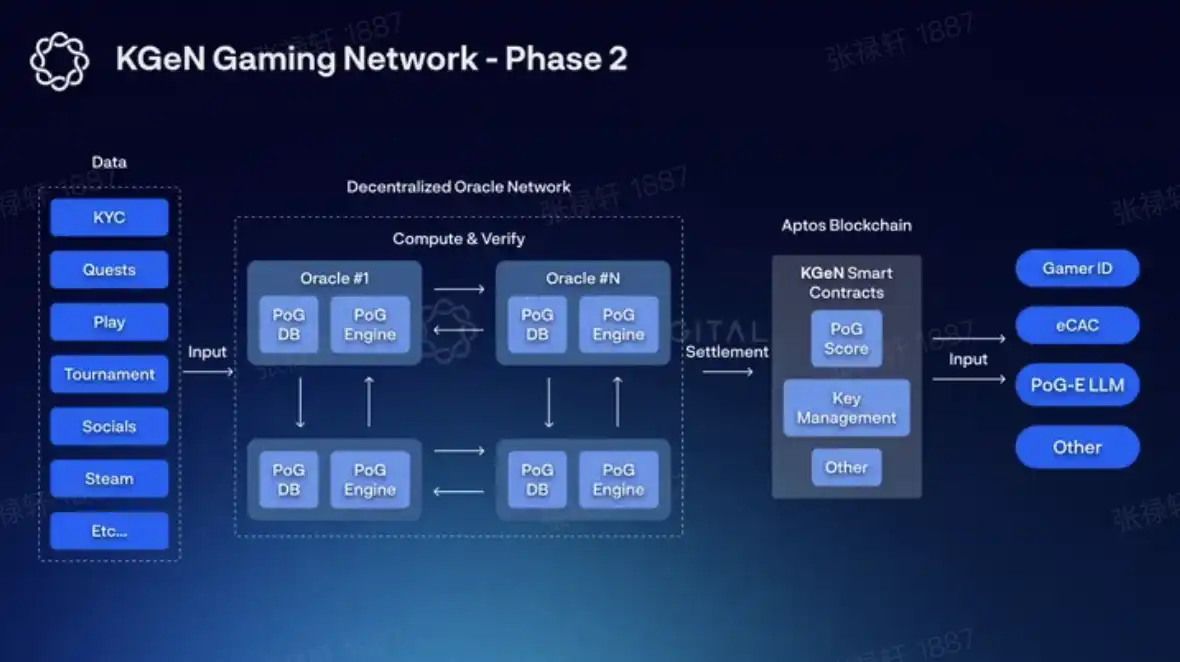
Another core component of the Oracle Network is the Oracle Key. The key is an NFT required to participate in the network. The more oracle operators spend on their Oracle License, the more keys they receive. KGeN also indicates that additional key sales to the public may be available in the future.
Oracle Keys will remain locked in an account until the network transitions to the second stage, at which point they will become tradable, and key holders can delegate their keys to oracle operators. Key delegation is similar to a typical staking mechanism, temporarily locking the key NFT in exchange for KGEN token rewards from the key reward pool.
The weight of an oracle in the key reward pool is calculated based on three variables: the amount of keys staked to the oracle, the protocol's base reward, and the oracle's performance. Performance is only relevant as KGeN transitions to the second stage, and the specific calculation method is yet to be determined. The base reward is based on emissions and serves as an indicator of the overall network health. While specific details are not confirmed, the goal is for all oracles' base rewards to increase as the network's value grows.
The Oracle Network combines aspects of node and Delegated Proof of Stake (DPoS) frameworks to decentralize the PoG Engine. In a fully centralized framework, KGeN's centralized data center represents a single point of failure for data corruption or deletion. Additionally, core stakeholders (i.e., players and publishers) hold some trust assumptions, namely that these PoG scores have not been manipulated.
In this scenario, the benefits of decentralization are quite subjective to users. In certain circles, it may be challenging to find a player actively complaining about the centralized nature of their Xbox Gamerscore or Steam account. Similarly, publishers are more concerned with scalable user acquisition than decentralization.
However, this overlooks the potential network effects and aligned incentives that the token model can help achieve. By providing stakeholders with a way to benefit from the growth of KGeN, you can create brand advocates who support the project. Assuming that KGeN's growth flywheel translates into positive token price action, more stakeholders will be attracted to the ecosystem, further accelerating the network effect.
5. Competitive Landscape
KGeN is not the only company with this ambition. As we discussed earlier, token issuance is seen by many as one of the biggest challenges facing the current gaming industry. Whether expanding user acquisition (UA) activities profitably or optimizing core engagement metrics by increasing player liquidity, multiple industry players are tackling these issues with varying degrees of success.
Next, we will focus on analyzing some companies operating in the Web2 and Web3 markets, comparing their business models, uncovering potential opportunities, and highlighting some key considerations.
5.1 Ad Tech Titans: Then and Now
In the Web2 market, there are two typical cases that exhibit many synergies with KGeN's current business model while also revealing key growth opportunities for the future. The first is Facebook, whose core strength lies in deep mining of user profiles and behavior analysis. The second is Applovin, an enterprise deeply rooted in advertising technology, spanning the mobile ad ecosystem, which, with its powerful AI-powered tools, has gained a considerable market share in the mobile user acquisition (UA) space.
Facebook:
After trying various ad formats, Facebook found its foothold at the end of the web game era and the rise of mobile.
Companies like King ("Candy Crush Saga"), Playtika ("Slotomania"), and Zynga ("Farmville") successfully built games on Facebook's web platform and then sought ways to break through the natural flow of growth. These game companies' investment in Facebook ads reached unprecedented levels, to the point where in the first half of 2011, Zynga contributed 12% of Facebook's revenue.
Between 2013 and 2016, Facebook gradually shifted its focus to mobile ads, capturing nearly 30% of the mobile ad market share in 2014, up from 0% just two years earlier, becoming the industry's second-largest player behind Google.
The success of Facebook's advertising business lies in the precise tracking of user behavior, engagement with games, and spending patterns to optimize ad delivery and distribution. The platform's key value is its ability to identify and precisely target high-value users—those who exhibit higher game engagement and willingness to pay, for whom developers are willing to pay a higher price for targeted advertising.
By integrating with the game's SDK, Facebook further strengthens this capability, allowing it to track post-install user behavior and optimize downstream metrics like ROAS (Return on Ad Spend). Additionally, Facebook's social features provide game developers with additional organic growth channels.
To some extent, KGeN has adopted a strategy similar to Facebook's, focusing on player data as a core value. However, while Facebook's target users are mainly in the casual gaming space, covering hundreds of millions of users, KGeN is more focused on mid-core and hardcore game categories, with its user base consisting entirely of gamers.
To further solidify its positioning as a decentralized Facebook ad network, KGeN can increase its investment in the social features of its own product (they plan to gradually introduce new messaging and tournament features). This will not only help KGeN collect more data on user journeys, preferences, and behaviors but also provide developers with additional distribution channels.
Applovin:
Applovin is a highly sophisticated ad tech platform whose business model relies on optimizing ad delivery and improving delivery effectiveness while leveraging its Supply-Side Platform (SSP) data for pricing analysis. The company has a presence on both ends of the mobile advertising market:
Its Supply-Side Platform (SSP) MAX, through acquisitions like MoPub, Machine Zone, and its in-house game studio Lion Studios, has amassed a vast amount of data to help developers sell ad inventory at the best prices.
Its Demand-Side Platform (DSP) AppDiscovery assists advertisers in buying ad inventory based on user acquisition (UA) targets and cost metrics.
Following Apple's introduction of the App Tracking Transparency (ATT) privacy policy, traditional user-level tracking has been impacted. However, leveraging its end-to-end data integration advantage, Applovin can provide developers with user valuation within compliance boundaries, maintaining the accuracy of ad targeting.
At the core of the Applovin ecosystem is its machine learning engine, AXON, which combines mobile app user behavior data with platform bidding data to predict the apps that users are most likely to download and engage with.
This bidirectional data flow model gives Applovin a competitive edge, allowing it to not only obtain data from ad demand sources but also to understand the supply side's market dynamics and pricing information, thereby providing industry-leading data insights and ad optimization capabilities.
Undeniably, Applovin's ad tech platform far surpasses KGeN in maturity and scalability. However, similar to Applovin, KGeN also has the opportunity to collaborate directly with partners to drive integration of their own SDK or to flow game database back into the PoG engine.
This will not only greatly enrich the PoG database but also enhance ad tracking capabilities. Additionally, this more comprehensive data system will support KGeN's newly launched POG-E LLM (Large Language Model enhanced by KGeN's proprietary data), enabling it to recommend more relevant tasks to players easier to convert into paying users, similar to AXON.
Mystplay:
Mystplay is one of the fastest-growing reward-based UA platforms in the Web2 space. Its core product is a standalone game discovery app where users can earn points by trying out games on the platform, which can be redeemed for gift cards.
Reward-based UA platforms are rapidly emerging in the gaming industry, with 68% of developers believing that compared to other UA channels, reward-based marketing offers higher ROAS. These platforms generally claim that the users they acquire outperform the industry average in terms of retention and revenue. For example, some cases from Mystplay show that their rewarded users can increase 20%-50% in 7-day retention rate or ROAS. Currently, other well-known reward-based UA platforms include Adjoe, Almedia (Freecash), Tapjoy, MyAppFree (MAF), among others.
Mystplay's unique advantages lie in its rich social features (such as chat, weekly competitions, and leaderboards) and its AI-driven recommendation engine, which can match players with the games that suit them best, enhancing user stickiness and gameplay duration. Mystplay follows a quality-first UA strategy, leading to rapid growth over the past 24 months.
As of 2022, Mystplay has approximately 16 million registered users, with over 2 million monthly active users (MAU) in 2023, over 400 partner games, and is often recognized as one of the top 10 performing Android distribution platforms. Its annual revenue is estimated to be around $55 million, the team has grown by about 43% in the past year, achieving a 445% growth in four years, successfully making it to the Deloitte Technology Fast 50 list of high-growth tech companies in 2024.
At first glance, Mystplay's value proposition is very similar to KGeN's. However, Mystplay mainly targets the European and American tier-one markets and is constrained by the lack of a globally available blockchain payment channel, forcing it to adopt a "quality over quantity" strategy. Therefore, Mystplay relies on AI for precise matching to improve conversion rates and retention rates, which is a key direction that KGeN can learn from.
5.2 Web3 Competitive Landscape:
In the Web3 market, competitors can mainly be divided into two categories: publisher ecosystems and task platforms. Both aim to drive user growth through collaborative projects.
Web3 Publisher Ecosystems:
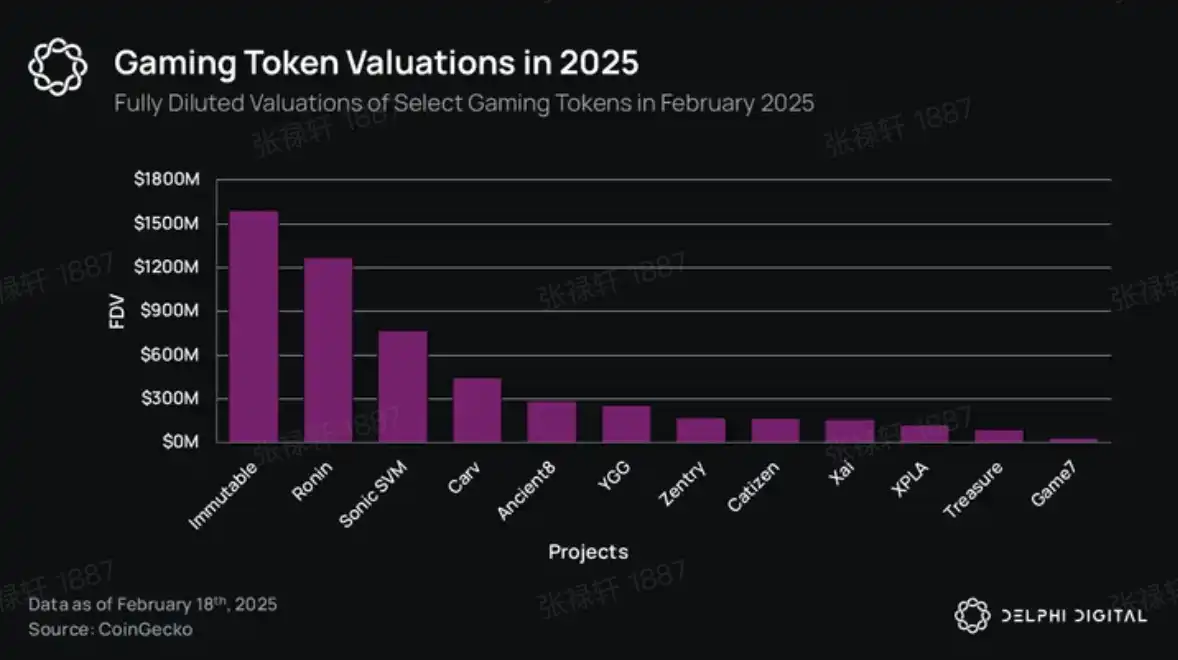
Publisher ecosystems typically provide Web3 User Acquisition (UA) optimization support for partners in the following ways: offering tokens for UA spending, utilizing ecosystem token inflation for UA incentives, etc. Representative ecosystems that adopt these models include Ronin, Immutable, Xai, and Catizens, with their fully diluted valuations (FDV) being $16.5 billion, $23.4 billion, $2.882 billion, and $2.616 billion, respectively.
Due to some fundamental differences, there is no direct competitive relationship between publisher ecosystems and KGeN. The revenue model of publisher ecosystems is mainly based on the fee structure of developer activities, while KGeN's core lies in "controlling" the user journey and being able to operate freely across different blockchains and games. This irrelevance allows KGeN to avoid getting into a zero-sum exclusive agreement competition, thereby expanding its Total Addressable Market (TAM).
However, as described in the Applovin section, KGeN often fails to obtain many key data points once users reach the target location (in-game or in-app). Publisher ecosystems like Ronin have a greater advantage in user behavior visibility as they have end-to-end user data (especially on-chain data and wallet profiles). Furthermore, publisher ecosystems deepen their competitive moat by providing funding and infrastructure support to applications.
Task Platforms:
Reward tasks are widely used by Web3 projects in various fields to increase market awareness and distribute assets to stakeholders. This is particularly evident for game projects that aim to accelerate growth through UA incentives, enhance user retention through reward mechanisms, and maximize protocol activity.
The core advantage of task platforms is that they can aggregate tasks from multiple projects, providing users with a one-stop task participation experience while allowing issuers to reach a broader audience.
Currently, KGeN is also a task discovery platform competing for user attention with other Web3 task platforms. Its strong community base in India and Brazil has given it a first-mover advantage in these markets. However, this does not guarantee its continued success in the future. The following analysis will delve into the success factors of blockchain-driven task platforms and evaluate the strengths and weaknesses of KGeN's current model.
5.3 Competitive Analysis
Essentially, all task platforms offer "quest-to-earn" services, with their differentiation mainly reflected in scale and the ability to deliver value-driven results for issuers.
The market's demand for high-quality User Acquisition (UA) results has grown exponentially. As traffic distribution becomes increasingly challenging, a significant portion of UA budgets is wasted on low-quality interactions every year. It is estimated that in 2023 alone, digital advertising's wasted expenditure due to bot traffic amounts to a staggering $840 billion.
While fraud issues are less prevalent on Owned and Operated (O&O) platforms such as TikTok, Snapchat, and Instagram, malicious actors persist in large-scale UA campaigns using last-click attribution. Some industry leaders, such as Applovin, have sought to address criticism from players and issuers by collaborating with third-party anti-fraud technology solutions. However, publishers and advertisers using programmatic advertising still need to establish trust in ad platforms.
For KGeN, its Proof-of-Growth (PoG) engine, especially PoH and PoP scores, forms a key competitive advantage for the platform in the high bot traffic market. By gradually decentralizing the PoG engine, KGeN aims to reduce remaining trust assumptions. The market's demand for these verifiable high-interaction users is strong, as evidenced by KGeN's continuous revenue growth and high rate of repeat customers.
That being said, when measuring the success of UA activities, merely looking at effective Cost per Acquisition (eCAC) is not sufficient. KGeN needs to effectively monetize users, acquire more data points along the user journey (especially PoC-related data), and use this data to provide precise targeting and optimization for partners to ensure profitability.
When examining the key factors for how Web3 task platforms can excel in a scalable competition, we can make the following assumptions:
As long as the switching cost is low and there is sufficient economic incentive between platforms, the same group of users will attempt to participate in tasks across all platforms.
When time becomes a primary limiting factor, users will allocate their energy to activities with the highest ROI.
Based on this assumption, and excluding the narrative fluctuations in the Web3 space, we can use two key metrics to measure the scalability competitiveness and user retention capability of Web3 task platforms: Total Potential Rewards (TPR) and Locked Platform Value (LPV).
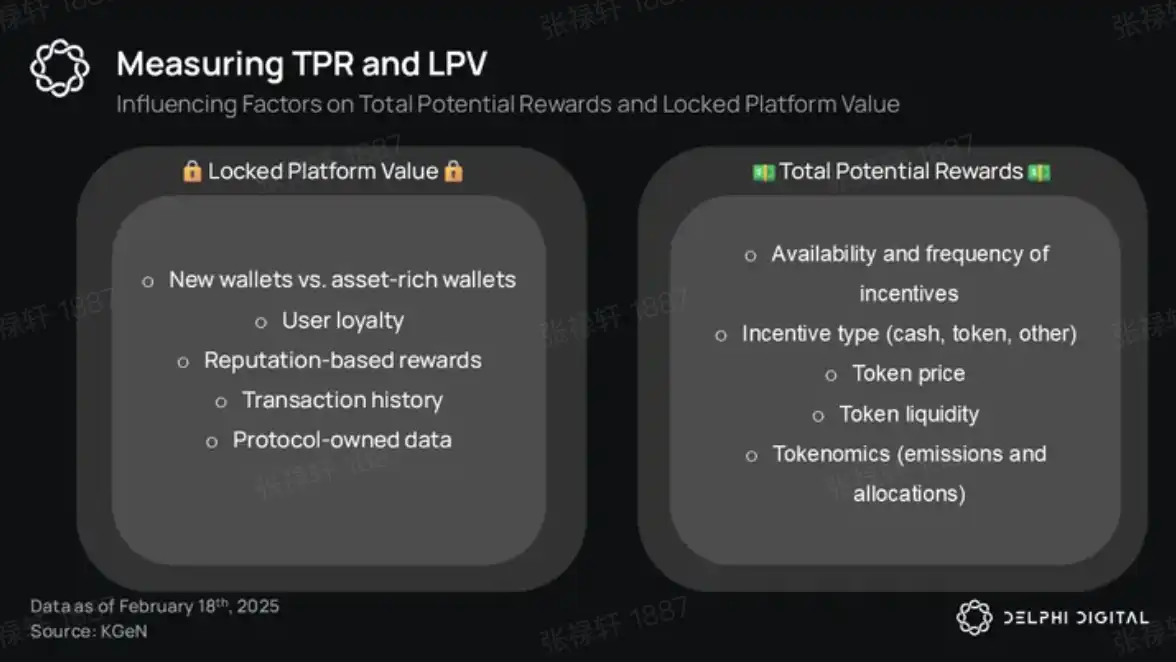
TPR (Total Potential Rewards) refers to the total amount of financial rewards users can earn throughout the platform's lifetime. TPR is mainly influenced by the tokenomics model (such as allocation ratio, inflation mechanism, etc.), the number of available incentive mechanisms, the ratio of cash rewards to token rewards, the frequency of task rewards, and is also constrained by some external factors, such as token price and liquidity.
LPV (Locked Platform Value) measures the protocol's level of "control" over users and the perceived level of user quality. Factors affecting LPV include the ratio of new wallets to high-asset wallets in associated wallets, user loyalty, reputation-based reward systems (more favorable to long-term active users), on-chain and off-chain transaction history, and the protocol's ownership of user data (which also feeds back into TPR because more accurate user data can increase the protocol's ad revenue, further enhancing the user reward pool).
In terms of TPR, we can assume that, in the absence of monopolistic pricing power, over time, UA incentive rewards between different platforms will gradually trend towards equilibrium.
Regarding LPV, for advertisers, the most valuable platforms are those with the largest user bases and those that have the deepest user data (enhancing targeted advertising and monetization capabilities).
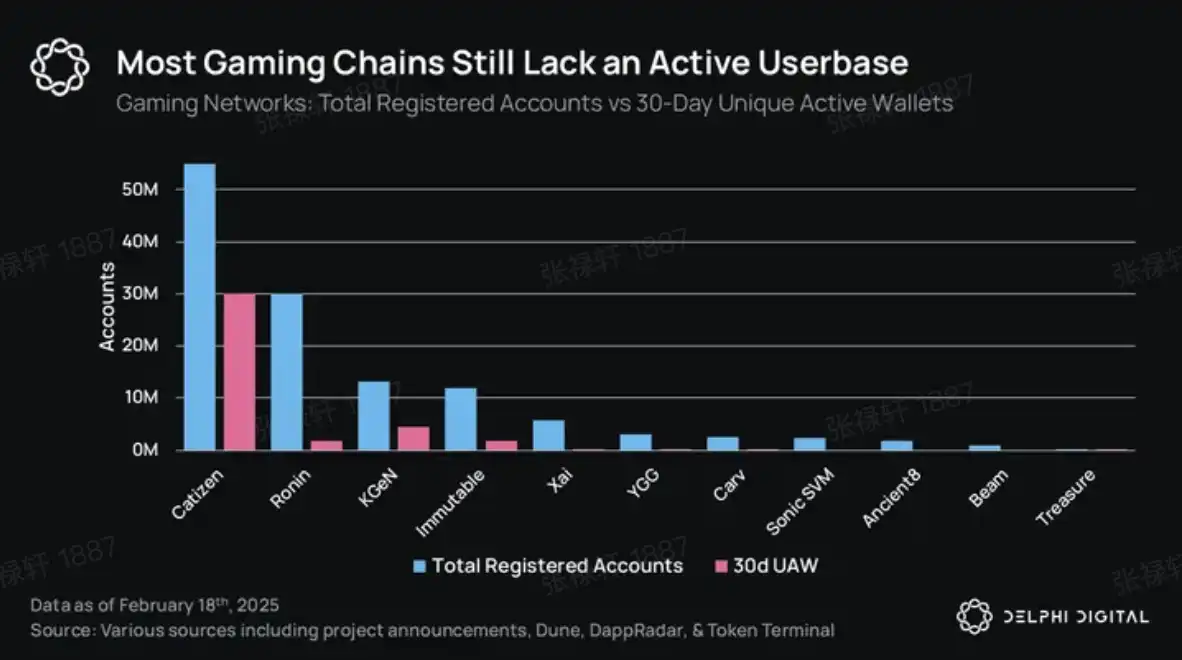
KGeN currently has the highest number of registered accounts across all task platforms, as well as the highest number of 30-day active wallets. Additionally, as mentioned earlier, PoH (Proof of Humanity) and PoP (Proof of Participation) are important metrics lacking in many other platforms. These two factors give KGeN a significant competitive advantage in terms of LPV, and this advantage will continue to grow as the PoC (Proof of Contribution) data matures.
In contrast, the comparison regarding TPR is not as straightforward. One key factor is the number of active tasks at any given time and the frequency of new task launches. Some platforms may boost these metrics through unsustainable high inflationary token distribution, but for the purpose of this analysis, it is assumed that all rewards are calculated in USD to enable a more objective comparison.
As mentioned earlier, KGeN leads in both total registered accounts and monthly active users (MAU), both of which are crucial benchmarks for issuers to assess market demand. Additionally, KGeN has stated that the company has never subsidized any UA activities on KGeN Play, suggesting that the market demand for its services is at least on par with Web3 counterparts, if not higher.
Post TGE (Token Generation Event), other key factors affecting TPR include token price, token reward distribution mechanisms, and overall reward allocation. The specific issuance rates of the latter two are currently unpredictable, but it is worth noting that KGeN's community reward allocation ratio stands at a high 40%, placing it at the upper end of industry reward distribution.
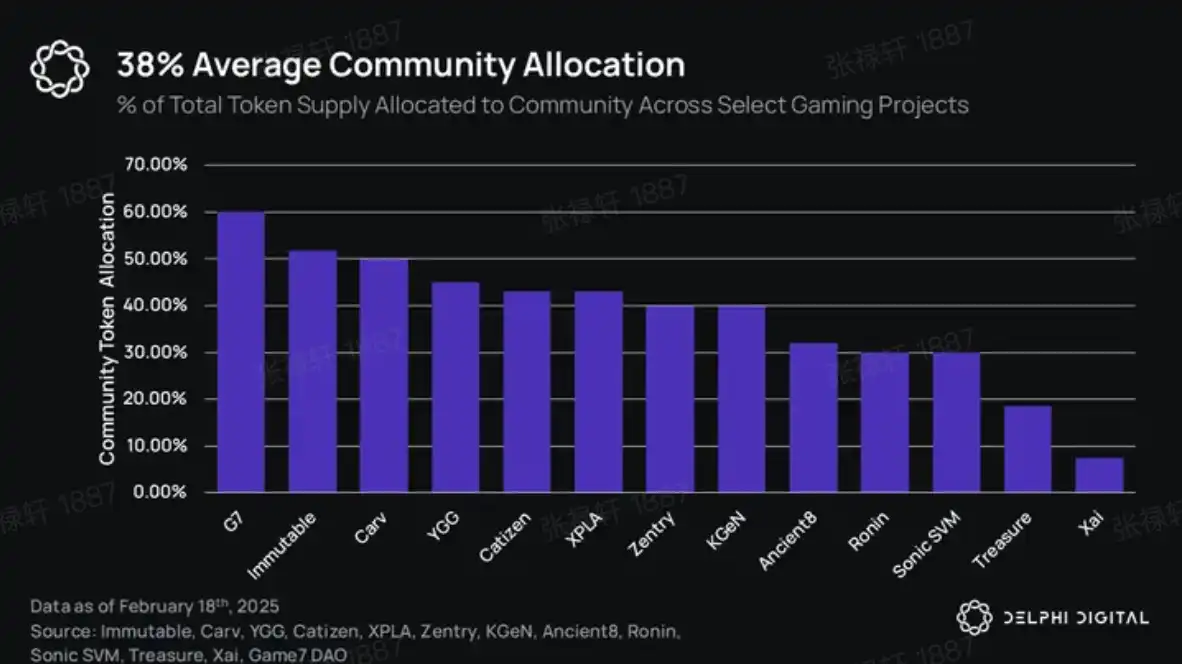
Regarding token price, assuming the reward for a single task remains constant, to compete effectively in the market, the market cap of the KGeN token would need to reach at least $140 million at launch to remain competitive with Zentry ($138 million market cap) and YGG ($132 million market cap). From a Fully Diluted Valuation (FDV) perspective, the most valuable task platform currently is Carv, exceeding $600 million (although Carv appears to be transitioning from a task platform to a multi-chain data infrastructure provider).
To achieve global competitiveness in both the Web3 and Web2 markets, KGeN needs to continue expanding into the Global South markets to achieve market coverage similar to giants like Applovin. At the same time, KGeN must maintain its eCAC cost advantage at this scale and demonstrate the monetizable value of these users through attributes such as Proof of Contribution (PoC).
6. Future Opportunities
KGeN has built a strong core growth flywheel, but currently relies heavily on external incentives during the user acquisition phase. However, as the network scale continues to grow, KGeN has the opportunity to evolve into a critical distribution layer of the Web3 ecosystem, going beyond early financial incentives and truly unlocking the immense potential of network effects.
External incentives (such as a reward mechanism) can be used not only for initial growth but also to effectively guide users to develop new skills or acquire new knowledge, gradually transforming into users' intrinsic motivation. Therefore, in the future expansion phase, KGeN should strategically utilize external rewards to guide user participation in non-core tasks such as friend referrals, market promotions, user feedback, community governance, and bug bounty programs. At the same time, the platform should avoid predictable fixed financial returns (ROI) and prioritize non-monetary rewards such as in-game items, privileges, social benefits, or other rewards to enhance user stickiness and community loyalty.
More importantly, KGeN has the opportunity to significantly enhance the data value in the Proof of Consumption (PoC) dimension through on-chain transactions and behavioral data, combining user wallet activity with user behavior, consumption preferences, social interactions, and other data to build a unique, profound, and widely applicable data ecosystem. This data-driven capability will significantly surpass traditional Web2 UA platforms, providing unprecedented insights into user behavior, thereby optimizing ad targeting and user value discovery.
As the Proof of Gamer (PoG) engine matures, it will gradually evolve into the standardization of reputation and identity systems in Web3. As a composable reputation layer, PoG will be widely adopted by more projects, not only to support game publishers in launching more SKUs and expanding on-chain transaction volumes but also to become the underlying infrastructure for multiple applications such as decentralized finance (DeFi), esports events, community governance, AI model training, and others. This widespread adoption across projects will further enhance the network effect of KGeN, establishing an irreversible market leadership advantage.
At the same time, KGeN should implement flexible incentive and monetization mechanisms, reduce arbitrage behaviors effectively through blurred rewards and set revenue payment thresholds, optimize user structure, and nurture a high-value user base. This will drive healthy growth of the network, further consolidating KGeN's strategic position in the Web3 ecosystem.
Data capability is KGeN's core competitive advantage. The network not only provides a high-quality player pool in the early stages (such as a gold user base) but also, in the scaling phase, enhances attribution models by building bidirectional data streams and performs real-time optimization through AI technology. In the future, KGeN should rapidly develop a data sharing mechanism between advertisers and publishers, build highly differentiated AI data tools such as personalized recommendation engines, real-time user matching algorithms, and dynamic optimization tools. This will establish an irreplicable data barrier, strengthening the game network's competitive advantage in global South and other emerging markets.
7. Conclusion
KGeN has become one of the largest Web3 game networks, with access to over 270 million data attributes covering over 13 million registered accounts. With its unique growth flywheel, KGeN not only effectively reduces publisher eCAC costs but also significantly increases user long-term value.
KGeN has established a strong first-mover advantage in the global southern markets, with 4.4 million MAU active user base and robust community engagement capabilities, making KGeN an ideal partner for entering emerging markets and the preferred Web3 UA Distribution Layer.
As a composable Reputation Layer, the PoG engine has been successfully utilized to generate users' on-chain reputation scores and has gained widespread recognition. Its decentralized design enhances network trustworthiness and resilience, reducing manipulation risks. In the future, KGeN will further expand the application of the PoG engine, build a more profound data ecosystem, and support various scenarios, including precise UA optimization, user reputation assessment, and AI large-scale data training.
Looking ahead, KGeN is committed to becoming the core distribution network (Distribution Layer) of the Web3 ecosystem, continuously improving monetization capabilities, refining the ROAS calculation system, and accelerating the development and application of AI and data tools to solidify its strategic position in the next-generation internet era.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia







