DYDX v4 is about to be released: reshaping token economic models and market prospects.
Original author: OUROBOROS CAPITAL
Translated by: Deep Tide TechFlow
Our bullish view on DYDX is based on the following factors:
1) More people are buying DYDX tokens after v4, because potential validators accumulate spot tokens to obtain transaction fees for v4 tokens.
2) After decentralization is implemented in v4, there will be a significant increase in product innovation.
Additionally, in the long term, we believe the following factors will drive cost growth:
i) The validator's ability to capture MEV;
ii) Through the wider adoption of new features such as market prediction and account abstraction;
iii) The panic of centralized exchanges will drive the growth of DEX.
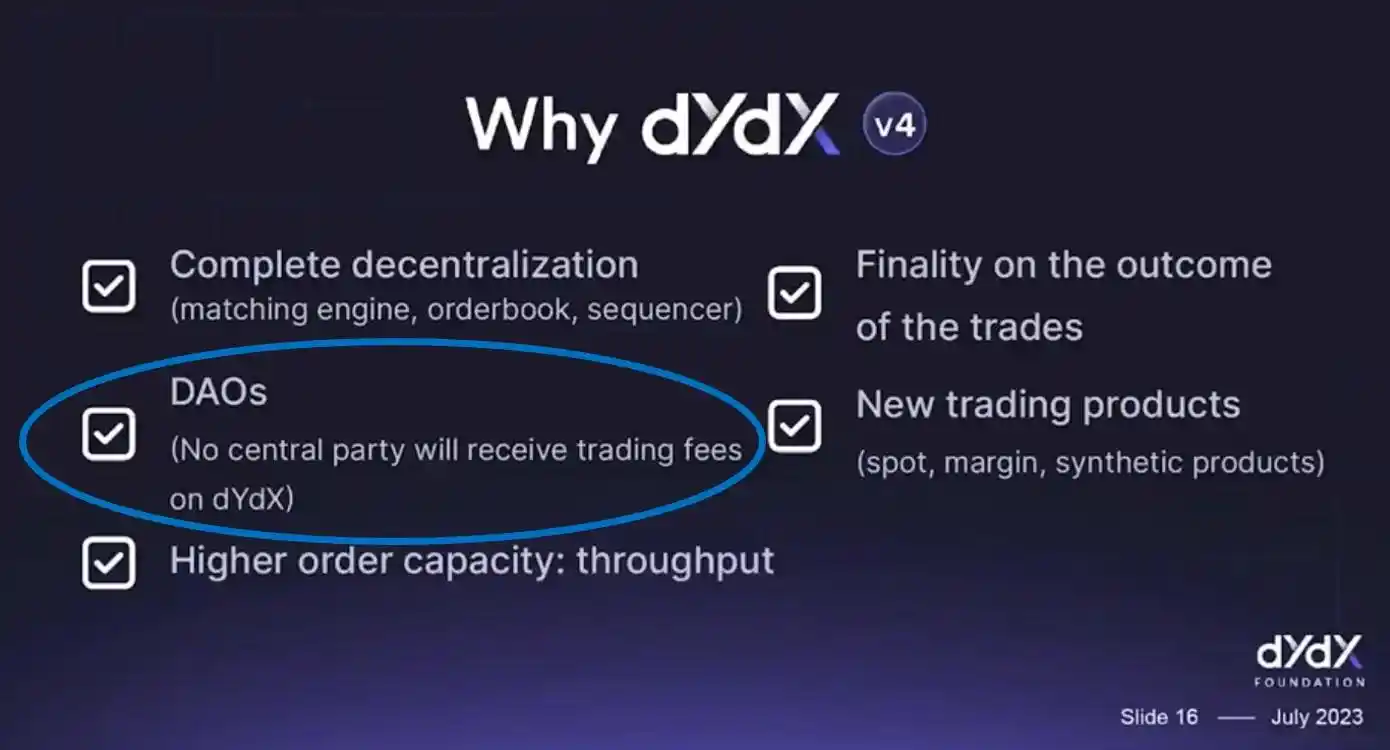
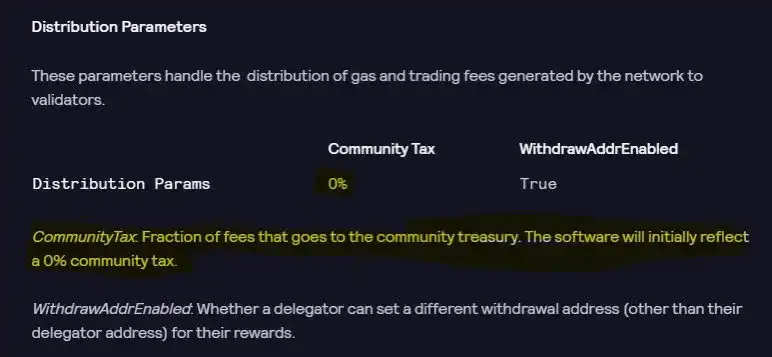
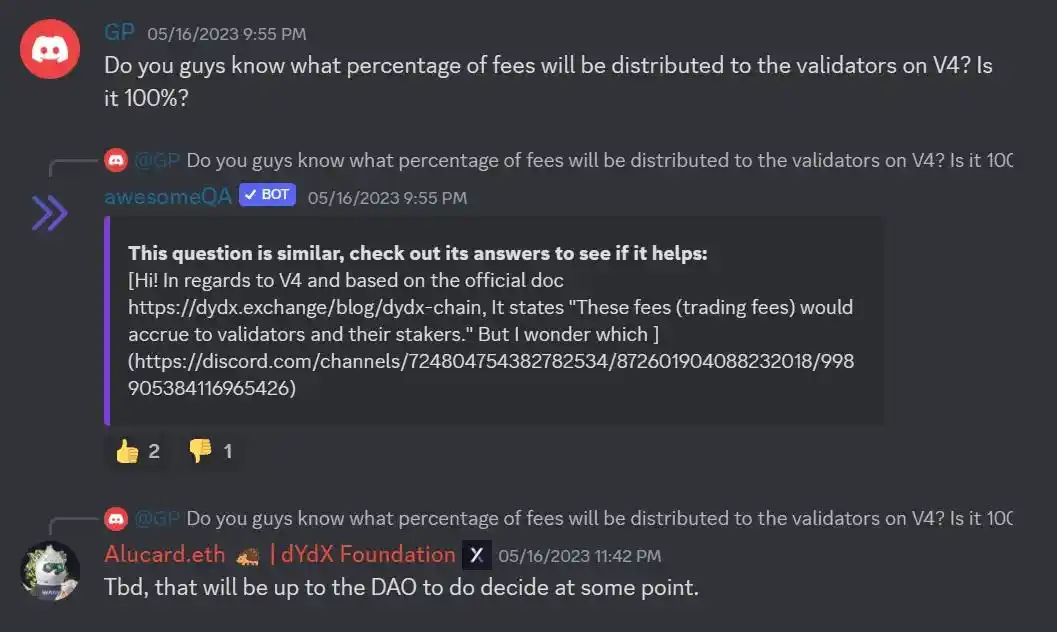
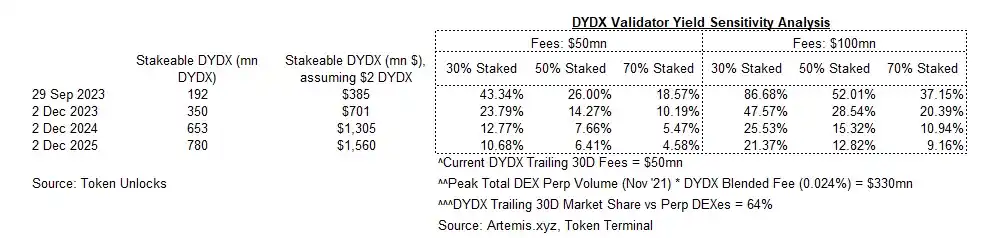
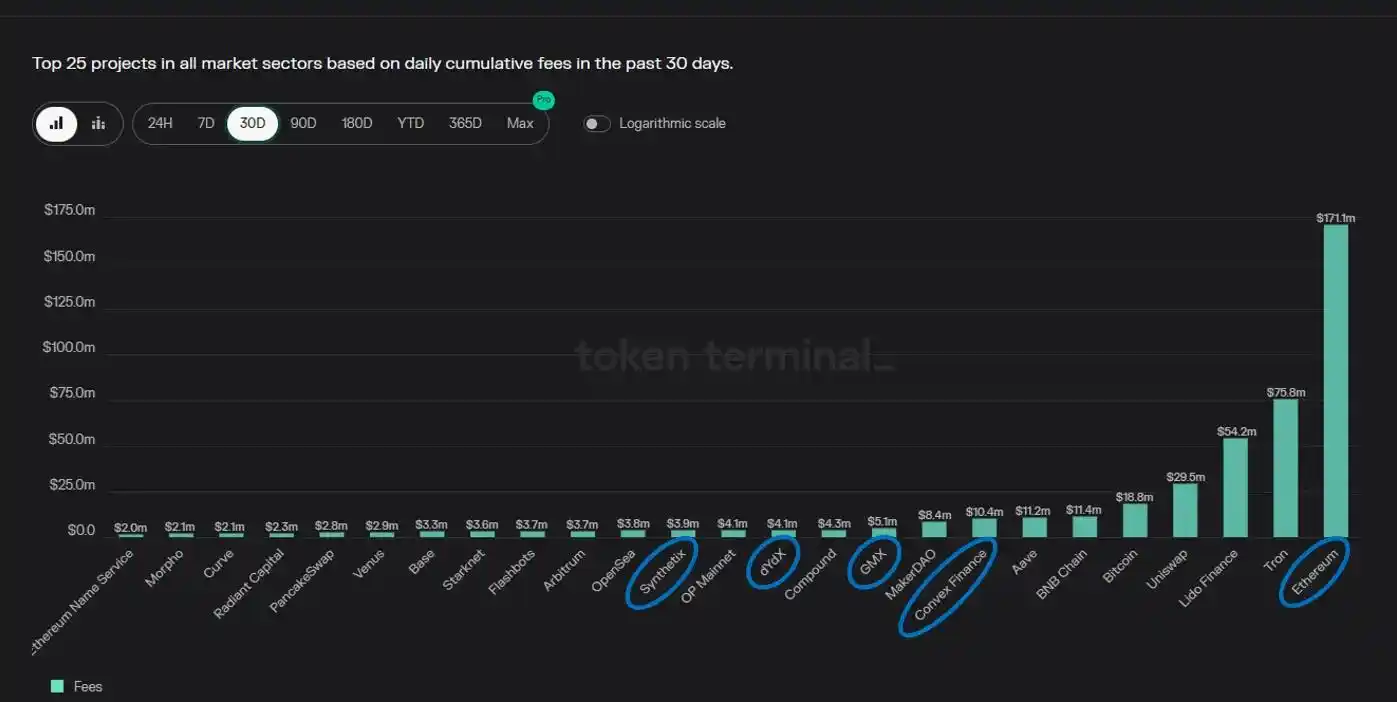
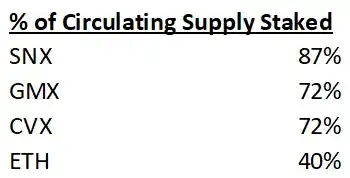
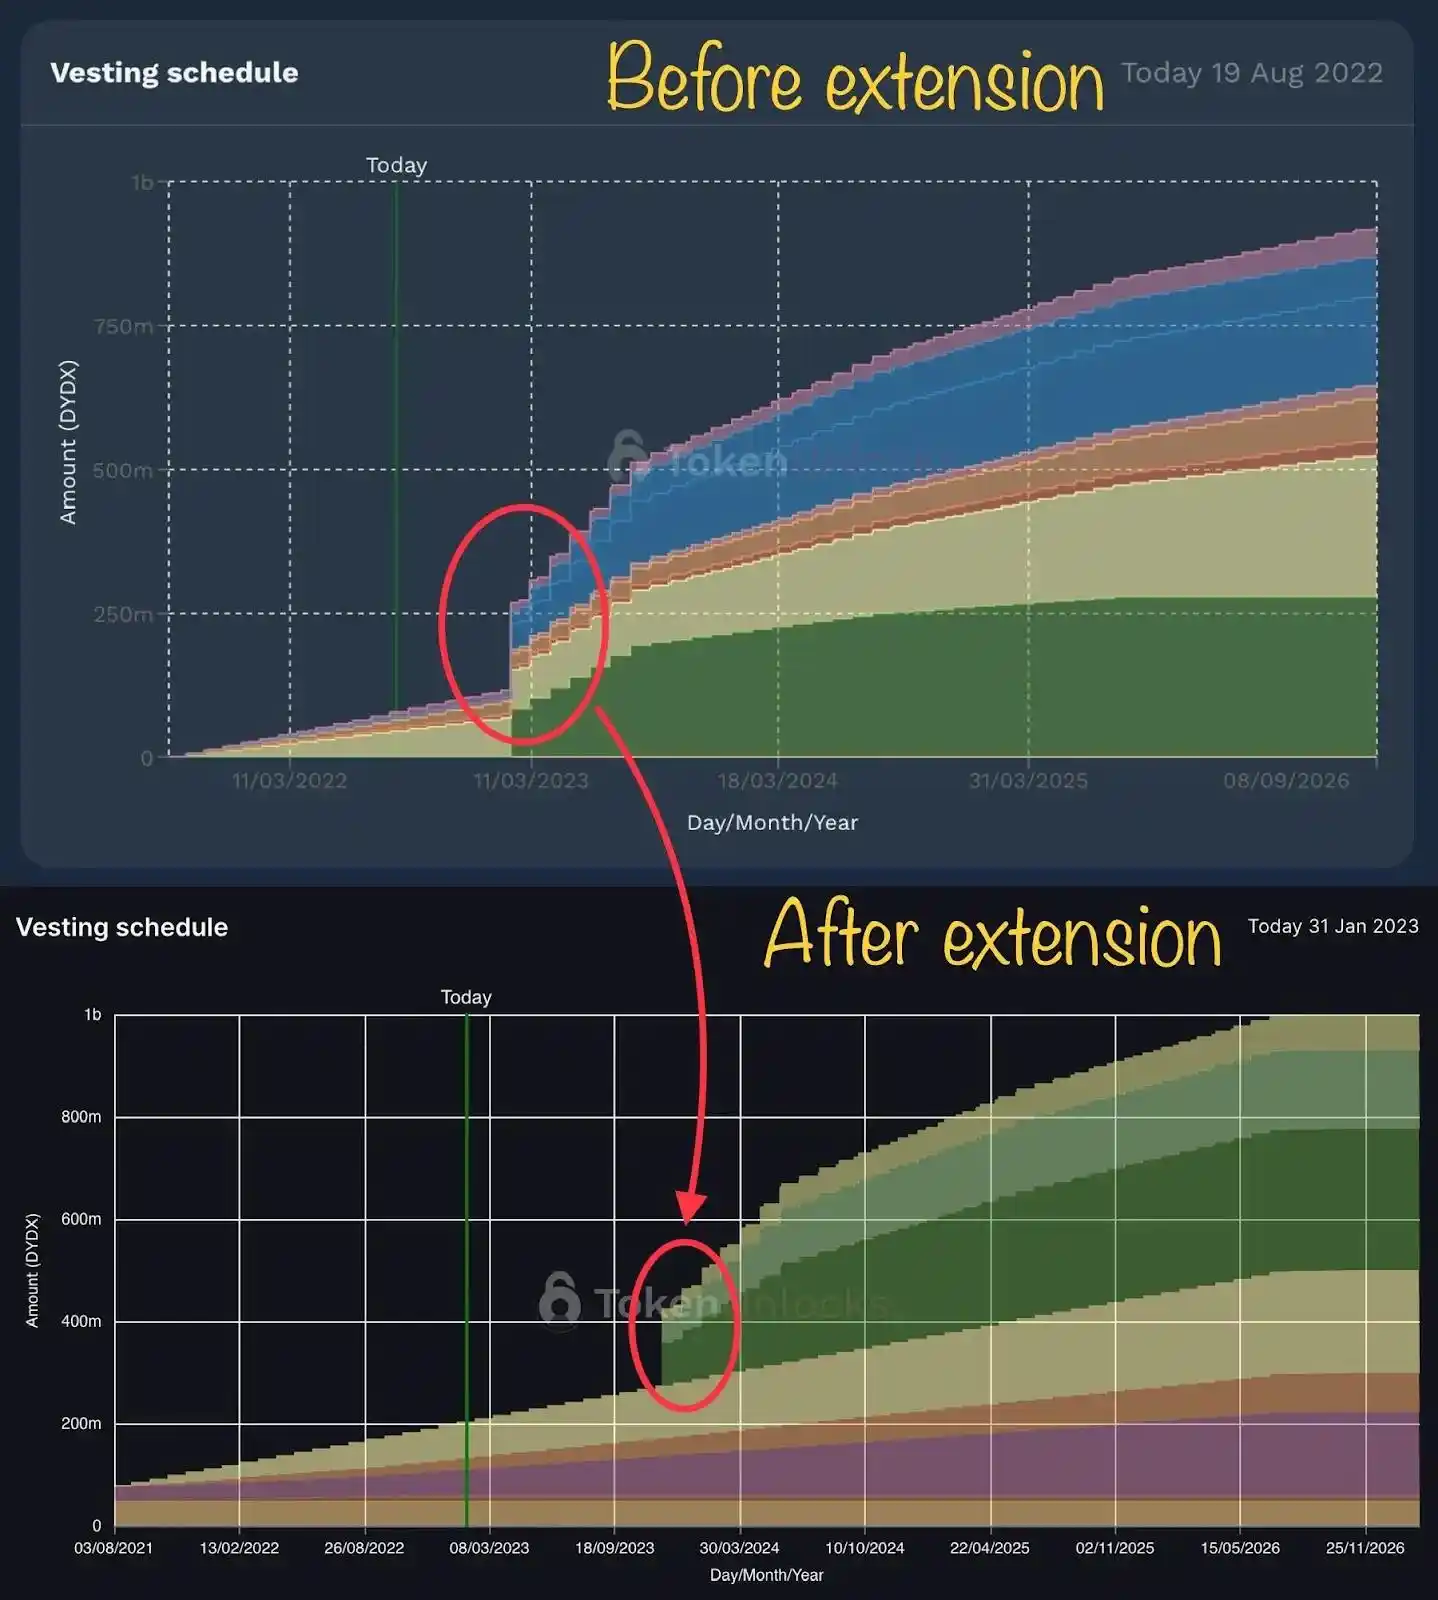
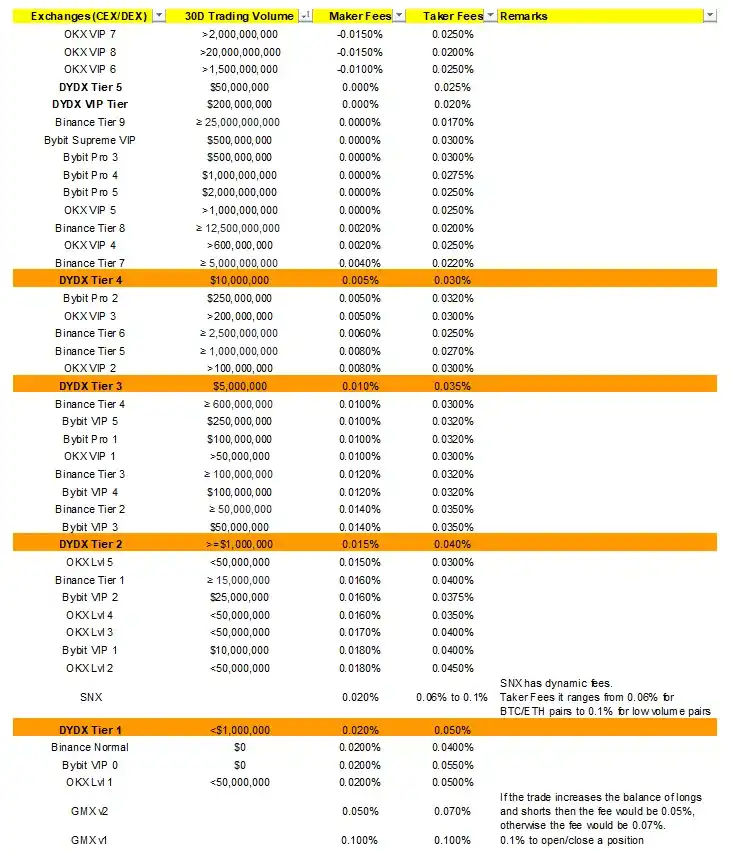
DYDX v4 will be launched at some point at the end of September. This update will fundamentally change the token economic model and further drive the market adaptability of the product. With more perpetual contracts moving from off-chain to on-chain trading, we expect DYDX to continue to perform well, with higher fees, better user experience, and even potentially becoming a complete derivatives platform, including options, prediction markets, and more. Previously, transaction fees were not accumulated for token holders, but were distributed to equity holders, effectively making the token a useless governance token. The v4 and dYdX chains will attribute transaction fees to token holders, meaning we can consider v4 as the introduction of a transaction fee switch for token holders. There are multiple indications that the DYDX token after v4 will accumulate 100% of the transaction fees. Based on the current DYDX transaction fees (50 million USD - 30-day transaction fee annualized), we estimate that the validator's staking yield will be at least 15% from day one (assuming all circulating DYDX is staked), but it is more likely to be close to 20% (assuming the staked token ratio is similar to other high transaction fee growth tokens such as SNX, GMX, and CVX). In addition, we believe that this transaction fee amount is an estimate during the low point of trading volume, and we expect trading volume to increase when speculative demand returns. Currently, the trading volume of perpetual contract decentralized exchanges is about 30% of the historical peak (February 2022). Nevertheless, considering that the penetration rate of perpetual contract decentralized exchanges is now higher and may further increase in the context of growing panic in centralized exchanges, we believe it is reasonable to assume that the annualized transaction fee can reach 100 million USD (or even higher) in a rising market. The original plan for the unlocking of investor tokens and v4 was scheduled for earlier in 2023, but was later postponed. We can clearly see that the timing of v4 has now been synchronized with the unlocking time to ensure a balance between the new supply and the demand brought by the new and improved token economic model. This section answers common misconceptions we believe exist about DYDX. The biggest concern for the token currently is the upcoming December unlock. The December unlock will increase token supply by 80% and another 80% after a year. However, we believe that the concern here is exaggerated and in fact, the team has sufficient incentives to ensure good support for the token at the time of unlocking, supporting our bullish view. Of the 150 million DYDX tokens unlocked on December 1, 2023, 30% belong to "employees and consultants." We have seen precedents of this situation before, as previous unlocks have been delayed to better synchronize with the delayed v4; it is likely to ensure a good intersection between token supply and demand after value accumulation. It is worth noting that in the "Employee and Advisor" token, 70% of the tokens will be fully unlocked on June 1, 2024, and 90% of the tokens will be fully unlocked on June 1, 2025. This provides more time for token holders to better align their interests. One common criticism is that market makers wash trade heavily to obtain rewards for traders/liquidity providers. Although in the past, the value of dYdX tokens given to traders and liquidity providers was higher than the fees, this is no longer the case. In fact, we have observed that transaction/liquidity provider rewards are gradually decreasing while transaction fees/volumes remain stable. In addition, the protocol has also made intentional efforts to reduce token rewards for traders and liquidity providers through several governance proposals, but this has not led to a decrease in trading volume. We compared the fees of DYDX with those of centralized exchanges and found that DYDX's fees are competitive and not affected by fee compression. In fact, we believe that considering the DYDX token as a reward for being a trader/liquidity provider, the fees may be considered low. From the FTX incident, we know that when CEX is surrounded by panic, perpetual DEX often gains market share and token prices perform well. Against the backdrop of increased regulation of CEX, this is an additional catalyst, and we believe it could benefit dYdX, making it a good "hedge" in a CEX panic scenario in investment portfolios. One idea that has been recently explored is that DYDX validators can earn MEV income on exchanges. We have read Chorus One's in-depth report on DYDX validators extracting MEV and are convinced that "validators can increase their income by working with trading firms to extract MEV," further enhancing the appeal of spot purchases to launch validator nodes. We believe that DYDX is an opportunity for both trading (short-term) and investment (long-term). In the short term, we expect v4 to trigger an "unlocking rally" as token fees increase and validators accumulate spot demand. In the long term, we also see it as a good core holding in a cryptocurrency investment portfolio, as it has a strong fundamental market performance in cryptocurrency bull cycles. In addition to potential share gains from new products after v4 and perpetual DEX, it also benefits from real value appreciation from speculative trading volume in the return of cryptocurrency. Welcome to join the official BlockBeats community: Telegram Subscription Group: https://t.me/theblockbeats Telegram Discussion Group: https://t.me/BlockBeats_App Official Twitter Account: https://twitter.com/BlockBeatsAsia
I am a professional in the encryption industry. Please translate the following Chinese text into English without considering the context or industry-specific terms and names. Do not omit any English words or phrases, including capitalized ones such as ZKS, STARK, and SCROLL. If there are English characters in an tag, do not translate them and return the tag as is. If the content consists only of punctuation marks, return them as is. Do not translate HTML tags such as , , , and
. If an HTML tag contains English characters, omit the translation and return the tag as is. Please preserve any content within tags. Translate all Chinese characters.
The text to be translated is:
Introduction
DYDX was launched in 2021 and caused a sensation in the market with its huge trading volume, even surpassing Coinbase at one point. At that time, the trading volume was mainly driven by incentives, and there were quite a few money laundering transactions to obtain incentives. Today, the situation is completely different. DYDX is now a top perpetual decentralized exchange, occupying about 60% of the market share (with fees often exceeding incentives).What is v4?
In short, v4 is the process of dYdX migrating to its own chain built on the Cosmos SDK. v4 was first announced in January 2022 and detailed information about the dYdX chain was subsequently released in June 2022.Investment Thesis 1: The annualized return rate for DYDX holders after v4 is approximately 20%
Investment Thesis 2: Decentralization Will Bring Innovation
We believe that the decentralization of DYDX may open up new verticals that were previously difficult to enter due to regulatory barriers, such as prediction markets, options, and synthetic products. This was also mentioned in the DYDX demo at the recent Nebular Summit.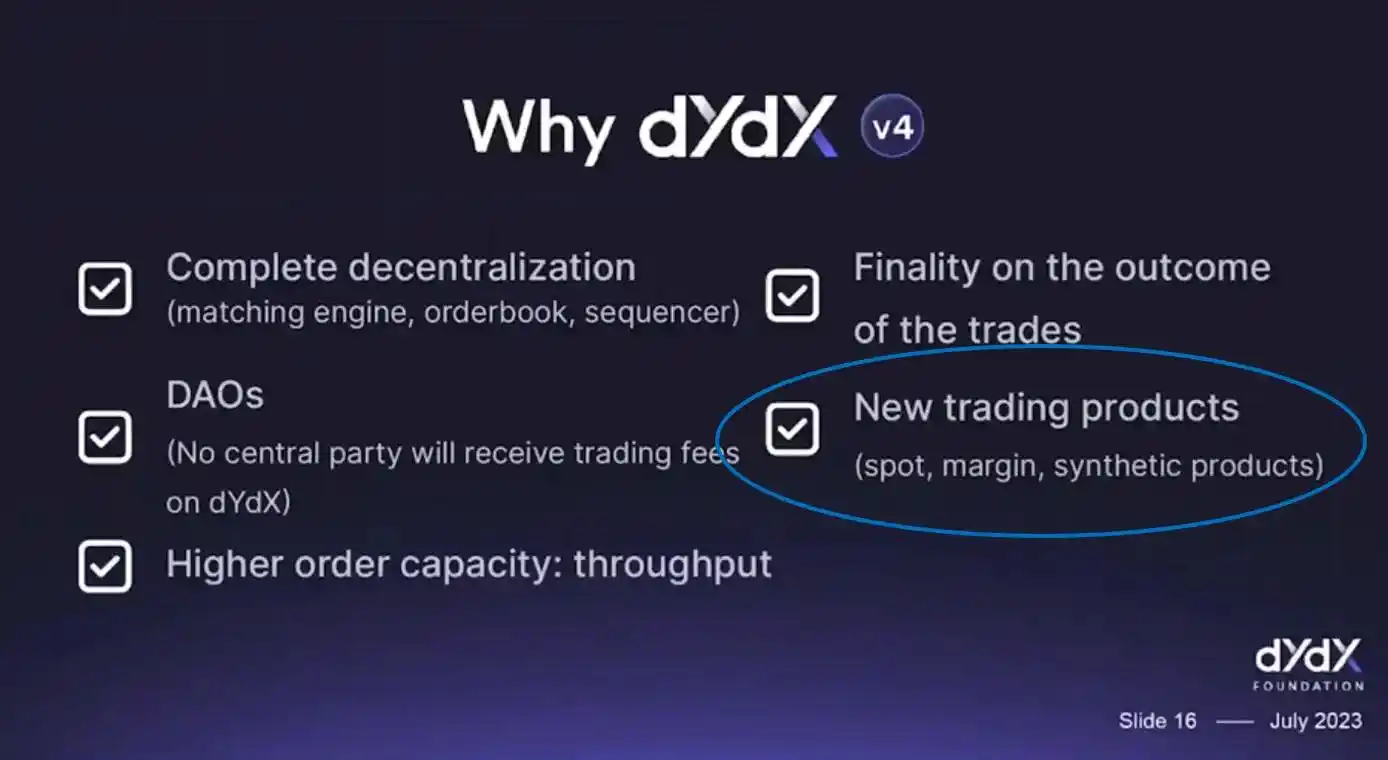
Investment Thesis 3: Bullish Unlock
Rumor Decryption
Misconception 1: There will be a large-scale unlocking in December, and tokens may be sold off

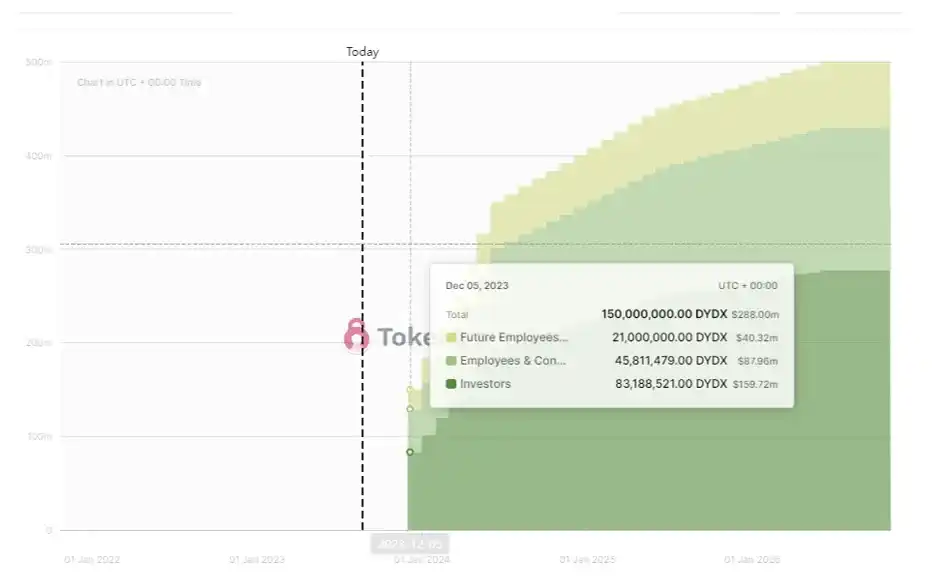
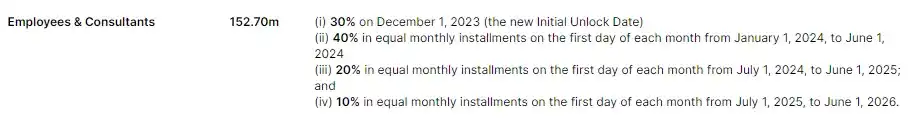
Misconception 2: The trading volume of DYDX is not real, and market makers wash trade heavily to obtain trading/liquidity provider rewards
The following table highlights the trend of DYDX net profit margin (fees minus issuance) this year, with the latest month reaching breakeven. We expect it to return to profitability after reducing liquidity provider incentives in DIP-24.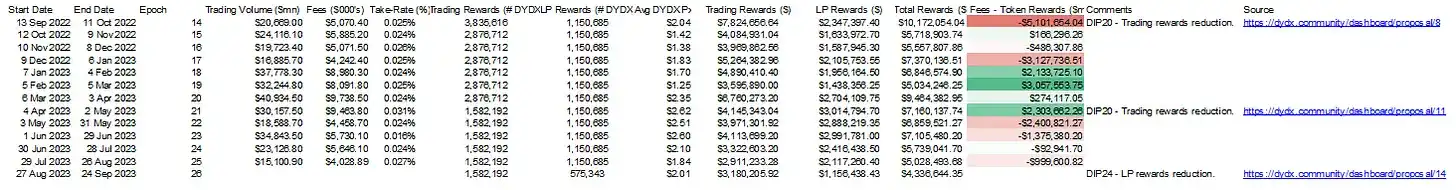
Misconception 3: The transaction fees for Perp DEX are very expensive
Catalyst 1: The loss of centralized exchanges equals the profit of decentralized exchanges (DEX)
Catalyst 2: Validator MEV in version v4
Conclusion
Original article link

 Related Articles