Decentralized Reserve Stablecoin: Historical Development and Model Analysis.
Source: Mint Venture
Impossible Triangle

Graphic: Mint Ventures
In the stablecoin field of encryption, there has always been an impossible triangle, that is, the stability of prices, decentralization, and capital efficiency cannot be achieved at the same time.
Centralized stablecoins such as USDT and USDC have the best price stability and up to 100% capital efficiency on the chain. The only issue is the risk brought by centralization. The impact of regulatory issues on BUSD's new business and the SVB incident in March this year clearly revealed this point for USDC.
The algorithmic stablecoin craze that began in the second half of 2020 attempted to achieve under-collateralization on a decentralized basis. Projects such as Empty Set Dollar and Basis Cash quickly collapsed. Luna later used the credit of the entire public chain as implicit collateral and did not require over-collateralization in the process of users minting UST. For a considerable period of time (from 2020 to May 2022), it achieved a combination of decentralization, capital efficiency, and price stability. However, it eventually collapsed due to credit issues and entered a death spiral. Projects such as Beanstalk, which also used under-collateralization, have appeared but have not attracted much attention from the market. The inability to maintain stable anchoring is the fatal flaw in the development of such tokens.
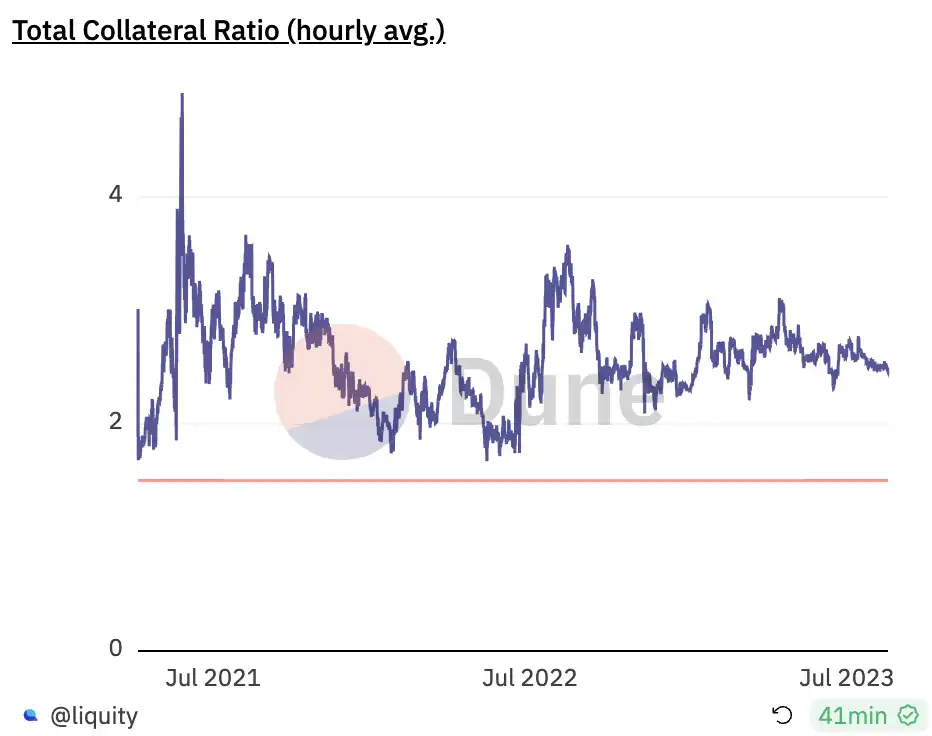
On the other hand, another approach starts with MakerDAO and hopes to achieve price stability by over-collateralizing underlying decentralized assets, sacrificing some capital efficiency. Currently, Liquity's LUSD is the largest stablecoin supported entirely by decentralized assets. However, to ensure price stability, Liquity's capital efficiency is indeed low, with the system's collateralization ratio consistently above 250%. This means that every 1 LUSD in circulation requires over 2.5 ETH worth of collateral. Synthetix's sUSD is even more extreme, with a minimum collateralization ratio typically exceeding 500% due to the greater volatility of the collateral asset SNX. Low capital efficiency means a low ceiling on scale and low attractiveness to users. Liquity's planned V2 version aims to solve the problem of low capital efficiency in V1, while Synthetix plans to introduce other assets as collateral in its planned V3 version to reduce the minimum collateralization ratio requirement.
Early DAI (before 2020) also had the problem of low capital efficiency, and because the overall market value of the cryptocurrency market was small at the time, the collateral ETH for DAI fluctuated greatly, causing DAI's price to also fluctuate greatly. To solve this problem, MakerDAO introduced the PSM (Price Stability Module) in 2020, which allows the use of centralized stablecoins such as USDC to generate DAI. DAI partially gave up decentralization in the trade-off between decentralization, capital efficiency, and price stability, which brought more stable price anchoring and higher capital efficiency to DAI, and helped DAI rapidly grow in scale along with the overall development of DeFi. FRAX, which was launched at the end of 2020, also uses centralized stablecoins as its main collateral. Currently, DAI and FRAX are the top two decentralized stablecoins in terms of circulation, which proves that their strategies are effective in providing users with stablecoins that better meet their needs, but also indirectly indicates that maintaining decentralization limits the scale of stablecoins.
However, there are still a series of stablecoins that attempt to maintain decentralization while achieving high capital efficiency and strong price stability. They all aim to provide users with such a stablecoin:
Generated by decentralized assets (such as ETH), avoiding censorship risks;
Using 1 dollar of assets can generate 1 dollar of stablecoin without over-collateralization, making it more conducive to scaling;
The value of stablecoins remains stable.
In fact, this is also the most intuitive and theoretically optimal decentralized stablecoin. We use Liquity V2 to name this type of protocol - decentralized reserve protocol to name this type of stablecoin. It should be pointed out that, unlike traditional over-collateralized stablecoins, for users, the assets used to generate stablecoins belong to the protocol after their assets are exchanged for this type of stablecoin, and are no longer associated with the user. In other words, users are more like performing an ETH -> stablecoin swap operation. This type of stablecoin is more similar to centralized stablecoins such as USDT, where $1 of assets can be exchanged for $1 of stablecoins, and vice versa. The only difference is that the decentralized reserve protocol accepts cryptocurrency assets.
(Some people may think that since the collateral does not belong to the user, stablecoins like this do not have leverage function and will lose a major use case of stablecoins. However, the author believes that stablecoins in our real life do not have leverage function, and centralized stablecoins such as USDT and USDC have never had leverage function. Settlement tools, accounting units, and value storage means are the core functions of currency, while leverage is only a special function of CDP (collateralized debt position) type stablecoins, rather than a general use case of stablecoins.)
However, the reason why previous stablecoin protocols were unable to consistently provide such stablecoins is due to a simple yet difficult-to-solve problem: decentralized asset prices fluctuate greatly, so how can they ensure the redemption of the stablecoins they issue with a 100% collateralization rate?
From the asset-liability table of stablecoin protocols, the collateral deposited by users is considered an asset, while the stablecoins issued by the protocol are considered a liability. How can we ensure that the assets will always be greater than or equal to the liabilities?
Or a more intuitive example is that when ETH = 2000U, a user sends 1 ETH to the protocol to mint 2000 stablecoins. When ETH drops to 1000U, how does the protocol ensure that these 2000 stablecoins can still be exchanged for assets worth 2000U?
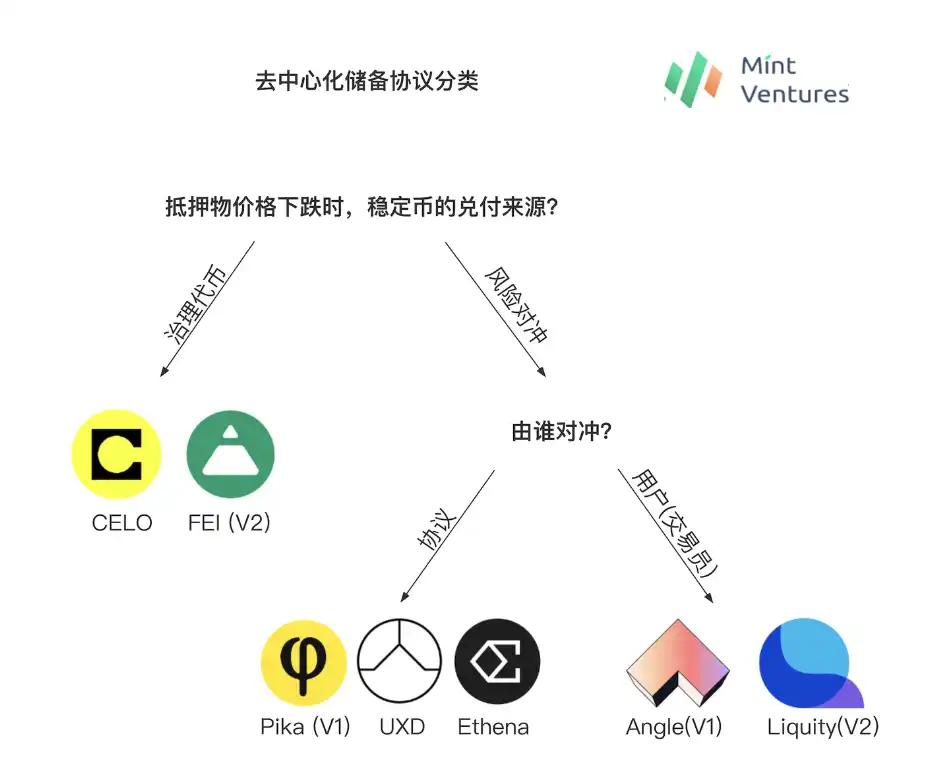
From the development history of decentralized reserve protocols, there are mainly two approaches to solving this problem: using governance tokens as reserves and hedging reserve asset risks. Based on the approach of hedging reserve asset risks, there are decentralized reserve protocols that hedge protocol risks and decentralized reserve protocols that hedge user risks. Let's learn about them one by one.
Graphics: Mint Ventures
A Decentralized Reserve Protocol with Governance Tokens as Reserves
The idea of the first type of protocol is to use the governance token of the protocol itself as the "new collateral" of the protocol. When the price of the collateral asset drops sharply, the protocol will mint more governance tokens to pay stablecoin holders. We can call it a decentralized reserve protocol with governance tokens as reserves. In the above example, when ETH drops from 2000U to 1000U, the decentralized reserve protocol with governance tokens as reserves uses 1000U worth of ETH and 1000U worth of protocol governance tokens to pay users holding 2000 stablecoins.
Protocols that adopt this approach include Celo and Fei Protocol.
Celo
Celo is a stablecoin project that was launched in 20XX. Previously, they existed as an independent L1, but in July of this year, the core team proposed to transition Celo to the Ethereum ecosystem through OP stack. The stablecoin mechanism of Celo is as follows:
Celo's stablecoin is backed by a reserve pool consisting of a comprehensive asset portfolio. The reserve ratio (the ratio of the value of reserve assets to the value of circulating stablecoins) is much higher than 1, providing the most fundamental support for the intrinsic value of its stablecoin.
Celo's stablecoin is not minted through over-collateralization, but rather obtained by sending Celo tokens to the official stable module Mento. Users can send 1 USD worth of Celo to receive 1 USD worth of cUSD stablecoin, or vice versa by sending 1 USD worth of cUSD to Mento to receive 1 USD worth of Celo. Under this mechanism, when the market price of cUSD is lower than 1 USD, someone will buy cUSD at a lower price to exchange for 1 USD worth of Celo. Similarly, when cUSD is higher than 1 USD, someone will use Celo to mint cUSD to sell, and the existence of arbitrageurs will ensure that cUSD does not deviate too far from its anchor price.
There are three mechanisms that will be used to ensure the adequacy of the reserve pool funds: 1. When the reserve ratio is below the threshold, the Celo produced by the block will be included in the reserve pool to supplement capital; 2. A certain percentage of the transfer fee can be charged to supplement capital (currently not enabled); 3. A certain stable fee will be charged in the trading module of Mento to supplement reserve capital.
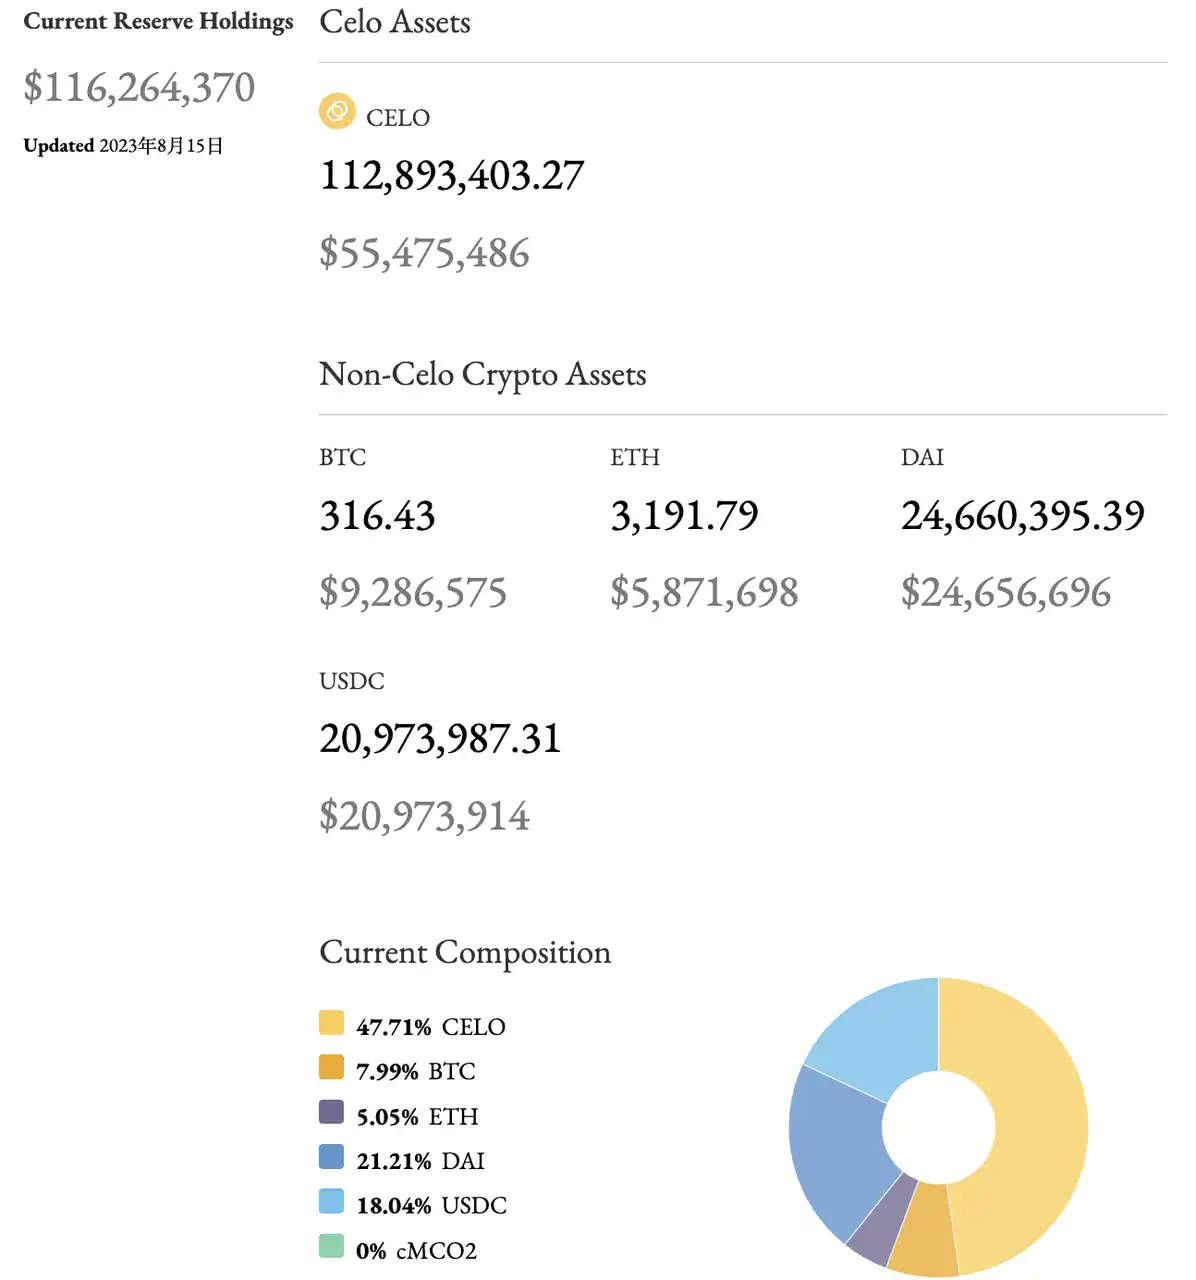
In order to improve the security of reserve funds, the asset portfolio is more diversified, currently including Celo, BTC, ETH, Dai, and carbon credit token cMCO2. This is safer than using only project tokens as collateral (similar to Terra's approach, where Luna is the implicit collateral for its native stablecoin).
Source: Mint Ventures Celo Research Report
It can be seen that Celo is similar to Luna, as it is an L1 centered around stablecoins, with similar minting and redemption mechanisms to Luna/UST. The main difference is that when the entire system enters a potential under-collateralization state, Celo will first use the $CELO produced by the blocks as collateral for the protocol, to ensure the redemption of its stablecoin cUSD.
 The content you provided is:
Source: https://reserve.mento.org/
Currently, the Celo system has a total collateral of 116 million US dollars and has issued stablecoins worth 46 million US dollars. The overall excess collateral ratio is 254%. Although the entire system is in a state of excess collateral, users who want to use its stablecoin cUSD can exchange 1 unit of CELO for 1 cUSD at any time, with excellent capital utilization. Of course, from the composition of collateral, half of Celo's collateral comes from centralized USDC and semi-centralized DAI, so it cannot be considered a completely decentralized stablecoin.
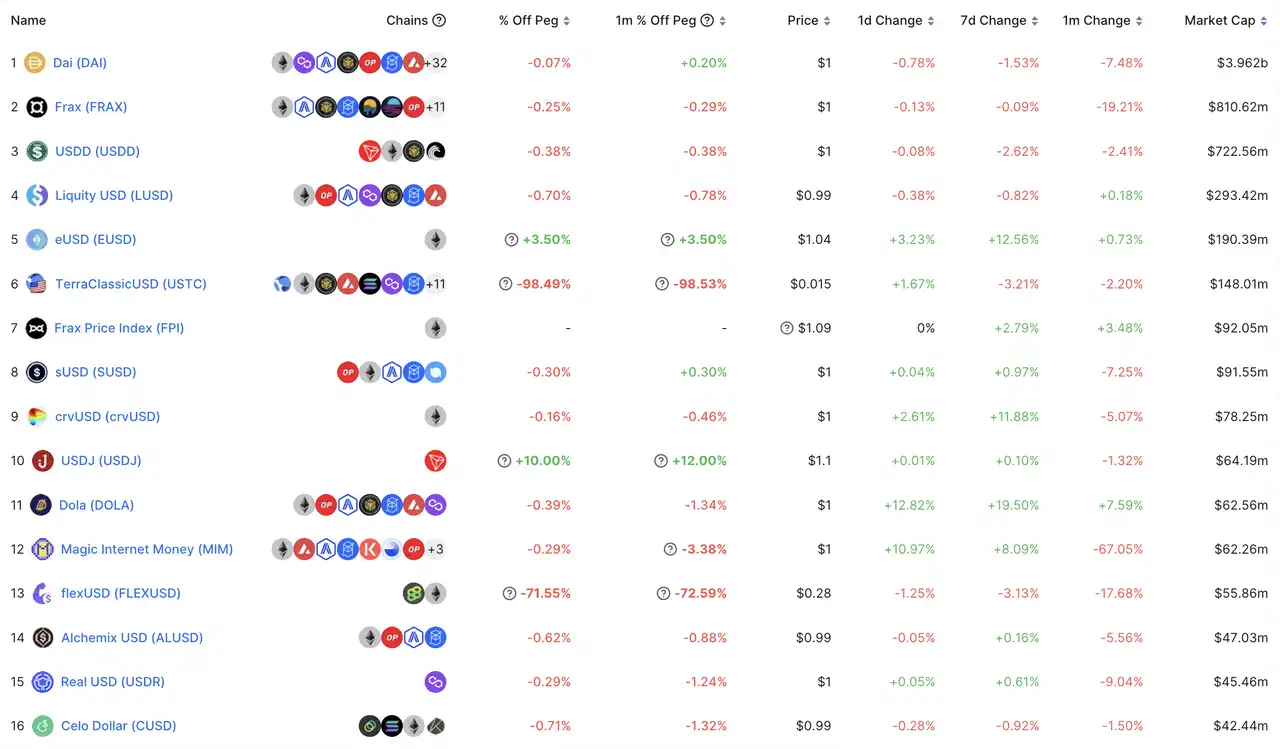
Currently, Celo's stablecoin ranks 16th among decentralized stablecoins (excluding UST, which can no longer be pegged, and flexUSD, it ranks 14th).
Source: https://defillama.com/stablecoins?backing=CRYPTOSTABLES&backing=ALGOSTABLES
Fei
Fei Protocol, which received $19 million in funding from institutions such as A16Z and Coinbase at the beginning of 2021, attracted widespread attention in the market due to its combination of the hottest algorithmic stablecoin concept at the time. In the initial stage of their project launch (end of March), they attracted 639,000 ETH for the minting of stablecoin FEI, generating a total of 1.3 billion FEI, making FEI the second largest decentralized stablecoin after DAI (with a circulating market value of $3 billion at the time).
Due to the excessive satisfaction of FEI's demand in the initial stage (users mainly for obtaining Fei Protocol's governance token TRIBE), the supply of FEI is severely excessive, and the newly launched stablecoin FEI has no application scenarios, so FEI has been trading below $1 for a long time. Soon after, it encountered market fluctuations in May, and the panic of price decline caused users to redeem FEI, leading to the protocol's decline since its launch.
In the V2 version that will be launched at the end of 2021, Fei Protocol has proposed a series of measures to try to bring the protocol development back on track, including modifying its price stabilization mechanism. In V2, FEI can be directly generated by collateral such as ETH, DAI, LUSD, etc. at a 100% collateralization rate. After generating stablecoins, users' collateral will be included in the Protocol Controlled Value (PCV). When the protocol's collateralization rate (= PCV/circulating FEI) is higher than 100%, it means that the protocol's assets are appreciating well and there is no pressure to redeem FEI. The protocol will issue a portion of FEI to purchase TRIBE, thereby reducing the collateralization rate of the protocol. Similarly, when the protocol's collateralization rate is lower than 100%, there is a possibility that the protocol may not be able to fully redeem all FEI, and the protocol will issue a portion of TRIBE to purchase FEI, thereby increasing the collateralization rate of the protocol.
Under this mechanism, the governance token TRIBE becomes a reserve fund for the entire FEI system in times of potential risk, and can also generate additional revenue during system growth (this mechanism is similar to the Float Protocol launched with Fei V1). Unfortunately, Fei V2 was launched at the peak of the entire bull market, and since then, the price of ETH has been falling all the way. Fei also suffered a hacker attack in April 2022, losing 80 million FEI, and ultimately decided to terminate protocol development in August 2022.
The decentralized reserve protocol that uses governance tokens as reserves essentially dilutes the rights of all governance token holders to ensure the redemption of stablecoins. During the bull market cycle in the market, with the increase in the scale of stablecoins, governance tokens also rise, making it easy to form a rising cycle. However, during the bear market cycle in the market, as the reserve assets on the asset side of the protocol fall, the total market value of governance tokens will also fall with the market. At this time, if more governance tokens need to be issued, their governance tokens are likely to further decline, forming a death spiral in the price of governance tokens. If the market value of governance tokens falls below a certain proportion of stablecoins, the credibility of the entire protocol's commitment to redeem stablecoins will also become unreliable in the eyes of stablecoin holders, ultimately accelerating the escape and leading to the death spiral of the entire system. Whether it can survive the bear market is the key to the survival of this type of stablecoin. In fact, the reason why Celo can maintain its survival in the current bear market is inseparable from the overall "over-collateralization" status of the protocol, and the reason why the protocol is in an over-collateralization state is also because in the previous market high, Celo relatively allocated more reserves to USDC/DAI and BTC/ETH, allowing the protocol to remain safe even as the CELO price fell from 10 to 0.5.
Decentralized Reserve Protocol for Hedging Reserve Asset Risks (Risk-Neutral Stablecoin Protocol)
The idea of the second type of protocol is to hedge the risk of these encrypted assets on the asset side of the protocol. When the price of collateral assets drops sharply, the hedge is realized to ensure that the assets of the stablecoin protocol can always repay the debt. We call this type of protocol a decentralized reserve protocol for risk hedging, or a risk-neutral stablecoin protocol. In the example above, after receiving 1 ETH worth 2000U, the decentralized reserve protocol for risk hedging will hedge this 1 ETH (such as opening a short position on the exchange). When ETH drops from 2000U to 1000U, the decentralized reserve protocol for risk hedging will use 1000U worth of ETH and 1000U worth of hedging income to redeem 2000 stablecoins held by users.
Specifically, depending on the specific hedging party, it is divided into decentralized reserve protocols for hedging risks in agreement and decentralized reserve protocols for hedging risks for users.
Decentralized Reserve Protocol for Hedging Risks in Agreements
The stablecoin protocols that adopt this approach include Pika Protocol V1, UXD Protocol, and Ethena, which recently announced financing.
Pika V1
Pika Protocol is currently a derivative protocol deployed on the Optimism network. However, in its initial V1 version, Pika had planned to launch a stablecoin, which was hedged through Bitmex's inverse perpetual contract. Inverse perpetual contracts (also known as coin-margined perpetual contracts) are also one of Bitmex's inventions. Compared to the more popular "linear perpetual contracts" that track the price of coins in U.S. dollars, the characteristics of inverse perpetual contracts are to track the price of coins in their own denomination and in U.S. dollars. The profit example of an inverse perpetual contract is as follows:
A trader goes long 50,000 contracts of XBTUSD at a price of 10,000. A few days later the price of the contract increases to 11,000.
A trader went long on 50,000 XBTUSD contracts at a price of 10,000. A few days later, the contract price rose to 11,000.
The trader』s profit will be: 50,000 * 1 * (1/10,000 - 1/11,000) = 0.4545 XBT
The profit of the trader will be: 50,000 * 1 * (1/10,000 - 1/11,000) = 0.4545 XBT.
If the price had in fact dropped to 9,000, the trader』s loss would have been: 50,000 * 1 * (1/10,000 - 1/9,000) = -0.5556 XBT. The loss is greater because of the inverse and non-linear nature of the contract. Conversely, if the trader was short then the trader』s profit would be greater if the price moved down than the loss if it moved up.
If the price actually falls to 9,000, the trader's loss will be: 50,000 * 1 * (1/10,000 - 1/9,000) = -0.5556 XBT. Due to the inverse and non-linear nature of the contract, the loss is even greater. On the other hand, if the trader goes short, then if the price falls, the trader's profit will be greater than the loss when the price rises.
Source: https://www.bitmex.com/app/inversePerpetualsGuide
With a little analysis, it is not difficult to find that the decentralized reserve protocol for hedging the risk of reserve assets with reverse perpetual contracts is a perfect match. Using the example mentioned above, suppose that when ETH = 2000U, Pika Protocol receives 1 ETH from a user and uses 1 ETH as margin to short 2000 ETH reverse perpetual contracts on Bitmex. When the ETH price drops to 1000U, Pika Protocol's profit = 2000 * 1 * (1/1000-1/2000) = 1 ETH = 1000U. That is to say, when the ETH price drops from 2000U to 1000U, Pika Protocol's reserve changes from 1 ETH to 2 ETH, and it can still effectively redeem the 2000 stablecoins in users' hands (without considering transaction fees and funding costs). The product design of Pika Protocol V1 is exactly the same as that of NUSD mentioned in Arthur Hayes' blog post, which can always perfectly hedge the long position of coin standard.
Unfortunately, inverse perpetual contracts have non-linear characteristics in terms of inverse and returns for the vast majority of cryptocurrency investors who use USDT as their base currency (the relationship between the base currency's price fluctuations and the contract's price fluctuations is not linear), and are not very easy for ordinary users to understand. In the subsequent development process, the development of inverse perpetual contracts (coin-based perpetual contracts) is far less popular than that of linear perpetual contracts (U-based perpetual contracts). In mainstream exchanges, the trading volume of inverse perpetual contracts is only about 20-25% of that of linear perpetual contracts. BitMex, which has been affected by regulations, has gradually degraded from a first-tier contract exchange to a state where its market share is less than 0.5%. Pika believes that linear perpetual contracts cannot meet their hedging needs, while the market space for inverse perpetual contracts is relatively small. In its V2 version, Pika Protocol officially turned to derivatives exchanges and cut off stablecoin business.
UXD
UXD Protocol is a stablecoin protocol running on the Solana network, which was launched in January 2022. In 2021, UXD completed a $3 million financing led by Multicoin and raised $57 million in IDO. In January of this year, UXD decided to cross-chain into the Ethereum ecosystem and has already launched on Arbirturm in April, with plans to launch on Optimism in the future.
At the time of launch, UXD Protocol supported users to deposit SOL, BTC, and ETH to mint its stablecoin UXD at a 1:1 ratio with USD value. The collateral deposited by users will be hedged through short positions on Mango Markets, a lending and perpetual contract trading platform on Solana, to achieve redemption of the stablecoin. The funding fees collected from short positions will be the protocol's income, and the funding fees paid will be covered by the funds raised by the protocol. For a considerable period after the launch, the UXD protocol operated smoothly, and the protocol even needed to limit the issuance of UXD because the overall open position of Mango Markets was below the level of one billion US dollars. If the short position of UXD reaches tens of millions of US dollars, there is a potential risk of default. In addition, too many short positions will make the funding rate more inclined to become negative, thereby increasing the hedging cost.
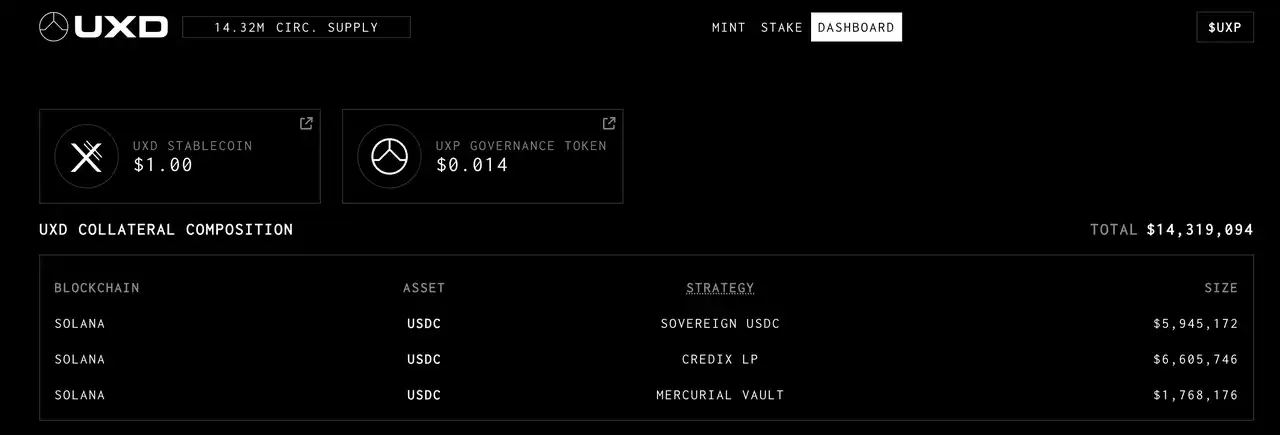
Unfortunately, Mango Markets suffered a governance attack in October 2022, causing UXD to lose nearly $20 million. At the time, UXD's insurance fund balance was still over $55 million, so UXD was able to receive normal payouts. Although Mango Markets later returned the funds to the UXD protocol, Mango Markets has since struggled and the FTX thunderbolt event caused funds to quickly flow out of Solana, making it difficult for UXD to find a suitable exchange to hedge their long positions. Afterward, the collateral supported by the UXD protocol was only USDC, and USDC did not need to hedge risks, so they invested users' collateral USDC in various on-chain USDC vaults and RWA. It was also after this that UXD decided to cross-chain into the Ethereum ecosystem and has already launched Arbirturm in April, with plans to launch Optimism in the future. They are also continuing to search for suitable on-chain hedging venues.
Currently, the circulation of UXD is 14.3 million US dollars, and the balance of the protocol insurance fund is 53.2 million US dollars.
Source: https://dashboard.uxd.fi/
In addition, the stablecoin protocol Ethena Finance, which recently announced financing, will also use risk hedging to hedge its reserve assets. Ethena Finance has received a $6 million investment led by Dragonfly, with participation from centralized exchanges such as Bybit, OKX, Deribit, Gemini, and Huobi. Ethena's financing institutions include many second-tier derivative exchanges, which will be helpful for its collateral hedging. In addition, Ethena also plans to cooperate with the decentralized derivative protocol Synthetix, allowing Synthetix to open short positions as a liquidity provider and bring more use cases to its stablecoin USDe (allowing USDe to be used as collateral for certain pools).
For decentralized reserve protocols that hedge against protocol hedging risks, the advantages are obvious. By hedging the encrypted assets of collateral, the protocol can obtain a risk-neutral position overall, thereby ensuring the redemption of stablecoins and ultimately achieving 100% capital efficiency on a decentralized basis (mainly depending on the hedging venue). At the same time, if the protocol can complete position hedging through a high capital efficiency method, the collateral reserves owned by the protocol can also generate interest in many forms. In addition, the funding rate can be used as protocol income, giving the protocol more room for maneuvering: these profits can be distributed to stablecoin holders to create interest-bearing stablecoins and give stablecoins more use cases; they can also be distributed to governance token holders.
In fact, any governance token of a stablecoin protocol has an implicit use case as the "lender of last resort" for its stablecoin. A stablecoin protocol that hedges against reserve asset risk can also use its governance token as a source of redemption for its stablecoin in extreme cases. For stablecoin holders, holding this type of stablecoin provides an extra layer of security compared to a stablecoin backed solely by governance tokens. Mechanically speaking, the logic of hedging against reserve asset risk is more self-consistent and theoretically immune to market cycles, without the need to test the governance token's ability to withstand market downturns during bear markets.
However, there are also many limitations to the development:
Centralized risks in hedging venues. Currently, centralized exchanges still account for the majority of liquidity in perpetual contracts, and the design of most decentralized derivative exchanges is not suitable for stablecoin protocol hedging, inevitably exposing the protocol to centralized risks. These centralized risks may be divided into two categories: 1) inherent risks of centralized exchanges themselves; 2) due to the small total amount of hedging venues, a single hedging venue will inevitably occupy a larger proportion of the protocol's hedging position. If a hedging venue encounters problems, it will also have a significant impact on the protocol. The UXD Protocol suffered losses and stopped operating due to the attack on Mango Markets, which is an extreme example of this centralized risk.
There are certain limitations when it comes to selecting hedging tools. Currently, the mainstream way of linear perpetual contract does not perfectly hedge their long positions. Taking ETH as an example, stablecoin protocols require ETH collateral and ETH-based short positions for hedging. However, the largest trading volume of linear perpetual contracts requires USDT collateral, and its short profit curve is also based on USD, which cannot perfectly hedge the ETH position. Even if stablecoin protocols use ETH to obtain USDT through some kind of borrowing, this will increase operational costs and the difficulty of risk management, while also reducing capital efficiency. From the example of Pika Protocol mentioned above, we know that reverse perpetual contracts are the perfect choice for decentralized reserve protocols that attempt to hedge reserve asset risks, but unfortunately, the market share of reverse perpetual contracts is not large enough.
The growth of scale has certain self-limitation. The stablecoin scale growth of the agreement means that there needs to be persistent and sufficient perpetual contract short positions for hedging. In addition to the complexity of obtaining sufficient short positions, the more short positions the protocol itself holds, the higher the liquidity requirement for the counterparty when closing positions, and the funding rate is more likely to be negative. All of this means potential higher hedging costs and operational difficulties. For stablecoins with a scale of tens of millions of dollars, this may not be a big problem, but if you want to further expand the scale to hundreds of millions or even tens of billions, this issue will significantly limit its ceiling.
Operational risk. Regardless of the form of hedging, it will involve high-frequency opening, adjustment, and collateral management operations. These processes inevitably require manual intervention, which can create significant operational and even moral risks.
User Decentralized Reserve Protocol for Hedging Risks
Protocols that adopt this approach include Angle Protocol V1 and Liquity V2.
Angle V1
Angle Protocol launched on the Ethereum network in November 2021. Prior to this, they had received a $5 million financing led by a16z.
Regarding the protocol design of Angle Protocol V1, readers can visit Mint Ventures' previous research report for more information. Here, we provide a brief summary:
Like other decentralized reserve protocols, Angle supports users to generate 1 agUSD stablecoin using 1U ETH in an ideal state (of course, the first stablecoin launched by Angle is agEUR anchored to the euro, but the logic is the same. For the sake of context, we still use the example of a USD stablecoin). What sets Angle apart is that its target users include not only traditional stablecoin demanders, but also perpetual contract traders, which Angle refers to as HA (Hedging Agency).
Still using the example we mentioned earlier, when ETH = 2000U, a user sent 1 ETH to Angle and minted 2000 USD stablecoins. At this point, Angle will open a leverage position worth 1 ETH for traders to open. Let's assume that HA uses 0.2 ETH (worth 400U) as collateral and opens a 5x leverage position. At this time, the protocol has a total of 1.2 ETH collateral, worth 2400U, and a total of 2000U stablecoins on the liability side.
When ETH rises to 2200U, the protocol only needs to retain 0.909 ETH that can be redeemed for 2000U stablecoin, and the remaining 0.291 ETH (worth 640U) can be extracted by HA.
When ETH drops to 1800 U, the protocol still needs to hold ETH that can be redeemed for 2000U stablecoins, which is 1.111 ETH. At this point, the margin position of HA will become 0.089 ETH (worth 160U).
It can be seen that traders are essentially going long on ETH in a coin-based manner. When the price of ETH rises, they not only benefit from the increase in the value of ETH itself, but also from the "surplus" ETH of the protocol (in the above example, the trader earns 60% when the price of ETH rises by 10%); when the price of ETH falls, they not only need to bear the decline in the value of ETH itself, but also the decline in the collateralized ETH of the protocol (in the above example, the trader loses 60% when the price of ETH falls by 10%). From the perspective of Angle Protocol, traders hedge the risk of collateral price decline for the protocol, which is also the origin of their name "hedge agents". The long leverage ratio of traders depends on the ratio between the open hedging position (0.2 ETH in the above example) and the stablecoin position (1 ETH in the above example) opened by the protocol.
For perpetual contract traders, using Angle to go long on perpetual contracts has certain advantages: 1) they do not need to pay funding fees (centralized exchanges usually require longs to pay funding fees to shorts), and 2) the trading price is directly based on the oracle price without slippage. Angle hopes to achieve a win-win situation for stablecoin holders and perpetual contract traders: stablecoin holders can obtain high capital efficiency and decentralization, while contract traders can also have a better trading experience. Of course, this is only an ideal situation. In reality, there may be situations where there are no traders opening long positions. Angle introduces Standard Liquidity Providers (SLPs) to provide additional collateral (stablecoins) to ensure the safety of the protocol, while automatically earning interest, trading fees, and governance token $ANGLE rewards.
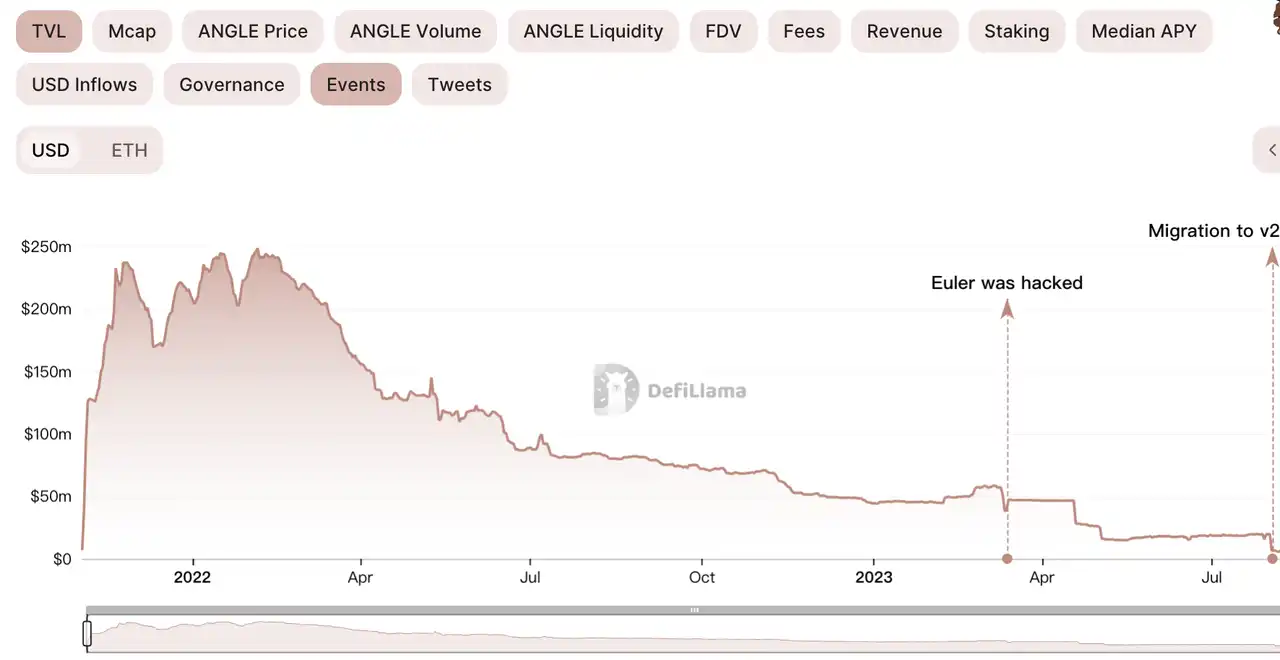
The actual operation of Angle is not ideal. Although traders have a considerable amount of $ANGLE as a reward, most of the time, the collateral of the protocol is not fully hedged. The core reason, in my opinion, is that Angle has not provided a product attractive enough to traders. With the decline in the price of $ANGLE tokens, the protocol's TVL has also fallen from the initial $250 million to around $50 million.
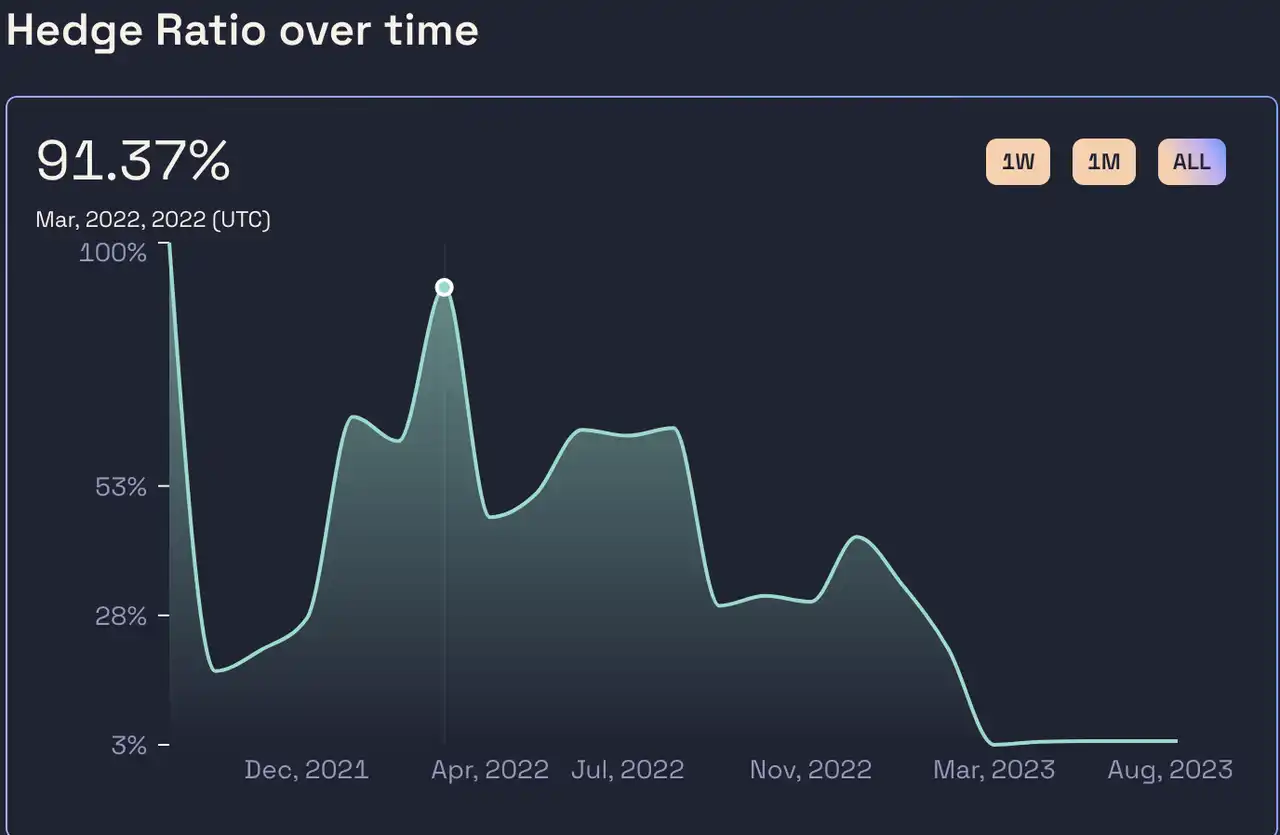
Angle stablecoin's main collateral source - the hedging ratio of the USDC pool / source: https://analytics.angle.money/core/EUR/USDC
Source: https://defillama.com/protocol/angle
In March 2023, Angle's reserve assets for staking unfortunately suffered a hacker attack by Euler. Although the hacker eventually returned the corresponding assets, Angle was severely damaged. In May, Angle announced the end of the above-mentioned product logic, which they called Angle Protocol V1, and launched the plan for V2. Angle Protocol V2 changed to a traditional over-collateralization model and was just launched in early August.
Liquity V2
Since its launch in March 2021, Liquity's LUSD has become the third largest decentralized stablecoin in the market (after DAI and FRAX), and the largest fully decentralized stablecoin. We have published research reports on Liquity V1's mechanism and subsequent product updates and use case expansions in July 2021 and April 2023, respectively. Interested readers can learn more by visiting here and here.
The Liquity team believes that LUSD has achieved a relatively good level in terms of decentralization and price stability. However, in terms of capital efficiency, Liquity's performance is relatively average. Since its launch, Liquity's system collateralization rate has remained around 250%, which means that every circulating LUSD requires 2.5U worth of ETH as collateral.
Source: https://dune.com/liquity/liquity
Liquity officially introduced its V2 features on July 28th. The core content, besides supporting LSD as collateral, mainly claims to achieve high capital efficiency through delta-neutral hedging across the entire protocol.
Currently, Liquity has not publicly released specific product documentation. The current public information about V2 mainly comes from founder Robert Lauko's speech at ETHCC, the introduction article previously released by Liquity, and discussions in Discord. In the following text, we will mainly organize based on the above information.
Regarding product logic, Liquity V2 is similar to Angle V1. The hope is to introduce traders to conduct leveraged trading on Liquity, using their margin as additional collateral for the protocol, and hedging the risks of the entire protocol through traders. At the same time, Liquity provides attractive trading products for traders.
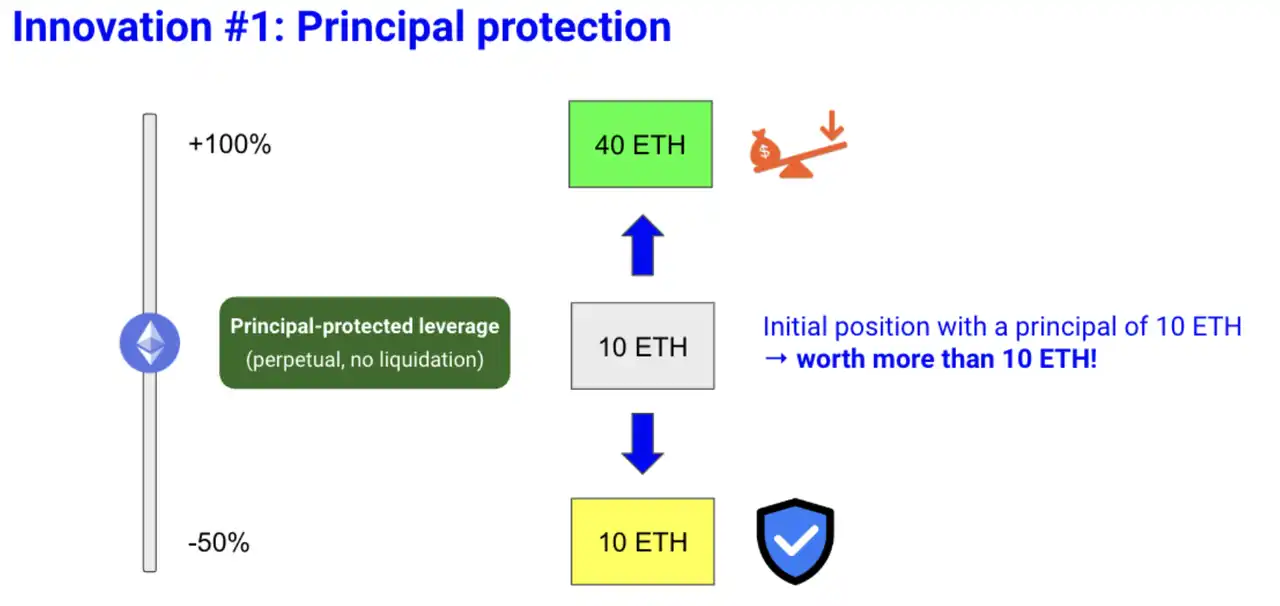
Specifically, Liquity proposes two innovations. The first is the so-called "capital-protected leveraged trading". Liquity will provide contract traders with a leveraged trading product that protects their capital. After paying a certain premium, users can use this feature, which allows them to recover a certain amount of U even if ETH falls sharply. According to the example in the Liquity article, when the ETH price is 1000U, users pay 12ETH (10ETH principal and 2ETH premium) to obtain a 2x leveraged long position with downside protection. That is to say, when the ETH price doubles, the 2x leveraged long position takes effect, and the user gains a total of 40ETH due to the rise. When the ETH price falls, the purchased put option takes effect, and the user can withdraw their original 10,000U (10*1000) at any time.
Source: https://www.liquity.org/blog/introducing-liquity-v2
It can be seen that Liquity's product innovation is mainly based on Angle, and the main feature is the "capital protection" function. Although Liquity did not explain the implementation method, according to the product form and discussions in Discord, this "capital protection" function is similar to a call option.
Liquity believes that this combination product may be more attractive to traders because it can protect their principal. Call options can allow traders to leverage their gains when prices rise, while also ensuring their principal when prices fall. From a trader's perspective, this may be more attractive than Angle's simple leverage trading product (although it also depends on Liquity's pricing of the premiums). From the protocol's perspective, the premiums paid by users can serve as a safety cushion: when the price of ETH falls, Liquity can use these premiums as additional collateral to redeem stablecoin holders; when the price rises, Liquity can distribute the appreciation of its own collateral to contract traders as profits.
Of course, there are obvious problems with this mechanism. When traders want to close their positions and retrieve their ETH midway, Liquity will face a dilemma: traders have the right to close their positions at any time, but if they do so, the proportion of the entire Liquity protocol position that is hedged will decrease, and the security of the Liquity protocol will become vulnerable as this part of the "collateral" is withdrawn. In fact, the same problem has occurred in the operation of Angle, where the hedging ratio of Angle's system has remained at a low level for years, and traders have not fully hedged the overall position of the protocol.
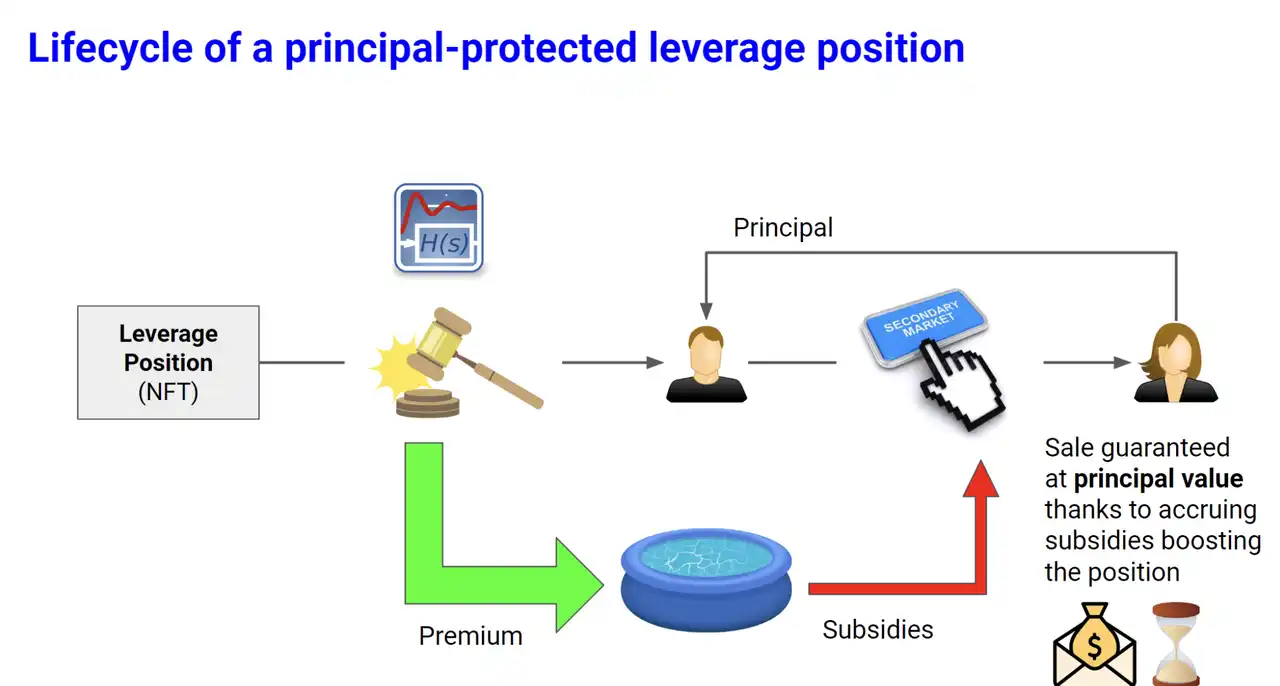
In order to solve this problem, Liquity proposed the second innovation, the official subsidy of the secondary market.
That is to say, in the leveraged trading position (NFT) within Liquity V2, in addition to opening and closing positions like normal leveraged trading positions, they can also be sold on the secondary market. In fact, Liquity is concerned that traders will close their positions, as this will reduce the protocol's hedging ratio. When a trader wants to close a position, if other traders are willing to buy at a price higher than the current intrinsic value of the position on the secondary market, they can naturally earn more cash. For Liquity, although the "current intrinsic value of the position" is subsidized by the protocol, maintaining the hedging ratio of the entire system through a relatively small subsidy can improve the security of the protocol at a lower cost.
Source: https://www.liquity.org/blog/introducing-liquity-v2
(Note: This content contains HTML tags and English characters, which will not be translated. The content within the a tag will be preserved.)
For example, Alice opened a position of 10 ETH with a premium of 2 ETH when the ETH price was 1000U. This position corresponds to the value of 10 ETH long + principal protection. However, when ETH drops to 800U, the value of the 12,000U worth of ETH invested by Alice can only be exchanged for 10 ETH (8000U) at present. At this time, in addition to directly closing the position to obtain 10 ETH (8000U), Alice can also sell her position in the secondary market at a price between 8000U-12000U. For Bob who wants to buy Alice's position, buying Alice's position is similar to buying a call option (8000U + a strike price of 1000U) when ETH is at 800U. This option must have value, so this also determines that the price of Alice's position must be higher than 8000U. For Liquity, as long as Bob buys Alice's position, the protocol's collateralization ratio will not change because the premium collected by the protocol is still in the protocol's funding pool. If Bob does not buy Alice's position for a long time, the Liquity protocol will gradually increase the value of Alice's position with the passage of time (the specific form is not specified, but for example, reducing the strike price or increasing the number of call options can increase the value of this position), and the subsidized part comes from the protocol's premium pool (note that this situation will slightly reduce the overall excess collateralization ratio of Liquity). Liquity believes that not all positions need to be subsidized by the protocol, and the subsidy does not necessarily need to be a large proportion of the income of this position, so subsidizing the secondary market can effectively maintain the protocol's hedging ratio.
Finally, even with these two innovations, there may still be no way to completely solve the problem of illiquidity in extreme situations. Liquity will also use a standard liquidity provider mechanism similar to Angle as a last resort (possibly allowing users to deposit some V1 LUSD into the stable pool to support the redemption of V2 LUSD in extreme situations).
Liquity V2 is scheduled to launch in Q2 2024.
Overall, Liquity V2 has many similarities with Angle V1, but it also makes targeted improvements based on the issues encountered by Angle: it proposes the innovation of "capital protection" to provide more attractive products for traders; it proposes an "officially subsidized secondary market" to protect the overall hedging ratio of the protocol.
However, Liquity V2 is essentially the same as Angle Protocol, where the stablecoin team attempts to create an innovative derivative product and support their stablecoin business. The Liquity team has already proven their ability in the stablecoin field, but it remains uncertain whether they can also design excellent derivatives, find PMF (Product Market Fit), and successfully promote them.
Conclusion
A decentralized reserve protocol that can achieve decentralization, high capital efficiency, and price stability at the same time is undoubtedly exciting, but the ingenious and reasonable mechanism design is only the first step of stablecoin protocol. What is more important is to look at the expansion of stablecoin use cases. Currently, decentralized stablecoins are progressing slowly in terms of use case expansion, and the vast majority of decentralized stablecoins only have one real use case, which is "mining tools", and the incentive for mining is not inexhaustible.
To some extent, the issuance of PYUSD by Paypal is a warning for all stablecoin projects, as it means that well-known institutions in the web2 field are beginning to enter the stablecoin field, and the time window left for stablecoins may not be too long. In fact, when we talk about the centralization risk of custodial stablecoins, we are more concerned about the risks brought by unreliable custodians and issuers (Silicon Valley Bank is only the 16th largest bank in the United States, and Tether and Circle are only "crypto-native" financial institutions). If there are really "too big to fail" financial institutions in the traditional financial industry (such as JP Morgan) issuing stablecoins, the national credit behind them will not only make Tether and Circle lose their foothold instantly, but also greatly weaken the decentralized value advocated by decentralized stablecoins: when centralized services are stable and powerful enough, people may not need decentralization at all.
Before that, we hope to have a decentralized stablecoin that can achieve enough use cases to reach the Schelling point of stablecoins (referring to the natural tendency of people without communication), although this is difficult.
Original article link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles