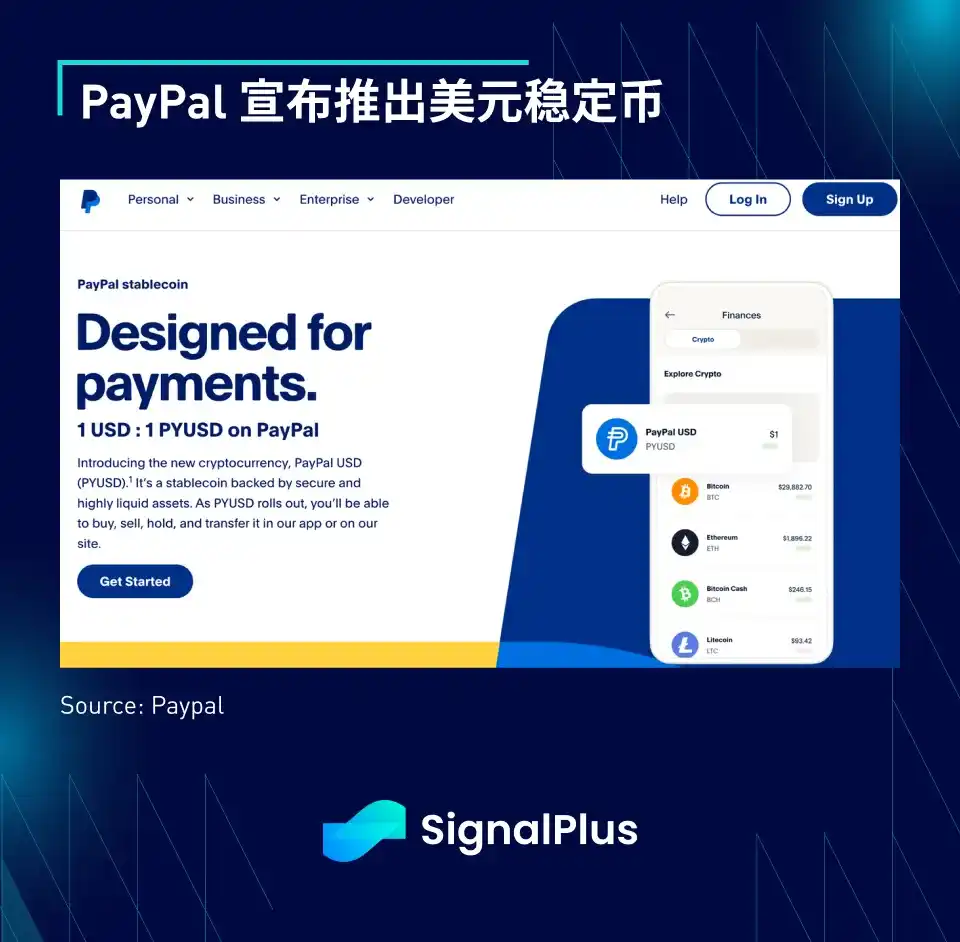
SignalPlus Macro Research Report: PayPal launches stablecoin issued by Paxos Trust and deployed on Ethereum.
Original Title: "SignalPlus Macro Research Report (20230808)"
Original Source: SignalPlus Chinese
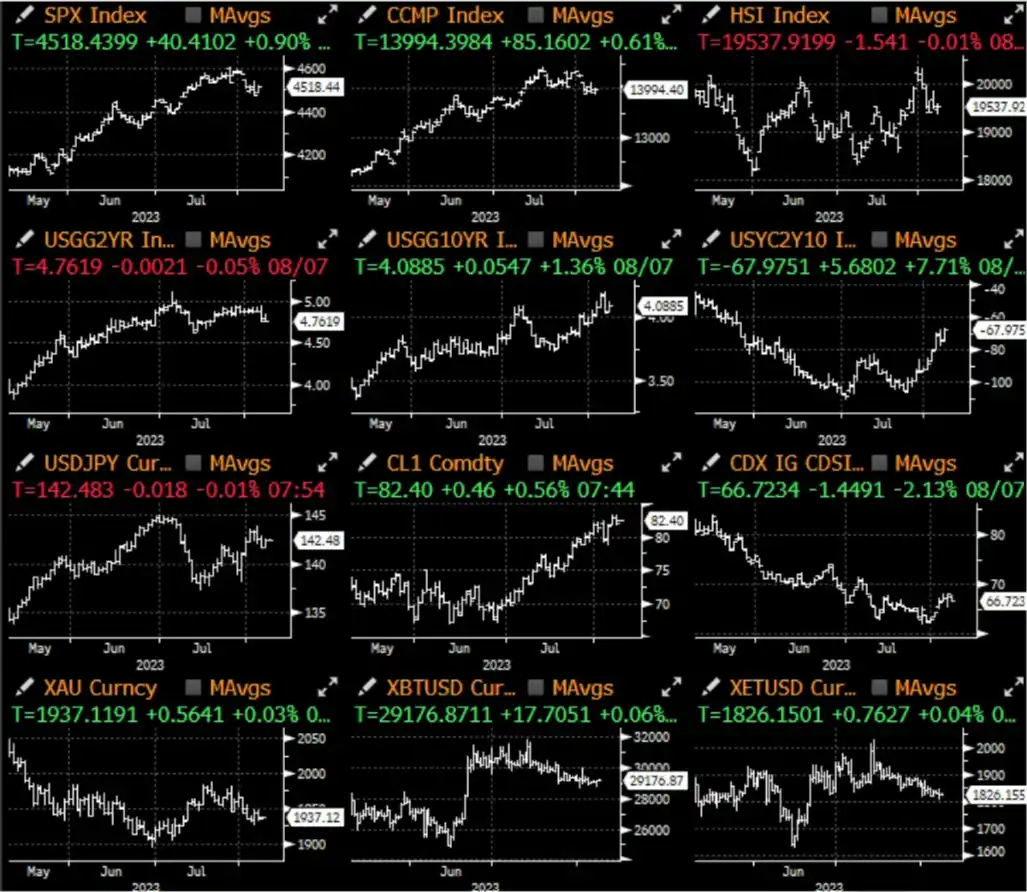
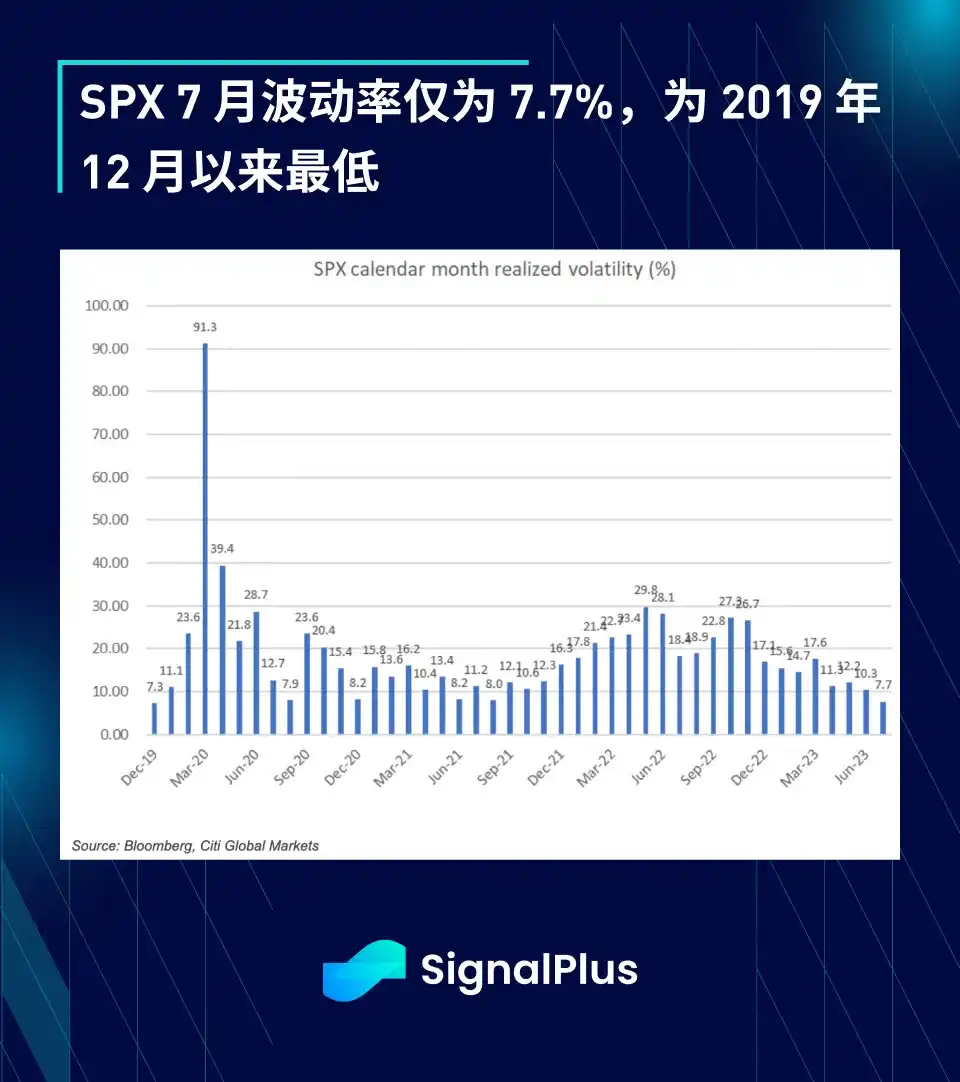
After experiencing a sluggish performance last week, the market's trading at the beginning of this week was also not active. The market tried to reorganize and find a foothold before the release of CPI. There were no noteworthy economic data releases in the United States, and Canada and Australia were also on holiday. The trading volume was only about 50-60% of normal levels. In addition, the monthly volatility of SPX in July was only 7.7%, the lowest level since December 2019. Furthermore, the daily volatility of SPX in July did not exceed +/- 1%, which is comparable to the extreme sluggishness of mainstream cryptocurrencies.
The yield on US Treasury bonds has risen again, with the 10-year yield up 5 basis points, while the stock market rebounded by about 1% yesterday after falling in the final trading session last Friday. Google (+2.6%), Meta (+1.9%), and NVDA (+1.5%) led the gains, while Apple (-1.5%) and TSLA (-2.1%) performed poorly. Tesla's stock price was affected by the unexpected resignation of CFO Zachary Kirkhorn, who was previously considered a potential successor to Elon as CEO.
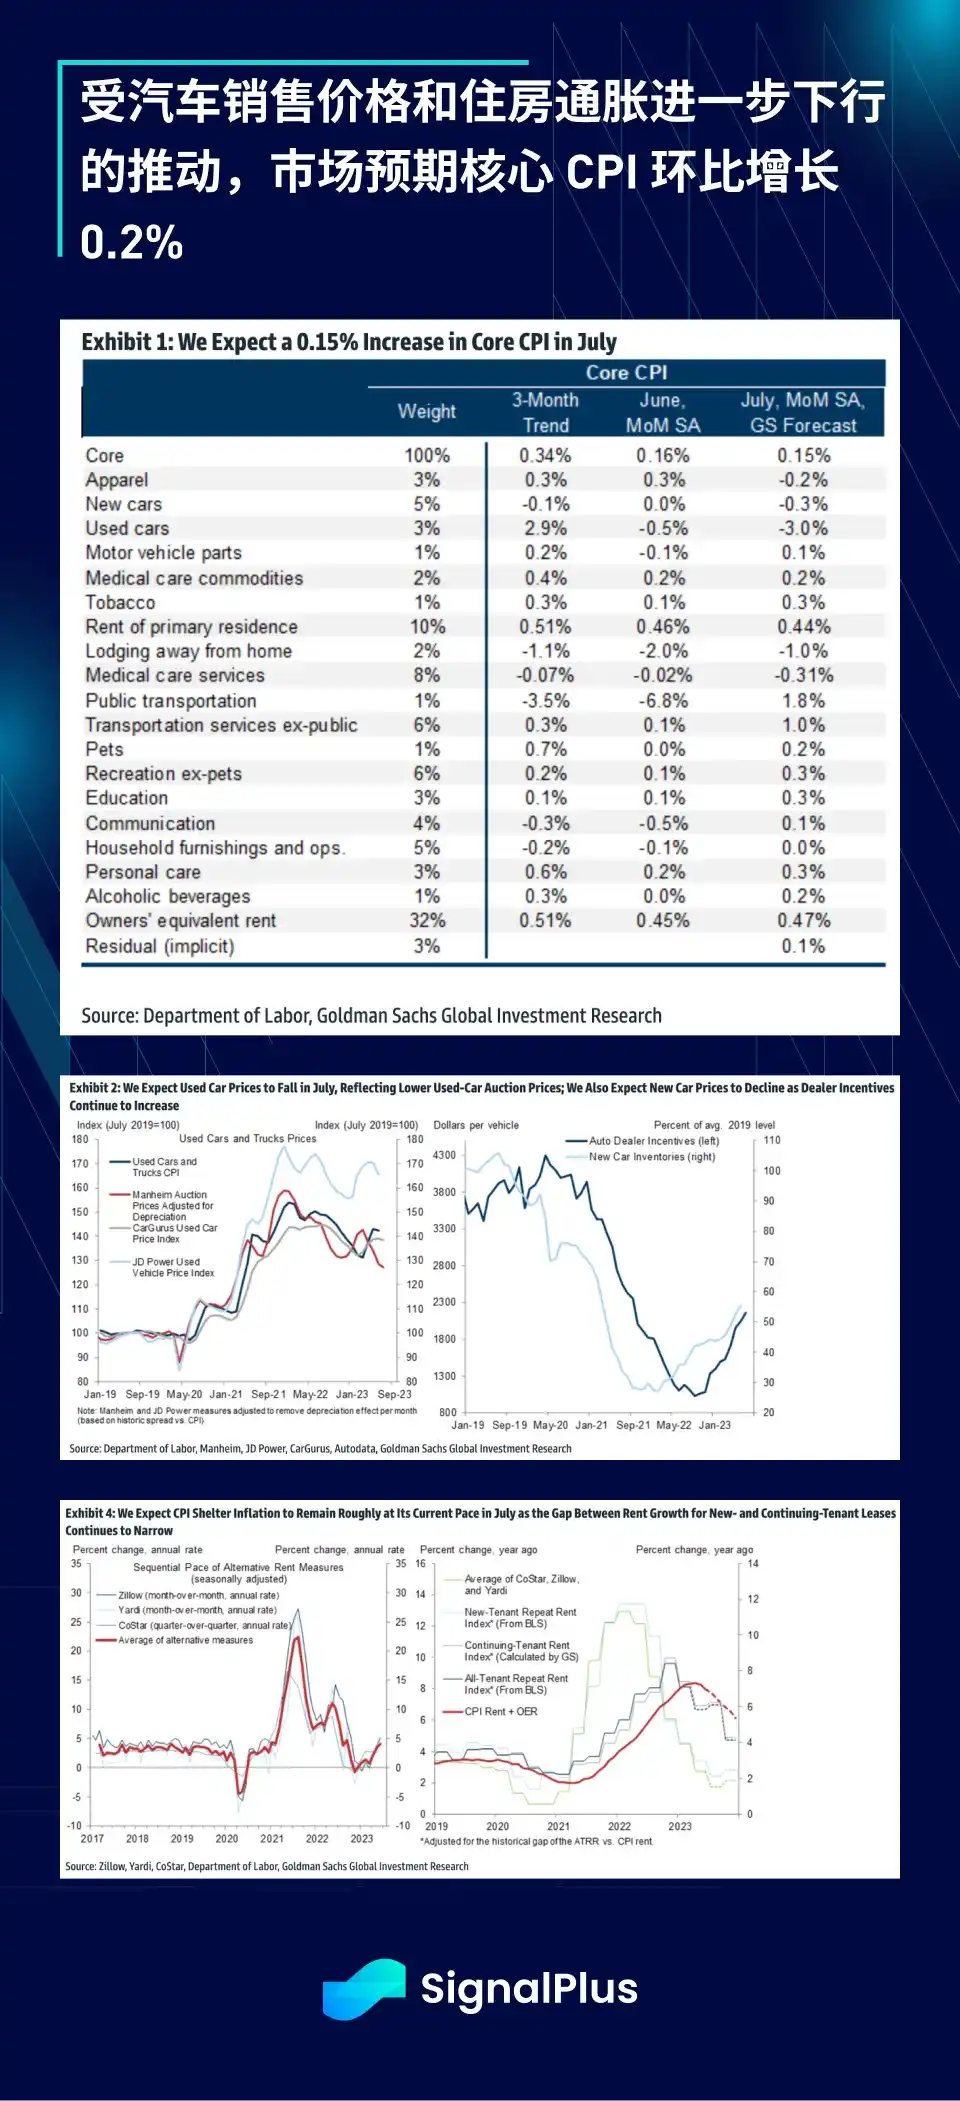
CPI is the only economic data worth paying attention to this week. Due to the expected further easing of car sales prices and housing inflation pressures, the market generally expects the month-on-month core CPI to be around 0.2%. However, the actual market changes on CPI release days this year have been disappointing, with Citigroup's report showing an average fluctuation of only +/- 0.62%.
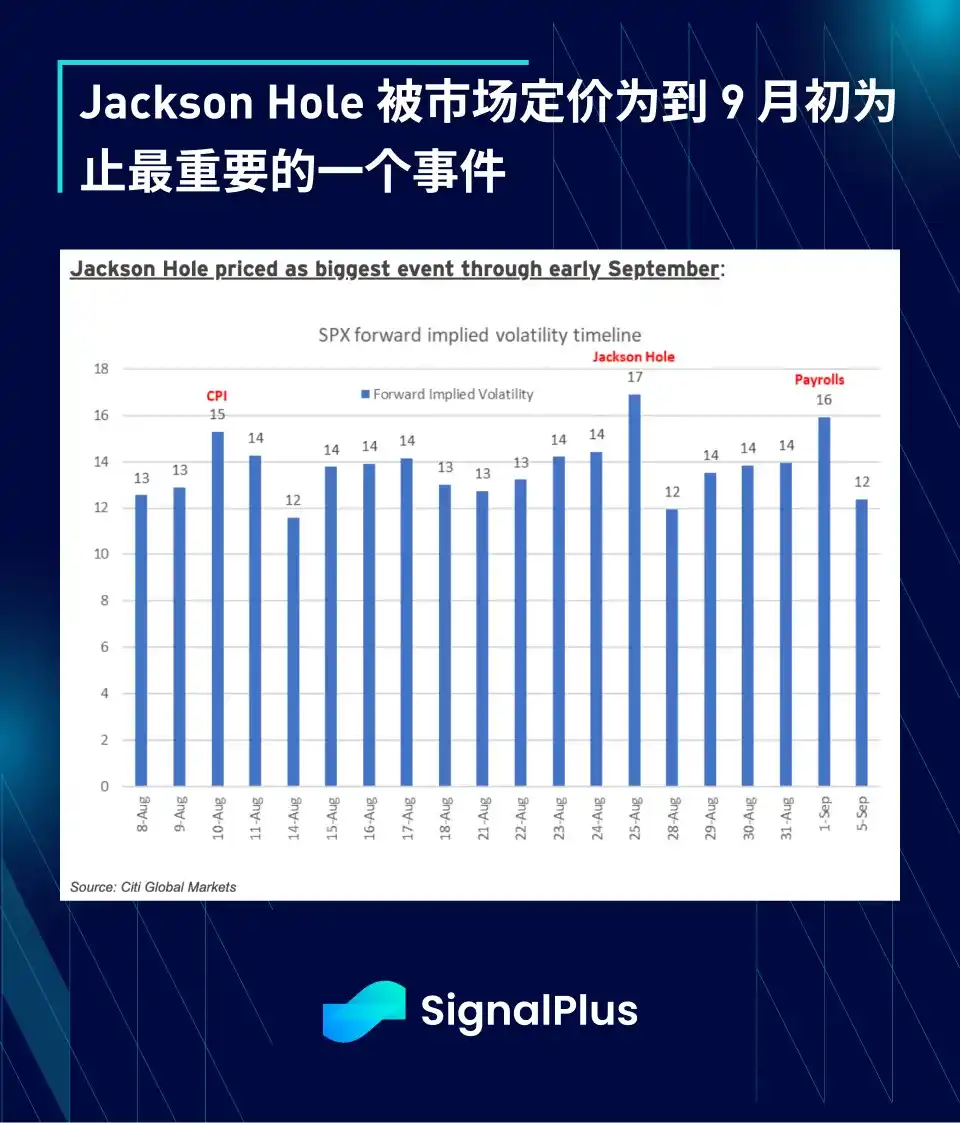
As far as the volatility caused by economic events is concerned, Jackson Hole is currently priced by the market as the most important event until early September, surpassing this week's CPI and the release of non-farm employment data after Labor Day.
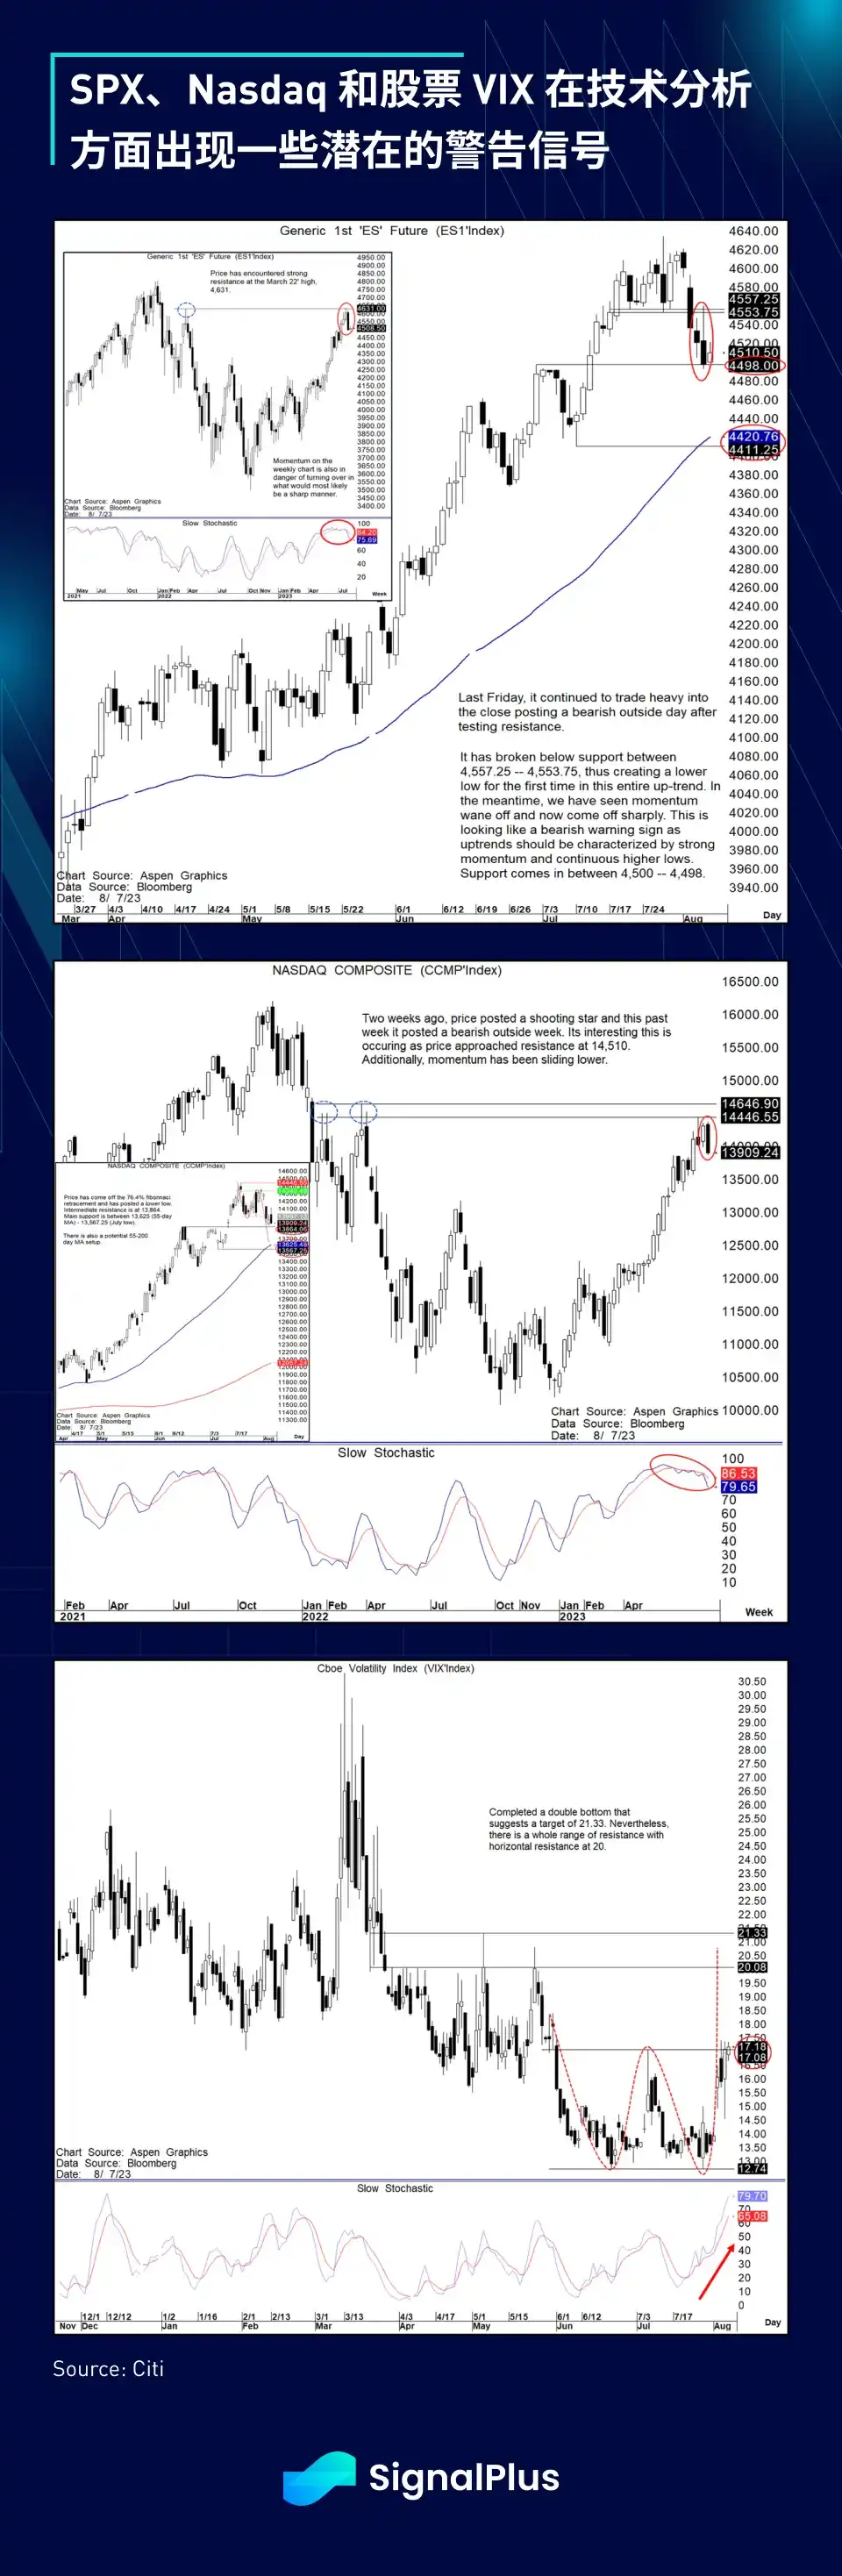
From a technical perspective, last Friday's sudden stock market drop also led to some worrying signs in different technical chart patterns. SPX and Nasdaq are both close to forming a bearish engulfing weekly pattern, while the stock VIX also has the opportunity to complete a double bottom pattern. Also, don't forget that we are entering the 9-11 months, which historically have not been friendly to the stock market.
In terms of digital assets, PayPal has become the first mainstream financial institution in the United States to launch a stablecoin (PYUSD). The stablecoin will be issued by Paxos Trust and launched on the Ethereum network. It will be supported by a 1:1 ratio of US dollar deposits, short-term government bonds, and cash equivalents. Obviously, this news has been warmly welcomed by the cryptocurrency community, and participants hope to see more traditional institutions truly get involved.
Interestingly, the original plan for PYUSD was to collaborate with the now infamous founder of FTX, SBF, and launch on the Solana blockchain in 2022. As with many things in the cryptocurrency space, the reality of 2022 turned out to be quite different from what was expected. One can't help but wonder what the current landscape would look like if some key players had made slightly different decisions or actions at the time.
Original article link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles