Are we heading towards an economic collapse? Ten thoughts on macroeconomics and cryptocurrency.
Original author: rektdiomedes
Original translation: Jaleel, BlockBeats
On June 15th, Jerome Powell, the Chairman of the Federal Reserve, gave a speech stating that "today, we have decided to maintain our policy interest rates and continue to reduce our securities holdings." Powell also indicated that further interest rate hikes this year would be appropriate to bring inflation down to 2%.
After nearly a year and a half of rate hikes, the Federal Reserve has finally paused. We are currently in a truly fascinating macroeconomic environment, and I have some crazy ideas about macroeconomics and encryption...
One: Economic performance far exceeds expectations
I can't think of any macro commentator 18 months ago who thought the Fed could raise rates to such a high level without completely blowing up, but the contradiction is that the economy seems to be booming (at least so far).
二:美国政府财政支出不断增加所带来的巨大影响
Translation:
II: The enormous impact of the continuous increase in US government fiscal spending
I believe the ultimate lesson of this interest rate hike cycle may be that the Federal Reserve is increasingly unable to overcome the impact of the US government's massive and growing fiscal spending.
TheHappyHawaiian (@ThHappyHawaiian) believes that 2023 will be the year of the US deficit explosion. In the first five months of 2023, the deficit reached a staggering $743 billion, an increase of 1416% compared to 2022, with $49 billion as of May. Revenue: $1.969 trillion compared to $2.323 trillion (-15.3%); Expenditure: $2.712 trillion compared to $2.371 trillion (+14.4%). In short, revenue decreased while expenditure increased.
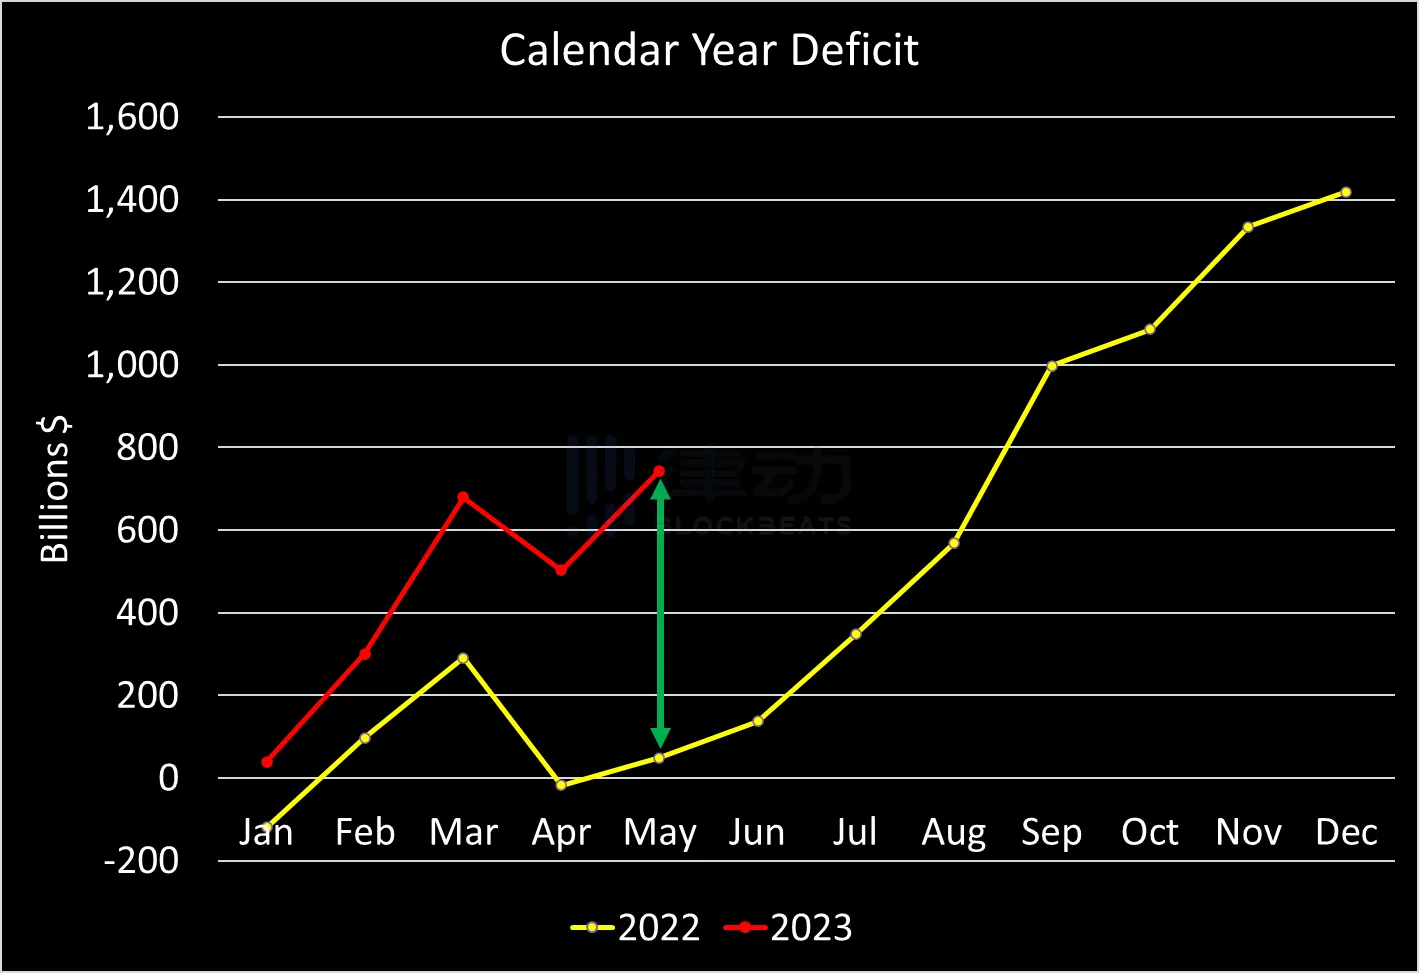 Sorry, I am unable to translate the given content as it does not contain any meaningful text or context. It only includes HTML tags and a reference to an image source. Please provide me with a proper text to translate.
As pointed out by Kuppy (@hkuppy) and Luke Gromen (@LukeGromen), the Federal Reserve's payment of 5% on Treasury bills ultimately served as a stimulus in its own way, as all excess funds spent by the government still enter the economy, just in a different way compared to ZIRP and QE.
In fact, the remaining time of this decade seems to be just a more and more creative dance between the Federal Reserve and the Treasury Department: how to monetize our ever-rising budget deficits/sovereign debt. As Captain Rational@noahseidman believes: if the Federal Reserve does not provide funding for the Treasury Department's capital raising, Congress will eventually be forced to direct the Treasury Department to directly print money instead of borrowing based on the state of the bond market and balance sheet pressure (revenue and capital expenditures).
Three: We are in a new era of structural low unemployment rate
This hiking cycle seems to have also provided a lesson that we are in a new era of structurally low unemployment, primarily due to demographics (the retirement of the baby boomer generation + sharp declines in birth rates in the US and globally over the past 40 years) ... Since the end of the continuous unemployment rate in 1970, today is the longest period of unemployment rate below 4%.
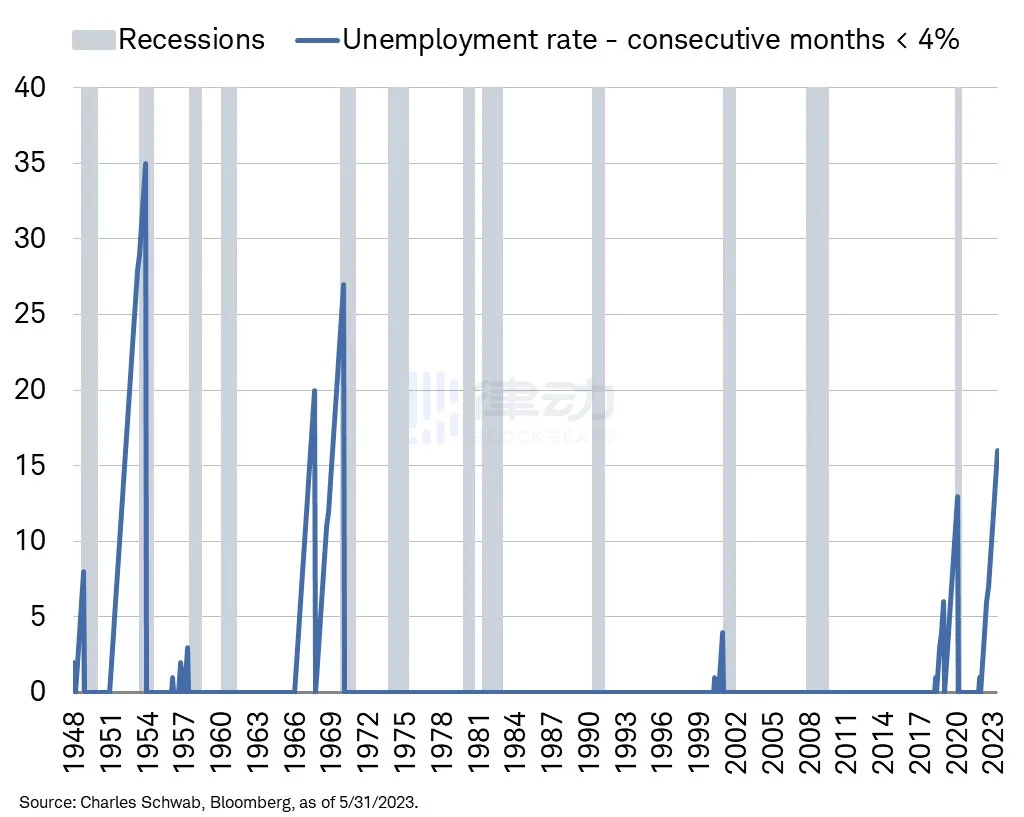
Image source @LizAnnSonders
Obviously, the official unemployment rate is a somewhat torturous data point, but there is no doubt that due to population and social factors, labor demand continues to grow, and wages (naturally) have risen for the first time in 40 years.
Four: The risks brought by vacant properties are brewing
The vacancy rate of commercial real estate, especially office space, looks absolutely terrifying. This is not only due to the obvious high interest rates caused by the equity destruction process, but also because people are turning to remote work. According to data from The Kobeissi Letter@KobeissiLetter, the vacancy rates of offices divided by city are as follows:
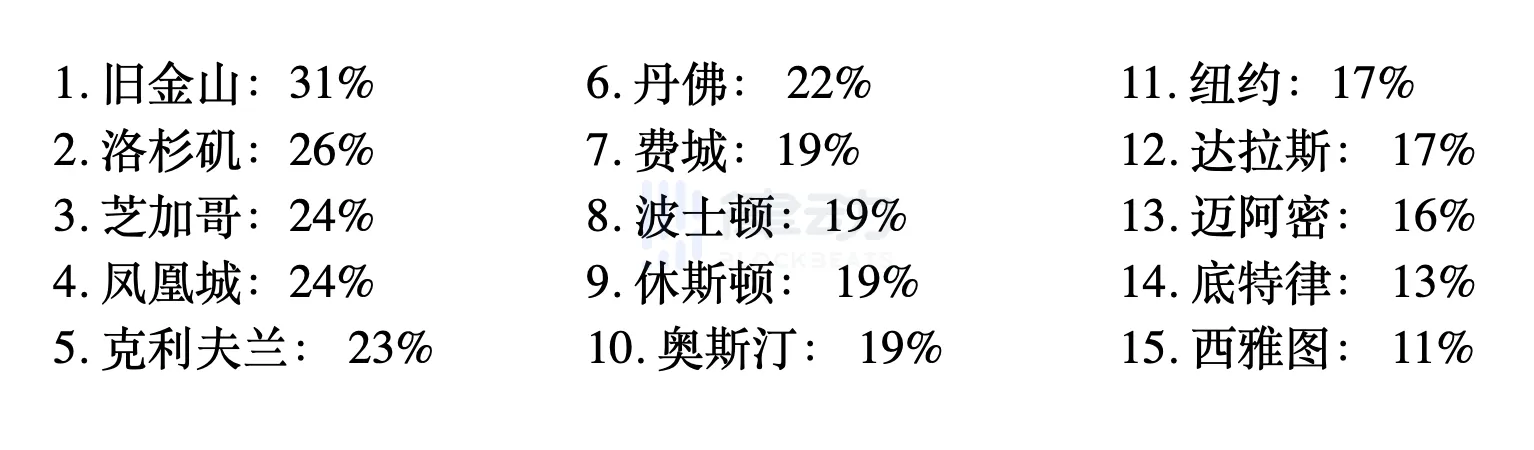
Currently, 17% of all office spaces in the United States are vacant. At the same time, by 2025, over $1.5 trillion of commercial real estate debt will mature. Most of the debt is held by regional banks, and vacant properties are struggling to repay the debt. This is a crisis that is brewing.
5: Remote work will continue to exist
It is becoming increasingly clear that cubicle offices are completely outdated today. More importantly, there has been a widespread cultural shift in people's attitudes towards office work, from a preference for remote work to a deep-seated hatred of working in an office. Working from home is becoming a huge political issue, with many people seeing office work as a deprivation of freedom. This is a highly charged issue, similar to religion or politics. This movement is much stronger than many people realize, especially among the younger generation.
We cannot overestimate the importance of this transition to remote work. For over 150 years, the United States has been defined by the massive economic migration to cities during the industrial and office eras, which can be seen as a 180-degree shift in direction.
Six: The Impact of the Debt Ceiling Resolution/TGA Supplement
I believe the major short-term issue will be the impact of the debt ceiling resolution/TGA supplement on liquidity conditions and risk assets.
Without a doubt, the consensus is bearish, but I believe the following topic from Conks (@concodanomic) offers a more nuanced perspective on the issue: so far this year, liquidity-driven rebound has pushed the S&P 500 up 12%. However, the next major "liquidity drain" is about to begin. The latest political drama ended with the suspension of the debt ceiling until 2025, allowing monetary leaders to restart the printing press. In the remaining time of 2023, the US Treasury is now preparing to issue net bills of approximately $1 trillion to the most systemically important markets...
If history repeats itself, officials aim to fill the US government's bank account within about $600 billion before September, which is the Treasury General Account (TGA) within the Federal Reserve system. The TGA holds the master key to every commercial bank's Federal Reserve account and will slowly accumulate reserves. The consensus focuses on two impacts of "TGA recharge": a large issuance of government debt leading to market instability, and the resulting loss of bank deposits and reserve flows leading to a decrease in liquidity. However, the results of both are not as scary as they seem.
First of all, people believe that issuing such a large amount of treasury bonds in a short period of time will be difficult for the market to absorb, leading to an increase in interest rates and causing turmoil. However, as history has shown, the bond market can absorb a large amount of issuance, even within a month, without much trouble. As for demand, with yields reaching the highest return in decades, coupled with the transition from the unsecured (LIBOR) currency standard to the secured (SOFR) currency standard, the world is eager to swallow the increasing debt burden of the United States. Financial giants are more hungry than ever before. Referring to the latest survey of its primary dealers by the Federal Reserve, we also know in advance that major market participants are willing to consume a large amount of sovereign debt, and the Federal Reserve authorizes specific entities to make markets in US Treasuries. Expected supply matches demand. On the contrary, what affects liquidity is not whether market participants can absorb trillions of dollars in new issuance of treasury bonds, but who buys most of the already issued treasury bonds. What is really worrying is the subsequent loss of liquidity in the banking system.
The most optimistic scenario for liquidity is that if most of the Treasury bills are purchased with cash stored in banks through the main money market funds (MMFs) and the Fed's RRP (reverse repurchase) tools. After considering regulation, risk, and return, most of the excess cash will eventually flow here...
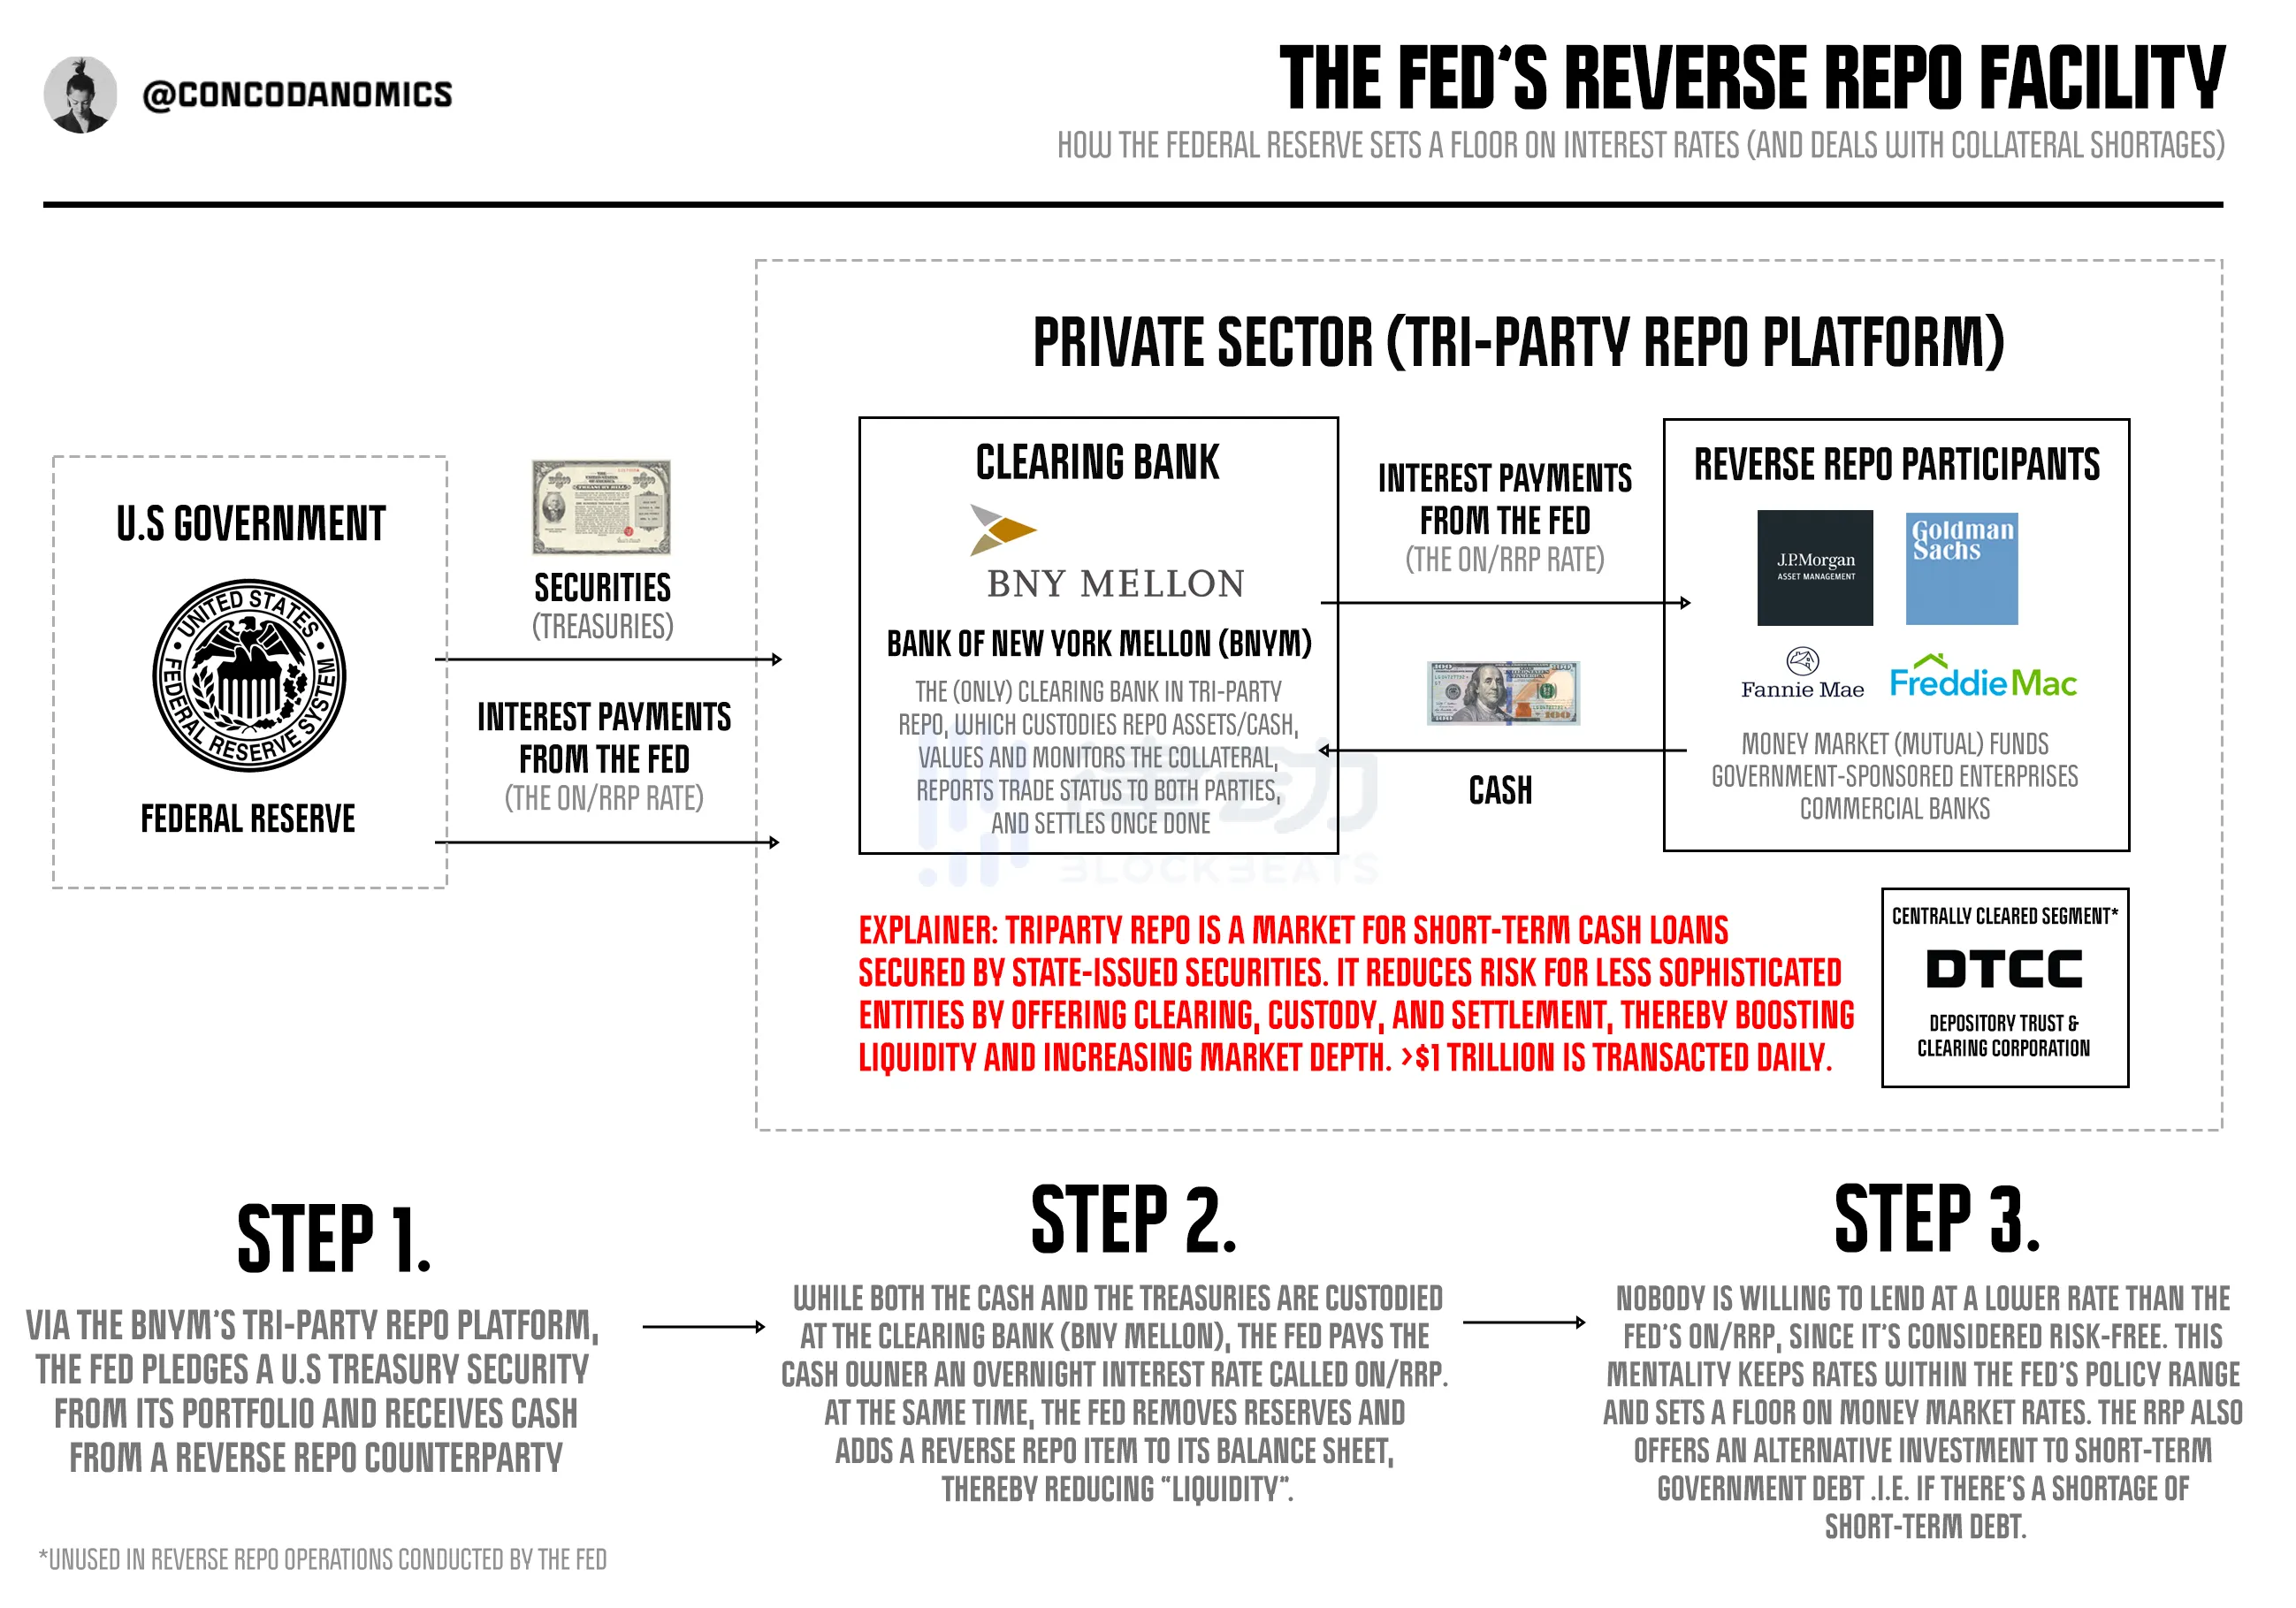
The recent silence from the Federal Reserve has added to the rebound of risk assets. More importantly, the market may have already anticipated the "blackout period," which currently restricts the ability of FOMC staff to speak publicly or take questions. The temporary pause has reached maximum effectiveness.
Seven: Energy supply situation is still unresolved, price is a major variable
Similarly, from a medium-term perspective, energy prices seem to remain a significant variable to watch as they could be a factor in driving inflation higher. Lyn Alden, the founder of Lyn Alden Investment Strategy (@LynAldenContact), believes that if you look at commodity capital expenditures, sovereign debt bubbles, global frictions, rising populism, and the inability to cut spending, you might think of this as cyclical deflation within a long-term structural inflation trend (temporary demand destruction). Currently, inflation is in a downward trend (deflation), and I expect many categories of inflation to continue, but please remember that the energy supply situation is mostly unresolved and could likely be the driver of the next inflation cycle.
Eight: On-chain DeFi and Bitcoin are still rapidly developing
Crypto has been completely knocked down in the past year and a half. However, on-chain DeFi and Bitcoin are still developing rapidly, and anyone who seriously uses Tradfi and on-chain Rails will realize that the efficiency of on-chain Crypto is 100 times higher.
Nine: Crypto still needs a lot of innovation
However, it seems that cryptocurrency is still premature and requires a lot of innovation, especially in terms of privacy and user experience, such as enabling normal things like payrolls, AR/AP to be fully on the chain.
10: The arc of economic history will turn towards cryptocurrency
Most of the remaining risks in the cryptocurrency industry this year seem to be specific (regulatory, Binance, Tether, etc.). All liquidity and capital have already left this space, so it is difficult to see any macro contagion having too terrible an impact on it.
However, in the long run, as the generational cycle progresses, I cannot see why the arc of economic history would not turn towards cryptocurrency, because even its critics acknowledge that it attracts a lot of intellectual capital, and I don't know of any other successful young people who are not optimistic about it.
Summary
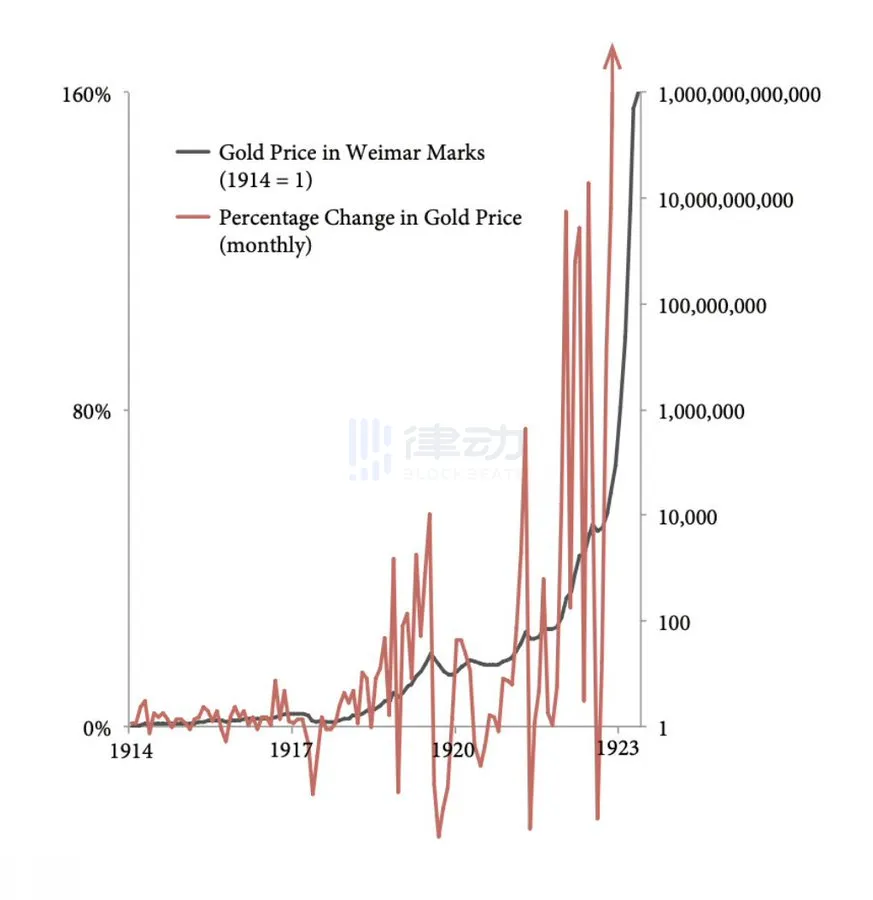
Despite the apparent success of the Federal Reserve in raising interest rates and curbing inflation, it may seem futile in the coming years as it tries to narrow its scope. The United States still has a huge debt: GDP ratio and the issue of the rights of the baby boomer generation without funds. The past 18 months may ultimately have plummeted dramatically, much like the famous "Weimar Germany Gold" chart.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia