When Binance Launchpool meets Uniswap V4, whose ace is bigger?
Last night, Binance announced the launch of the new project Maverick Protocol (MAV) on Launchpool. Users can deposit BNB and TUSD into the MAV mining pool on the Launchpad website to receive MAV rewards starting from June 14th. Binance will open the MAV trading market after the MAV Token meets the liquidity requirements.
It is a coincidence that just one hour after Maverick announced the launch of Binance Launchpool, Uniswap released the code draft of its V4 version, hoping to bring more innovative power to the DeFi field by introducing new features such as Hooks and Singleton. For example, V4 will allow pools to support dynamic fees, add on-chain limit orders, or act as a time-weighted average market maker (TWAMM) to spread large orders over time.
After the release of the V4 code, the most discussed topic in the community was the innovation made in custom liquidity through the new feature Hooks. Contracts that run at various points in the pool operation lifecycle can make the same trade-offs as V3 or add entirely new features. In addition, V4 pools will exist in a single contract, reducing the cost of creating mining pools by 99%.
Interestingly, Maverick, which announced the launch of Binance Launchpool just an hour ago, has also made some innovations in custom liquidity. What are the similarities and differences between Maverick and Uniswap V4?
Directional LP: Maverick's solution to custom liquidity
Maverick AMM has launched the design of Dynamic Distribution AMM, which includes the following three major functions:
1. The first AMM with the native ability to automatically move concentrated liquidity based on transaction prices.
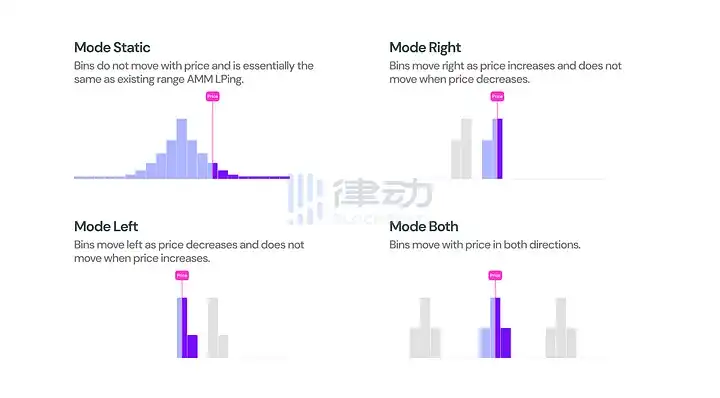
2. Provide tools to empower LPs to execute different liquidity provision strategies: only move with price increases, stay in place when prices decrease; only move with price decreases, stay in place when prices increase; move with both price increases and decreases; and provide fixed liquidity at certain price points.
3、AMM helps LPs earn real-time compound interest.
Specifically, Maverick generates four modes including Static Mode (liquidity does not move), Right Mode (liquidity changes as the price rises but remains unchanged when the price falls), Left Mode (liquidity changes as the price falls but remains unchanged when the price rises), and Bidirectional Mode (liquidity moves with both price increases and decreases).
Based on the leftward and rightward flow patterns in the four liquidity models, Maverick introduces the innovative AMM concept of Directional LP, which allows liquidity providers (LP) to follow the price of the trading pair and choose the direction of liquidity movement, thereby obtaining excess returns when choosing correctly, while avoiding impermanent loss.
Confronting concentrated liquidity is not always capital efficient and may lead to improper allocation and efficiency decline. Maverick AMM helps users improve capital efficiency by automatically re-concentrating liquidity, and liquidity providers can choose from four liquidity transfer modes to eliminate high GAS fees caused by adjusting positions around prices.
In the current AMM field, liquidity providers cannot set a single, definite bullish or bearish position when providing liquidity. For any existing AMM in the DeFi space, liquidity providers implicitly bet that the price of the asset pair in their pool will oscillate horizontally, allowing them to collect transaction fees, while the ratio of their deposited assets will not change significantly. If this bet is wrong - that is, if the price moves in any direction other than sideways - liquidity providers will suffer impermanent losses that may exceed any fees they collect.
In static liquidity AMMs, it is advantageous for LPs to have bilateral asset allocation, so that LPs can immediately access trading volume and therefore charge fees. However, bilateral LPs increase the possibility of impermanent loss.
In AMMs like Uniswap V2 with xy=k, even one-sided LP is not supported. In existing range-based AMMs like Uniswap V3, one-sided LP is possible, but with one-sided LP, your capital may become stagnant as the AMM price deviates from your range. Without a built-in mechanism to move liquidity closer to the price level, the capital efficiency of one-sided LP is zero.
In Maverick, due to the underlying Maverick liquidity transfer mechanism, directional LPs can provide liquidity for an asset while still maintaining high capital efficiency.
Liquidity providers can now choose to follow the price of an asset in one direction, effectively betting on the price trajectory of a specific token. These directional bets are similar to one-sided liquidity strategies, as liquidity providers will be mostly or entirely exposed to a single asset in a given pool.
As the price moves in the chosen direction, AMM will automatically re-concentrate liquidity to follow it and obtain more fees. If liquidity providers make the correct bet on the price direction, they can enjoy liquidity that is re-concentrated around the price when it moves in their chosen direction without suffering any impermanent loss (IL).
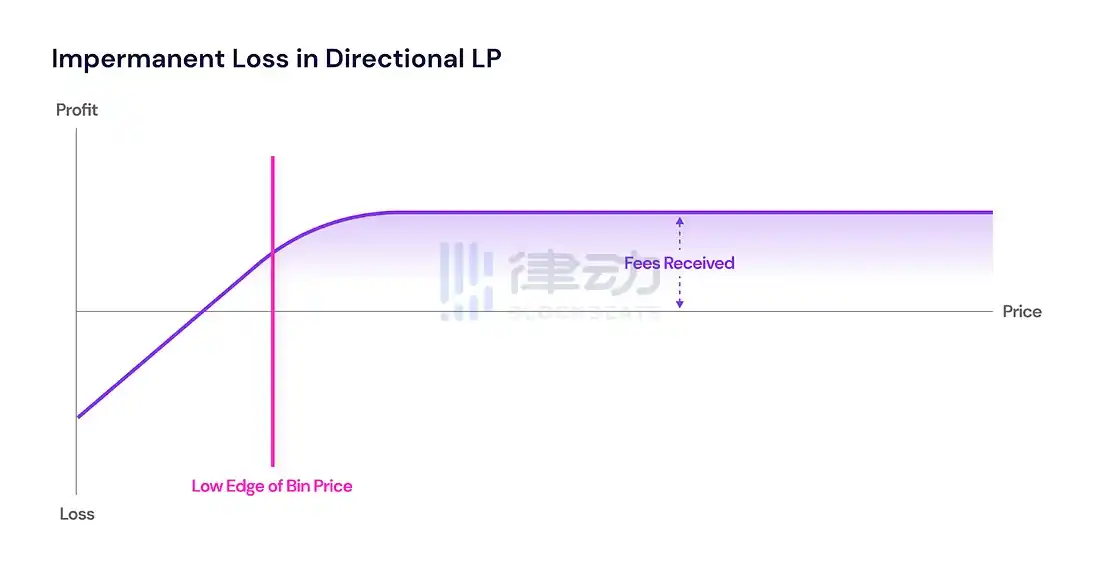
That is to say, the directional LPs in Maverick with a single asset, i.e. LPs using Mode Right or Mode Left, are only exposed to IL in one direction. If the LP chooses the mode of change corresponding to the price change (e.g. the LP is in Mode Right and the price rises), the LP will not experience IL. Therefore, IL is only one-way, meaning that LPs only face the risk of price changes in one direction, not two.
Uniswap V4 Hooks
So how does the newly announced Uniswap V4 achieve custom liquidity? In the Uniswap official blog post, there is a relatively detailed explanation of Hooks and the custom liquidity they bring. The following content is excerpted from the blog post "Our Vision for Uniswap v4":
What are "Hooks" and custom liquidity pools? Each Uniswap liquidity pool has a lifecycle. During the lifecycle of a liquidity pool, several things happen, including users creating liquidity pools with default fee levels, liquidity being added, removed, or adjusted, and users trading tokens.
In Uniswap v3, these lifecycle events are tightly coupled and executed in a very strict order.
In order to create space for customizable liquidity in Uniswap v4, Uniswap hopes to create a method for liquidity pool deployers to introduce code that executes specified operations at key points throughout the lifecycle of the liquidity pool - such as before or after token trades, or before or after LP position changes.
Enter "Hooks" and these plugins can customize the interaction between liquidity pools, exchanges, fees, and LP positions. Developers can innovate on top of the liquidity and security of the Uniswap protocol, creating custom AMM pools through "Hooks" integrated with v4 smart contracts.
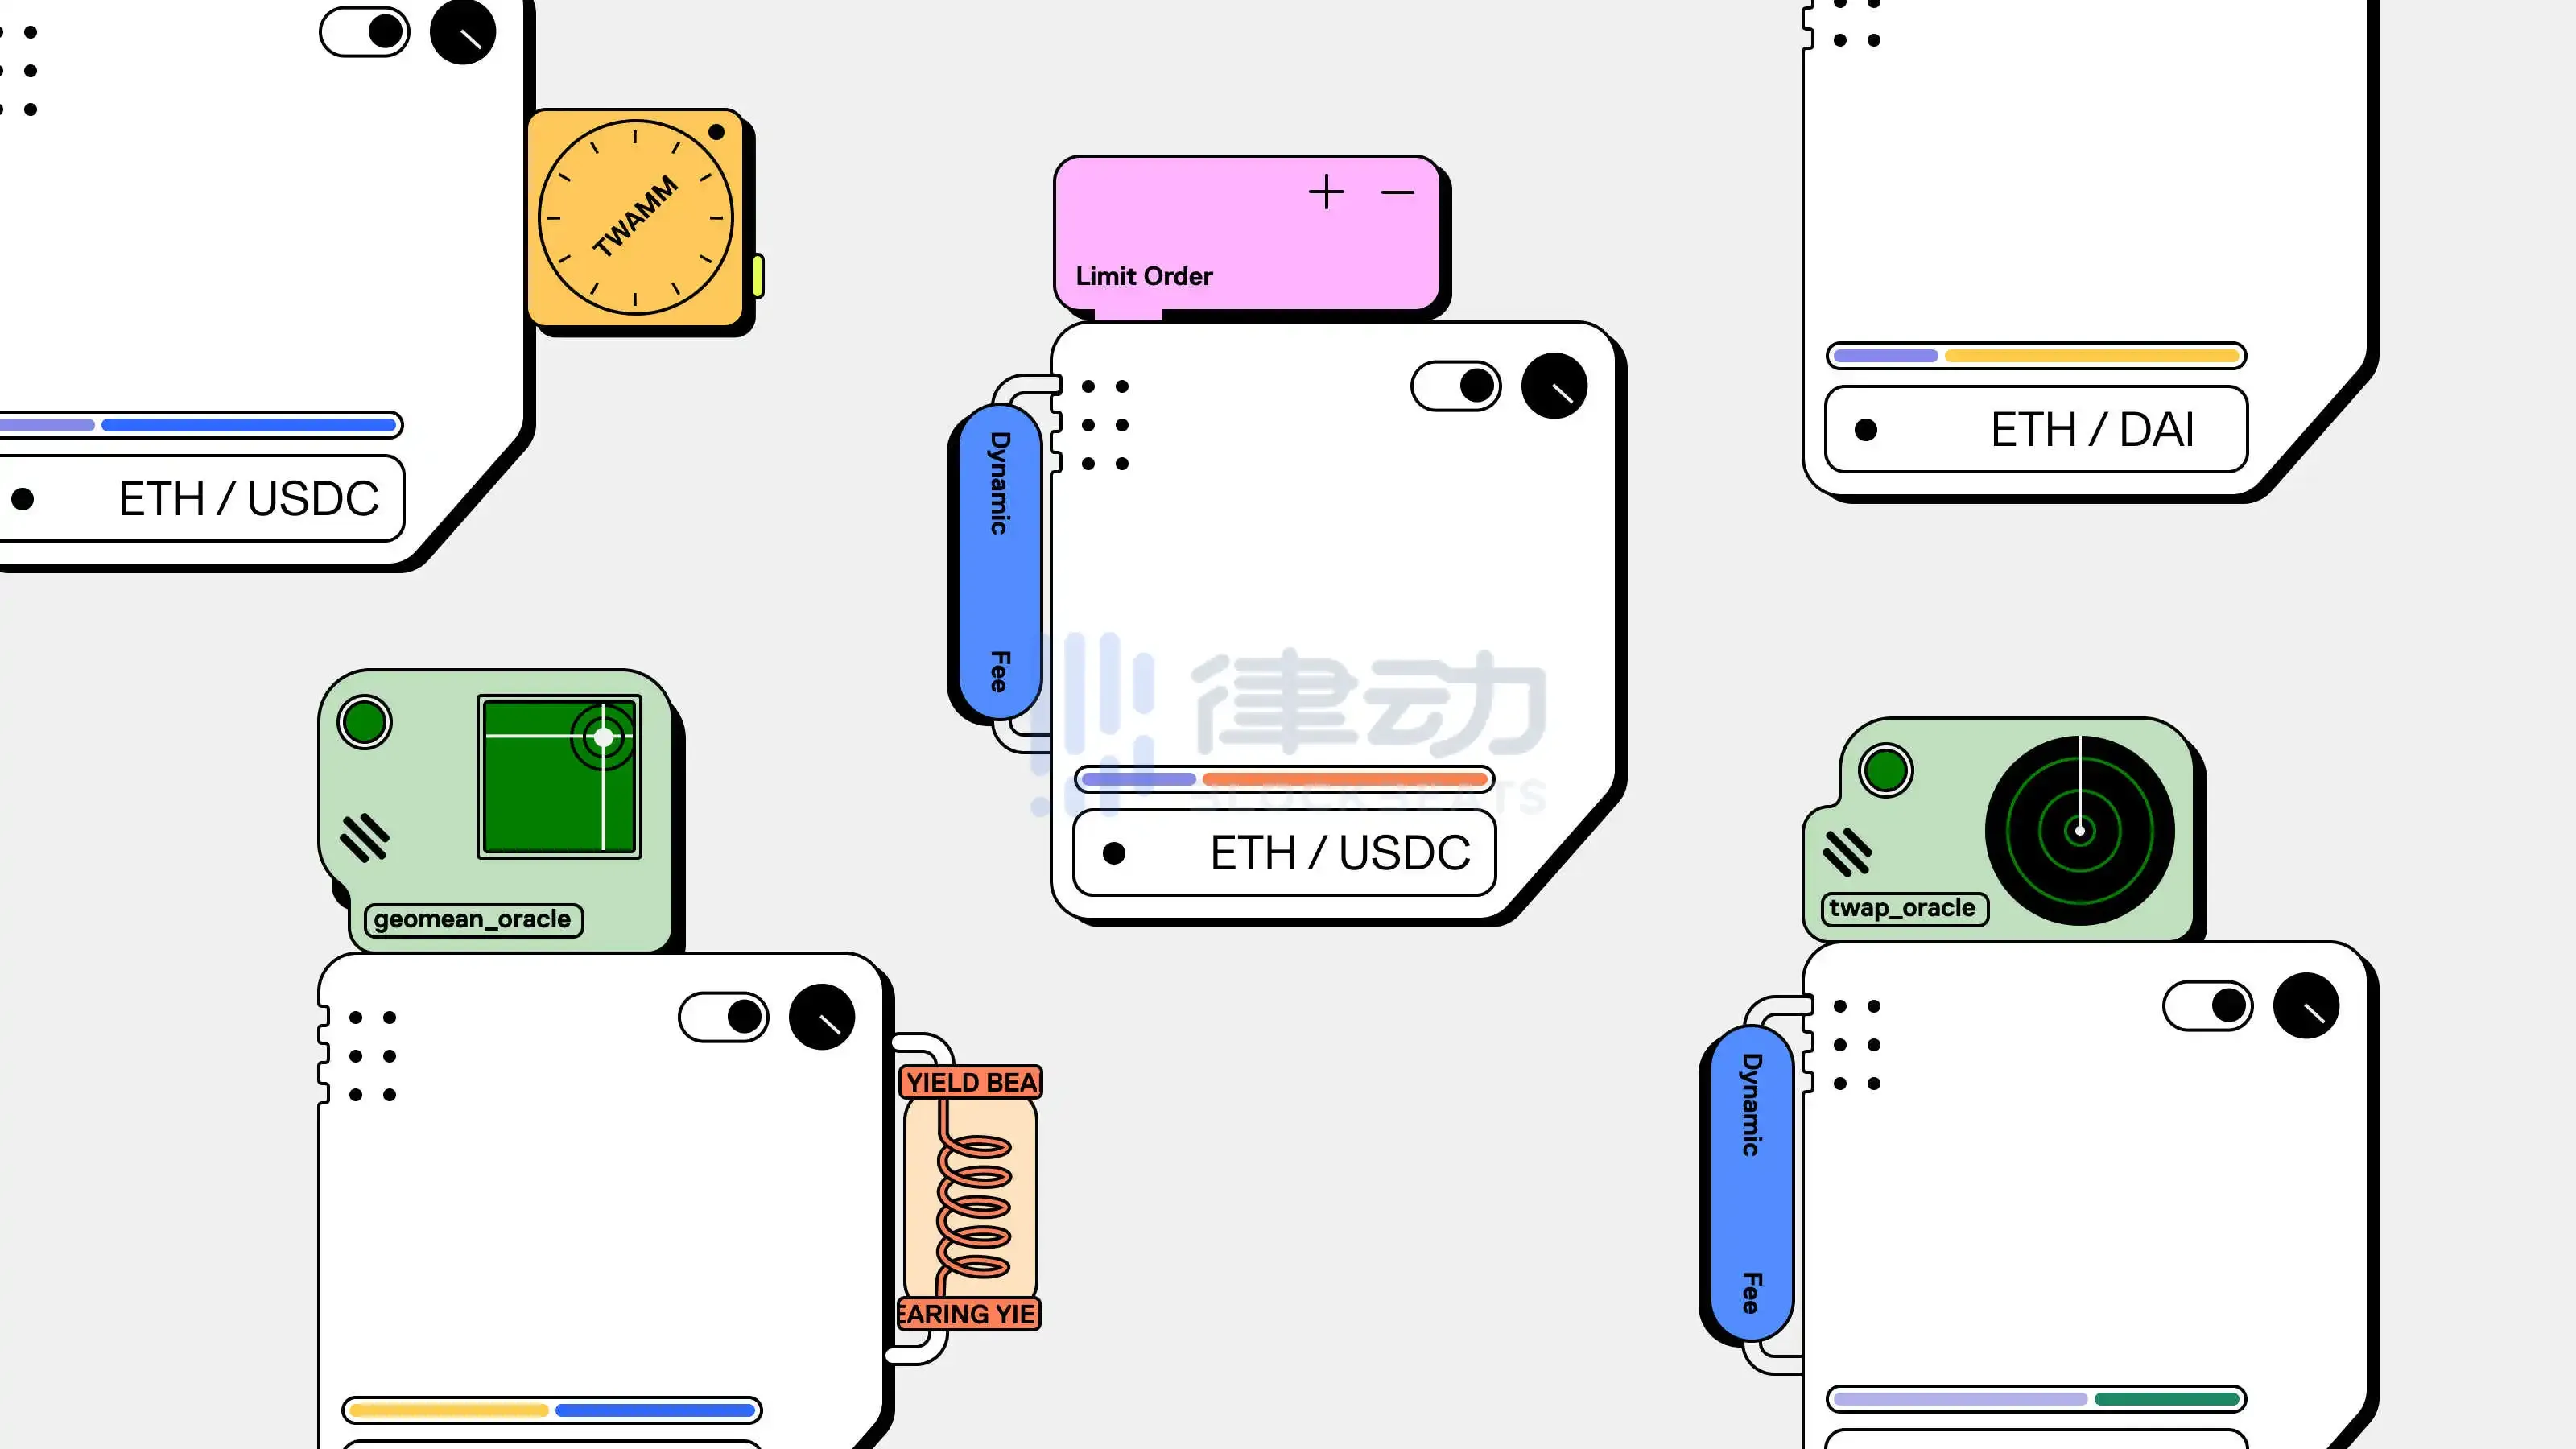
Some experiments that Uniswap is interested in include: Time-Weighted Average Market Maker (TWAMM); dynamic fees based on volatility or other inputs; on-chain limit orders; depositing liquidity beyond the range into lending protocols; customized on-chain oracles, such as geometric mean oracles; automatic compounding of LP fees into LP positions; internalized MEV profit distribution to LPs;
However, in reality, imagination has no limits. As each liquidity pool is now defined not only by tokens and fee levels, we will see liquidity pools of various colors, shapes, and sizes. The core logic of Uniswap v4 is the same as v3 and is non-upgradable. Although each liquidity pool can use its own "Hooks" smart contract, "Hooks" can only be restricted to specific permissions determined at the time of creating the liquidity pool.
Uniswap has created an example "Hooks" contract to get started with the current framework. Uniswap also hopes that developers can come up with new and interesting ways to build functionality that they haven't even thought of.
Additionally, Uniswap V4 has improved its architecture to save Gas.
In v3, Uniswap deployed a new contract for each liquidity pool, which made the cost of creating liquidity pools and performing multi-pool exchanges higher. In v4, Uniswap saves all liquidity pools in a "singleton" contract, which will greatly save gas, as token trades will no longer need to transfer tokens between liquidity pools held in different contracts. Preliminary estimates suggest that v4 has reduced the gas cost of creating liquidity pools by 99%, and "Hooks" introduces a world of endless choices, while "singleton" allows users to efficiently route to all options.
This "singleton" architecture has been supplemented by the new "flash accounting" system. In v3, the system does not transfer assets into and out of the liquidity pool at the end of each exchange, but only transfers them on the net balance - which means a more efficient system that can provide additional gas savings in Uniswap v4.
Uniswap believes that the best "fast accounting" design is to use "transient storage", a feature that will be enabled by EIP-1153. This EIP is considered part of the Ethereum Constantinople hard fork and will bring significant gas improvements and more concise contract design to various applications.
With "Singleton" and "Fast Accounting", there is no longer a need to limit the expense level. Liquidity pool creators can set them to the most competitive level or customize them using dynamic fee "Hooks". V4 also restores support for native ETH, which saves additional gas.
Not only that, the Hooks feature also allows for the use of Uniswap liquidity in different ways. This is similar to Balancer's Boosted Pools, where liquidity beyond a certain range can be deposited into other protocols, such as lenders, to earn additional returns.
The above examples related to Hooks functionality are just some applications conceived by the Uniswap team. In addition, anyone can build and deploy their own Hooks functionality without the need for permission.
Uniswap V4 will upgrade the DEX vs CEX war?
Undoubtedly, the emergence of Uniswap V4 will have a wide and inevitable impact on the entire DeFi ecosystem. In the eyes of many, Uniswap's ambition is not to "dominate" DeFi, but to replace the centralized and trust-based CEX camp.
Because the Hooks feature can improve the capital efficiency of protocols, it is more customizable and has higher gas efficiency compared to V3. The latter two features should help Uniswap attract more order flow from DEX aggregators and longer-tail heterogeneous trading pairs, while maintaining its dominant position in high-volume trading pairs such as ETH/USDC, ETH/USDT, ETH/DAI, etc.
The significance of the Uniswap V4 upgrade is not only to help Uniswap maintain its position as the DEX with the largest trading volume, but also to enable Uniswap to create more types of orders, such as TWAP and limit orders. This will help Uniswap attract more diverse traders to switch to DEX, thereby enhancing its competitiveness with CEX.
Related reading: "How does Uniswap V4 implement limit order trading?"
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles