



In-depth analysis of the economic principles, operational data, and market performance of L1 and L2.
Source: Token Terminal
Translation: Deep Tide TechFlow
We often intuitively feel the costs and benefits generated by using different blockchains, namely gas fees and incentives.
However, do you really understand their complete economic models? Where do gas and incentives come from, and where will they flow? How do markets perform under different economic model designs?
Token Terminal has explored the blockchain economic models of major L1 and L2 based on PoW and PoS, as well as emerging models such as liquidity staking protocols. The economic models of each blockchain are explained in a very easy-to-understand way and illustrated with examples.
Meanwhile, by visualizing the daily cost changes of the blockchain, insights and analysis on the market performance of mainstream blockchains were also provided for investors to use the framework in the article to compare the economic performance, potential, and sustainability of the blockchains.
Introduction
The following visualization shows the daily fees of blockchain mentioned in this article over the past 180 days.
Deep Tide Note: It can be seen that the total transaction fees of Ethereum and Bitcoin are still far ahead.

The key components that typically make up the economic structure of a blockchain are transaction fees, block rewards (incentives) for inflation, and fee destruction.
The transaction fee represents the market price of block space.
Incentives are economic rewards that encourage people to take action (such as verifying transactions).
Fee destruction is a mechanism that removes a portion of transaction fees from circulation.
Given the limited capacity of a single blockchain, we will see a world with multiple different blockchains - each optimized for different use cases - interoperating with each other. The blockchain market was initially dominated by Bitcoin, an extremely simple and limited contract execution environment. With the launch of Ethereum, it became possible (in theory) to deploy arbitrarily complex contracts or programs on the blockchain. Now, with the rise of scaling solutions, application-specific blockchain, and cross-chain bridges, it is also possible to deploy arbitrarily complex contracts in practice (scalability is no longer a limitation). In this article, we will break down the economic models of the most common types of blockchains.
Based on PoW L1
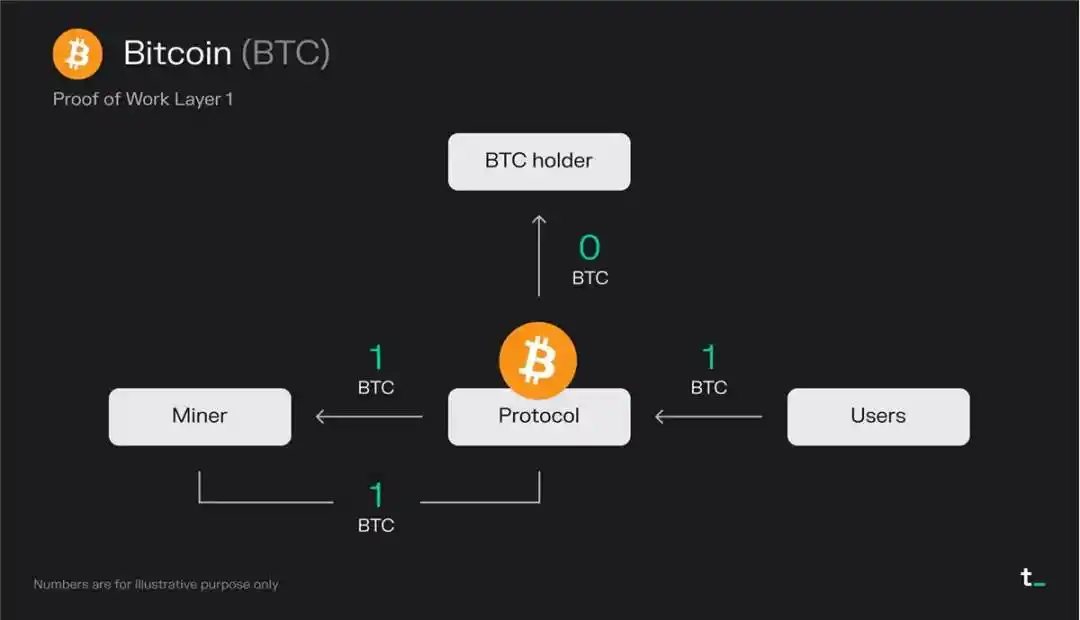
Principle Description:
- The user pays a transaction fee of 1 BTC for a block.- Miners receive all fees (1 BTC).- Miners receive 1 BTC (newly issued BTC) as a reward from the block.
Final Result:
Points:
The demand for submitting transactions on Bitcoin has created a market for block space. Users pay for block space to miners. Bulk subsidies further incentivize miners, which are newly minted bitcoins that increase the total supply of currency. Currently, all fees and block subsidies for Bitcoin belong to miners.
Bitcoin provides security through CPU power. Its value proposition is to create a secure, transparent, and immutable global ledger that allows for trustless and irreversible value transfer. These values are maintained by the security derived from CPU usage. Each block requires a significant amount of CPU power to be validated on the network. Essentially, 1 CPU corresponds to 1 vote on the network. Therefore, as long as the majority of CPU power is in the hands of honest miners, the network is secure.
The economy of Bitcoin is determined by two variables: transaction fees and block subsidies. Transaction fees are determined by the supply and demand of network block space. Block subsidies are inflation rewards that increase the circulating supply of BTC. Currently, miners receive a reward of 6.25 bitcoins per block, which is halved every four years. Eventually, Bitcoin will reach a maximum supply of 21 million (expected to occur around 2140), and block rewards will consist solely of transaction fees. This means that it is crucial for users to adopt practices that maintain economic sustainability for the network.
Based on PoS L1
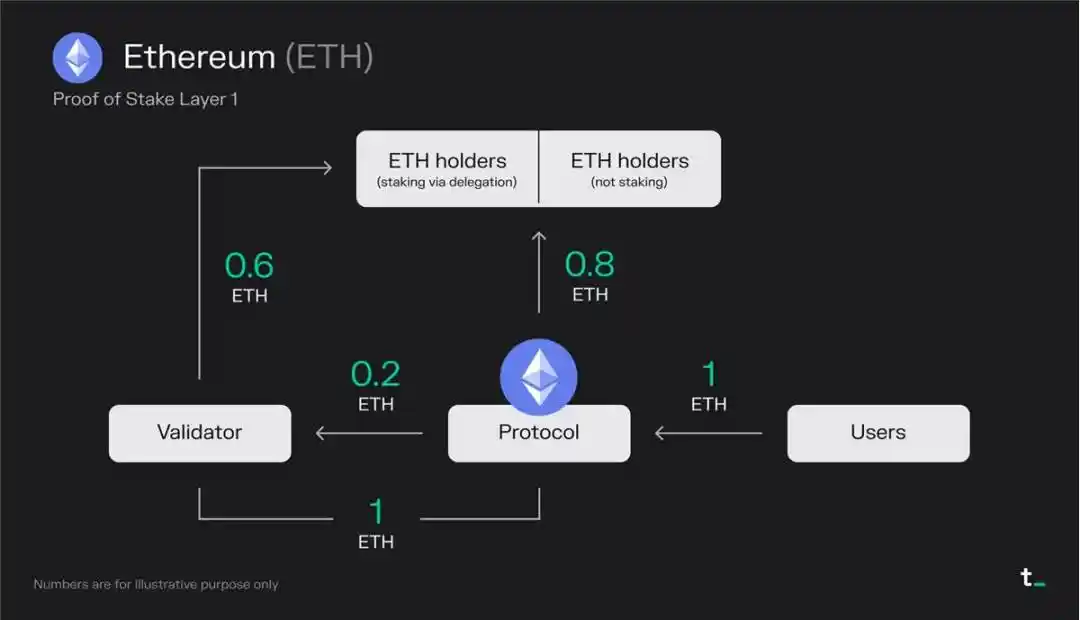
Principle Description:
- The user pays a transaction fee of 1 ETH (including MEV) for a block.
- 0.8 ETH was destroyed -> "stock buyback" benefits all ETH holders equally.
- Validators earn 0.2 ETH from fees.
- Validators receive 1 ETH (newly issued ETH) as a reward from the block.- Due to the fact that the validator has already obtained half of the shares from the principal, the validator must share 50% of its income with these ETH holders.
Final Result:
- 0.8 ETH was destroyed.- Validators received 0.6 ETH.- Holders of ETH who pledge through delegated staking receive 0.6 ETH.
Points:
On Ethereum, approximately 85% of the total transaction fees are burned, effectively serving as a "stock buyback" that benefits all ETH holders. Meanwhile, validators earn the remaining fees and additional staking rewards, namely newly minted ETH. In the past 30 days, Ethereum has collected an average of about $15 million in fees per day.
The fee burning mechanism implemented through EIP-1559 in August 2021 has turned ETH into a productive asset. Additionally, the transition from PoW to PoS has lowered the new issuance rate of ETH. Since the Merge in September 2022, Ethereum no longer distributes block rewards to miners. This change has resulted in a decrease of approximately 90% in the issuance of new ETH (with about 14k ETH/day of block rewards being replaced by approximately 1.7k ETH/day of staking rewards). This has caused a supply crunch of ETH during periods of high usage.
The economic structure of Ethereum consists of three key components: total transaction fees, the portion of transaction fees that are burned, and staking rewards. Transaction fees are determined based on the supply and demand of network block space. Staking rewards are an inflationary reward that increases the total supply of ETH. The burning of transaction fees puts deflationary pressure on the supply of ETH, while the reduction of circulating supply may increase the value of the token over time.
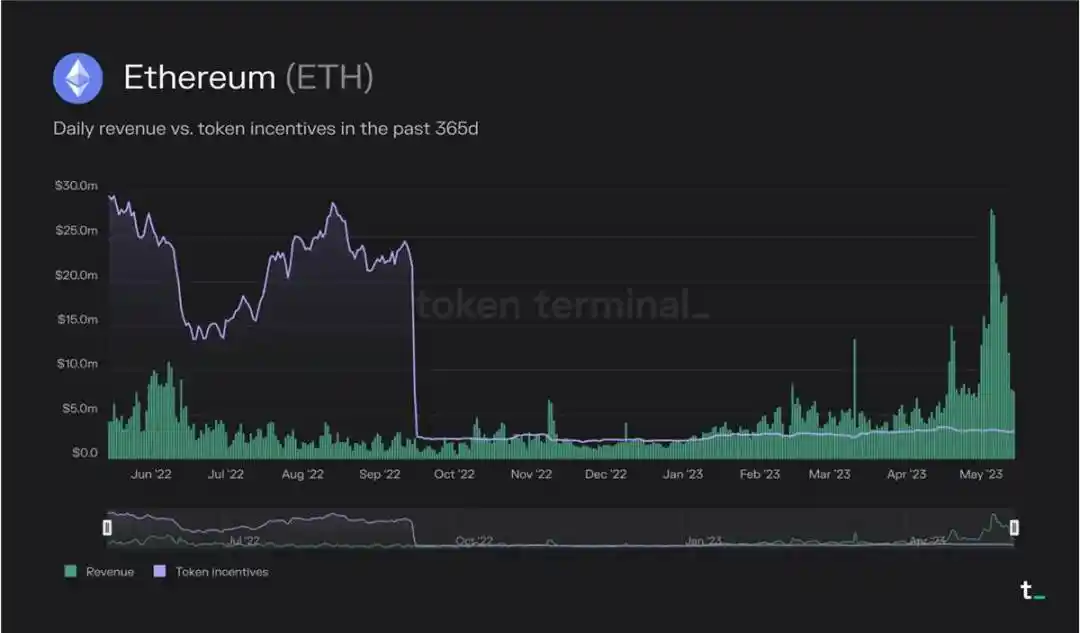
After the merger, the supply of ETH has remained in a deflationary state during periods of high usage. For example, in May of this year, the amount of ETH destroyed (revenue) was consistently greater than the amount of ETH minted as staking rewards (token incentives).
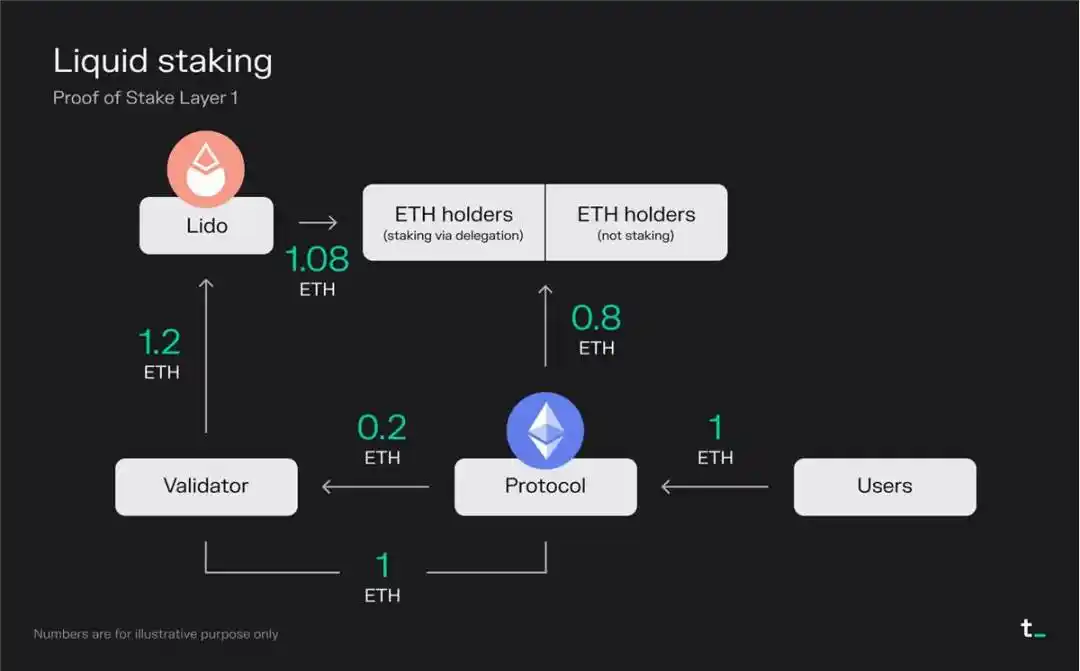
The liquidity collateralization project allows users to collateralize their assets and maintain liquidity through derivative tokens called liquid staking derivatives (LSD) that represent the underlying assets.
Principle Description:
- The user pays a transaction fee of 1 ETH (including MEV) for a block.
- 0.8 ETH was destroyed -> "stock buyback" benefits all ETH holders equally.
- Validators earn 0.2 ETH from fees.- Validator receives 1 ETH (newly issued ETH) from block rewards.
- Validators have obtained full ownership from users who have deposited ETH through the Lido liquidity protocol, and therefore share 100% of the revenue with these ETH holders.- Lido deducts 10% (0.12 ETH) from the total staking rewards provided for its services, and distributes the remaining 90% (1.08 ETH) to ETH holders who stake through Lido.
Final Result:
- 0.8 ETH was destroyed.- Validator received 0 ETH.
- Lido received 0.12 ETH (50% of which is used to pay for node operation costs).- ETH holders who pledge through delegation will receive 1.08 ETH.
Points:
Liquid staking protocol enhances user experience. Staking, essentially a technical and high-maintenance process, has been simplified by protocols like Lido. By allowing users to lock their ETH and receive transferable utility tokens (stETH), Lido facilitates seamless staking while enabling users to earn rewards associated with validation activities. To provide this service, Lido charges a fee of 10% from the total revenue, which is split equally between node operators and Lido DAO.
The technicality and high capital requirements of collateral have opened up opportunities for liquidity collateral protocols. Traditional Ethereum Staking requires users to maintain a node, invest a large amount of capital (32 ETH), and sacrifice token liquidity. In contrast, Lido allocates users' tokens in bulk to validators, eliminating the barrier of 32 ETH. By simplifying the user experience, providing liquidity, and democratizing pledging, Lido and similar protocols are opening up a rapidly growing market.
The democratization of collateral allows for a wider range of investors to participate. In addition to blockchain (L2), the liquidity staking market sector is one of the fastest growing market sectors. The successful execution of the Shapella upgrade (April 12) can be said to reduce the risks associated with investing in ETH, as well as the risks associated with ETH as a revenue asset. Therefore, it is expected that the ETH staking ratio (staking assets/circulating market value) will increase and be on par with other PoS chains. Currently, the staking ratio of ETH is about 15%, which is relatively low compared to other PoS chains. For example, Solana and Avalanche currently have over 60% staking rates. Given the high market value of ETH, which is about $220 billion at the time of writing, we can expect billions of dollars in staked assets to grow in the coming quarters.
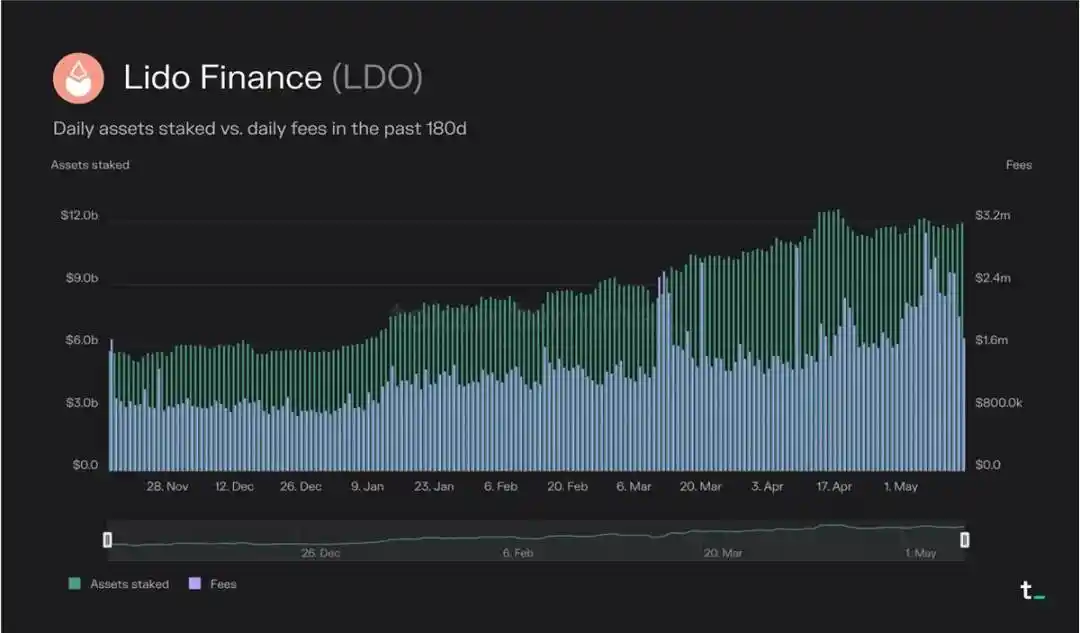
Lido has become the current market leader in the field of liquidity staking, with a total staked asset value of 12 billion US dollars. This number has increased by 38% year-on-year and by 105% in the past 180 days.
In the past 30 days, Lido has generated $60.4 million in expenses and earned 10% of it, which is $6.04 million in revenue. The revenue is split 50/50 between node operators and Lido DAO.
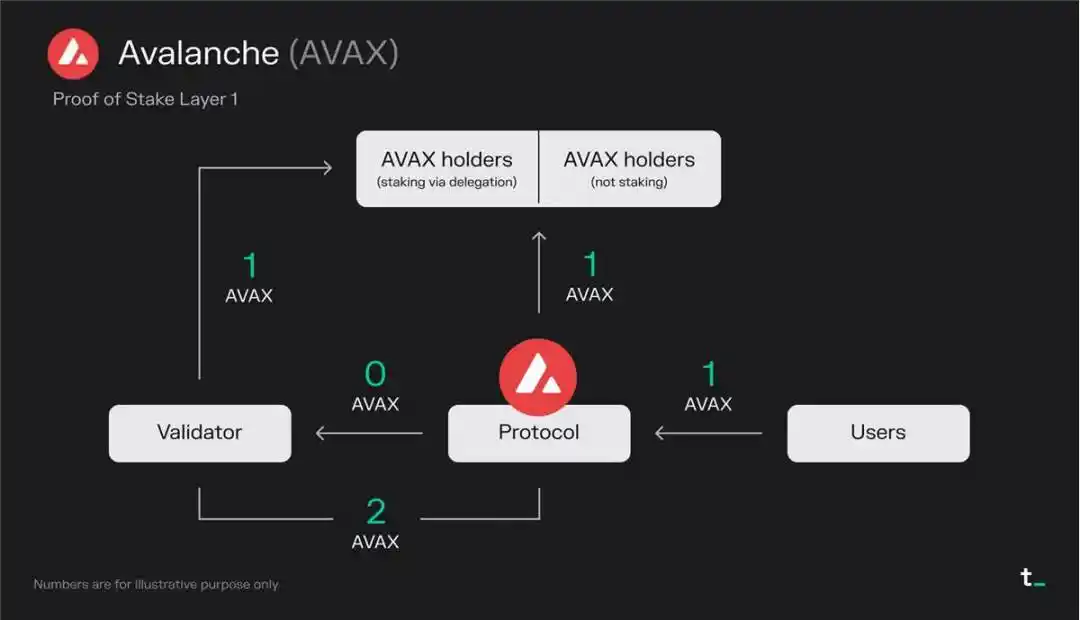
Avalanche is a type of blockchain (L1) that competes with Ethereum by prioritizing scalability and faster transaction speeds. It uses a novel consensus algorithm that provides strong security, fast transaction finality, and high throughput while maintaining decentralization.
Principle Description:
- The user pays a transaction fee of 1 AVAX for a block.
- 1 AVAX has been destroyed -> "stock buyback" benefits all AVAX holders equally.
- Validators earn 0 AVAX from fees.
- Validators receive 2 AVAX (newly issued AVAX) as a reward from the block.
- Due to the fact that the validator has already obtained a portion of the shares from the delegator, the validator must share its income with those AVAX holders.
Final Result:
- 1 AVAX has been destroyed.- Validator received 1 AVAX.
- By entrusting the pledged AVAX, the holder will receive 1 AVAX.
Points:
On Avalanche, all transaction fees are destroyed, and the only source of income for validators is staking rewards. The destruction mechanism serves as a "share buyback" and is equally beneficial to all AVAX holders. In the past 30 days, the average daily fee on Avalanche has been approximately $64,000.
As a relatively new member in the blockchain industry, Avalanche is issuing a large amount of AVAX tokens to reward its validators. This approach is commonly used as a way to guide growth in the early stages of a platform. These rewards attract validators and stimulate growth and activity within the Avalanche ecosystem.
Avalanche's economic model may change in the future. The fee and reward structure is not set in stone and can be adjusted based on future governance decisions. Currently, 50% of the total supply of AVAX tokens is allocated as staking rewards for validators. This allocation plan takes place over a period of ten years, from 2020 to 2030. As the staking reward allocation eventually comes to an end, we may see some transaction fees redirected to validators in the future.
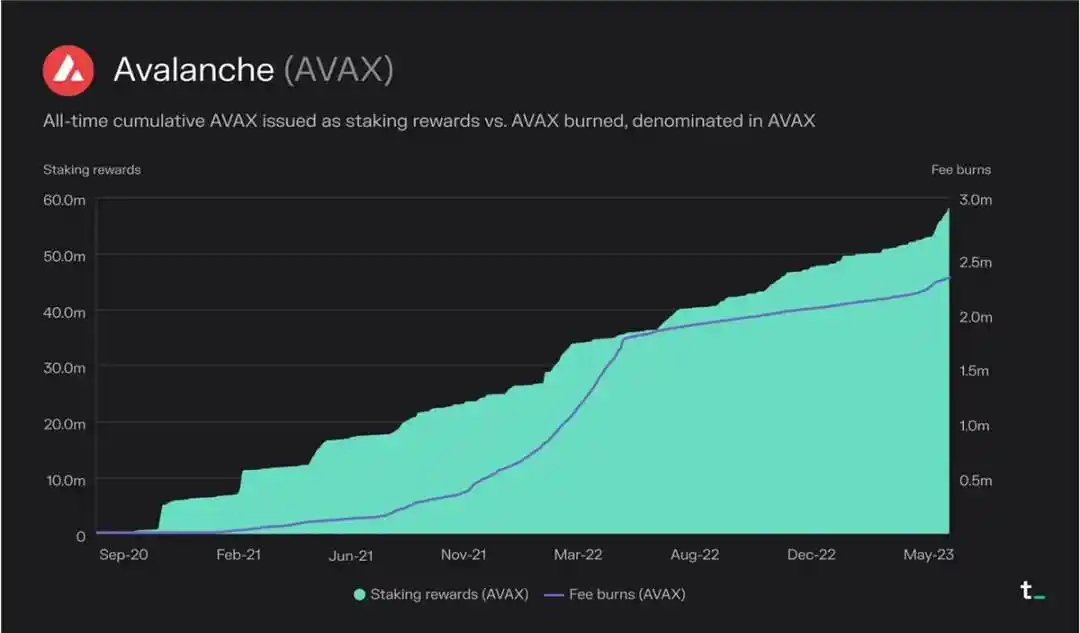
Since the network launched in September 2020, approximately 2.3 million AVAX have been destroyed and approximately 57 million AVAX have been distributed as staking rewards.
Based on PoS L2
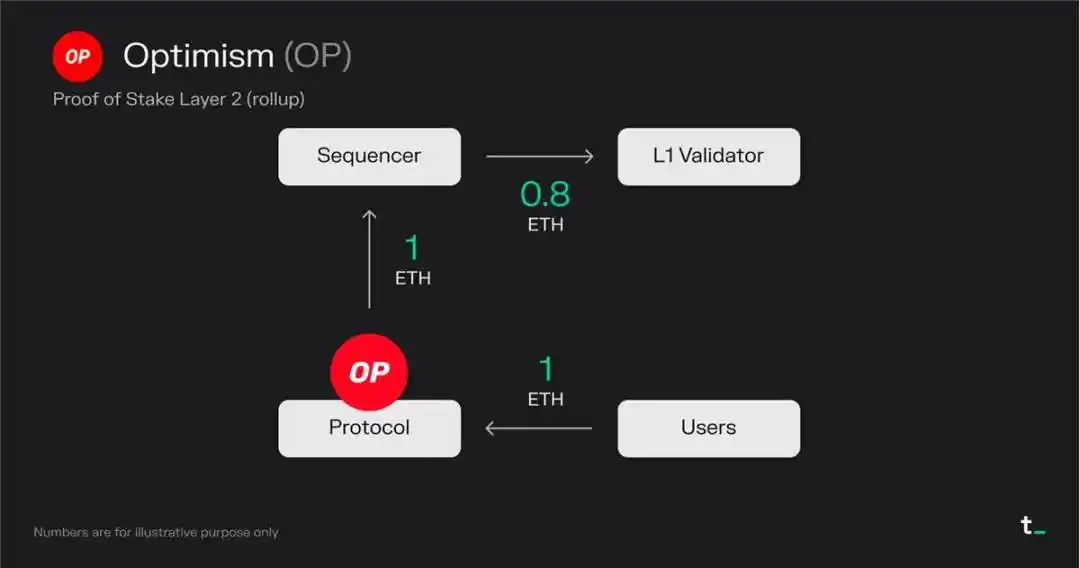
Optimism is an expansion solution aimed at making Ethereum better by increasing its transaction speed and throughput. Optimism executes transactions on L2 and batches them for final confirmation on L1. Depending on the transaction type, this results in approximately 5-20 times gas reduction.
Principle Description:
- The user pays a transaction fee of 1 ETH for a block.
- All transaction fees (1 ETH) go into the sequencer operated by the Optimism Foundation.
- Sequencer pays a transaction fee of 0.8 ETH to submit the transaction to L1 (Ethereum).
- Sequencer (in this case, Optimism Foundation) reserves 0.2 ETH as profit.
Final Result:
- 0 ETH has been destroyed (excluding destruction on Ethereum).- The sorter received 0.2 ETH.- The L1 validator received 0.8 ETH.
Points:
The second layer of blockchain expansion applications. L2 blockchains allow widely used L1 applications such as Uniswap, Blur, OpenSea, etc., to move their transaction activities from L1 to a separate chain, which regularly settles their transactions back to L1. Currently, more than 30% of Uniswap's transactions come from L2.
The second layer of blockchain supports a more optimized user experience. As an L2, this application can optimize the user experience for its use cases (such as transactions) (transaction fees/MEV collection and rebates, on-chain privacy, etc.). These optimizations can be implemented while still maintaining transaction records on a more secure L1.
The economics of Layer 2 blockchain are driven by two variables: the fees charged by L2 and the cost of settling transactions on L1. The main business model of L2 blockchain is to generate revenue by reducing the transaction fees paid by users. Profit margins are determined by the cost of settling transactions on L1. For example, since its launch, users on Optimism have paid a total of $38.2 million in transaction fees. Of these fees, $28.5 million were used to pay gas fees to submit transactions to Ethereum. Therefore, Optimism captured the difference, which is $9.7 million, as revenue. As competition intensifies, profit margins for L2 blockchain are expected to decline. L2 blockchains that can optimize their gas expenditures on Ethereum through data compression and other technologies to further reduce L2 fees may gain market share in the future.
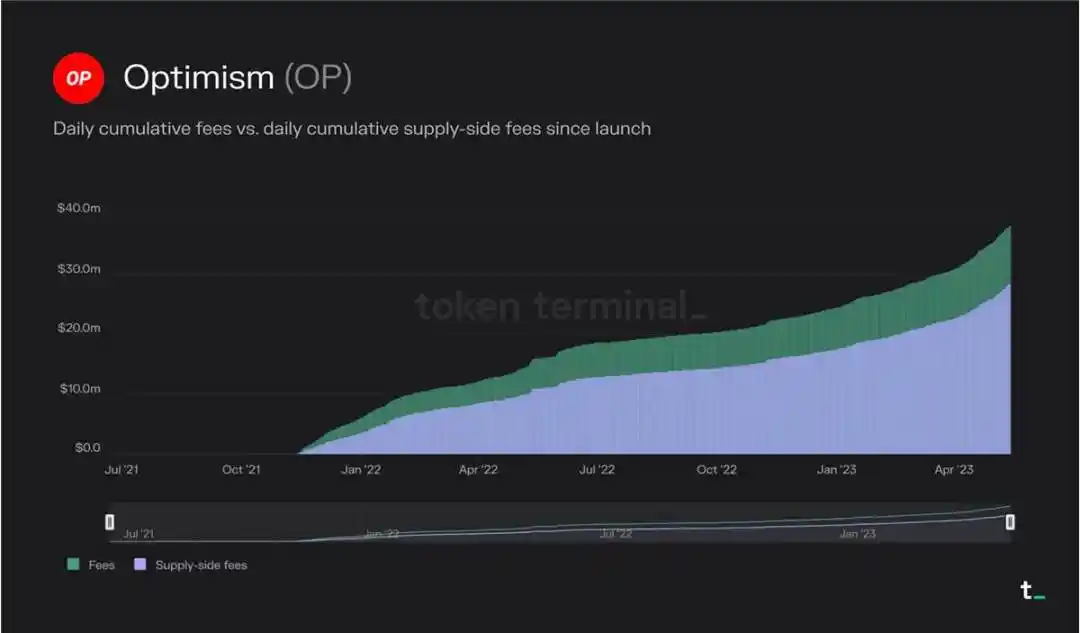
Since its launch, users on Optimism have paid a total of 38.2 million US dollars in transaction fees. Of these fees, 28.5 million US dollars were used to pay for gas fees submitted to Ethereum.
Conclusion
Blockchain is redefining the infrastructure of economic activity by providing a decentralized, secure, and transparent transaction processing architecture. In rapidly evolving industries like cryptography, we see constant innovation in the economic models of these computing platforms. Despite differences, investors can use the above framework to compare their economic performance, potential, and sustainability.
Original Link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia







