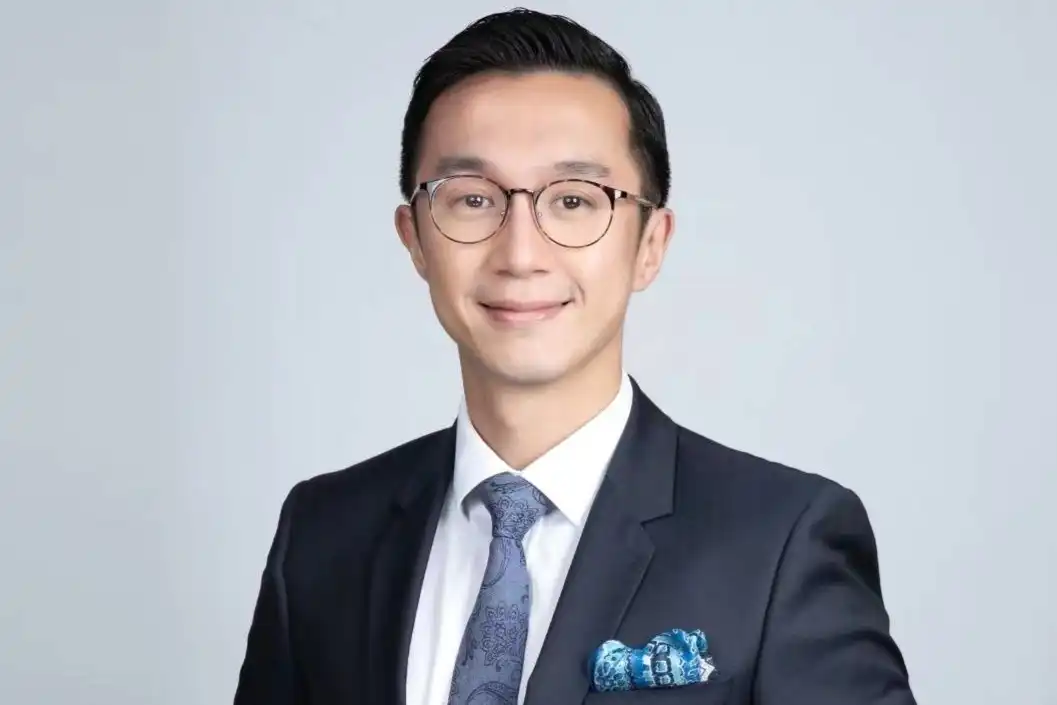
Hong Kong Fintech Advisory Group Chairman: Strong regulation will be implemented on DeFi and relevant enterprises need to be licensed to operate
Chairman of Hong Kong Fintech Advisory Group: DeFi will be subject to strong regulation, related companies need to be licensed to operate
Wu said blockchain
Speaker: Mr Choi Chung-fai, Interim Head, Intermediation Division, Securities and Futures Commission, Hong Kong (Chairman, Fintech Advisory Group)
Good morning. It is an honor to be invited to speak at this wonderful festival. In the past few years, there have been many amazing developments and breakthroughs in various technologies. For example, we are already seeing companies integrating AI into their operations, and central banks, financial institutions are exploring the benefits of using distributed ledger technology (DLT). Just a few weeks ago, I experienced firsthand the wonder of Chatgpt.
The potential applications and materialization of related technologies are huge. We've seen news reports that financial firms are testing the tool and using it to write research reports. I must admit, the idea of using Chatgpt to write this speech also came to mind. But I gave up because this kind of technology has its own limitations and errors, including the fact that it sometimes generates wrong answers to questions. Let me give you an example. An asset manager asked Chatgpt to give him ten stocks that could benefit from virtual reality.
Chatgpt provided seven names, and from the remaining three, the manager found that Chatgpt had made up three false names. This example underscores the importance of taking advantage of innovative technologies in a responsible manner. As with the advent of DLT-based web3, it promises to bring huge economic benefits and has the potential to change the way the Internet and we interact. We must also be aware of potential risks and manage them properly.
To be clear, the SFC (Hong Kong Securities and Futures Commission) recognises the opportunities presented by web3. In fact, in her speech at last year's Hong Kong Fintech Week, Ms Julia Leung, our Chief Executive Officer, said that SFC has noticed the potential impact of web3, virtual assets, NFT, metacomes and GameFi in our daily lives, and we support the underlying DLT technology development and innovation, So let me take this opportunity to share with you today: two very important themes related to SFC policy initiatives -- the centralized Virtual Asset trading Platform (VATP) and decentralized Finance (DeFi).
So let's start with DeFi, as with the evolution from Web 2.0 to Web 3.0, enabling a decentralized Internet that delivers the power of fintech to users and puts it into practice. DeFi advocates building a decentralized financial ecosystem, adopting distributed ledger technology (DLT), virtual assets (VA) and smart contracts to provide financial services, discarding traditional financial intermediaries. The original idea of DLT was to democratize finance, making DeFi accessible to anyone with an Internet connection and a wallet capable of storing virtual assets. Proponents argue that if the ideas behind DeFi are upheld, the financial services industry is poised for a seismic paradigm shift.
In DeFi, we are already seeing many products and services similar to traditional finance, including trading, lending, asset management, insurance and derivatives. However, the DeFi faces some unique challenges.
First, financial stability issues arise from within the DeFi and the virtual asset (VA) ecosystem, as well as the interconnectedness between DeFi and traditional financial products. Financial stability risks also arise from leverage. For example, in a VA loan agreement, users can use VA as collateral to obtain more loans. Second, the interrelationships and connections are less transparent because of the lack of data and the fact that many of the companies and activities involved are not currently regulated.
Third, the DeFi ecosystem faces market integrity issues such as price manipulation, front-running, and other types of abuse. Finally, it is worth noting that the growing scale of cyber attacks raises investor protection concerns. For example, in March 2022, the NFT gaming platform "Axie Infinity" suffered a massive hack that resulted in the theft of $625 million worth of assets.
You may ask whether regulation is feasible in the face of DeFi's uniqueness. Indeed, it is difficult to regulate DEFIs for a number of reasons. First, who is responsible when something goes wrong? Traditional financial intermediaries cannot operate independently, and in some DeFi protocols, developers or operators cannot modify smart contracts once they are deployed on the blockchain.
In addition, the governance of DeFi products or services may be decentralized to varying degrees and may involve the use of governance tokens or decentralized autonomous organizations. Governance token holders (which may include the original developers of the smart contract) can vote on product changes such as new product features.
In such decentralized governance situations, it can become very difficult to identify the individuals responsible for defining the product or service. This question begs the question of whether DeFi services are controlled by smart contract developers, some or all governance token holders. Second, regulation is made more difficult by DeFi's autonomy and the challenge of identifying the developers and operators of the DeFi protocol. This challenge is further compounded by the cross-border nature of DeFi's products and services, as its developers and operators may be located in multiple jurisdictions.
I will now share with you the views of the Securities and Futures Commission (SFC) on DeFi. The SFC aims to ensure that financial activities subject to its supervision are defined by applying the same existing regulatory framework, as long as DeFi activities fall under the Securities and Futures Ordinance (SFO).
Following the "same risk, same approach" principle advocated by the SFC, DEFIs will be subject to the same regulatory requirements as traditional financial entities. Persons engaged in or performing such activities shall be subject to licensing requirements and regulated by the SFC to clarify that the provisions of the automated trading Service are activities regulated by the SFO. If a decentralized platform allows trading in securities or futures constituting the SFO, then the platform and its operators will need to be licensed for Category 7 regulated activities.
In Hong Kong, the provision of collective investment schemes (CIS) to the public must comply with the authorization requirements under the Securities and Futures Ordinance (SFO), as DeFi liquid capital pool agreements that meet the definition of CIS may require compliance with these legal requirements. Arrangements to provide virtual asset (VA) deposits, savings, earnings and services to Hong Kong investors, some of which may constitute CIS under the regulation of the SFC and may even be in fact an illegal collective investment scheme (ICIS).
The challenge of determining who bears responsibility for the DeFi may in fact not be entirely insurmountable. The SFC will evaluate each DeFi service or activity on a case-by-case basis after understanding the inner workings and arrangements of the DeFi agreement. However, in terms of some of the challenges mentioned earlier, it is worth noting that some DeFi agreements may be decentralised in name only.
In practice, a small number of developers, operators, or interested parties may still have control, for example, they may hold the vast majority of governance tokens or have the power to make decisions on governance recommendations made by the audit. Therefore, when analyzing the problem, it is important to focus on the actual solutions of these arrangements, not just how they advertise their projects.
Next, I'll talk about centralized virtual asset trading platforms (VATPs). Today, SDCS are more focused on centralized VATPs, as the majority of virtual asset (VA) transactions take place on these platforms. This point of contact with investors raises investor protection issues, which explains why the SFC introduced sweeping regulatory measures for VATPs in 2019, specifically for VATPs that offer at least one security token trading service. The regulatory regime covers the requirements applicable to traditional brokers and automated trading platforms, with some adjustments for VA specific risks.
Now, this means that we not only regulate VATP from an anti-money laundering perspective, but also from an investor protection perspective. The regulatory requirements cover areas such as safe custody of liquid assets, conflicts of interest, cyber security, prevention of market manipulation activities, as well as setting access procedures for bad transactions. As you may know, following the passage of the Anti-Money Laundering and Counter-Terrorism Financing Amendment Bill 2022 by the Legislative Council, the SFC is seeking to implement a new licensing regime covering centralised VATPs. When the system came into effect on June 1 this year, centralised VATPs that allow non-security token trading, all centralised VATPs operating in Hong Kong, regardless of whether they offer security token or non-security token trading, must obtain our licence.
The cryptocurrency market turmoil itself reinforces belief in the need to set record regulatory standards and develop appropriate guardrails for VATPs to protect investors, market integrity and market stability. While this episode shows that the market for virtual assets is not large enough to cause systemic risk concerns, we must not forget the cases that have caused harm to consumers.
Retail investors, for example, suffered from the implosion and collapse of Celsius, a virtual asset lending platform, and FTX, a centralized exchange. News coverage following the FTX failure revealed a range of issues, including a lack of basic governance and risk management controls, conflicts of interest and, more importantly, abuse of such assets, which would not be tolerated in any regulated entity.
These failures show that it is essential for VATP to have a robust risk-management mindset, which is the area covered by our existing regulatory regime for VATP. That is why, when the SFC issued its consultation document, we effectively translated the comments under the existing regulatory requirements into proposals for a new regime, with certain amendments based on market developments and experience with the operation of the current regime. Under the current system, the SFC imposes conditions on operators that restrict them to providing services only to professional investors.
This requirement will be relaxed, subject to additional GAAP accounting rules designed to protect investors. This includes requiring VATP to understand the customer's risk profile during the account opening process to assess whether it is appropriate to provide such services and to set appropriate limits. Ensure that the type of exposure is reasonable by referring to the client's financial situation and personal circumstances. In addition to requiring VATPs to develop criteria for due diligence and access to VAs for trading, the SFC also recommended that VAs offered to retail investors meet additional access criteria, which would qualify them as qualifying large market virtual assets.
Now, given the turmoil and scandal in the virtual asset ecosystem, I believe everyone will agree that the SFC-licensed VATP must put in place appropriate controls and risk management measures to prevent similar incidents from happening in Hong Kong. The SFC's consultation on the proposed regulatory requirements under the new regime ended on 31 March.
I would like to take this opportunity to thank those market participants and interested parties who reviewed the consultation document and provided feedback on the proposals. This engagement and constructive dialogue with industry cannot be stressed enough to be essential for the development of SFC policy. We will carefully review all comments received to ensure that the regulatory regime for centralised VATPs in Hong Kong is robust, effective and strikes the right balance between investor protection and support for innovation.
In conclusion, the SFC fully supports the use of new technologies to provide financial services and products in Hong Kong. We need to embrace scientific and technological innovation, be alert to potential risks, and speed up our commitment to protecting market investors. I firmly believe that with the concerted efforts of the government, regulators and industry, Hong Kong will eventually become not only an international financial centre, but also a premier hub for web3 and virtual assets. I hope you enjoy this activity. Thank you very much.
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles