Bixin Ventures: What can we expect from Ethereum Shapella upgrade?
Bixin Ventures: What can We Expect from the Ethereum Shapella Upgrade?
原文作者: Henry Ang, Mustafa Yilham, Allen Zhao, Jermaine Wong & Jin Hao
原文编译: Evan Gu,Evie Xie & Vivian Fang
Where are we on the Ethereum roadmap?
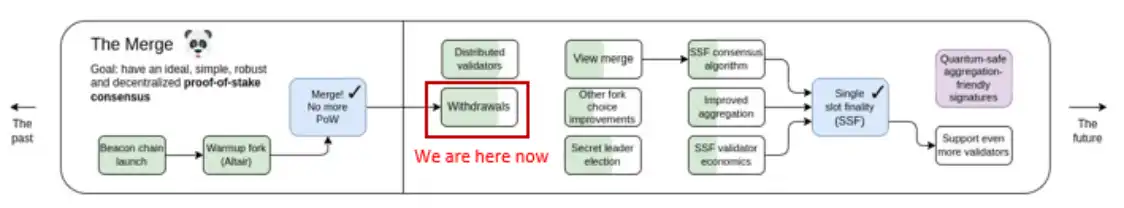
The Ethereum merger lasted through 2022. Ethereum passed the Paris upgrade, transitioning from proof of Work (PoW) to Proof of Equity (PoS). On April 12, Ethereum will carry out Shanghai and Shapella upgrade, pledged ether coins can be withdrawn, Ethereum will be completely transformed into a proof of equity mechanism of blockchain.
In the post below, we'll share the background of the "Shapella" upgrade, its impact on the $ETH price, who the beneficiaries are, and what's next on the Ethereum roadmap.
Background of the Shapella upgrade.
Although Shapella appears to be a single change to Ethereum, it's actually a merger of two names that were upgraded at the same time -- Shanghai and Capella. Ethereum's executive tier will get a Shanghai upgrade, while its consensus tier will get a Shapella upgrade.
While the Shanghai Upgrade consists of five EIPs, the most important of these is EIP-4895, which enables withdrawal of all Ether tokens in Ethereum's consensus layer (beacon chain) that have been pledged and locked by verifier since its launch in December 2020. Shapella is the third major upgrade to the Consensus layer and is designed to facilitate this process, not only allowing blocks to process withdrawal requests, but also implementing account cleansing capabilities, which we'll describe in more detail later.
Once the Shanghai and Shapella upgrades are completed, ETH withdrawals will be available in full or in part.
Partial withdrawal
Partial withdrawals involve only those amounts in excess of the 32 ETH required to run the verifier. This account cleaning (or "scraping") happens automatically and periodically to any active verifier that has been updated to the new withdrawal credentials.
This feature is extremely useful for two main reasons:
Since the verifier award does not automatically reinvest, this mechanism can improve the capital efficiency of the pledge fund. The pledgee will be allowed to reconfigure his excess ETH for other benefits without having to pay any Gas charges.
In addition, partial withdrawals prevent long exit queues and excessive verifier rotation, which would require the verifier to completely exit the beacon chain in order to access its rewards, potentially destabilizing the network.
Since only 16 partial withdrawals occur in each period, the frequency of drawdown is heavily dependent on the total number of qualified verifiers. Validators should expect partial withdrawals to be between 2 and 5 days apart.
Full withdrawal
If a verifier chooses to "opt out" completely as an active verifier of the network, the 32 ETH and all rewards accrued since its creation will be retracted, and the process will result in a full withdrawal.
Similar to other PoS blockchains, verifiers will have a release period during which they will wait until they receive their full pledge and reward balance. The length of this release period is determined by the sum of two variable times, the time required for the verifier to exit the Ethereum consensus layer and the time required for the entire withdrawal process. Therefore, a verifier seeking to make a full withdrawal should expect at least 261 epochs or 28 hours.
Another factor to consider is the flow limit. This defines the maximum number of verifiers that can exit the consensus layer per epoch, a number that increases as the total number of active verifiers increases. There are currently approximately 525,000 verifiers, with eight quits allowed per epoch, which translates to a maximum of 1,800 verifiers quits per day. Consensys explains in detail how these estimates are achieved in the article.
What does this mean for the price of $ETH?
With over 18 million ETH pledged on the beacon chain to date, it's not hard to see why investors were so worried in the months leading up to Shapella's upgrade. On the face of it, enabling drawdown should result in a supply shock that would put significant downward pressure on ETH prices. But what will the real impact be?
Status of existing ETH pledges
To estimate the potential price impact, we need to first assess the state of existing mortgagees and the decisions they are likely to make. We believe these decisions are largely driven by the financial situation of the pledgee. In other words, is the ETH pledge making a profit or a loss?
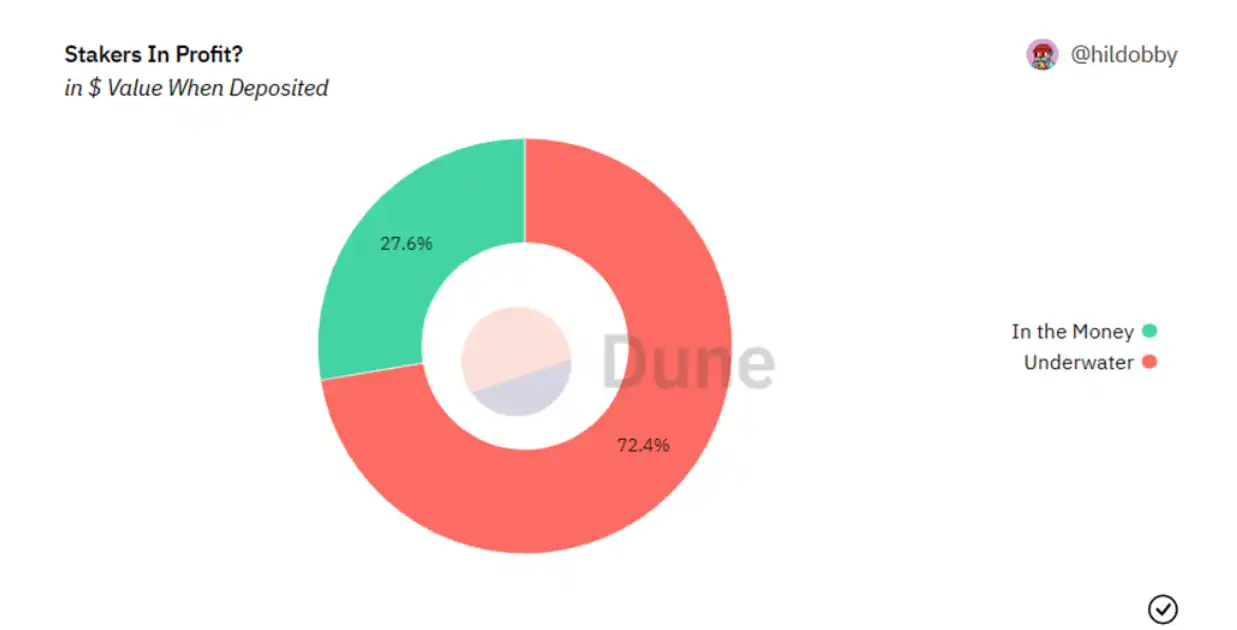
Dobby data board, provided by hildobby, shows that only 27% of ETH borrowers are actually profitable, based on the value of their assets, and 73% are lossmaking. Based on this data, the pledgees realize the loss of selling the current ETH, so that they can get the reward of remortgaging, so as to maximize the future income.
The amount pledged under a liquidity pledge agreement
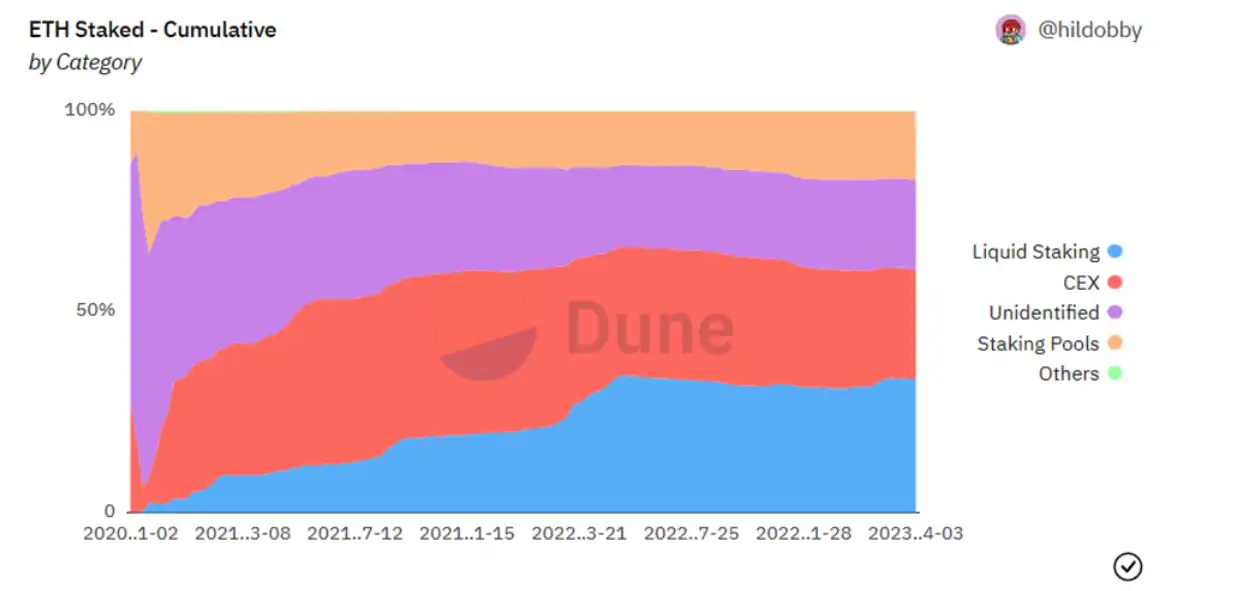
Another factor is to consider how much ETH has been pledged through liquidity pledge agreements (LSPs). At the time of writing, according to DefiLlama, the number is over 30% (and closer to 45% if you include the amount of pledges on Coinbase), with the majority of ETH pledged to Lido.
In the case of the Lido, stETH automatically readjusts to take into account the cumulative rewards earned by the liquidity pledge. This means that users who choose to pledge in Lido can "capture" ETH rewards by selling them on the secondary market. Therefore, for the verifier behind the Lido, direct withdrawals are less stressful and have more flexibility to deal with excess rewards.
We believe that these validators will make better use of these excess incentives by expanding their number of validators rather than selling them. Thus, this further reduces the overall downward pressure on ETH prices arising from withdrawals and inflows.
$Indicates the ETH price
Now that we have considered the potential key factors that determine the possible sale of ETH incentives, what does this mean for the $ETH price?
"If we assume that the verifier will sell 50% of its pledged ETH awards (as opposed to its primary pledged ETH), we expect 553,650 ETH to be sold. On a 7-day amortization basis, this equates to about 1% of daily ETH trading volume (both spot and perpetual futures) sold per day.
Based on the overall risk environment and ETH's general liquidity situation during the expected Shanghai upgrade in early April, we believe the impact of this volume will gradually extend to a slight decline in ETHUSD. The other view is that the smooth progress of the Shanghai upgrade is an overall bullish factor for Ethereum as a technology, so ETHUSD goes up." - the Galaxy
While we can't provide a price forecast, we would like to share Galaxy's perspective on the possible outcomes based on partial and full withdrawal execution volumes, which we highly recommend reading.
Regardless of where the price ends up, we believe Shapella will open up new opportunities for Ethereum. We will share the details below.
Beneficiaries of the Shapella upgrade
Liquidity pledge agreement
The Shapella upgrade could be a bullish catalyst for liquidity pledge agreements (LSPS) from a variety of perspectives.
As ETH can be extracted, LSPS should be able to maintain their respective liquidity derivatives (LSD) and ETH price linkage more easily and economically. This allows LSDS to borrow collateral better, as a tighter peg helps limit price volatility and thus reduces liquidation risk. Coupled with the growing adoption trend of LSD in the Ethereum DeFi ecosystem, this will be an opportunity for investors to pursue higher capital efficiency gains.
The tighter peg also facilitates ETH's liquidity pledge, which is more like a "risk free" or benchmark interest rate for investors. They have been wary of long-term pegs, which depend in large part on the supply and demand balance of various pools of liquidity. There have been recent failures (with stETH devalued due to massive selling on the curve) that have been impressive.
For the above reasons, we expect that most of the extracted ETH and idle ETH will flow into LSPS, and their adoption rate will further increase. However, which LSPS are better prepared than others? We'll look at some of the different LSPS below, covering what they do, their flywheel effects and feedback paths, and how these LSPS give users more control over their extraction keys, NFT utilization, and additional benefits through MEV strategies.
Lido Finance (LDO, stETH)
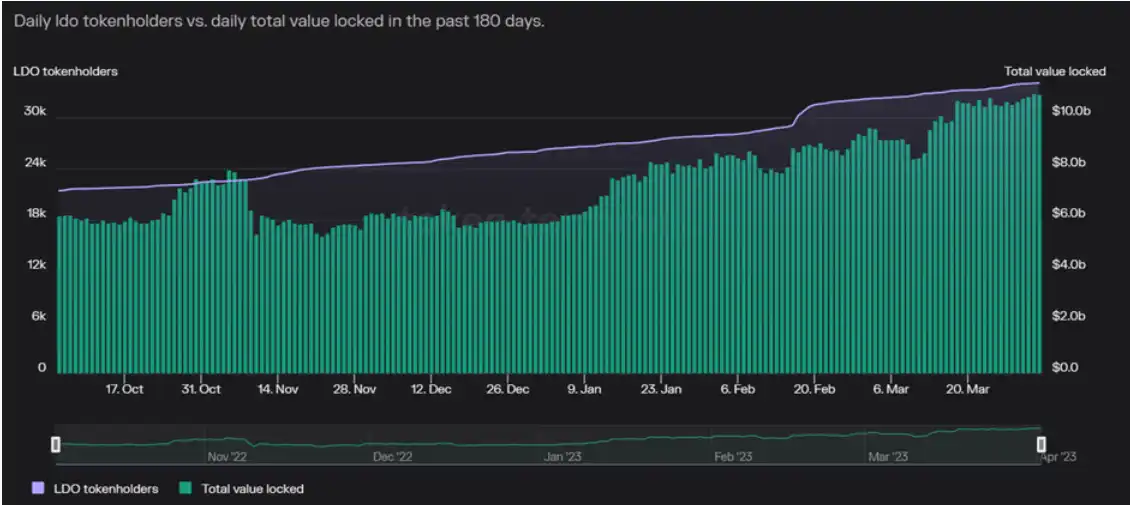
After the upgrade, it is clear that Lido's TVL will grow significantly to become a leader in the LSP space. With a strong reputation, deeper liquidity and extensive DeFi integration, those looking for liquidity pledge programs have good reason to choose Lido. Since November, the number of Lido token holders and TVL have been on an upward trend, accounting for nearly 75% of ETH's total pledges to date.
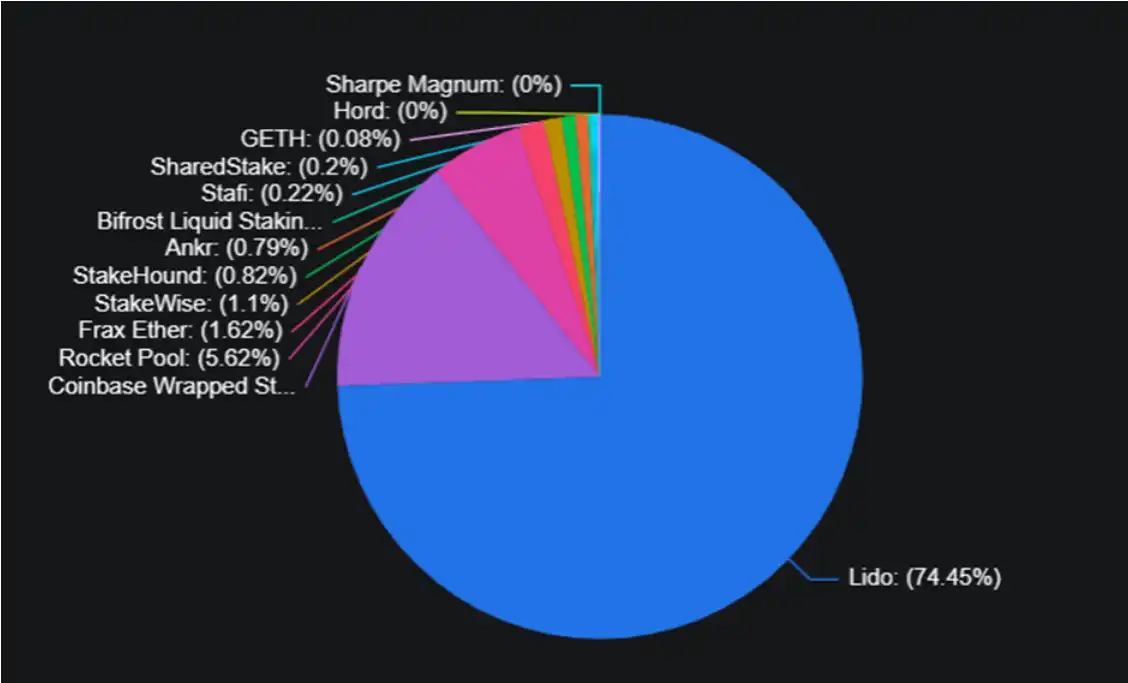
With the more and more strong position of Lido in LSP track and the centralization problem, coupled with the more intensive governance review after Arbitrum incident, governance system will be more important than before. While it is commendable that they have taken steps to include stETH holders as part of the LDO holder governance system, users who want to help decentralize ETH tokens may also consider the other alternatives we have listed below. Lido also recently announced that its upcoming v2 will be a step toward further decentralization and is built around two major upgrades: drawdown and pledge routing.
Swell Network
Swell Network is also an upcoming LSP designed to provide users with higher pledge yields. Currently, their latest version, Seawolf, is running on the Goerli test network, and Swell is preparing to launch on the main Ethereum network in late April after the Shapella upgrade. While the initial collaboration with a set of licensed specialist node operators will continue to provide large-scale, reliable benefits to users in a competitive environment, subsequent iterations will see the set of operators expand and eventually become non-licensed, with sufficient liquidity, stability, and risk mitigation technologies, such as DVT, in line with the value orientation of the agreement.
Swell's liquid pledge token, swETH, will be a token with a payoff that increases in value as rewards accumulate on the chain. Users can be rewarded through consensual-level rewards (such as pledge revenue) and execution-level rewards (such as priority fees and MEVs). Users who pledge in the Swell Network also have access to vaults that run revenue-enhancement policies, all within their dApp. Swell will be the lowest-cost pledge program on the market, with no agreed pledge fees.
Rocket Pool (RPL, rETH)
Rocket Pool seems to have some advantages over more dominant players like LDO, such as a more decentralized network of node operators and a lower capital requirement for node operations (only 16 ETH). However, it also has its own disadvantages. These drawbacks include higher performance charges compared to competitors and the fact that node operators must lock up a percentage of the value of the ETH they pledge in the RPL as collateral for agreement insurance.
Despite this higher friction for users who want to operate nodes from Rocket Pool, the advantages of the upcoming Atlas upgrade may more than offset it. The Atlas upgrade, scheduled for release on April 18, brings several improvements, including increased protocol efficiency, increased node operator incentives, and greatly increased rETH capacity, while maintaining the protocol's completely license-free nature. One of the most important features is the introduction of eight ETH mini-pools, which will further reduce the minimum capital requirement. At the same time, this feature can result in higher returns for node operators and rETH pledges, providing up to 18% additional returns when users run two 8-ETH mini-pools instead of one 16-ETH mini-pool. While this is good for Rocket Pool's future development, it remains to be seen whether the update is really effective in attracting TVL and market share from its competitors.
Frax Finance (FXS, frxETH/sfrxETH)
Frax's market share has grown rapidly this year to become a strong competitor, and it still has a strong future. This growth is easily related to Frax's top pledge annualized yield of around 5.6%, as well as its dual token model. In this context, frxETH acts as a stablecoin loosely linked to ETH, and sfrxETH is a pledged version of frxETH that can receive pledge rewards. With this design, Frax enables frxETH holders to earn income in a number of ways, namely by pledging to receive sfrxETH and validator rewards, or by providing Frxeth-Eth liquidity on the Curve. Together, these two options not only create deeper frxETH liquidity, but also increase the annualized returns in the sfrxETH and Curve liquidity pools.
Like Rocket Pool, Frax is scheduled for a post-Shapella upgrade that could be a powerful catalyst for adoption. The frxETH v2 upgrade plan increases decentralization by enabling unrestricted validators, which are run by the protocol itself. In addition to this, a proposal was recently passed to use FXS bribes and incentives to kick-start liquidity for future frxETH trading pairs, creating a powerful flywheel that theoretically should eventually lead to increased value for FXS and frxETH, as well as generating higher yields and attracting more liquidity for LSD. DWF Labs ZhouYeMen explains this topic in great detail here.
Ether.fi (eETH)
Ether.fi is another decentralized LSP coming to market, but it has some important distinguishing characteristics. Ether.fi uses an unmanaged equity protocol where users generate and hold their own ETH key. Another feature is that it utilizes NFT, casting for every verifier initiated through the protocol. These FTTS control the rights to 32 ETH and store validator related metadata such as clients, geolocation, node operators, and any node services. The eETH of Ether.fi is then cast from the liquidity pool of these NFT.
The combination of these two mechanisms enables users to submit exit commands themselves, rather than the usual node operator. Repossessed pledged ETH will be deposited into a withdrawal safe deposit box where users will be able to net reclaim their ETH by destroying their NFT. This successfully reduces the significant and opaque counterparty risk that users have in other LSPS, while ensuring that there is always enough ETH liquidity for eETH holders to redeem. As a result, we expect Ether.fi to be one of the LSPS that will see a surge in users and TVLS after Shapella.
In the future, Ether.fi plans to use EigenLayer to create a market for node services, where users and node operators can sign up for their minted NFT, provide node infrastructure services, and share revenue from those services with users and node operators. Currently, Ether.fi offers institutional equity mandates, services for customizing investment structures, and the development of early adopter programs for retail liquidity equity. With ETH extraction enabled, institutions may also view ETH equity mandates as viable investments, and Ether.fi is positioned as one of many beneficiaries.
Manifold Finance (FOLD, mevETH)
Manifold is also a new entrant to the LSP space, launching its MeV-optimized, multi-chain LSP less than a week ago. mevETH is implemented as a full-chain universal token (OFT) that can be bridged directly between chains without a wrapper, making it the most compostable LSD to date. Meanwhile, mevETH is designed around MEV capture and uses Manifold LSP's unique and novel MEV approach to provide users with additional benefits in addition to mortgage income. One way to do this is by arbitraging the peg between ETH and mevETH, not only providing a means of additional revenue, but also helping to strengthen the peg relationship.
Manifold has said it aims to accumulate 100K ETH by the end of the year, about a sixth of the ETH currently mortgaged by Lido. As LSD is gradually integrated into existing DeFi protocols, mevETH's high composability is likely to propel it to become the adoption leader, creating a strong market share for itself.
The point about LSD
Regardless of which agreement ultimately benefits the most from the Shapella upgrade, ETH mortgage participation will almost certainly increase due to the increased attractiveness of liquid mortgages, whether due to natural escalation or protocol-driven development. Based on mortgage ratios in other PoS chains, such as Polygon and Solana, it seems likely that ETH mortgage ratios will increase to the 40-70% range, at least 2x higher than the current 15%. While this may raise the specter of an eventual decline in mortgage yields and greater supply inflation, it also opens up a number of other opportunities and possibilities, which we will explore below.
DeFi
Pendle Finance (PENDLE)
Pendle is a yield trading protocol that allows users to execute various yield management strategies by encapsulating income tokens and splitting them into two tokens - PT, which represents principal, and YT, which represents income, both of which can be traded via their custom AMMs. 1 PT gives the user the right to redeem the underlying asset at maturity, a date determined by the initial token holder, while 1 YT gives the user the right to receive proceeds on the underlying asset prior to the maturity date. This allows Pendle to essentially create income markets that enable users to pursue a variety of strategies, including holding assets for the long term at a discount, targeting the annualized rate of returns, and even earning fixed income with low risk and steady growth.
Similarly, locked ETH users can use Pendle to split their stETH into 1 PT stETH and 1 YT stETH, and then use Pendle's custom AMM to trade either token and place directional bets on the proceeds. With the upcoming Shapella upgrade and the expected pledge yield declining over time, one possible trade stETH holders could take is to sell YT stETH at the current price for a differential gain based on their existing earnings.
Pendle's TVL has experienced a sevenfold surge since December, with more users discovering its potential. More than a third of that can be attributed to LSD, including stETH and frxETH, according to DefiLlama's token TVL breakdown. With Pendle's latest integration of sfrxETH, we may see an increase in the proportion of LSD in Pendle's TVLS.

Gearbox (GEAR)
On the topic of leverage, the closer connection between LSD and ETH after the Shapella upgrade above reduces liquidity risk and unlocks the feasibility of leveraged ETH pledge. Gearbox is a two-way lending marketplace that connects users looking to offer their assets through passive and secure APYs with leverage enthusiasts looking for additional capital. The agreement introduces leveraged liquid pledge derivatives, known as LLSD, as a one-click strategy that enables users to locally pledge up to 10 times the value of their ETH collateral for higher pledge returns of up to 12% compared to the 4.3% APR currently offered by Lido.
So far, the strategy has been enabled for Lido's stETH and Coinbase's cbETH (pending DAO vote), and the plan is that once Frax and Rocket Pool have their Chainlink Seers, Integrate its frxETH and rETH. As the foundation layer of leverage, Gearbox is positioned to benefit indirectly from the projected increase in the number of ETH pledges and the growth and adoption of LSPS and LSD, as more ETH pledges look for relatively low-risk ways to increase their pledge gains. Over the past few months, stETH has accounted for more than a third of Gearbox's total credit account, TVL, or about $22 million.
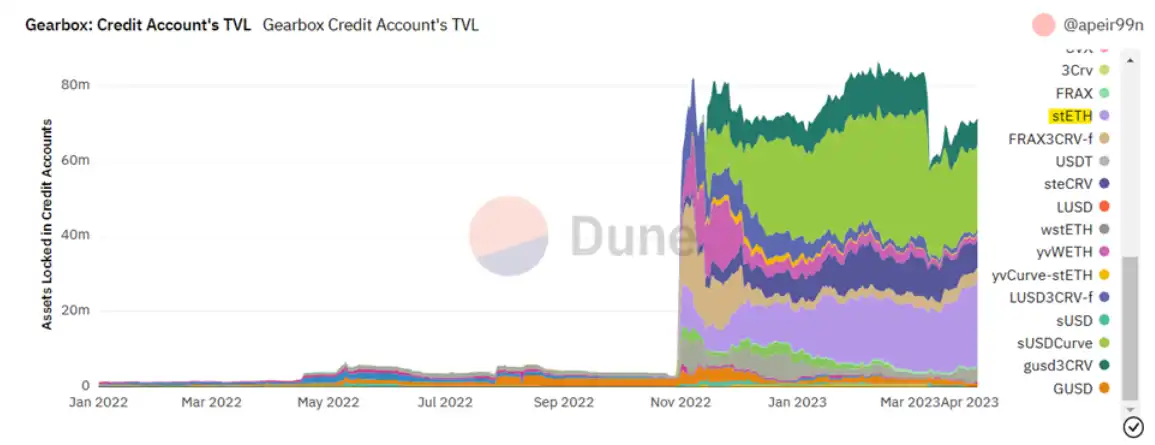
With the launch of Gearbox v3 just around the corner, one can expect new features, such as automated portfolio management and health factor maintenance, to further motivate LSD token holders to take advantage of Gearbox's leverage capabilities and push it to the forefront of DeFi.
Flashstake (FLASH)
Flashstake is another novel protocol that introduces a unique mechanism to increase the capital efficiency of user assets. Users deposit and pledge their assets, lock in the current annual rate of return, and coin time-based derivatives (TBDs) corresponding to their holdings. Users can then burn or exchange these TBDs for an upfront income on their assets, retrieving their principal deposit after the selected lock-up period. This is particularly interesting given that ETH mortgage yields are expected to decrease over time. Flashstake enables early adopters to not only secure and fix the current (and reportedly highest) ETH mortgage revenue for up to 1 year, but also to continue generating revenue elsewhere.
Understandably, this may raise some eyebrows. Where do these advances come from? To provide this revenue to users, Flashstake employs a three-pool approach consisting of a revenue pool, a liquidity pool, and an acceleration pool.

Unlike loans, Flashstake's pool-based approach also ensures that assets deposited by users are always 100% collateralized and are not exposed to any liquidation risk. Isolation of each vault policy also provides an additional layer of security for users, as any potential attack impact is limited to the affected vault. With its strong value proposition and innovation mechanism as well as its strong security, the total lock-in value of Flashstake seems well positioned to benefit from the influx of liquid ETH and the increase in mobile proof of interest.
repledge
EigenLayer
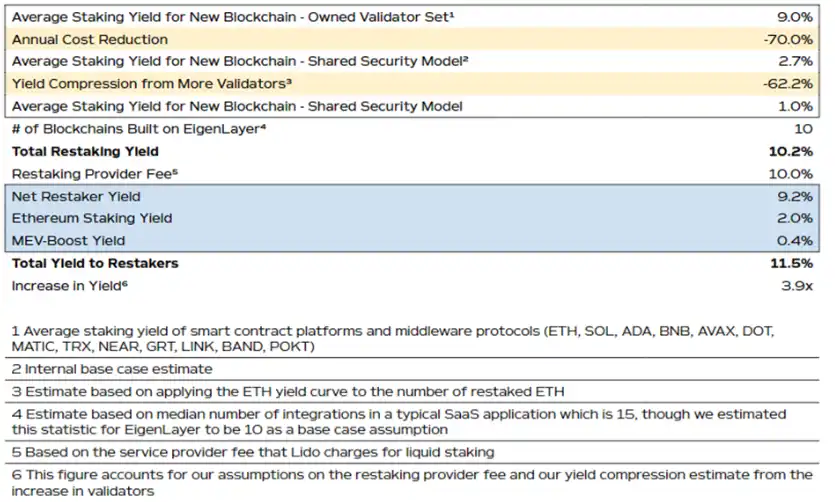
With the Shapella upgrade able to extract Ethereum, ETH using EigenLayer contract locking can be withdrawn and reduced if malicious intent is detected. This paves the way for EigenLayer to become a decentralized layer of trust built by applications, on which existing ETH holders can choose to use their pledges to secure new applications on EigenLayer. EigenLayer's remortgage mechanism provides users with an opportunity for incremental revenue beyond what they would have gained by simply pledging ETH and receiving MeV-related rewards, while at the same time achieving its main purpose, which is to modularize Ethereum's trust layer and enable a wide design space for new middleware and adjacent chains.
Finality Capital Partners expects ETH remortgagors to earn up to 11.5% APY by 2028, with an estimated underlying ETH pledge yield of around 2.0% in 2028. This 2.0% pledge yield is based on their expectation that the pledge ratio of ETH can reach 60% instead of the current 15%. As a result, we see remortgaging through EigenLayer becoming a common practice for ETH holders, particularly those looking for relatively low-risk ways to increase yields.
New innovation
Ion Protocol
Despite some success in increasing the adoption of LSD in DeFi, there is still great friction today. Because there are many different LSD and liquidity pledge designs, a DeFi protocol that integrates each of them will require multiple customizations and novel solutions. For example, Uniswap could not accept stETH equal-base LSD from Lido, while blue-chip protocols such as Aave and Maker required the creation of separate vaults and pools for different LSD tokens. This results in a fragmented and shallow liquidity of LSDS, which leads to increased slip points and inefficient price discovery, defeating their original purpose of representing the pledged ETH and distributing the proceeds of the pledge.
Among its many goals, Ion Protocol aims to provide a solution to the above problems by aggregating deposits of various existing LSD tokens into a common unit of account using a dual token model. This common unit of account will allow for better frictionless integration into DeFi, taking full advantage of the full potential of LSD, using it as low-risk, yield-generating collateral and even increasing capital efficiency through leverage.
UnshETH (USH)
UnshETH promotes the decentralization of the verifier through incentives, directing more revenue to the less dominant LSPS. This is done through a new class of primitives called LSDfi, including verifier decentralized mining (vdMining) and verifier Dominated Options (VDO).
vdMining is a token allocation mechanism that rewards users when they invest more in LSPS that meet predefined optimal decentralized ratios, while VDO is a mechanism that allows holders of dominant LSD to sell "put options" on their verifier's dominant percentage, Strike prices are set at a percentage lower than their current dominant position. If the dominant position falls below the exercise price at maturity, the VDO holder will lose a portion of the proceeds, which will be distributed to the holders of other LSDS. These two mechanisms combine to incentivize new stakeholders to do so with less dominant LSPS, and to incentivize more existing dominant LSD holders to spread their capital across various LSPS.
New features planned for the Shapella upgrade are also in place, including routers for pledging ETH liquidity and others that will help improve the utility of UnshETH's native token USH. The next step is to see how much UnshETH's TVL will eventually capture and whether it can become a de facto revenue solution for ETH holders as collateral.
Zero Liquid (ZERO)
Zero Liquid is another new protocol, possibly a new track for LSDfi, that issues self-financing loans for users' LSDS. Similar to more traditional money market protocols such as Aave and Euler, users first deposit the asset as collateral and are then able to obtain a loan for a portion of the value of their collateral.
In the case of Zero Liquid, the user is able to deposit LSD and native chain tokens (ETH, MATIC, etc.) as collateral and obtain a synthetic version of the asset as a loan. However, these loans are characterized by their 0% interest and self-repayment nature, which, combined with the use of synthetic assets, allows the agreement to provide a zero liquidation model. Zero Liquid does this by automatically paying off debt using the proceeds generated by the user depositing collateral.

While the protocol has yet to officially launch its products, one can already anticipate many unique use cases in addition to maximizing user assets, and it is very convenient in these areas. With zero liquidity, users can basically invest and buy without any upfront capital. With some similarities to the real-world "buy now, pay later" model, making payments through Zero Liquid's products will allow users to buy or "consume" immediately and pay only with the future yield (or time, depending on how you look at it) of the collateral they deposit.
Like UnshETH, Zero Liquid introduces entirely new models and mechanisms to solve existing problems faced by users, while unlocking potential and increasing the use cases for LSD. Still in their infancy, both protocols have a lot to prove about PMFS and their practical ability to engage users to achieve the goals they set out to achieve, but there is no doubt that these new developments provide reasons for greater optimism in LSD.
What happens after Shapella?
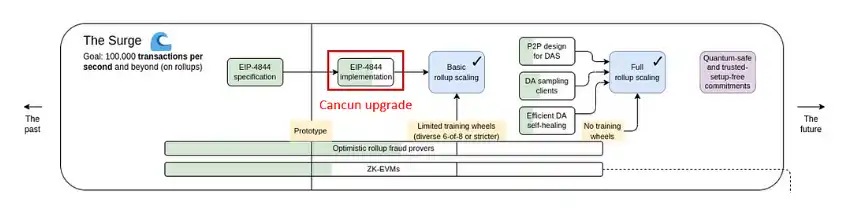
After Shapella, the next much-anticipated Ethereum upgrade will be the Cancun upgrade, which is part of the expansion roadmap. While Tier 2 expansion solutions such as Optimism and Arbitrum have reduced costs by more than eightfold, data storage remains expensive, accounting for more than 90% of transaction costs.
The EIP-4844 aims to reduce the cost of L2 rollup by 10-100x by introducing proto-danksharding into Ethereum and inaugurate a new era of low-cost on-chain activity. It provides support for implementing Danksharding schemes (e.g. transaction formats, validation rules). Ip-4844 introduced temporary "blob" storage that could be removed from Ethereum when no longer needed. Ethereum is expected to deliver over 100 times throughput and reduce transaction costs to less than $0.001.
Other possible improvements in the Cancun upgrade include the six Eips accumulated over the years in the EVM Object Format (EOF) group, which aims to better construct bytecode, or computer object code, that interpreters can convert into binary machine code for computer hardware processors to read, Making systems faster, more efficient, cheaper, and more secure. One of these has been included in the previous London upgrade, some may be in the upcoming Shanghai upgrade, and the rest may come along with the Cancun upgrade. These EIP will support the implementation of EOF2, a new extension of EOF that revolutionizes the control process.
The immediate beneficiaries of the Cancun upgrade will be rollups and users that can be deployed directly for Dapps. New applications will also be able to benefit from this upgrade, thanks to significantly reduced transaction costs, such as lower on-chain order book costs, and decentralized physical infrastructure networks will be able to take advantage of faster L2 transactions and settle to the trusted Ethereum foundation layer. We'll explore these opportunities further as Cancun upgrades.
This article is from submission and does not represent the views of BlockBeats.
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles