Crypto Winter's spin-off Disaster: Silvergate and Abra's Death
Silvergate Explodes as Crypto-Friendly Banks Suffer
Original source: R3PO
On January 5, the Wall Street Journal reported that crypto-friendly bank Silvergate had handled $8.1 billion in withdrawals after the FTX crash, and cryptocurrency-related Deposit Q4 plunged 68%. To meet the demand for withdrawals, Silvergate liquidated the debt it held on its balance sheet and took a huge discount.
Silvergate, which topped $200 at the cryptocurrency's peak in 2021, is now trading at $11, wiping out nearly 95% of its market value. Silvergate's fall, no doubt to Web3 investment institutions sounded the alarm that the development of the crypto banking circuit may be negatively affected.
R3PO will analyze the impact of Silvergate incident, crypto banking circuit and competing product Abra case on the business degree of crypto banking circuit.
Silvergate suffered a huge run on FTX
Silvergate (SI) was originally a community retail bank based in California, providing financial services to local small and micro businesses. With its transformation into a crypto-friendly bank and the provision of bank clearing services for Coinbase, Gemini, and now scandal-plagued FTX trading platform and trading firm Alameda Research, Silvergate achieved a "quality" transformation and landed on the NYSE in late 2019.
The market reaction to SI's share price, which has fallen more than 80% over the past three months, reflects two concerns: 1) SI may have credit exposure to FTX/Alameda in its Bitcoin mortgage portfolio (approximately $300 million as of September 30, or approximately 27% of tangible common stock); 2) SI will see a large outflow of deposits due to the market crash.
Investors' fears have recently been validated by the market.
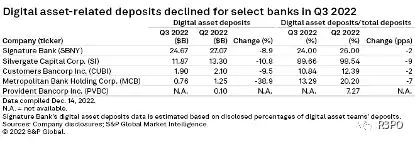
Digital currency deposits plunged nearly 70%
Total digital currency deposits fell to $3.8 billion at the end of the fourth quarter, down 68% from the previous quarter, with deposits as low as $3.5 billion during the quarter and Silvergate's customer bankruptcy-related deposit losses of $150 million. According to the 8-K disclosed by Silvergate on November 16, the size of its digital currency deposits was $9.8 billion, down $2.2 billion from the average digital currency deposits of $11.9 billion in Q3-22.
Source: S& P Global
Selling assets in response to a run
Silvergate sold $5.2 billion of bonds it held on its balance sheet in Q4 2022 to meet withdrawals and took a large discount loss. Since 2013, the bank's $718m loss on debt sales has far exceeded its total profits. Resulting in a loss of $718 million. At the end of the third quarter, the Company also had approximately $427 million of HTM securities portfolio losses not carried to book value. From management's statement regarding the closing balance sheet, fair value securities at the end of the quarter were approximately $5.3 billion (company cash was approximately $4.6 billion).
Lay off workers and trim operations
Silvergate announced a 40% layoff of about 200 employees, which is expected to result in cumulative charges of $12 million related to employee severance and benefits. It also said it would reduce its business and shelved plans to develop its own digital currency through the $196 million acquisition of Diem. Because the company is "no longer in a rush to launch blockchain payment solutions in the current market environment."
R3PO believes that the subsequent Silveragate Bank is affected by many factors:1) The Company may be subject to further potential regulatory penalties; 2) Weaker crypto markets, tighter crypto regulation, and lower-than-expected deposit growth; 3) Considerable uncertainty about the regulatory environment for cryptocurrencies may cause the company's share price to continue to decline,SI's business and development are still likely to remain depressed for a long time.
2023 May see the end of some unprofitable crypto banking
While crypto penetration has increased over the past few years, banking and financial services for crypto assets are far from universal, so interest in the sector has increased, with crypto-friendly banks trying to capture deposits flowing into the digital asset ecosystem, and some experimenting with using cryptocurrencies or cryptocurrency mining equipment as collateral for loans.
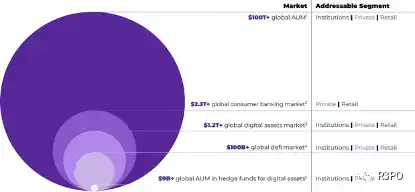
As of October, about 80 financial institutions under the supervision of the Federal Deposit Insurance Corporation have expressed interest in cryptocurrency related activities, of which about 24 are active participants, hoping to provide service dynamics from the $1.2 trillion global digital asset market. In particular, crypto-friendly banks stand at the bridge between fiat and digital currencies. Serves the widest range of institutional and retail users.
Source: Abra Company Data
Industrial market segment
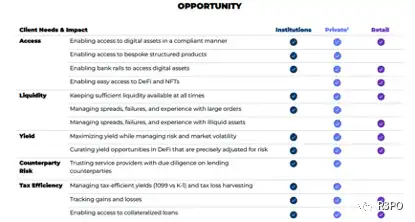
In the big industry of cryptocurrency storage, there are segmented industrial markets such as custody, banking and CeFi, and each segmented industry participant also provides a diversified product portfolio. Compared with the trading platform attribute of Coinbase, Signature and Silvergate only provide basic cryptocurrency deposit transfer function, while CeFi organizations such as Celsius and BlockFi provide complex financial products without regulatory security and compliance. The path for crypto banking is to cover as many product requirements and features as possible along the compliance path to gain revenue.
Source: Abra Company Data
Crypto asset banking business model
The main source of bank income is interest income and non-interest income. Non-interest income, also known as fees, is not the main source of income for banks; Behind the core of bank income is net interest income. When you deposit cash into a bank account, the bank may offer you an interest rate of 1%, which is interest expense to the bank (they pay you). This cash is then lent to another customer at an interest rate of 3%, which is the bank's interest income. Net interest income is the spread between interest income and interest expense, and in a competitive market, the only way to create that spread is to take some risk. The two most common are: credit risk: the risk that a borrower will not repay; Interest rate risk: The risk of market interest rates changing if you lend for more than one day.
In cryptocurrencies, there are two important risks: liquidation risk: the loan is over-collateralized, but you expect to be able to liquidate the collateral to avoid any losses; Protocol risk: Blockchain is code, and code can be exploited to the detriment. The banks we're going to look at today are full reserve banks, and they don't bear these risks.
In the real world, deposit differences between banks are fairly small because regulations, such as Basel III, use the liquidity coverage ratio (LCR) and high quality liquid assets (HQLA) to define how much high level of funds banks should keep. It creates homogeneity.
As we have seen, every bank has a goal: to increase the amount of deposits in the bank so that they can charge the difference between the interest rate on funds and the interest rate on investments and other fees.
R3PO believes that crypto bank is the same as traditional bank. Its business profit comes from non-interest income and net interest income generated in the deposit-payment-loan chain of fund flow. The business model of crypto asset bank benefits from the following businesses:
1. Transaction fees shall be charged for fluctuations in the overall volume and trading volume of the cryptocurrency market.
2. Deposit accounts that attract cryptocurrencies charge account-related fees,
3. Charging interest to crypto mortgage customers
4. Charge a commission for the flow of funds generated by linking the Defi and NFT entries
5. Interest charges and rebates from credit card issuers and merchants are charged to credit card users
6. Charge management fees and performance fees for the self-operated capital management business
R3PO believes that for cryptocurrency banks, how to manage balance sheets to meet solvency and liquidity constraints while optimizing the spread between funding and investment rates will determine who is the king of the track and the winner will be a trillion-dollar company.
However, with the market value of cryptocurrency dropping from nearly $3 trillion in November 2021 to below $1 trillion at present, investment institutions' investment confidence in the cryptocurrency industry is shaking, and the business of participants in the crypto banking circuit is also greatly affected.
, Provident Bancorp Inc. delayed filing its third-quarter Form 10-Q as it evaluates the actual level of losses incurred by troubled cryptocurrency miners
, Voyager Digital Ltd accounted for about 70% of the $485.9 million drop in crypto-related deposits at Metropolitan Bank in the third quarter of 2022
, Signature Bank, whose clients had $24.67 billion in digital-asset-related deposits as of Q3 2022, said it would cut its cryptocurrency-related deposits to $8 billion to $10 billion in Q1 by 2023
, Silvergate Bank's 2,022Q3 customer digital asset deposits were $11.9 billion, while recently disclosed Q4 data showed that deposits fell to $3.8 billion, a 68% sequential decline
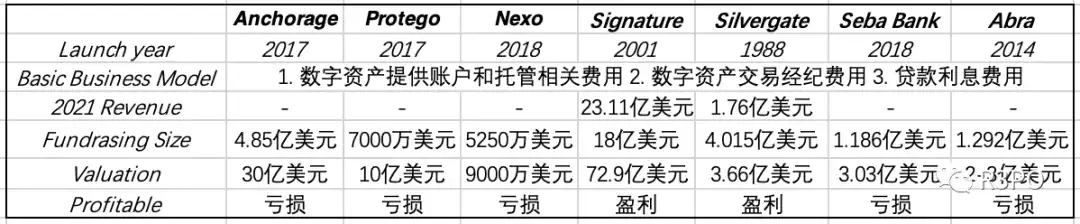
R3PO believes that as the leading players in the crypto banking circuit shrink their business, some crypto banks that are still unprofitable will face a dual dilemma of revenue generation and financing in 2023 or even an end.
Abra continued to bleed during the bear market
R3PO got word that as a favorite on the Crypto Bank circuit,Abra had just completed a $22.6 million bond financing in December 2022, and had just disclosed that it was cutting jobs and restructuring its business.Crypto investment manager Abra is restructuring several of its business lines and considering cost cuts as a buffer against a bear market, according to online media, citing three people familiar with the matter.
Founded in 2014, Abra is a crypto financial services company for institutions and individuals around the world, providing crypto asset trading, custody, investment, interest collection, lending, payment and credit card services. Abra's business exploded due to the rapid expansion of the crypto market in 2021, and in September 2022,Abra Bank expects to receive its first fully regulatory U.S. banking license in January 2023,Will enable U.S. citizens to deposit and bank using digital assets in a manner similar to traditional banking. The bank plans to set up shop in U.S. states and become the first regulated cryptocurrency bank in the country, with plans to later launch a global program, Abra International, to serve clients outside the U.S.
Summary of Key Messages for Abra 2022:
· Cooperated with American Express as a card issuer to provide customers with encrypted credit cards with 2.5% cash back rate
· Focusing on the users of encryption institutions to solve the industry pain points is expected to smooth the industry cycle fluctuations
· In 2022, the company faces a serious loss and not small existential crisis
· U.S. banking license with full regulatory clearance expected in January 2023
The business data of Abra refer to the 2020-2021 business data is very bright. What is worth integrating is the International layout of Abra, the launch of Abra International and the overseas market (Canada, European Union, Japan, etc.).
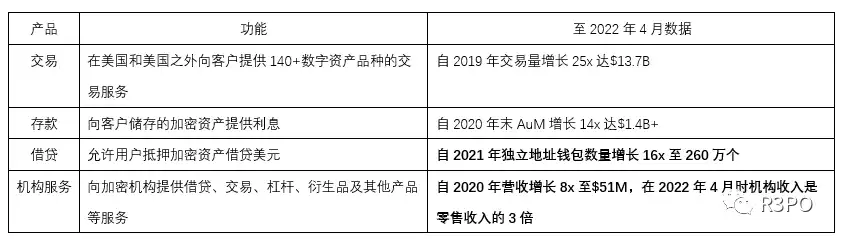
Source: Abra Company Data
Highlights of the Abra 2023 Road map:
· Defi/NFT: Provide access to Defi applications and protocols for institutional and individual customers, and provide NFT custody and storage services
· Cash management: Cash usage services for real-time conversion of crypto assets and fiat currency
· Credit Cards: Partnered with American Express to offer customers an encrypted credit card with 2.5% cash back
· US bank license: Wyoming SPDI bank charter; Ex-US bank license: Bermuda DABA
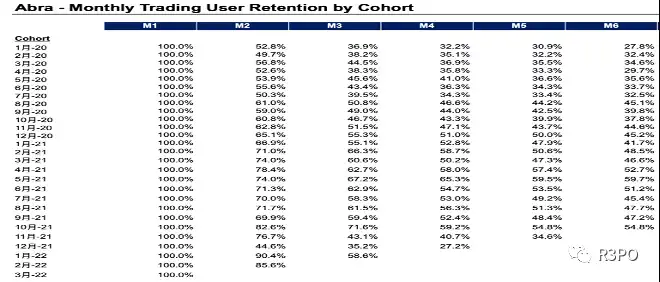
However, the data for the first half of 2022 shows that Abra worryingly, in a banking industry with high retention attributes, the retention rate of Abra users over 6 months dropped below 50%. Even considering the negative impact of the macro environment, this figure still has high room for improvement. At the same time, the average monthly transaction volume decreased by 90% month-on-month in February and March of this year, which is likely to remain at a low level in the 2022-2023 cryptocurrency contraction environment.
Abra's financial situation is worrying
· Abra has a high asset-liability ratio,The parent company, Plutus Financial 2022 H1, has a total of $533M in assets, of which $496M is in stable ratios and cryptocurrencies and $525M in debt.
· Abra faces the problems of reducing expenses, shrinking, loss and increasing profit margin, etc.In the 2022 profit loss statement, Plutus Financial H1 showed a sequential decline in revenue and a rapidly expanding loss. In the first half of 2022, the total revenue was $23M, but the loss was $42M, including negative gross margin in March and June.
· Based on the company's losses from April to June, Abra's cash flow problems occurred in the second half of 2022,2022H1 has $12M of cash on its books, while the cash flow in the first half of the year was -$26M, which is also confirmed by the disclosure of debt financing information in December.As for how long the $22.6 million will last, Abra's timely job cuts and business line changes are part of the answer.
Financing and valuation
· In December 2022, Abra received $22.69 million in bond financing at an undisclosed valuation, with the possibility of a flat round or even a lower valuation.
, In September 2021, Abra raised $55 million in funding led by Ignia and Blockchain Capital, Other investors in the round included Kingsway Capital, AmEx Ventures and CMT Digital Ventures. In this round of financing, based on the amount of financing in the last round and the changes in Cap Table, it is roughly estimated that the last round of financing accounts for 22% of Abraabra. it is estimated that Abra's valuation after investment in the last round of financing is about $250-$300M.
R3PO's view on the Abra aftermarket
1. The business performance of Abra is very bright in the 2020-2021 stage. The company has excellent business growth ability, rich product portfolio and strong product strength.
2.Abra's financial model forecast and past valuation are based on optimistic expectations of the macro crypto market. However, the risk of the depressed macro environment will greatly affect Abra's business acquisition ability and user retention. The operating revenue and profit will decline as a result of the depressed trading.
coda
With the arrival of 2023, whether Abra's subsequent business and license planning development can be realized will determine its subsequent customer growth and financing progress. Whether the crypto banking circuit can be revitalized directly depends on how hot or cold the macro environment of cryptocurrency is. In an increasingly strict regulatory environment, crypto banks will be further and further away from blockchain fundamentalism, and gradually towards the trend of embracing regulation.
R3PO believes that only a cryptocurrency market with sound asset security policies can be watered by traditional funds. The competition for licensing compliance on the crypto banking circuit continues to intensify, but the road to internationalization will be made more difficult by the difficulty of obtaining regulatory licenses in various regions. In the future, the barriers to entry in the US crypto banking market will be gradually raised, and small players may emerge in local, more conservative national markets.
The recovery of rapid growth on the basis of compliance will continue to test the technical strength of each crypto bank, the degree of completion of the blockchain payment network and the comprehensive degree of product portfolio. R3PO will provide more analysis of crypto credit cards and crypto banking licenses in a future post.
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles