Pantera: Thinking about the Importance of decentralized Systems from the FTX bankruptcy
原文标题:《 无需信任系统的必要性 》
原文来源: Pantera Capital
nbsp; NBSP;Baize Research Institute
The FTX crash was a step backward for the industry, but the resulting crypto regulation could be a catalyst for two steps forward for the industry, as regulation would be a necessary catalyst for institutional adoption of cryptocurrencies.
Dear investors, after the high-profile outburst of the last DeFi Summer, we named our year-end letter:
DeFi works well DeFi still works well.
But this year's letter reads:
Regulated exchanges work well.
Before we get to regulated exchanges and other material, I'd like to share a few thoughts on FTX fraud. Many media reports have this version:
"If you can't trust FTX, who can you trust?!?!"
It is usually followed by:
"Blockchain is a failure."
However, the claims of blockchain skeptics, as well as some regulators and politicians, miss the point. The FTX crash had nothing to do with blockchain technology. It's not cryptocurrencies that have failed. Bitcoin and all other protocols work just fine.
"This is really old-fashioned embezzlement. It's just using a client's money for your own purposes. It's not complicated at all."-- John Ray, new CEO of FTX
On 12 December, Sam Bankman-Fried was arrested by Bahamian authorities acting on behalf of the US Attorney's Office for the Southern District of New York (SDNY) after a month of uncertainty. Charges against him could include wire fraud, securities fraud, money laundering and conspiracy. Prosecutors said Mr Bankman-Fried "engaged in a scheme to defraud FTX customers by diverting customer deposits." The money was transferred to Alameda Research, SBF's crypto hedge fund. He also defrauded lenders, the indictment alleges, and prosecutors have cited campaign finance violations for making excessive political contributions "in the name of others."
"The SEC's complaint was even more volubrious. It said that from the early days of FTX, Bankman-Fried had transferred FTX customers' money to Alameda, so that" 'there is no meaningful difference here. Bankman-Fried then "used Alameda as his personal piggy bank to buy luxury apartments, support political campaigns and make private investments. He took out large loans and "on two occasions Bankman-Fried was both a borrower in his personal capacity and a borrower as CEO of Alameda ".
"Mr Bankman-Fried claims that Alameda has no special privileges on FTX platforms. However, the SEC said his hedge fund had access to a "virtually unlimited" line of credit and was not subject to "automatic risk mitigation agreements" designed to ensure the stability of FTX. Client money was mixed up in internal accounts. The end came when cryptocurrency prices fell and "many of Alameda 's lenders demanded repayment of their loans."
-- Wall Street Journal, "Sam Bankman-Fried's Cryptocurrency Meltdown"
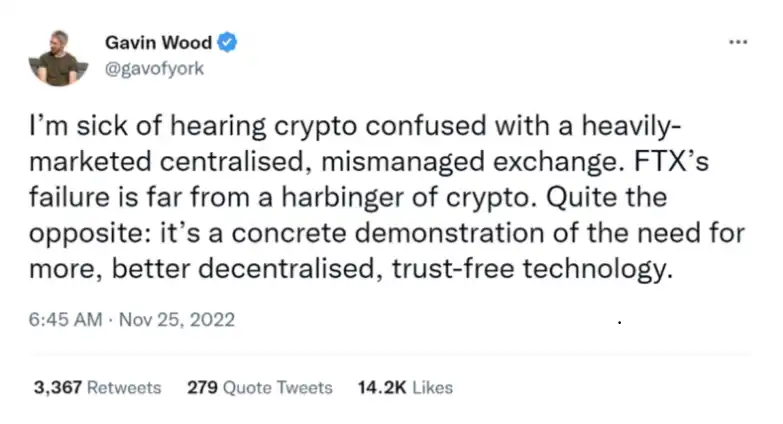
In most ways, FTX's collapse is comparable to that of Three Arrow Capital, Celsius, BlockFi and Voyager. Centralised, opaque, unaudited and offshore entities, and over-leveraged. With the crypto market down 70% and certain things, such as Grayscale's Bitcoin Trust (GBTC) trading at a 49% discount to the bitcoin in the trust, it's no surprise that highly leveraged entities will struggle.
Details are still emerging, but the FTX debacle involved massive conflicts of interest and, apparently, fraud. This pattern is as old as time. Traders, when confronted with a small problem, try to solve it and create a big problem. When the forensic accountants are done, we may learn that FTX/Alameda went bankrupt earlier than the public knows. We estimate the losses would have been much smaller if they had filed for Chapter 11 protection.
"If you can't trust the FTX, who can you trust?
The two-pronged answer is:
Regulated exchanges work well -- Coinbase and Bitstamp, for example
DeFi works well, especially DEX - for example Uniswap, 0x, 1inch, Balancer and DODOFTX are not blockchain related. Blockchain is not failing.
Regulated exchanges work well
Regulated exchanges have been around for a long time, they are transparent, audited and regulated. The answer is already here. There are all sorts of crypto critics and skeptical regulators all talking about blockchain transactions needing some completely different future, but it's already here, and it's been for a long time. On exchanges like Coinbase, Kraken and Bitstamp, when customers send them money, they simply deposit it in the bank.
There's a lot of talk these days about high-tech "reserve proof," but that's only part of the story. This only shows proof of some of the assets on the balance sheet, but no liabilities. The answer is simple: you hire a Big Four accounting firm, and you prove not only that you own the assets, but that you have no liabilities in excess of those assets.
This is nothing new. Nine years ago, Pantera hired Ernst & Young) to conduct the first audit of the cryptographic entity.
As a sign of how deep the understanding of blockchain is - I had to spend New Year's Eve in the office with Wing On in order to complete the audit. I have to prove how many bitcoins we hold. If I can transfer them at noon on a weekday before New Year's -- anyone on their team can verify through the public blockchain browser that the bitcoins are still in the same account after New Year's weekend.
I was chairman of Bitstamp for many years. Four years ago, Ernst & Young was rehired to audit Bitstamp.
Deloitte audited Coinbase. If you store cryptocurrencies on an exchange, exercise the same caution as the auditor.
Regulated, transparent and audited exchanges are gaining market share dramatically. This is essentially winning back customers who fled to unsafe deals overseas in search of more deals, more leverage and lower fees. Exchanges such as Coinbase, Kraken, Upbit and Bitstamp have gained 30 percentage points in market share since October.
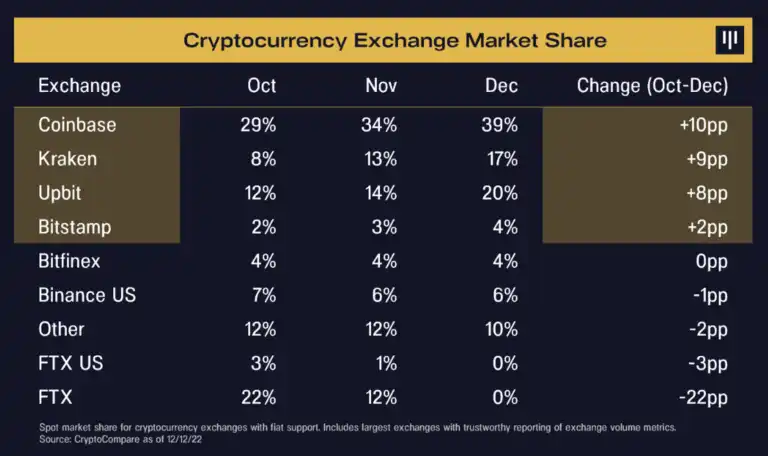
I think that trend is continuing. I hope it continues. It's great for our industry. It would be great if everyone had been using such regulated exchanges for the past few years.
"Based on our review over the past week, we are pleased to learn that many of FTX's regulated or licensed subsidiaries, both inside and outside the United States, have solvent balance sheets, responsible management and valuable franchises."
-- John Ray, new CEO of FTX
This is a very important point: even alleged perpetrators such as Sam Bankman-Fried did not (and do not appear to have, though details are still emerging) pillage regulated exchanges in the FTX empire. Even with all the madness and alleged fraud going on at FTX, they did not (or could not) plunder US-regulated FTX subsidiaries. LedgerX. It is such a powerful symbol of why smart regulation is good for our industry - it protects investors, it has disclosure and transparency.
What now?
Before the FTX crash, my gut feeling was that the worst was over for cryptocurrency prices. Excessive leverage that centralised lenders could not sustain exploded in May and June.
There seems to be no way for other entities with similarly high leverage to avoid bankruptcy six months later. When the dust settles, we may well find that FTX/Alameda went bust months earlier than the public knew. If that's the case, everything after that is just a crime.
Sam Bankman-Fried admitted in an interview a few weeks ago that they went bankrupt in the Terra-LUNA crash in May.
"FTX's chaotic accounting + margin trading position built up over time after the LUNA crash, but I did not realize its full extent until a few weeks ago."
-- Vox's Kelsey Piper interview with Sam Bankman-Fried, November 16, 2022
Next week he will testify - under oath - before the US House of Representatives.
"In FTX's bankruptcy filing, they released a list of the top 50 creditors who are owed $3.1 billion. The filing also shows that FTX and Alameda Research lost $3.7 billion between 2019 and 2021. So even in a bull market, they're actually losing a lot of money. It's not clear exactly when the fraud and theft is, but it seems like it could be even earlier than people previously thought."
-- Joey Krug, Co-CIO, Pantera, December 9, 2022
If Sam Bankman-Fried knew he was bankrupt as early as May (as SBF implied in the Vox interview) and continued to advertise customer deposits, raise funds, and steal customer money...... And continues to appear on TV, podcast and lobby the U.S. Congress. It's unbelievable. It's unbelievable.
Kelsey: "So it makes no sense to say, 'Let's lend customer deposits,' except that the various financial instruments end up adding up and you don't even see them add up?"
SBF: Like, oh, FTX doesn't have a bank account, I guess people can wire money to Alameda's to make money on FTX. ... three years later... "Oh shit, it looks like people sent $8bn to Alameda and gosh, we basically forgot the corresponding stub account so it was never delivered to FTX."
-- Vox's Kelsey Piper interviews Sam Bankman-Fried (@vox) November 16, 2022
Jesse Powell said it best:
"I'm really trying to manage my anger. It's not about aiming high and being down. It's about recklessness, greed, self-interest, arrogance, antisocial behavior that leads one person to risk more than a decade of hard-won progress in this industry for personal gain."
-- Jesse Powell, co-founder, Kraken, November 10, 2022
Us: Encryption regulation VS Internet regulation
The state of crypto regulation is the opposite of the rest of the Internet.
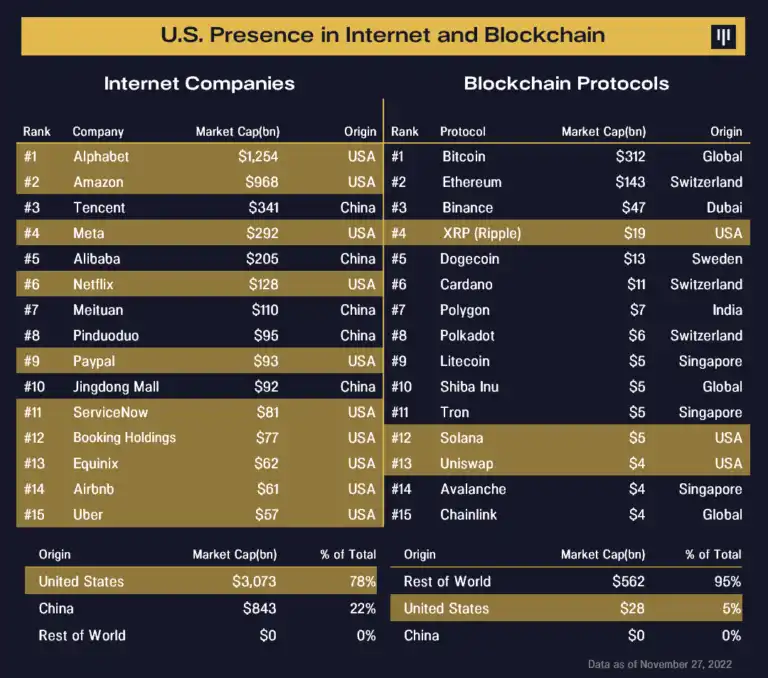
The U.S. government did build the Internet (ARPANET, which will celebrate TCP/IP's 50th anniversary next year). The government then gave early Internet companies numerous advantages. In particular, the United States offers them an unregulated safe haven and an 8.25 percent discount over brick-and-mortar competitors by exempting them from sales tax. As a result, all the biggest Internet companies in the world are in the United States.
So far, in the blockchain era, America's regulatory approach has backfired. It encourages 95% of blockchain entities to move offshore. Similarly, 95% of the crypto market capitalization is outside the US.
Regulatory Black Holes
Rostin Behnam, the chairman of the CFTC, pointed out something absolutely fascinating. Physical bitcoin exchanges have a regulatory black hole. This is a very odd question in the US regulatory system, where the CFTC has very clear jurisdiction over any derivatives or futures. If it finds a problem, it has the ability to take enforcement action in underlying physical commodity markets. But it does not have the ability to regulate the physical bitcoin market.
What about the Securities and Exchange Commission? Obviously, the "S" in the SEC is "securities," so it can only regulate what is a security. Although the SEC doesn't say what is or isn't a security, Bitcoin is widely believed not to be one. If it's not a security, it must be a commodity. So leaving this very strange black hole in crypto regulation without a congressionally mandated body overseeing physical bitcoin trading.
"We have handled over 60 encryption cases since 2014. However, since we have no direct oversight, we have to wait for individuals to come to us and say, 'Hey, you should check this issue we have identified' or 'I' have been scammed '. Every single case that we have dealt with is because we have received information that is not the traditional information that you would want or expect from a market regulator. Regulators monitor markets in real time and identify unusual transactions, whether they have registered entities, make sure they don't consolidate linked funds, they don't have conflicts of interest, they have books and records that you can check, they have financial resources, etc. All of these are core elements of the structure of financial markets."
-- Rostin Behnam, Chairman, CFTC, First DeCenter Summit, Princeton, November 30, 2022
"There is a growing demand for cryptocurrencies, but there is a major regulatory gap. I have been very vocal in warning that crypto markets are largely unregulated and we need comprehensive regulatory reform of crypto markets."
-- Rostin Behnam, Chairman, CFTC, First DeCenter Summit, Princeton, November 30, 2022
"The breakdown of all crypto entities is a real, tangible event, and voters, customers, investors and Americans are being hurt. We cannot stand idly by."
"Blockchain lending, trusteeship, markets, tax policy, etc. are core issues that the new Congress will have to address. It will be an uphill battle, but Congress will be determined to get something done."
I hope to use these events as a springboard for swift and comprehensive action. If we don't act quickly, I fear this could happen again. I will continue to advocate -- action must be taken in a timely manner because we cannot risk another entity going under again in the near future."
-- Rostin Behnam, Chairman, CFTC, First DeCenter Summit, Princeton, November 30, 2022
FTX, encryption winter will pass.
Pantera has invested in four similar "cryptocurrency winters." While the FTX crash is incredibly depressing, I'm sure......
"This too shall pass." -- Ancient Persian maxim
The failure of centralisation and weak regulation
This segment is written by Jesus Robles III, Content Assistant, and Chia Jeng Yang, Investment Assistant
At its peak, FTX was the second largest centralized cryptocurrency exchange by volume and was trusted by many. In the space of two weeks, the company went bankrupt, losing billions of dollars and causing a huge ripple effect that caused serious problems for many major cryptocurrency institutions, as well as a number of bankruptcies.
Naturally one asks, if you can't trust one of the biggest players in the exchange, one that has all the advantages of success and is trusted by a large swath of the industry, including institutional players, then who can we trust?
Since the early days of Bitcoin, the wisdom in the crypto industry has been "don't believe, verify."
While critics of our industry have railed against the failure of FTX, they have not said much about the overall promise of blockchain.
At this point, it's important to take a step back, put aside any emotional or knee-jerk reactions, and sobering assess the potential impact. A centralized financial institution that happened to trade in cryptocurrencies - and did not adhere to the same regulatory standards as non-crypto traditional financial institutions - mishandled the money so badly that it collapsed.
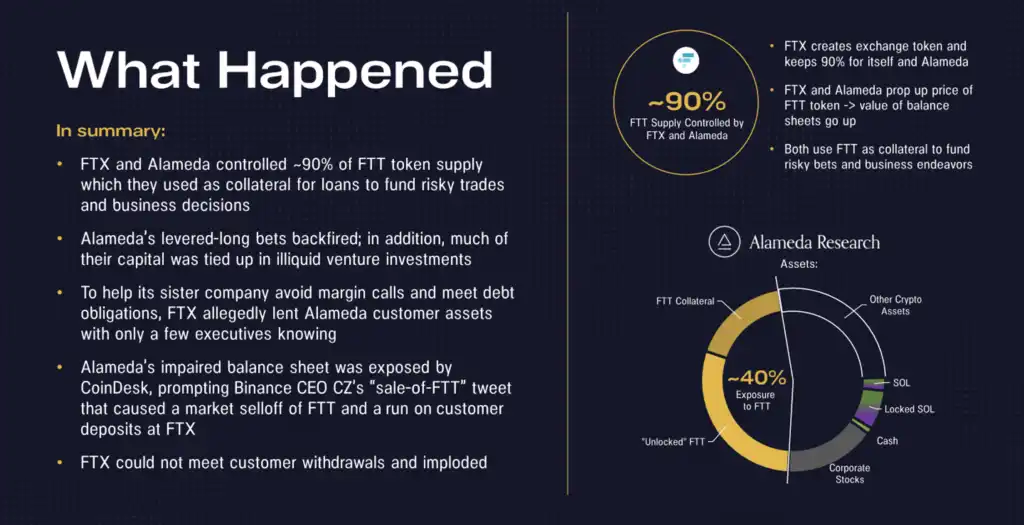
There is much speculation in the industry about the cause of the collapse. But, because of the nature of the cryptocurrencies held by exchanges or the technologies, protocols, and projects associated with those cryptocurrencies (excluding FTTS), the crash was anything but imagined.
This is in line with a handful of other crypto asset projects that have succumbed to mismanagement or willful centralization risks. We think it's pretty clear that the collapse of the exchange had nothing to do with blockchain.
"I have more than 40 years of restructuring experience. I have served as chief restructuring officer or CEO in some of the largest corporate failures in history. I have overseen situations involving criminal activity and allegations of malfeasance. I have overseen situations involving new financial structures (Enron and Residential Capital) and cross-border asset recovery and maximization (Nortel and Overseas Shipholding). Almost all of the situations I covered were characterized by some kind of deficiency in internal controls, compliance, human resources and system integrity."
"In my career, I have never seen a company [FTX] of this size control failure and such a complete lack of trustworthy financial information. From compromised system integrity and misguided foreign oversight, to the concentration of control in the hands of a very few inexperienced, unsophisticated and potentially compromised individuals, this situation is unprecedented."
-- John Ray, new CEO of FTX
The FTX collapsed because it was a bad organisation made up of malicious and unqualified actors - centralised risk.
We believe this is also partly due to regulators not having the proper authority or tools to guard the bottom line - mandated by Congress to take enforcement action only after harm has occurred, rather than having the ability to protect users and money up front.
Another major factor in the collapse of FTX was the regulatory uncertainty in the US that drove crypto agencies and users to leave the country. Like the "Wild West", it was very easy to start a company and operate -- a regulatory dilemma.
We think there are two ways to avoid this crisis:
1. Decentralization:If FTX is a decentralized exchange consisting of smart contract protocols, like DeFi, then the exchange's activities may already be fully transparent, auditable and verifiable. Moreover, user funds could have been kept in their own custody. Some DeFi protocols with these characteristics exclude many potential fraud, mismanagement of funds, withdrawal stops-that is, centralization risks. DeFi and blockchain are solutions to many of these classic centralised risks. Transparency, auditability, verifiability, and self-hosting are inherent features of some DeFi protocol architectures.
2. Regulation/Transparency:While we wait for DeFi to be widely adopted, a robust, comprehensive crypto regulatory framework will give us better guarantees of institutional integrity (for example, regulated traditional finance). A comprehensive regulatory framework would require transparency, auditing, reporting, periodic reviews, segregation of exchanges with potential conflicts of interest, etc., should be broad enough to protect all users, whether trading is offshore or not, and give regulators the appropriate authority and tools to spot any problems in advance.
We believe in transparent, audited, regulated exchanges -- like our portfolio companies Coinbase, Bitstamp, and Circle are great examples of institutional integrity. These centralized crypto finance companies have accepted and continue to support regulation, operate safely and successfully, and are embracing DeFi technology.
"Cryptocurrency regulation in the United States has been difficult to navigate, with regulators thus far failing to provide a viable framework for how cryptocurrency-related services can be provided in a secure and transparent manner. This means that a large number of cryptocurrencies based financial products, including lending, margin trading, and other instruments that are perfectly legal and regulated in traditional financial markets, are virtually illegal in the U.S. The U.S. is afraid of being sued. They don't want to break the rules, and now they don't know what the rules are."
"As a result, U.S. consumers and senior traders have been trading on high-risk overseas platforms outside the jurisdiction and protection of U.S. regulators. Today, more than 95 percent of cryptocurrency trading activity takes place on overseas exchanges."
"Part of the reason FTX was able to get big and strong was because it operated in the Bahamas, a small country with little capacity to regulate and monitor financial services operations. Did the regulator force FTX to act in the way it did in the past? No, but they did create a situation where FTX could take risks and have no impact."
-- Brian Armstrong, CEO, Coinbase, November 11, 2022
CeFi VS DeFi: FTX is a failure of centralization
This section by Jesus Robles, III, Content Assistant The distinction between "centralized" and "decentralized" entities, systems, companies, etc. in our industry is important.
Long story short: centralized organizations like traditional financial institutions and corporations face some obvious risks -- for example, management chooses to engage in fraud, mismanage user funds, and so on, leading to the demise of the company. Other members of the organization, users, etc., have no say in these bad decisions, but are still fully responsible for the consequences.
For decentralised systems, the "total failure of corporate control and total lack of trustworthy financial information" (the FTX case) is inherently more difficult to achieve because transparency and self-hosting are essential features in decentralised systems like DeFi, which are rigorously enforced by transparent and unbiased smart contracts and code.
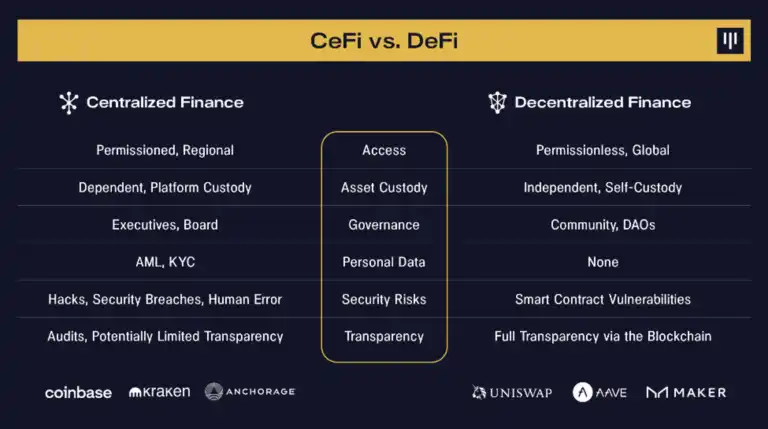
While its business involves decentralized projects, tokens, and more, FTX is fundamentally a centralized institution. Its demise is surely due to the risk that a small group of its decision-makers chose to centralise through fraud, mismanagement of funds and so on. For DeFi services, products and tools, or for DAOs (decentralized autonomous organizations), decisions need to be made democratically by all relevant actors and in full view of all participants. Most reasonable participants would not agree to fraudulent, mismanaged funds. Through democratisation and transparency, we believe DeFi will make it harder for things like FTX to happen.
A centralized entity or system is opaque -- there is no way to peer into its inner workings and assess any potential problems from the outside. Recently released documents from FTX's bankruptcy proceedings show that the company's problems had been worsening in the months leading up to its bankruptcy. This crisis could have been detected early and avoided if the company had been transparent and fully audited. This transparency is often native to DeFi services, products and tools, which makes it difficult to let things fester for as long as they did in FTX's case.
In the case of fintech, a centralized entity or system typically holds assets for users. While this does have some benefits, these assets also suffer if the entity or system fails. Indeed, this is the case with FTX. Hundreds of thousands, if not millions, of users have lost billions of dollars in crypto assets and will be "lucky" to recover a few cents once the bankruptcy process is complete. The Mt. Gox bankruptcy proceedings, for example, remain unresolved after a nine-year span. But with decentralized financial services, products, and tools, users have custody of their assets under a specific protocol or system architecture, so even if the project fails, they can still withdraw money from the service, product, or tool and avoid losing money.
Centralization failure led to the collapse of centralized FTX. Blockchain -- and how it is decentralized -- is the solution, not the problem.
DeFi 是卓越的 : 代码即法律
This section by Jesus Robles, III, Content Assistant
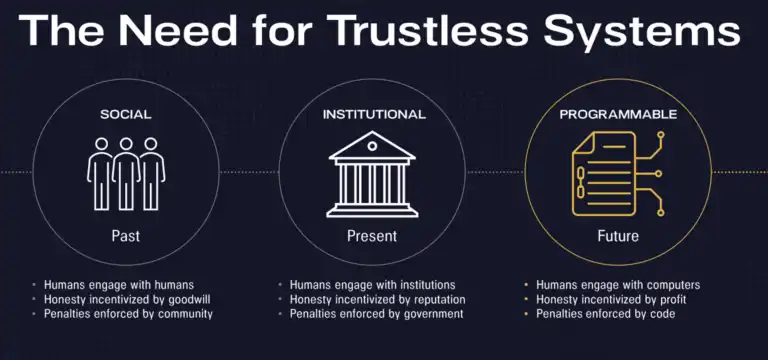
Unlike opaque, centralised finance, DeFi is rock-solid, rooted in immutable code, and fully transparent. In some cases, DeFi removes human subjectivity entirely, such as financing decisions. With DeFi, participants can transact openly and transparently on the blockchain - rather than backroom transactions through opaque, artificial (i.e., fallible) financial actors with possible conflicts of interest. So DeFi is a vision that we should strive to achieve instead of sticking to inefficient centralized financial systems.
DeFi has never "committed a crime". Rules are encoded into smart contracts. Users do not have to trust counterparties or the platform to conduct financial transactions. DeFi's code is just doing what both sides agree on.
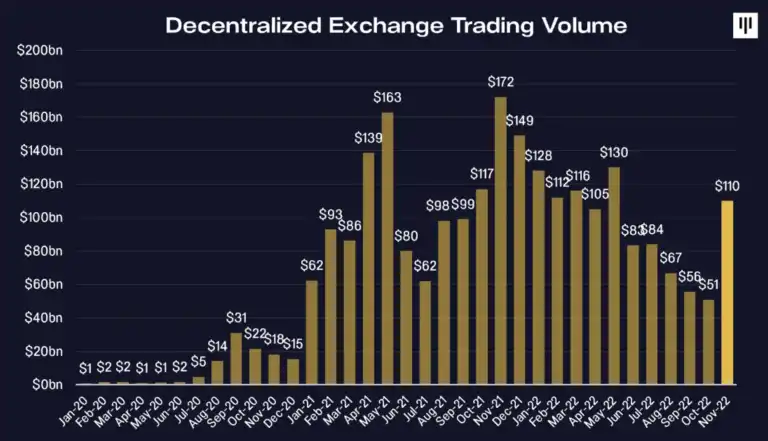
FTX 崩盘后,去中心化交易所 (DEX) 的交易量在 11 月飙升。
The best proof that DeFi is superior to centralized finance is head-on competition.
"" Furthermore, while crypto skeptics were greatly energized by news of the FTX crash, we would point out that all recent crashes in the crypto ecosystem have come from centralized players, not from decentralized protocols." "
-- Steven Alexopoulos, JP Morgan Cryptocurrency Analyst, November 10, 2022
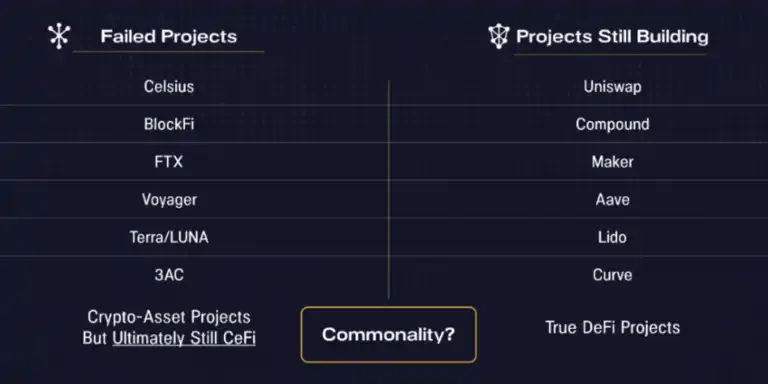
Defunct centralised financial firms such as Celsius and BlockFi did business with counterparties and then invested those funds in DeFi agreements. What happened next was far-reaching: these centralized financial firms were forced by smart contracts to repay the DeFi agreement.
Celsius was forced to prioritize repayment of its $400 million loan on Maker, Aave and Compound to prevent liquidation of its collateral. It has no ability to "reorganize"/renege on smart contracts. In DeFi, "a deal is a deal" - you can't back out. All centralised financial firms are forced by smart contracts to repay DeFi agreements. On the other hand, centralised financial firms such as FTX can lie and deceive their own customers. Unfortunately, their customers are unlikely to get their money back.
With DeFi, the result is different. Customers can monitor the protocols on the blockchain and determine that the code will execute their transactions.
FTX failed in part because Alameda allegedly had preferential accounts. Moreover, Alameda was allowed to trade without automatic clearing when it was over-leveraged. However, there is no backdoor or preference in DeFi, these are not allowed in DeFi. In DeFi, the same rules apply to everyone, and the agreement cannot deviate from them structurally.
We believe DeFi is the future of finance, and while it also has some unique early problems, it is certainly the solution to the risks and limitations of centralised finance, such as lack of transparency, backdoor trading risks, insolvency, mismanagement of funds, fraud, etc. This is part of the reason why we have invested in some DeFi agreements.
We believe the crypto industry will continue to drive the DeFi protocol forward.
Structurally safer finance: Regulated exchanges
This section is written by Jesus Robles, III, Content Assistant, and Chia Jeng Yang, Investment Assistant
While DeFi is at odds with CeFi in some ways, the coexistence of the two fintecs will become the norm, rather than DeFi "completely replacing" CeFi.
That said, CeFi can and must be improved as it relates to cryptocurrencies and needs better regulation. Regulated entities are generally safer, and we believe regulation creates financial institutions that are structurally safer and have better net assets, and they should be embraced.
Regulated CeFi exchanges can and do well. There's something to be said for well-regulated, fully transparent, rigorously run, centralized cryptocurrency exchanges -- like Pantera-backed Coinbase, Bitstamp, and Circle.
1. Coinbase
Coinbase, a publicly traded company, is heavily regulated and in 2017 was one of the first entities to receive a BitLicense from the New York Department of Financial Services. Coinbase also holds licenses in nearly every U.S. state and continues to seek and obtain international regulatory approvals to support the growth and expansion of the platform.
In June 2021, BaFin granted Coinbase Germany GmbH custody and trading licenses for cryptocurrencies under a new licensing system introduced in January 2020. The BaFin licensing framework is the first of its kind in the EU, and Coinbase Germany is the first company to receive such a license.
Thanks to its regulation, Coinbase is now the second largest cryptocurrency exchange by trading volume, and one of the most successful and prominent companies in the crypto industry. Regulated CefIs work well!
2. Bitstamp
We believe Bitstamp, the longest-established cryptocurrency exchange, is one of the industry leaders in compliance and regulation.
Reasons:
Hold assets 1:1 with BitGo, a licensed trust, and other regulated banking institutions.
There is criminal insurance. Currently working with BitGo and Ernst & Young to publish a proof-of-reserves transparency report as of FTX events.
Was the first cryptocurrency exchange to be licensed in Europe: it was granted an EBA payment agency license in Luxembourg in 2016.
Is one of the few companies with NYDFS BitLicense operating in New York State.
Each of the past four years has been audited by Ernst & Young.
Hold capital provident funds as required by NYDFS.
Bitstamp is now the fifth-largest cryptocurrency exchange by volume, and has seen its market share surge as users flee dangerous overseas exchanges for safer, regulated ones.
Regulated CefIs work well!
3. Circle
Circle has launched USDC, a stablecoin that serves as an exchange rather than a gateway to the crypto world. Every USDC on the Internet is 100% backed by cash and short-term Treasury bills, so it is always 1:1 for dollars. (Stablecoin is a reserve-backed cryptocurrency designed to take advantage of blockchain's decentralization while mitigating the risk of price volatility typical of crypto markets.)
Circle USDC reserves are held and managed by leading financial institutions in the United States, including BlackRock and Bank of New York Mellon. Each month, Grant Thornton LLP, one of the largest audit, tax, and consulting firms in the United States, provides a report on the size of the USDC reserves.
Circle, like PayPal, Stripe and Apple Pay, has received money transfer licenses under U.S. state laws. Circle's financial statements are audited annually and subject to SEC review.
In the US, Circle is also regulated as a money service by the Financial Crimes Enforcement Network (FinCEN), an arm of the US Treasury Department.
Outside the US, Circle is regulated as an electronic money institution (EMI) by the Financial Conduct Authority, under the responsibility of the Treasury and Parliament.
Recently, Circle also received approval-in-principle from the Monetary Authority of Singapore (MAS) to become a master payment institution licence holder. This allows Circle to offer digital payment products, cross-border and domestic money transfer services in Singapore, thus becoming a new generation of financial services and business applications.
Circle closely watches the actions of the above governments to ensure that it meets any future obligations.
With a cautious approach to regulation, Circle became one of the longest-running and most trusted entrances to the crypto world, leading the adoption of stablecoins and often advocating for more appropriate industry regulation.
Supervision and DeFi
This section is written by Jesus Robles, III, Content Assistant, and Chia Jeng Yang, Investment Assistant
Regulated entities are generally safer, and we believe regulation creates financial institutions that are structurally safer and have better net assets, and they should be embraced. Policing is one of many tools to strengthen security structures and help catch malicious actors - but there are limits. Legal structures and regulation should be seen as good but incomplete means of security, merely a means to an end of "structurally safer finance".

In the more open global environment created by cryptocurrencies, DeFi must protect its users through code, and for trust-free purposes, nothing is more mechanical, structured, or reliable than code.
While the FTX debacle is still ongoing, many DeFi agreements function as before, and many of them have been hardened by the many bankruptcies that have occurred this year.
"We should talk about the decentralised nature of DeFi because it raises a whole different set of issues, especially for regulators. We are used to being hands-on. For example, bank examiners are embedded in banks and their office is the bank they regulate. DeFi and DAO raise a lot of very difficult questions about the role of regulators."
-- Rostin Behnam, Chairman, CFTC, First DeCenter Summit, Princeton, November 30, 2022
Regulatory Outlook: Legalization of industries and technologies in the future
"" While certainly a significant short-term setback, we think the well-publicized FTX debacle could significantly accelerate the timeline for introducing cryptocurrency-related regulations (similar to the new banking regulations that followed the global Financial Crisis (GFC))." "
"" As such, we view the FTX debacle as a step backward for the industry, but this could prove to be the catalyst to take the crypto industry two steps forward (further unlocking the practical value of blockchain). In fact, we view the establishment of a regulatory framework as the necessary catalyst to drive cryptocurrency adoption by institutions at scale." "
-- Steven Alexopoulos, JP Morgan Cryptocurrency Analyst, November 10, 2022
See you in 2022. All the best in 2023!
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles