Ethereum Q2 Resets: DeFi resilience remains, NFT is still hot, L2 Token season opens
原文标题:《 以太坊状态:复盘以太坊 2022 Q2 》
Ben Giove, analyst at Bankless
The Way of DeFi
Following the previous Ethereum 2022 Q1 report, this report will examine key metrics for Ethereum protocols and ecosystem for q2 2022 -- ending June 30 -- in four categories: Protocols, DeFi, NFT & NBSP; And L2. We then discuss the highlights of the ecosystem and look into the future.
01. Agreement
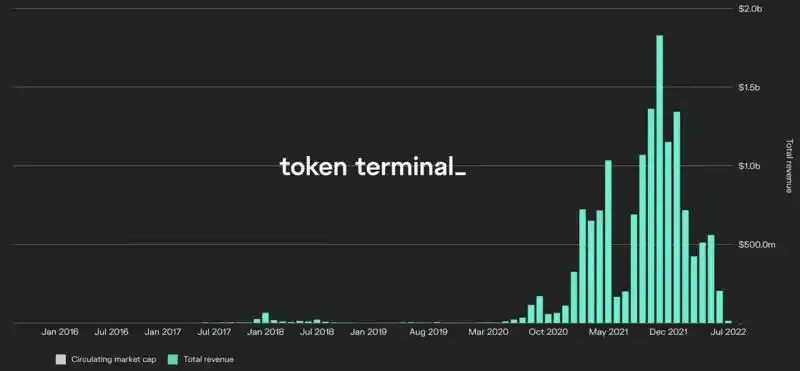
Ethereum network revenue; Source: Token Terminal
Online revenue fell 33.4 per cent -- to $1.28bn from $1.91bn
It measures the value of transaction fees paid to use the network. Of this amount, $1.09 billion (85.4%) of ETH was burned and removed from circulation supply.
The reduced demand for block space is likely due to market weakness during the quarter, which dampened speculative activity.
ETH inflation fell 37 per cent -- from 1.12 per cent to 0.71 per cent
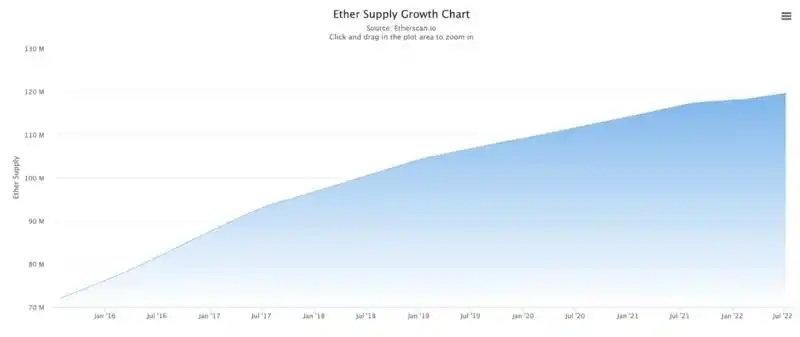
ETH supply growth; Source: Etherscan
The figure measures ETH supply growth during the quarter.
The decline is likely due to the expense burning mechanism implemented through IP-1559 in q3 2021.
Daily active addresses fell 20.6 percent -- from 593,404 to 471,447
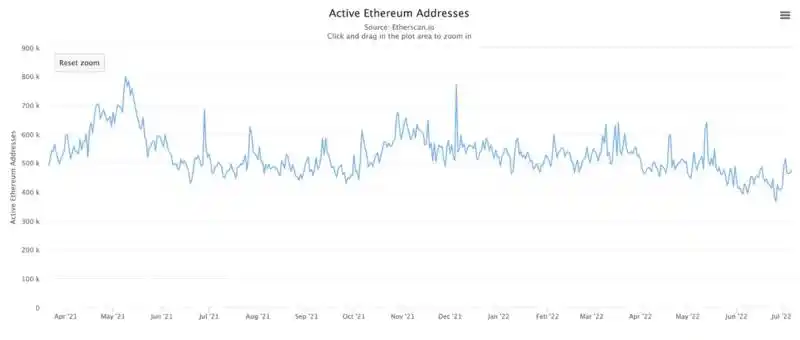
Ethereum daily active address; Source: Etherscan
The data tracks the average number of wallet addresses traded on Ethereum each day during the quarter.
As with online revenue, the decline is likely due to less speculative appetite among users as a result of the bearish backdrop during the quarter.
Pledges of ETH increased by 116 per cent -- from 6.01 million to 12.98 million
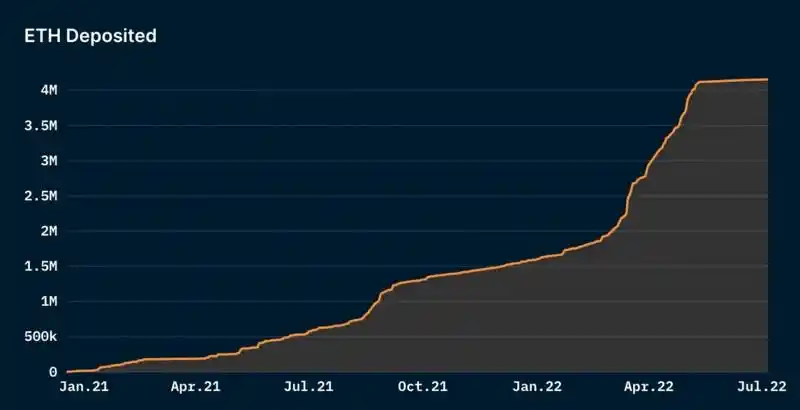
ETH pledged on beacon chain; Source: Nansen
This measure is the number of ETH's on the beacon chain before the network is about to transition from proof-of-work (PoW) to proof-of-stake (PoS).
By the end of the second quarter, about 10.86 percent of the total ETH supply had been pledged.
02. DeFi Ecosystem
DeFi TVL fell 42.4 per cent -- to $34.21 billion from $59.42 billion
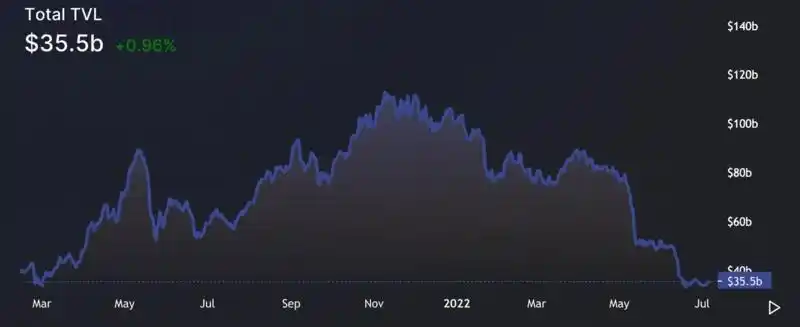
Ethereum DeFi TVL; Source: DeFi Llama
This data tracks the value of assets deposited into the DeFi protocol deployed on Ethereum.
This decline is likely due to the decline in crypto asset prices during the quarter, as well as liquidity outflows due to compressed yields and reduced risk appetite among DeFi users.
The amount of Stablecoin in circulation increased by 43.0%-- from $76.58 billion to $109.05 billion
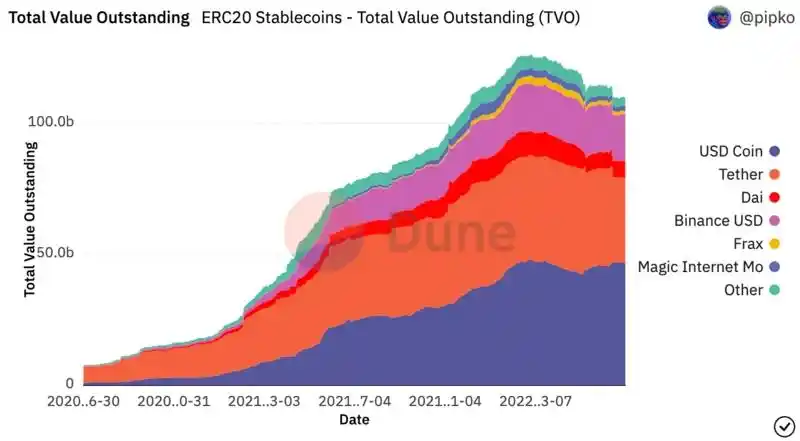
Stablecoin supplies; Source: Dune Analytics
This measures the number of DOLLAR-pegged stablecoins issued and circulating on Ethereum.
The increase can be attributed to increased demand for stable asset trading or leverage, as well as the growth of newly issued stablecoins such as FRAX.
The spot & have spent DEX Transaction volume fell 9.0%-- to $319.13 billion from $35.54 billion
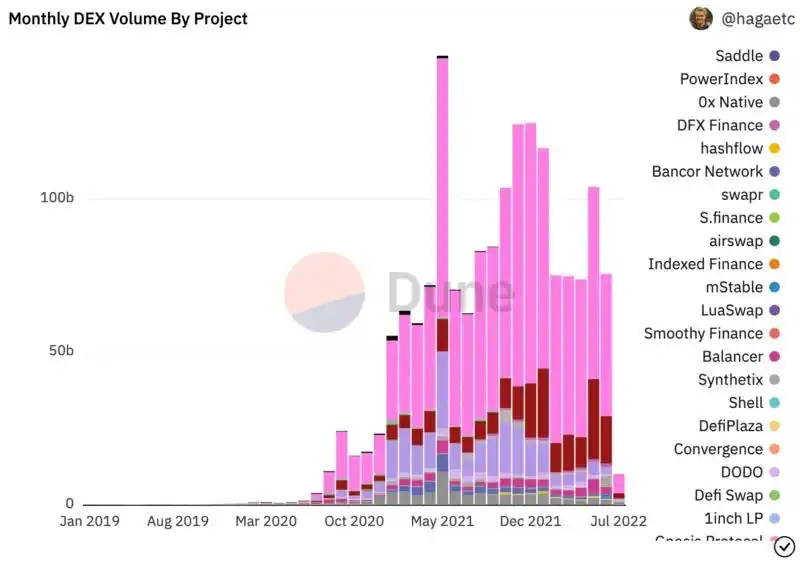
DEX monthly trading volume; Source: Dune Analytics
The figure measures total trading volume on the decentralized spot trading platform on Ethereum during the quarter.
The drop in spot trading volume could be due to market conditions as volume is highly correlated with bullish price action.
Perpetual DEX increased trading volume by 598.5 percent -- to $135.48 billion from $19.39 billion
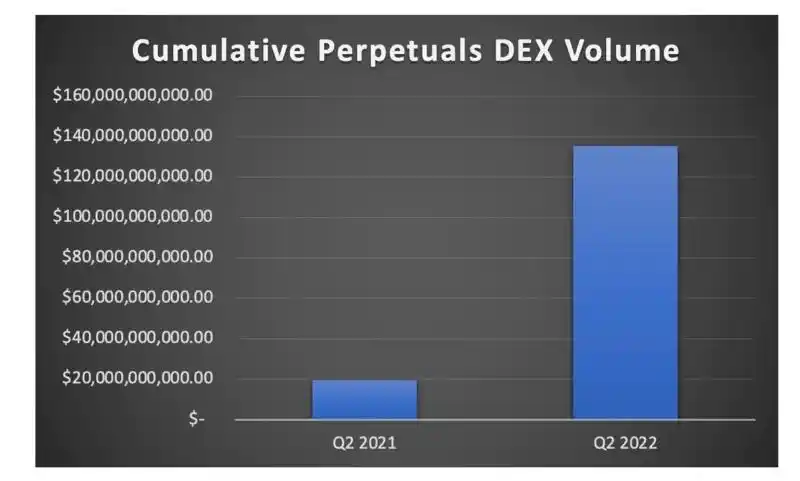
Quarterly sustainable DEX trading volume; Source: Token Terminal and GMX Analytics
The rise in perpetuity trading can be attributed to. -- its transactions were up 598.4% year on year.
Note: Perpetual DEX volume tracks volume from dYdX, Perpetual Protocol and GMX.
The share of liquidity pledges in beacon Chain deposits increased 177.5 per cent -- from 12.0 per cent to 33.3 per cent
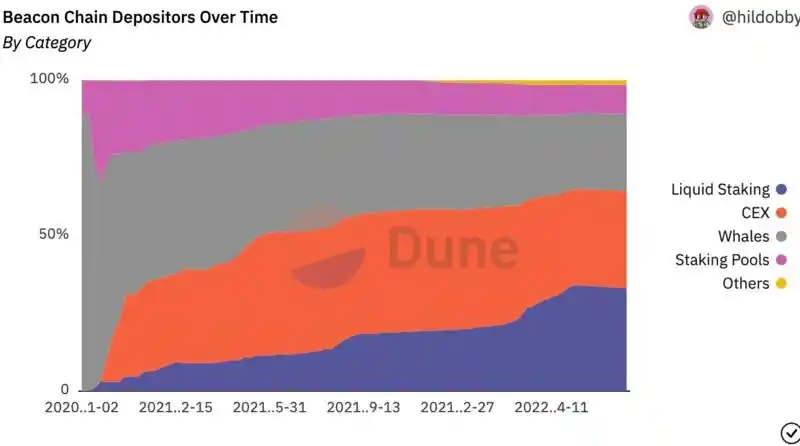
Types of beacon chain deposits by market share -- Source: Dune Analytics
This measure is the share of ETH pledged by unmanaged agreements that issue liquid pledged derivatives (LSD).
The increase is likely due to the long-term increase in ETH pledged on the beacon chain in the first quarter and due to the increase in LSD, such as Lido & NBSP; StETH, integrated into different DeFI protocols.
03. NFT ecosystem
NFT market volume increased 2,439.2% -- from $509 million to $12.93 billion
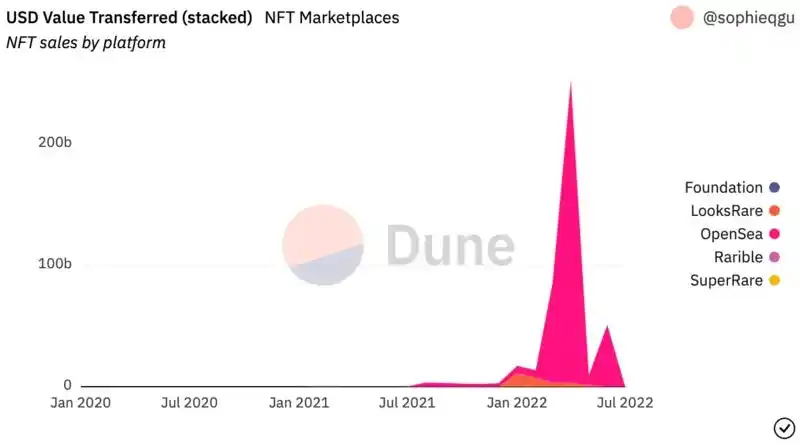
NFT market sales volume; Source: Dune Analytics
This data tracks transaction activity in the OpenSea, Foundation, LooksRare, Rarible and Superrare markets.
The reason for the increase is likely the long-term growth of the NFT ecosystem between Q2 2021 and Q2 2022 -- specifically the rise of PFP collectibles.
The average number of daily NFT traders rose 1,1114.5 per cent -- from 2,412 to 29,289
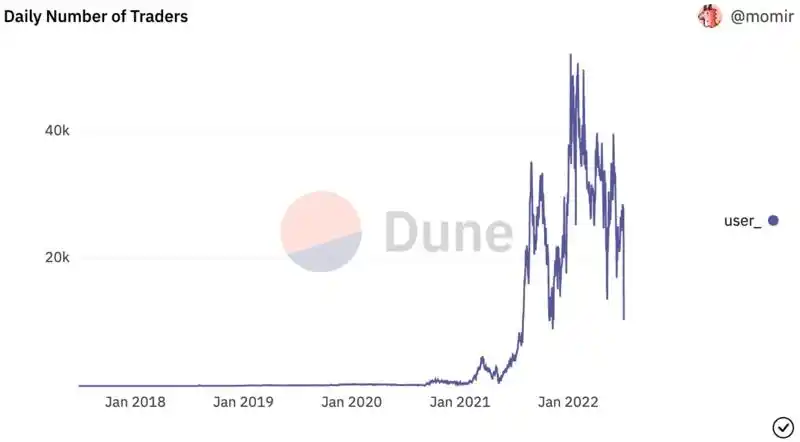
Number of NFT traders per day; Source: Dune Analytics
The figure measures the average number of users trading NFT per day during the quarter.
As with market volume, the growth in this metric is likely the result of long-term growth in the NFT ecosystem.
BAYC floor prices soared 3844%-- from 2.50 ETH to 98.60 ETH
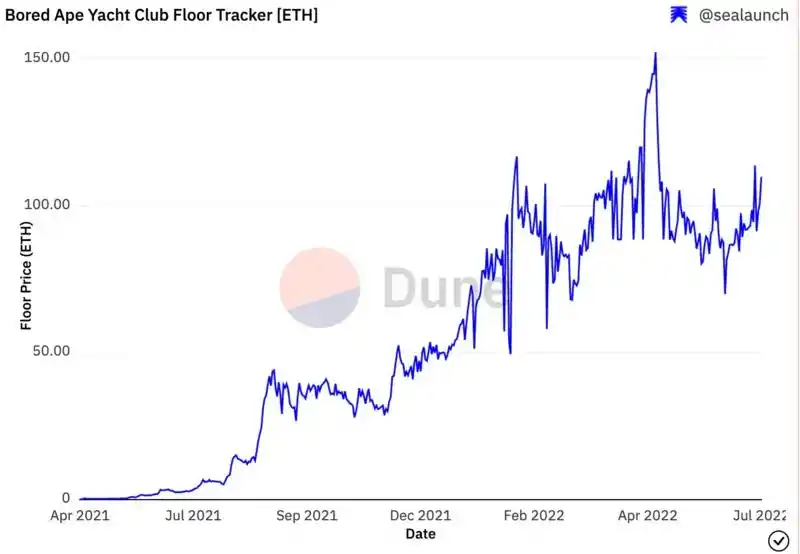
BAYC floor price (ETH); Source: Dune Analytics
The increase is likely due to the wider popularity of PFP NFTs and the increased adoption of BAYC by various celebrities and high profile public figures.
4. L2 Ecosystem
L2's TVL grew 896 percent -- from $374.17 million to $3.72 billion
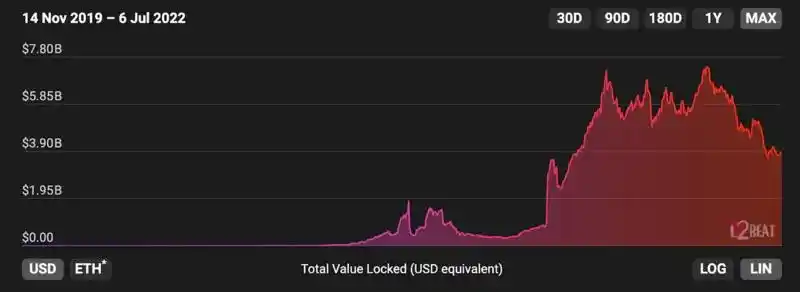
Ethereum L2 TVL; Source: L2Beat
This measure is the value of the ethereum L2 ecosystem that has been bridged, with growth likely to be driven by usage, mobility and deployment to Arbitrrum and Optimism. Such as the increase of network applications driven by.
Arbitrum Network revenue reached $8.2 million; Optimism had revenue of $5.58 million
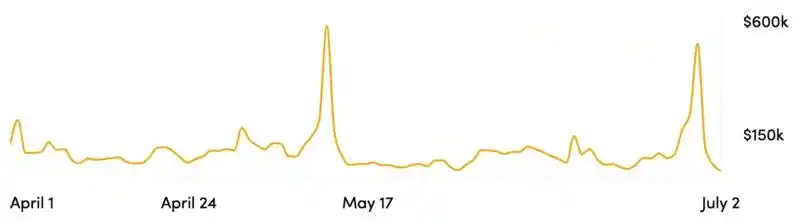
Arbitrum network revenue; Source: Cryptofees. Info
This data tracks the value of fees paid by users to transact on each L2.
Optimism had an average of 175,700 monthly active users; The accumulative number of addresses on Arbitrum reaches 1,031,688
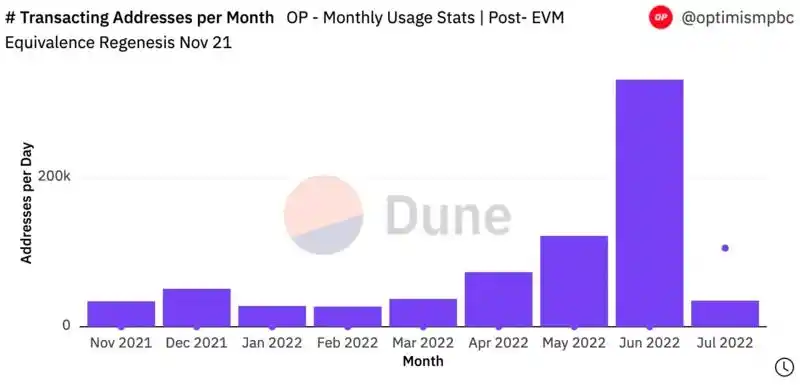
Source: Dune Analytics and Arbiscan
This data measures the average number of monthly users interacting with Optimism and the total number of independent addresses of Arbitrum in the quarter.
Note: Given that Aribtrum and Optimism were both launched in the third quarter of 2021, and due to limited public data available from both networks, year-to-year comparisons were not possible.
05. Ecological highlights
1) DeFi proves its resilience
Despite the TVL drop and slowing spot trading volumes, the Ethereum DeFi ecosystem proved its resilience by withstanding considerable stress testing throughout the second quarter.
The major turbulence began with the implosion of UST in May 2022, which at its peak was the third largest Stablecoin with a market cap of approximately & NBSP; $18.78 billion. Although on-chain damage is mainly limited to Terra & NBSP; Blockchain itself, but the decline of UST spread to the broader crypto industry, with the market down 45%.
This led to the collapse of many CeFi entities. Three Arrows Capital, an overleveraged hedge fund, and Voyager, a lending platform, are both in bankruptcy. The domino effect is also felt by other lenders such as Celsius and BlockFi. Has caused considerable pressure, the latter has been taken over. Acquisition.
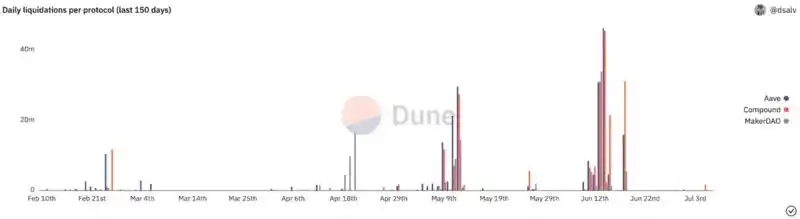
Compound, Aave & have spent And Maker's Daily reckoning -- Source: Dune Analytics
Despite the CeFi massacre, DeFi on Ethereum managed to weather the storm without any problems.
The three largest lending agreements, Compound, Aave and Maker, successfully processed $462 million in liquidations and continue to operate at 100 percent uptime, with current bad debts being negligible.
Interestingly, the transparency of the DeFi protocol allows market participants to monitor physical positions like Celsius, and analysts on Twitter can provide advance warning of the precarious state of a lender's finances.
While liquidity may have dried up and activity slowed in this bear market, the value proposition for on-chain financial systems has never been as clear as it was in the second quarter.
2) NFT is still hot
Ethereum's NFT ecosystem remains hot throughout 2022.
NFT prices peaked in the second quarter, and Nansen's Blue-chip 10 index, a capture-weighted index that tracks the ten largest NFTS by market capitalization, hit an all-time high on May 2.
This coincides with the $317 million land sale of Otherside, the upcoming metasverse project from Yuga Labs, the company behind Bored Ape Yacht Club (BAYC) and the largest component of NFT-10.
This sale caused a massive congestion of Ethereum, leading to record high Gas bills (and ETH burning).
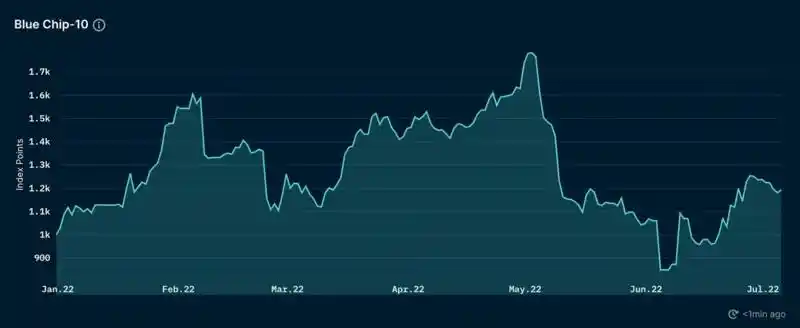
Nansen Blue-chip 10; Source: Nansen
Another standout collection that made a name for itself in q2 is Goblintown. Modeled after the bear market's "goblin-town" Meme, the free Mint's NFT collection gained momentum after it went viral on Twitter. PFP holders have been campaigning for the floor to reach 7.1 ETH in a matter of weeks.
The NFT sector also saw several high-profile acquisitions and agreement launches in the second quarter. This includes Uniswap & NBSP; Labs and OpenSea have acquired NFT aggregators Genie and Gem, respectively. In addition, OpenSea announced the launch of its decentralized marketing protocol, Seaport.
3) L2 Token 季开启
With the launch of Optimism's Governance Token OP, the Ethereum L2 ecosystem passed one of its most important milestones.
作为「四巨头」 中第一个推出 Token 的公司,OP 将被用来管理「Token 屋」,作为 Optimism 的两院治理系统的一部分。该模式允许持有人对网络升级和生态系统奖励的分配进行投票。在未来,这种 Token 很可能也会被用来去中心化,并从定序器中累积收入。定序器是负责将交易分批送到 L1 的实体,目前只由 Optimism PBC 运营。
虽然空投后的申领过程存在问题,但 OP 已经证明了 L2 Token 所拥有的潜力,以推动网络的兴趣、使用和活动的增加。
Since launching, Optimism has seen its share of Rollup DeFi TVL grow from 17.26 percent to 30.42 percent.
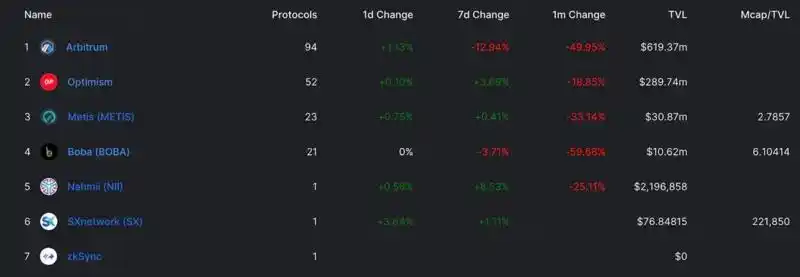
DeFi TVL on L2; Source: DeFi Llama
另一个值得注意的 Token 公告是 Immutable-X,一个使用 StarkEx 构建的专注于游戏的 L2,宣布它计划开始将 "协议费" 的一部分导向其 IMX Token 。一旦协议费被激活,持有人将能够获得网络上所有一级和二级 NFT 销售的 0.8%。
In addition, Arbitrum recently started its Arbitrum Odyssey campaign, which aims to guide the use of popular applications on the network, while rewarding participants with NFT. The event was postponed until the completion of the Arbitrum Nitro upgrade due to a record high transaction volume resulting in a spike in Gas fees.
尽管有这个小插曲,但 Arbitrum Token 的必然推出 -- 加上 Optimism 即将推出的激励计划 -- 应该有助于增加 L2 的使用,并加速用户从以太坊的迁移。
As far as the current situation is concerned, only 0.40% and 0.22% L1 addresses have used Arbitrum and Optimism respectively. A lot has happened in L2, and there is still a lot of room for growth.
06. Future outlook
1) A merger is coming
Ethereum's long-awaited transition from PoW to PoS finally appears to be nearing completion. The merger has been successfully completed on Ropsten and Sepolia test networks, leaving only Goerli as the last test network before the main network is rolled out.
The numerous reasons why the merger represents the most important event in Ethereum's history have been stated countless times, but still bear repeating.
As we know, ethereum for PoS will enable scalability upgrades such as the implementation of EIP-4488 and EIP-4844, which will reduce the cost of L2 calling data stores and implement Danksharding, respectively. In addition, it will enable the implementation of PBS, which aims to separate block building from block validation to mitigate the negative externalities of MEV.
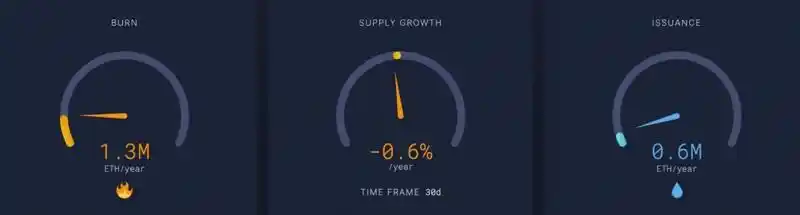
Release of merged ETH; Source: Ultrasound. Money
Of course, a merger would be a huge bullish catalyst for ETH assets. Based on the current AMOUNT of ETH pledged, the issuance required to secure the network after the merger is expected to decrease from 5.5 million ETH to 600,000 ETH.
Based on network revenues over the past 30 days -- which are at their lowest level since the summer of 2021 due to corrections and fee burnings --ETH is projected to experience net deflation, with its supply projected to decline by 0.6%.
Combined with the removal of structural selling pressure from the upgrade from miner to verifier, this represents a significant improvement in ETH's long-term value proposition.
2) Competition heats up
While many competitors lost momentum in the bear market, Ethereum and ITS L2 still face significant competition from other ecosystems.
DYdX recently announced plans to migrate from StarkEx and put its V4 protocol through its own Cosmos & NBSP; Chain launch, emphasized this kind of competitive force. As an early adopter of the new technology, DEX's migration is a validation of the chain of applications theory and a leading indicator that teams and protocols may follow in its footsteps in pursuit of more sovereignty.
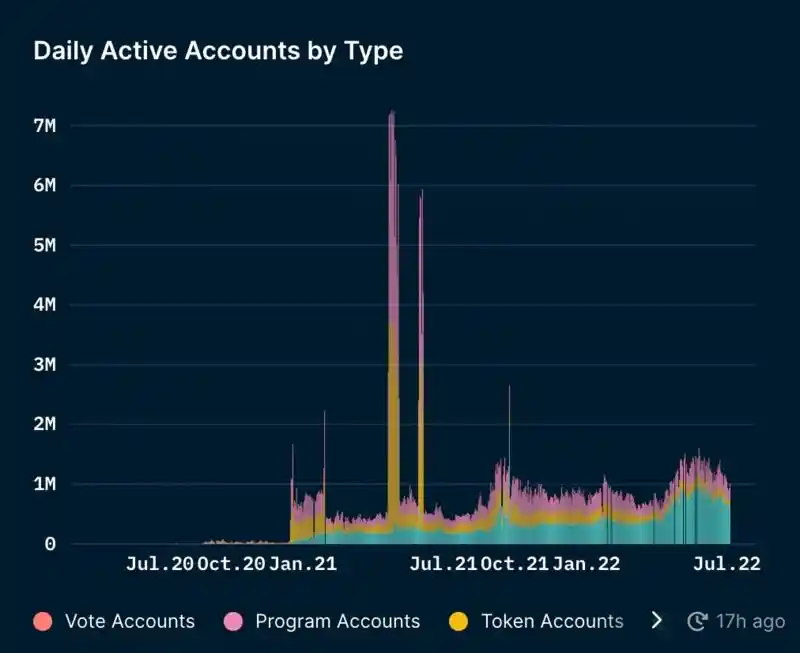
Solana Daily active account; Source: Nansen
Another network putting increasing pressure on Ethereum is Solana. With its rapidly growing NFT ecosystem, the network had the most users of any blockchain in the last 30 days, at 20.3 million. Solana continues to grow its user base and maintain developer mindshare despite the bearish winds.
With usage increasing, L2 players like Optimism and Arbitrum experiencing difficulties, and both experiencing the growing pains of implementing new cutting-edge technologies, the door seems wide open for other ecosystems to continue to exert competitive pressure on Ethereum and its scale-up solution network.
Note: This report is not related to Ethereum or the Ethereum Foundation.
** This article represents the views of the original author only and does not constitute any investment opinion or recommendation.
The original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
 Related Articles