The highlight of 2022? Annual rematch of mainstream L1 and L2
Original title: "A Detailed explanation of the Progress and Competitive Landscape of 10 Major Layer1 and 4 Major Layer2"
The Block
Translation of the original text : Gu Yu, chain catcher
The explosive growth of Layer1 is one of the most important developments in the crypto industry in 2021, with multiple emerging Layer2 networks challenging Ethereum and multiple Layer2 projects coming online to join the competition.
In The recent annual report released by The Block, The competitive landscape of Layer1 and Layer2 is analyzed in detail, and The technological and ecological progress of The 10 mainstream Layer1 platforms is described in detail.
I. Overview of competition in 2021
One of the major trends for 2021 is the growth of Layer 1 (L1) blockchains and their ecosystems, specifically related to the growth of ethereum, the current leading smart contract platform. As described in our State of the Market section, The Tier 1 protocol is one of the breakout winners in the cryptocurrency market in 2021.
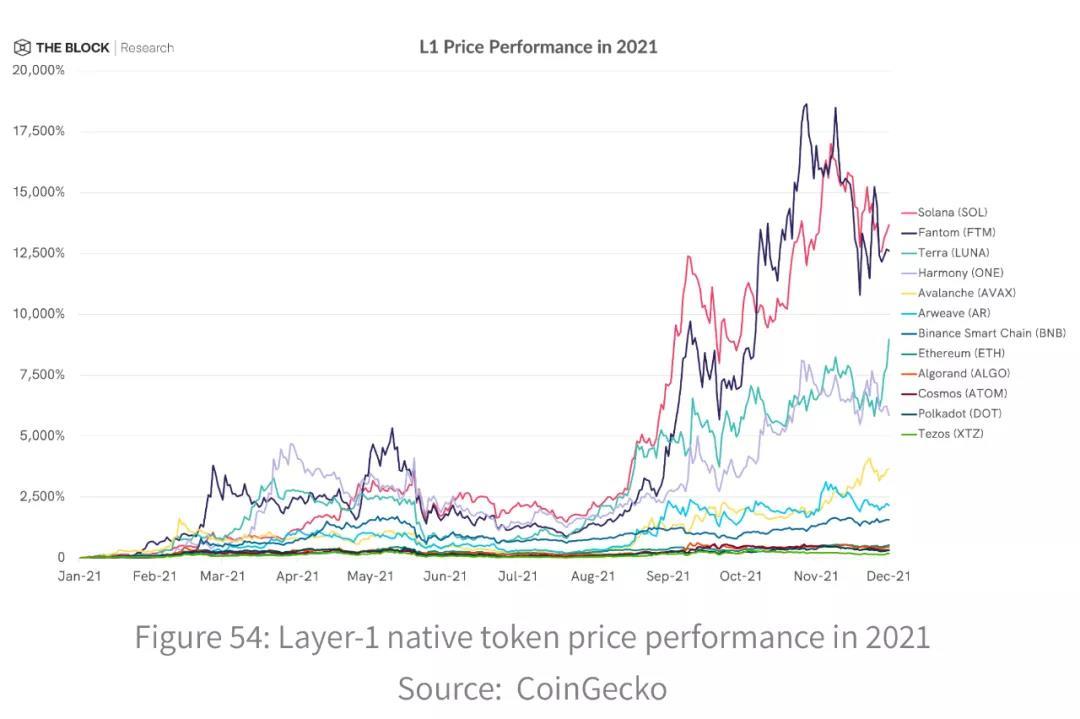
Zoom in on the price returns of tier 1 platform cryptocurrencies relative to ETH, and they significantly outperform ETH price returns, such as Fantom (FTM), Solana (SOL), and Terra (LUNA).
Price, performance aside, quantifiable user activity increased significantly in L1s 2021, driven by the emergence of DeFi ecosystems on various L1 platforms. With the growing number of DeFi protocols available, users are depositing record amounts of money into decentralized applications such as Decentralized exchanges (DEXs), lending agreements, income aggregators, and derivatives exchanges.
On Ethereum alone, the total lock-up value (TVL) of DeFi protocols rose from about $16.1 billion at the beginning of 2021 to $101.4 billion on November 30, up about 530% over the course of the year. L1 Ecosystem's DeFi program, TVL, has grown even faster overall, adding over $166 billion since the start of the year, an increase of about 974%.
While Ethereum still had almost all of the capital locked up in DeFi at the start of 2021, its share in DeFi TVL had fallen to 63% as of November 30.
The emergence of L1 alternative ecosystems comes at a time when crypto markets continue to grow, including Ethereum. Users of ethereum, the largest smart contract platform, began to experience major network scalability issues in early 2021 as transaction volumes continued to hit record highs between January and May, against the backdrop of a surge in the broader crypto market.
Average transaction fees for Ethereum rose to an all-time high in the first half of 2021, with high gas fees and long confirmation times sometimes paralyzing users during periods of extreme network demand. Priority GAS Auction (PGA) robots and increased MEV activity since January also contributed to the long period of high gas prices at the start of the year.
In this environment of huge network demand and rapidly rising costs, the relatively low-cost non-Ethereum L1 is starting to take center stage as users look for alternatives to the activities they typically perform on Ethereum. EVM compatible chains like Binance Smart Chain (BSC) are particularly suited to absorbing large numbers of old and new users, offering the opportunity to experiment in a new but familiar ecosystem without the barriers to entry of high capital costs.
From February, the BSC ecosystem grew dramatically, peaking at $34.8 billion TVL on May 9 and then representing about 26% of DeFi TVL. In addition to TVL, BSC also saw a significant increase in the number of daily users, hitting a new high of 8 million daily transactions in May.
As the crypto market generally declined from mid-May, the adoption and use of these metrics by BSC declined sharply until TVL regained its previous all-time high on November 14. Notably, the ecosystem also experienced a series of prolonged attacks throughout q2, highlighting the vulnerability and risks of a large number of protocols on the network that originated from an unaudited fork of the Ethereum DeFi protocol.
Still, BSC's explosive growth in 2021 provides a blueprint for other emerging L1s to build original DeFi protocols like DEXs and lending platforms into the new L1 ecosystem, which could be key to attracting active users and developers.
Having said that, one of the biggest challenges the agreement continues to face is the issue of liquidity fragmentation. Even with EVM compatibility, the new L1 ecosystem faces an uphill battle to attract liquidity, as users often need to have a compelling reason to move assets that may already be earning revenue on another platform. It turns out that one of the best ways to attract liquidity providers is simply to incentivize them.
Ii. Incentives and Funds
In the second half of 2021, the EVM compatible chain saw a dramatic increase in users and activity, due in part to a significant increase in the rewards offered by the L1 team and their funding.
Perhaps the most notable of these projects is the Avalanche Foundation's Avalanche Rush, which launched on August 18, Expanded its DeFi ecosystem by distributing 10 million AVAX tokens (worth about $180 million at the time) to the Avalanche protocol's liquidity providers.
Since then, at least eight other L1 funds have announced incentives of $100 million or more, including the Fantom Foundation, Terraform Labs and Algorand Foundation. Most projects focus on promoting DeFi in their respective ecosystems, although the exact goals and scope and token distribution methods vary from project to project.
Avalanche Rush is primarily designed as a liquidity mining reward for ecosystem participants, while other programs, such as Fantom's 370 million FTM reward program, are more specifically targeted at funded developers. In the Fantom project, if developers meet certain performance standards over a period of time, they can use rewards as they wish, including liquidity rewards.
Both Avalanche and Fantom projects distribute funds in the form of their local tokens, with other projects including Hedera, Algorand and Terra. As a result, the amount of these reward programs can vary according to the market, especially when contemporary coins are redistributed to a wider group of holders. These rewards typically come from team funding provided by early investors through seed rounds or token sales.
In 2021, investment firms increased their exposure to specific L1 ecosystems, whether through investments in specific projects or through local token sales.
For example, Solana Labs raised $314.15 million in June through a private token sale led by A16Z and Polychain Capital, as we highlighted in our fundraising and M&A section. Avalanche also announced a $230 million funding round in September, led by Polychain Capital and Three Arrows Capital.
Regardless of incentive-token distribution or financing, what matters most to each L1 team is the extent to which users and developers choose to invest time and money in their particular ecosystem. One way to measure this is to look at changes in ecosystem TVL over time, which provides a general sense of DeFi protocol growth.
However, as we noted in our previous report, DeFi protocols in a given ecosystem typically hold a large number of local network tokens (for example, SOL on Solana), which increases the impact of token price changes on the overall ecosystem TVL.
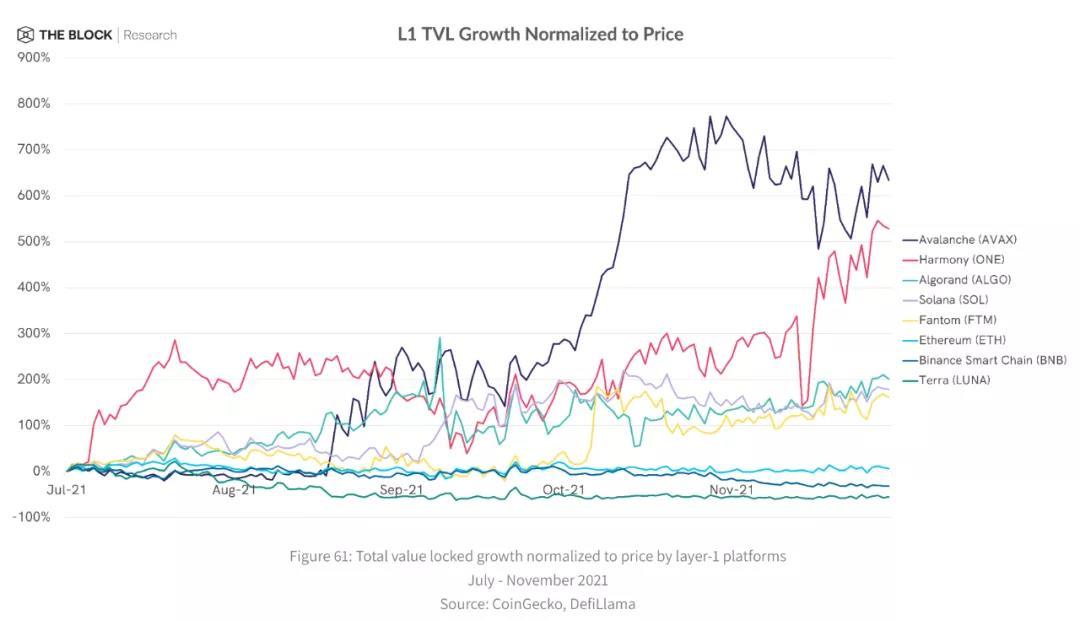
Normalizing the TVL growth of the ecosystem through the price of corresponding native tokens gives us a relatively more accurate picture of how much new capital is entering the ecosystem, rather than the dollar gain that is primarily determined by token price performance. Since the start of q3, just before the wave of L1 incentives began, TVL in the Avalanche ecosystem has seen a higher percentage increase in normalized prices than any other major L1 ecosystem.
Interestingly, Avalanche's TVL made its first big jump immediately after announcing Rush, and it's been able to retain a significant portion of its TVL over the past few months.
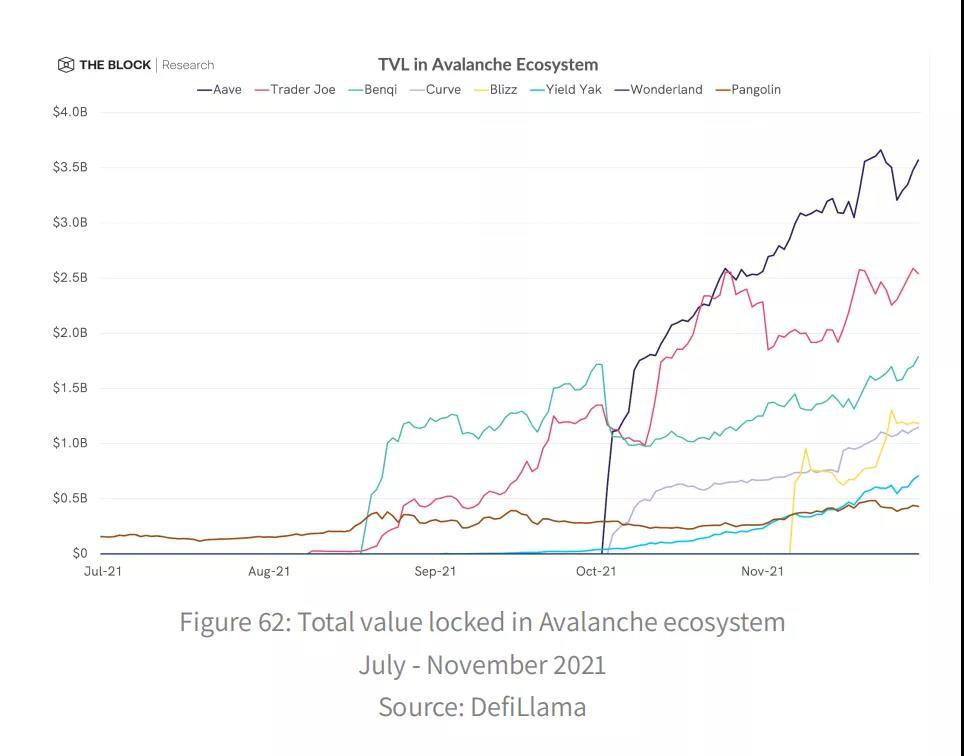
Avalanche's TVL has grown by $13.5 billion since q3 as of November 2021 when this article was written. Avalanche's success in attracting capital can be attributed in part to EVM compatibility on the Avalanche C chain, on which all DeFi protocols at Avalanche are currently based.
With users and developers able to interact with Avalanche using familiar Web3 tools such as Metamask and Solidity, the barrier to entry into this ecosystem is relatively low, especially for existing Ethereum users. Avalanche's growth in the second half of the year was also helped by Avalanche Bridge, which has significantly reduced cross-chain bridge costs since its upgrade in late August.
At the time of writing, Avalanche Bridge has continued to offer AVAX airdrops to Bridge customers for more than $75, ensuring Avalanche's Bridge customers can start using the network immediately without having to purchase AVAX separately as gas first.
Competition in the growing tier 1 ecosystem
Coupled with Avalanche's EVM compatibility, the relative ease of transferring value from Ethereum to Avalanche has fostered particularly strong competition in the growing ecosystem. At Avalanche, for example, Pangolin DEX was the biggest TVL deal to date, but Trader Joe launched in mid-August and shook up the ecosystem with its clean interface and liquidity mining rewards, surpassing Pangolin's TVL in September.
For more than a month, Trader Joe and The Loan agreement Benqi held the top spot in the Avalanche Ecosystem's TVL rankings, and by early October, both agreements held more than $1 billion in assets.
However, in early October, the arrival of existing DeFi protocols from Ethereum, Aave, and Curve marked the beginning of a new phase of competition in the Avalanche ecosystem. With the new liquidity incentive provided by the Avalanche Rush, Aave's TVL exploded at Avalanche, surpassing Benqi and Trader Joe for the first time in just a few days of release.
A similar story is playing out in the Fantom ecosystem, where TVL peaked at $6.2 billion on Nov. 9. As with the Avalanche ecosystem, DeFi's incumbents, who have gained significant adoption on Ethereum, are now starting to move into the Fantom ecosystem. Curve has become TVL's fourth largest agreement in the Fantom ecosystem as of November 30, having originally launched on Fantom in June and offering CRV liquidity rewards.
FTM rewards on Curve also went live on September 1, further promoting the use of staboin trading protocols through Fantom's rewards program. Interestingly, existing DeFi teams like Curve and Aave have been able to receive rewards directly from Avalanche and Fantom rewards programs, highlighting the desire of these L1 teams to attract established, well-known DeFi protocols to their ecosystems, It may even come at the expense of local protocols.
In fact, the proposal to deploy Aave on the Fantom network was approved on October 18. By such a strategy, Aave could receive FTM rewards and establish a deployment agreement in the near future.
In 2021, the battle for DeFi protocol dominance in the Fantom ecosystem remains intense, and during the year, Fantom's local DEX & NBSP; Both SpiritSwap and Spookswap are Fantom's top DEX, both TVL and quantity. In these rapidly evolving DeFi ecosystems, a clear trend in 2021 is that competition between protocols is evolving, leaving room for protocols to build significant network effects and communities.
With the DeFi protocol known as Ethereum native now starting to be released in many L1 ecosystems, these L1-native protocols are facing one of their biggest challenges to date in retaining and growing their user base. In a newer, smaller L1 ecosystem like Harmony, DeFi protocols naturally have more opportunities to quickly capture significant market share in the absence of an obvious leader.
Harmony has a relatively small user and capital base compared to the more popular EVM-compatible L1s, and as of Nov. 30, its approximately $542 million ecosystem in TVL is ready as it continues to grow. Environments like Harmony are also conducive to innovation, giving builders a chance to experiment with ideas in a less competitive environment.
A notable example of this innovation is the DeFi Kingdoms (DFK) agreement, which as of Nov. 30 has become Harmony's largest agreement, spending $280 million in TVL, or about 51% of Harmony ecosystem TVL.
As a DeFi protocol that includes a DEX based on an automated Market Maker (AMM) and a non-functional marketplace containing game UIs, DFK is a unique combination of games and DeFi in the crypto space today. In fact, DFK's position at the top of the TVL Harmony charts means it provides the highest source of liquidity for many deal portfolios in the ecosystem.
DFK has accumulated more TVL than SushiSwap and Curve's Harmony deployments combined, even though users must access its DEX and liquidity pool through a role-playing game (RPG) style interface. DFK and SushiSwap were more comparable in terms of DEXs volume, suggesting that some Harmony users looking to trade tokens may still prefer the standard, simple DEX.
Still, DFK has regularly outperformed SushiSwap in daily traffic on Harmony over the past few months, a clear sign that the new DeFi protocol has the potential to capture a meaningful share of user activity in the relatively small but growing L1 ecosystem. The big question is whether DFK can ultimately maintain its dominance over more established deals like Sushi in the face of future growth.
For now, DFK continues to extend its lead over DeFi rivals in the Harmony ecosystem, and seems unfazed even by Harmony's decision in September to offer Curve users a token $2 million bonus.
Ultimately, while it is difficult to predict which options will have the greatest success over time in L1 ecosystems, one thing is clear: with plenty of room for growth and destruction, the composition of these young ecosystems can change dramatically in just a few weeks.
Surpass EVM - Optimize performance and growth
As ethereum's network requirements and gas costs generally increase in 2021, evM-compatible chains are well positioned to position the flow of money from Ethereum to other L1 ecosystems as users and developers look for lower-cost alternatives with familiar UIs and concepts.
At the same time, the focus on L1 alternatives has brought renewed attention to non-EVM-compatible blockchains and their differences in performance, security, and design. Compared to previous years, the unique characteristics of different network architectures, Sybil resistance, and consensus mechanisms are being tested in production environments as various blockchains reach key milestones and usage begins to rise.
Following the explosive growth of DeFi and the overall crypto market in early 2021, many L1 chains began to develop their own DeFi ecosystems, without regard to EVM compatibility or easy access to on-chain capital.
A range of products launched throughout 2021 also highlights how protocols tailored to specific blockchains can enable experiences that may not be possible elsewhere. One of the most obvious examples of synergy between applications and blockchains is Serum, an order thin-based DEX built on Solana.
Typically, DEXs like Uniswap and SushiSwap generally adopt an AMM design throughout DeFi, where passive liquidity pools allow traders to trade tokens based on the current ratio of the two tokens in the pool. In the AMM category, variations on the standard constant product design have emerged over time, but they all still rely on auto-rebalancing liquidity pools that lack some of the core features of traditional central limit books.
For example, users of AMM are essentially asking to buy at market prices when they make trades, unlike traditional order books where the matching engine executes trades when buy and sell orders overlap at user-specified prices.
Solana's exceptionally high throughput (estimated at 50,000 transactions per second) and low transaction fees compared to other blockchains enable Serum's on-chain orders to function where other blockchains might not be feasible and costly. By comparison, throughput estimates for Ethereum and Avalanche are around 20 TPS and 4,500 TPS, respectively.
This ability to take advantage of its technical specifications to enable applications to benefit from the deployment of its ecosystem is likely one of the reasons Solana is poised for huge growth in 2021.
Although Solana is non-EVM compatible, it has accumulated $14.4 billion of TVL as of this writing, up from $153 million just six months ago, second only to Ethereum and BSC. Solana's TVL growth is significant, even normalizing it with a huge price appreciation relative to 2021, with SOL's price increasing from $1.84 at the beginning of the year to $208.71 on November 30.
Solana's DeFi ecosystem is dominated by its DEXs, which make up most of TVL's top protocols. At the top of the list is Raydium, which utilizes Serum's order book to provide a trading experience similar to that of a traditional centralised exchange, while also providing a liquidity pool that allows users to trade on Serum.
One of the first DEX releases on Solana, Raydium has been at the top of Solana's ecosystem TVL for most of 2021 and currently handles the majority of transactions in the ecosystem.
Marinade Finance, a deal that has grown considerably in recent months, is a liquid pledge solution for Solana that allows users to earn agreement fees by pledging SOL in exchange for mSOL, MSOL can then be used across the entire DeFi application of the Solana ecosystem.
Marinade's mechanism is similar to LidoFinance, a liquidity pledge solution that has seen considerable growth in the ethereum and Terra ecosystems in the form of stETH and bLUNA.
Interestingly, Marinade's growth continues despite Lido's deployment of its stSOL liquidity pledge solution at Solana in early September. At the time of writing, Marinade's PLEDGED SOL TVL, valued at about $1.5 billion, was much higher than Lido's $208 million.
The value of mobile products like mSOL and stSOL comes largely from their integration with other DeFi protocols in the ecosystem. If these products don't have sufficient liquidity or use cases, their value proposition drops dramatically compared to native SOL that can be used throughout the Solana ecosystem.
While Solana has seen immediate benefits from the technological superiority of its DeFi ecosystem, it has also seen significant growth in the NFT ecosystem in 2021, where factors such as network throughput are not necessarily critical. Using Solana's oft-fluctuating NFT floor price as its current market price, as of November 30, Solana   NFT has a total market capitalisation of more than $820m.
The Solana NFT ecosystem's growth in 2021 is due to a number of key infrastructure developments, one of which was the June launch of the Metaplex NFT platform, which allows users to create NFT on Solana and create their own store or marketplace.
The timely arrival of Metaplex's contract ecosystem underpinned the launch of Solana's major non-functional trading markets, such as Solanart and Digital Eyes, which were critical to the growth of Solana's overall non-functional trading activity.
One notable aspect of the upswing in NFT activity on Solana in 2021 is the interaction between Solana and Arweave, a decentralized storage solution that continuously backs up Solana's ledger data to its own blockchain via the SONAR cross-chain bridge.
Arweave also plays an important role with respect to NFTs, as it is the default storage solution for all NFTs created through Metaplex. In fact, one way to visualize non-functional financial activity on Solana in 2021 is to look at the transaction history on Arweave.
As the number of daily active users in the Solanart and Digital Eyes non-functional game markets began to rise in late August, so did the number of transactions on Arweave's network. Daily volume also peaked on October 7, which is consistent with the decline in active users on Solana's non-functional marketplace since mid-October.
As a whole, Arweave's unique symbiotic relationship with Solana's network is worth watching in the future, as the L1 network is expected to become increasingly interconnected over time.
The significant growth of the Solana ecosystem in 2021 can be attributed to the confluence of several key factors, including overall growth in the crypto market, timely product and infrastructure launches, and funding. However, its meteoric rise throughout 2021 has not been without challenges.
One of Solana's biggest network challenges for 2021 came in mid-September, when the main network experienced a long period of unplanned downtime that didn't begin to be fully resolved until approximately 17 hours after it started. A preliminary analysis of the event suggests that during the initial IDO of Grape protocol, a sudden increase in robot transactions resulted in an overload of network transaction processing queues, followed by excessive memory consumption that resulted in multiple nodes being disabled.
In the end, node verifiers voted to restart the network, but not before Solana's DeFi protocol faced a significant risk of failure that could result in significant losses of user funds. Solana's 2021 network outage highlights the unique challenges of creating a new blockchain ecosystem, especially when it's growing at such a rapid rate.
One problem is centralization, and Solana effectively trades throughput for decentralization because its validators are much more computationally intensive than other L1s. During outages, verifiers were able to quickly reach consensus to resolve critical issues, but it was also argued that this centralization of the network introduced a centralized point of risk.
While the ultimate goal of L1 like Solana is greater decentralization over time, blockchains are run by people, teams, and governance institutions that constantly innovate and allow systems to improve. For the relatively new L1 chain, this means occasional centralization may be needed early on to ensure continued success.
The fact that today's blockchain is ultimately evolving networks is most evident in the context of network upgrades, and the decisions of developers can have a huge impact on the future of networks. These upgrades can help optimize many aspects, including performance, growth, and security. For example, with the implementation of IP-1559, ethereum's London hard fork in August 2021 brought sweeping changes to the network's transaction fee structure and monetary policy.
Avalanche's September upgrade also introduced new block-based fees to the C-chain, as well as new congestion control mechanisms designed to combat malicious MEV activity on the network.
Sometimes upgrades are made to optimize growth, as we saw in the case of Tezos' Granada Mainnet upgrade in August 2021. Unlike most other L1 platforms, Tezos blockchain can be upgraded through an in-protocol modification process that does not require a hard fork.
In the Granada upgrade, Tezos' consensus algorithm was replaced, block times were reduced from 60 seconds to 30 seconds, and the concept of "baking" was introduced in the network. With this feature, Tezos governance effectively implements a local protocol mechanism to incentivize and attract network mobility.
To achieve liquid baking, Tezos created a fixed product market maker (CPMM) contract that acts like a liquidity pool for AMMs such as Uniswap. The contract encourages tzBTC to join the TZBTC-XTZ pool, continuously generating XTZ rewards, just as XTZ rewards are given to Tezos bakers (pledgers).
The addition of XTZ to the CPMM pool artificially inflates the price of tzBTC in the pool, thus incentivizes arbitragarists to add more tzBTC to their contracts in exchange for relatively "cheap" XTZ.
As of November 30, the contract had received about $20.2m in total liquidity since its introduction, although growth in the past few months has been relatively stagnant.
As we mentioned recently, one of the problems with tzBTC specific support from the Mobile baking contract is that tzBTC is relatively harder to come by for users who want to enter the Tezos ecosystem while remaining completely on the chain. To do this, you must bridge the asset through a wrapper protocol and then swap the tzBTC.
Instead, users may choose to simply connect the commonly used WBTC to wWBTC. As of Nov. 30, WBTC's liquidity on Plenty was about twice that of tzBTC. In fact, users may have little reason to remove their liquidity from CPMM contracts, limiting the effectiveness of liquidity incentives.
Even so, Tezos' unique approach of directly incentivizing liquidity through mainnet upgrades demonstrates just how liquid today's blockchain architecture is as it ADAPTS to changing market needs.
In this fast-paced crypto industry, protocol designs that were well suited to a particular L1 ecosystem a year ago tend to become obsolete once they reach new levels of growth or adoption. Thus, for new or growing blockchains, the ability to implement necessary changes relatively quickly could be an important factor in staying competitive and achieving continued growth.
L1, which has undergone a major upgrade in the past year, also has Terra, whose main network was upgraded to Columbus-5 on September 30. Terra's last mainnet upgrade to Columb-4 was in October 2020, and this upgrade brought Terra the CosmWasm Smart contract, which for the first time enabled developers to develop Rust applications for the Terra ecosystem. Less than a year later, the latest update brings many changes that reflect the needs of Terra's now more mature ecosystem.
In the early Columbs-4 Terra agreement, a portion of all LUNA destroyed for the release of UST was redirected to LUNA pledgers, as well as a community pool to fund general ecosystem initiatives. While this mechanism was initially beneficial in guiding the growth of Terra's young ecosystem, the emergence of supportive initiatives over the past year, such as Terraform Capital and the us $150 million Ecosystem Fund, has ultimately reduced the need for community pools.
Thus, Columb-5 instituted a new mechanism for the LUNA release tax, where 100% of the release tax is destroyed upon UST release, creating a simpler, more direct relationship between LUNA and UST needs.
This change is expected to put more deflationary pressure on LUNA in the long run as demand for Terra's UST staboin grows. Like ethereum's IP-1559 upgrade, Terra's 2021 Columbus-5 upgrade represents the way L1s is actively adapting to growth in a rapidly changing market environment.
Adapt to increasing connectivity in a multi-linked world
One of the main goals of Terra's platform is to expand the distribution of its UST staboin across the entire crypto ecosystem, regardless of the specific blockchain or protocol it uses. In the Terra model, UST was released during a period of increasing demand, where anyone could choose to destroy LUNA in exchange for an equivalent amount of UST at the current market price, effectively increasing the supply of UST.
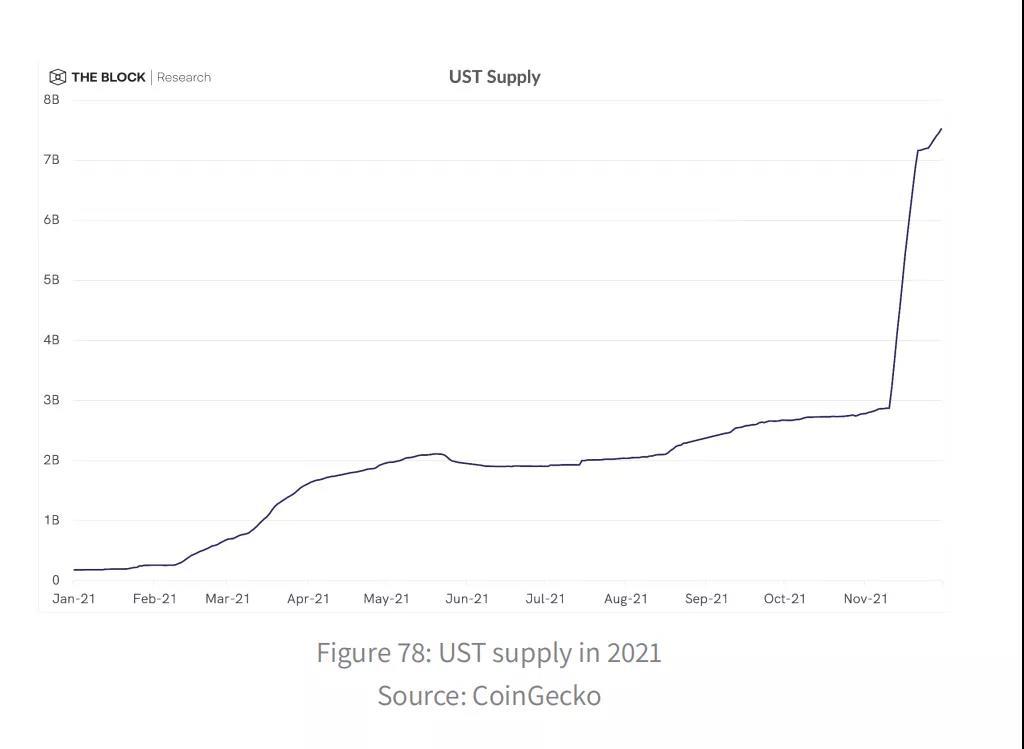
UST supply increased significantly during 2021, from about 182 million coins at the beginning of the year to about 2.7 billion coins on November 10, reflecting steady growth in demand for staboins throughout the year.
As of Nov. 22, UST supplies had soared to 7.2 billion pieces, an increase of about 4.5 billion pieces in just 12 days. The latest increase in demand is not the result of a natural surge, but is due to the November 9th adoption of Terra Proposals 133 and 134, designated in Columbus-5& NBSP; The Terra Community Pool created earlier destroyed 88,675,000 LUNA (about $4.5 billion at the time) in two weeks.
UST casted from the scheduled LUNA destruction is expected to be used for a number of programs, including funding Terra's local insurance agreement (called Ozone), purchasing collateral reserves for UST, and funding UST's multi-chain expansion.
Interestingly, another new feature implemented through the Columbus-5 upgrade is the transfer of LUNA/UST transaction fees to LUNA pledors, rather than being destroyed as in previous mainnet releases. In fact, the effects of LUNA's recent destruction on pledge rewards can already be seen.
Since Nov. 10, the annualized return on LUNA's pledge has more than doubled, and as of this writing, the expected annual return is about 10.4%. This increased revenue is also expected to benefit Terra's two largest TVL DeFi agreements, Anchor and Lido, which together hold $9.9 billion of the $12.7 billion worth of TVL in Terra's ecosystem as of November 30.
Anchor's TVL is largely made up of Lido issued bLUNA collateral, meaning the recent increase in LUNA's pledge revenue on Terra will benefit users of both protocols and translate directly into further growth. In addition to growth and protocol monetary policy, Terra's Columbus-5 upgrade also launched a significant new level of network interconnection, activating IBC transmissions on October 21.
As a blockchain built using the Cosmos SDK, Terra can theoretically communicate on-chain with any chain in the Cosmos ecosystem via the Inter-blockchain Communication Protocol (IBC).
With the ability to now transfer assets, Terra has taken a step further in expanding UST's presence, which is already available in other L1 ecosystems such as Ethereum and Solana. For the Cosmos ecosystem, activating Terra's IBC transmissions brings it closer to the vision of an interconnected system for the IBC support network.
At the time of writing, there are currently 25 IBC activated blockchains in the Cosmos ecosystem. Judging by the number of IBC transmissions, Osmosis currently leads the active area of the Cosmos network, followed by Cosmos Hub and Crypto.org. Since the launch of IBC in late October, Terra moved up to fifth place in the Cosmos most active region chain list in November.
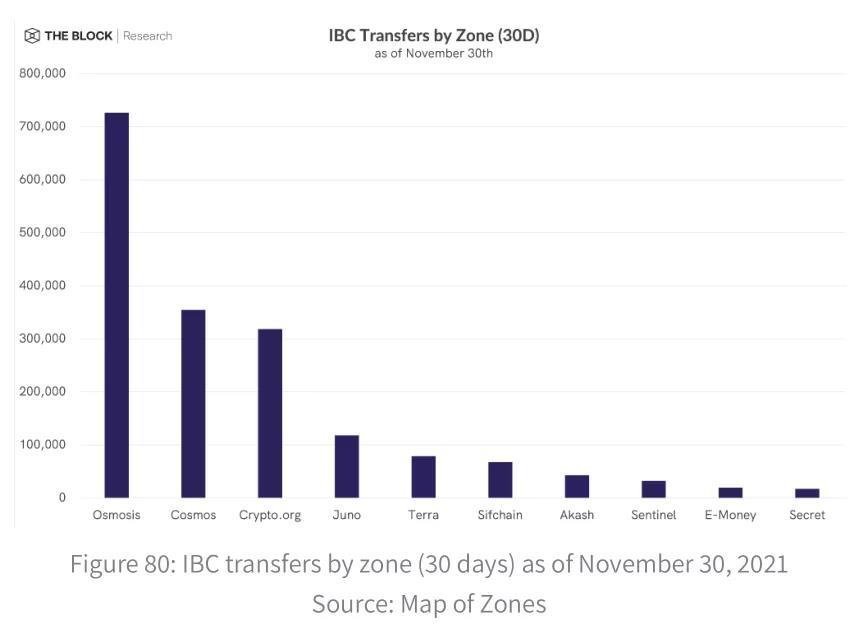
Perhaps the most obvious sign of Terra's expansion into the Cosmos ecosystem is the increased mobility of Terra's native assets on Osmosis. As the DEX with the largest volume and mobility in the IBC network, Osmosis can be seen as a litmus test for general activity in the Cosmos ecosystem.
UST and LUNA combined have amassed about $89 million in liquidity on Osmosis as of Nov. 30, second only to OSMO and ATOM, the native tokens of Osmosis and Cosmos Hub, respectively.
With increased liquidity, UST and LUNA are now among the most traded tokens on Osmosis, highlighting Terra's new presence in the Cosmos ecosystem.
For now, that is largely confined to Osmosis, which has grown rapidly since its launch in June. Since then, TVL on Osmosis has grown to approximately $615 million as of Nov. 28, thanks to initial airdrops to ATOM holders and continued OSMO incentives to liquidity providers.
The mobility incentive of Osmosis is representative of some key differences between Osmosis and Cosmos Hub, and the AMM DEX was originally conceived as a module.
Eventually, Osmosis was launched as a standalone DEX on its IBC-enabled blockchain, citing the need for rapid iteration of its characteristics, which would be limited by the relatively slow governance speed of the Pledgeers of the Osmosis Hub. In fact, signs of these limitations can be seen in the Hub's own DEX implementation, Gravity ; DEX.
The DEX, launched on July 13, gets much less liquidity than Osmosis, with about $34 million in TVL as of this writing. Although DEX itself technically went live in July, access to the exchange's front-end interface through Emeris Hub wasn't available until more than a month later, highlighting the obvious difficulties of building applications for the Cosmos ecosystem when constrained by hub proposals and voting processes.
At the time of writing, there is still no additional incentive provided for Gravity DEX mobility, a common feature in DeFi and Osmosis DEX. It was only as recently as November 9 that Cosmos Hub approved a proposal to increase the budget and agriculture module, which would allow ATOM to be allocated for specific purposes and through a standard agriculture mechanism. However, the actual implementation of these modules is not expected until early 2022.
As one would expect, with OSMO tokens, Osmosis's liquidity incentive mechanism gives it an advantage over Gravity in attracting liquidity, again demonstrating the effectiveness of rewards in promoting specific user behavior in DeFi. In the future, the role of the Cosmos Hub in the broader Cosmos ecosystem will be more clearly defined as a central portal that interacts with the chain connected to the IBC.
For example, the Hub will oversee the creation of a Gravity Bridge, a cross-chain Bridge that will allow users to connect ERC20 assets from Ethereum to Cosmos. As with other ecosystems, this cross-chain bridge is critical to widespread adoption of the Cosmos ecosystem, providing a direct way to transfer value from the most mature L1 ecosystem.
In the upcoming Vega upgrade, THE Cosmos Center will also add IBC router capabilities, which will allow it to route ibC-enabled chains for a fee.
One of the biggest developments in the Cosmos ecosystem was the introduction of the Cosmos Hub's interchain security system.
Essentially, this will allow a parent chain like Cosmos Hub to produce blocks for a child chain (such as an IBC-enabled chain, such as Osmosis). Although not expected until the second quarter of 2022, networks connected to the Cosmos Hub can inherit its security assurance, reducing the overall security cost of ibC-enabled chains.
When implementing this shared security model, the Cosmos ecosystem will start to look similar to the Polkadot network, which uses a primary relay chain to identify blocks for connected parallel chains. In 2021, the Polkadot ecosystem, like a field experiment, seeks to establish a network of interconnected networks protected by relay chains.
Much of this activity takes place on the Kusama network, which acts as a test net for Polkadot versions, allowing rapid iteration of theoretical concepts in production environments before Polkadot is deployed. One of the most important developments for the Polkadot ecosystem in 2021 was the first parallel chain auction held in Kusama in June.
Through the unique parallel chain slot auction process, which resulted in parallel chains like Karura and Moonriver, users were able to see in real time for the first time what a Substrate built network ecosystem could look like. Throughout the second half of the year, Kusama's parallel chain auction brought valuable attention and capital to the winners, effectively allowing the market to select the most coveted financial originals and products.
Crowdlending participants lock in hundreds of millions of dollars in KSM to support their favorite parallel chain projects, showcasing the overall hype for projects in the ecosystem and interest that fluctuates over time during the auction process.
So far, Polkadot's parallel chain slot trend looks similar to Kusama's story, with Acala and Moonbeam, sister networks of Acala and Moonriver respectively, winning the first two slots.
In fact, EVM use is so prevalent in the construction of L1 networks in 2021 that even emerging DeFi ecosystems like Algorand seem to be looking to take a cue from Ethereum, albeit from a slightly different Angle. In October 2021, the launch of Tinyman DEX was the biggest hit to DeFi from the ecosystem. Perhaps more important, though, is the introduction of algorithms and virtual machines (AVMs).
By developing the protocol's AVM enhancement tool on Algorand, the network is clearly hoping to replicate ethereum EVM's success in launching its smart contract platform.
As is often seen in other L1 ecosystems, the ability of developers to build DeFi primials on Kusama's connected network, supported by familiar Ethereum tools, facilitates rapid product launches and user acquisition. Moonriver is the best example of user activity, generating more than $350 million in TVL in the five months since its launch in June.
Nearly a third of Moonriver's TVL is currently locked in Solarbeam DEX, a platform that provides liquidity and offers native token SOLAR rewards. A key aspect of the Solarbeam protocol is that it integrates a cross-chain bridge between Ethereum and Moonriver, supported by the Anyswap protocol.
As of this writing, Anyswap: Moonriver Bridge's TVL is valued at around $284 million and is currently the largest source of capital transfer between Ethereum and the Kusama ecosystem. On October 19th, Bifrost and & NBSP; The Karura partnership exemplifies this important interconnectability, with BNC offering incentives for liquidity on the KaruraSwap DEX. Users can build a BNC bridge between the Bifrost and Karura chains by using XCMP's simple interface in both applications.
In a sense, Bifrost and The collaboration between Karura is reminiscent of composability, which is at the heart of mainstream DeFi protocols today, and the complexity of supporting tokens across different chains. At the same time, the introduction of new cross-chain technologies, such as the XCM format adopted by Polkadot and Kusama, comes with unforeseen risks that are often difficult to predict.
For example, Karura and Kusama ecosystems faced a major problem on October 12, when an attacker stole 10,000 KSM worth approximately $3.2 million from Kusama's parallel chain account. This vulnerability is likely due to Kusama network upgrading to XCM messaging standard V2, while its parallel chain still uses XCM V1.
In response, the administration quickly banned XCM transfers and passed a proposal that would allow them to force the stolen funds to be transferred back to Kusama's parallel chain accounts. Incidents such as these and the draconian measures taken by Karura and Kusama governance highlight the level of risk that remains in a largely unaudited environment that has undergone major iterations.
Main development of cross chain bridge & NBSP;
The emergence of cross-chain Bridges in 2021 is one of the most important developments that will facilitate the rise of various L1 ecosystems and current multi-chain landscapes. As the primary means of transferring assets between different chains without permission, these cross-chain Bridges have become important gateways for the seamless flow of capital across the entire crypto ecosystem. Similarly, tracking activity around cross-chain Bridges is now an effective way to assess the use and interest of certain ecosystems, both in the short and long term.
Perhaps the biggest example of the central role of a cross-chain bridge in today's crypto world is the dramatic rise of packaged Bitcoin assets on Ethereum. Since the beginning of 2021, the number of BTCS packaged on Ethereum has increased from around 140,000 to 3.1660 million today. At current BTC market prices, this represents an increase of about $10 billion in BTC assets on Ethereum, which is likely to be used as production assets under the DeFi agreement.
Most bitcoins on Ethereum exist as WBTC, which can only be issued by centralised custodians such as CoinList and Alameda Research. Other wrapped BTC assets, such as renBTC, are supported by a decentralized network of nodes, but they are still 1:1 supported with the actual BTC.
The best way to assess movement between L1 ecosystems is not just to look at the growth of packaged assets, but to look at the total value locked in by the cross-chain Bridges that connect the ecosystems. In 2021 in particular, a significant amount of money moved from Ethereum to other L1 chains, as DeFi participants sought to invest in early-stage protocols emerging on other chains, as well as to take advantage of attractive yields that might be found in the broader DeFi space.
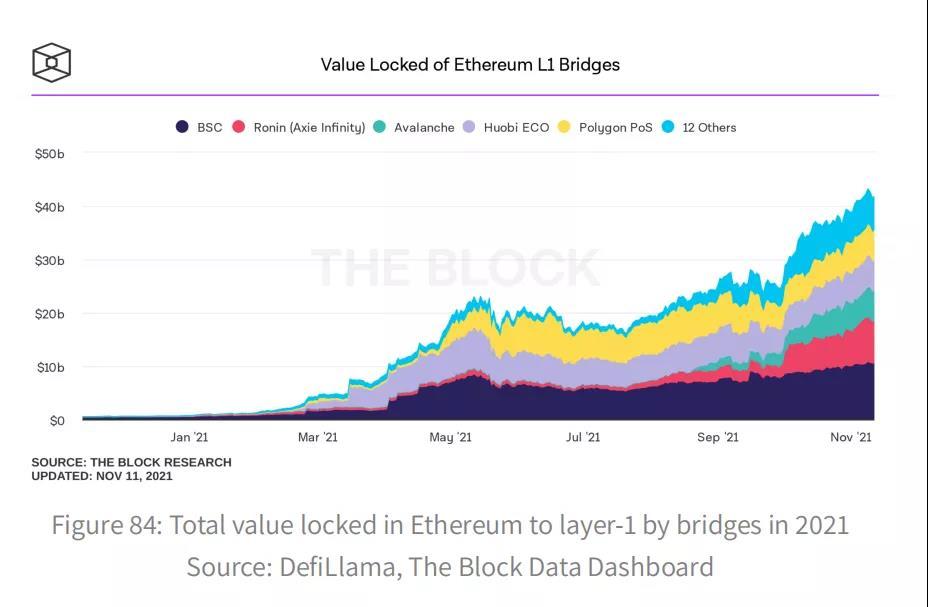
According to smart contract statistics on Ethereum, cross-chain Bridge's TVL for 2021 grew significantly, from $667 million at the beginning of the year to $32 billion as of November 30. Among the various cross-chain Bridges from Ethereum to other L1s, Binan Bridge has become the largest, with a TVL of about 10.4 billion us dollars as of November 30, reflecting the rise of BSC as the second largest smart contract platform. Cross-chain Bridges in 2021 take many forms, with different implementations and degrees of decentralization.
Binance Bridge, for example, is one of the most centralized cross-chain Bridges because it is completely managed by Binance. When a user sends an asset through binance Bridge, the asset is actually sent directly to binance Exchange, where they are still issued as a BSC-compatible wrapper asset.
While there is already a central point of failure in asset hosting, Binancbridge is not completely unpermissionable, as it prohibits users using US IP addresses, highlighting some of the major problems with central bridge for DeFi. Additional security measures have been put in place at other Bridges such as Avalanche Bridge in an attempt to better protect these assets, now worth billions of dollars.
In 2021, the analysis of capital flows to and from cross-chain Bridges has become a particularly meaningful indicator of capital flows to specific ecosystems. For example, another cross-chain bridge that reflects the growth of its target chain for 2021 is the Ronin Bridge, which players of the popular Axis Infinity game must cross in order to access the Ronin side chain and interact with the game.
Throughout 2021, leading P2E game Axie Infinity saw some of the most explosive growth in the DeFi protocol, jumping from an average of 581 daily users in January to an average of 121,000 daily users in November. This growth can also be seen in the TVL growth of Ronin's side chain, from approximately $31 million at the beginning of the year to $7.9 billion as of November 30.
Most of the Bridges deployed today have specifications similar to ChainSafe's ChainBridge protocol, which uses a "lock and release, destroy and release" mechanism. In this model, tokens transferred over the bridge are locked into the bridge contract and equivalent tokens are generated on the target chain.
When the packaged tokens are sent back via bridge junction, they are minted on the target chain and released from the bridge junction on the source chain. This approach works well in most cases because it provides an easy way to issue assets during a transfer without changing the supply of tokens in circulation.
However, the main drawback of this mechanism is that it requires bridge custody of transferred assets, which can create a vulnerable single point of failure. If the cross-chain bridge contract is breached, it could result in the theft of funds and render the packaged tokens worthless from the bridge. One of the cross-bridges using unmanaged mechanisms for cross-bridge transport is the Anyswap protocol, which became popular in 2021 as the main cross-bridge between Ethereum and Fantom.
Anyswap combines liquidity transactions with a normal issue/destroy mechanism, where intermediate tokens like anyUSDC are used to eliminate the need for bridge escrow. In an exchange example, a user connected to a USDC would put it into any exchange, which would issue any USDC 1:1 on Ethereum and then immediately destroy it, triggering any USDC issue on Fantom.
It then uses anyUSDC:USDC liquidity pool on Fantom to exchange the packaged USDC on Fantom. Under this mechanism, the transfer of assets does not require a bridge custody, only sufficient liquidity.
A notable example is the launch of Geist Finance on Fantom on October 6, with exceptionally high liquidity incentives, resulting ina flood of capital into the Fantom ecosystem via the Anyswap: Fantom Bridge. In just four days, the bridge received over $3 billion in deposit liquidity, most of which went into the Geist Finance agreement.
With returns on new lending agreements falling rapidly, capital was quickly pushed out of the Fantom ecosystem and the bridge lost about $1.8 billion in TVL just two weeks after TVL peaked. As cross-chain Bridges become an increasingly important source of value and activity in a growing multi-chain world, users may start looking for cross-chain Bridges that offer the ideal combination of speed, security, and decentralization.
These may look similar to the protocols of AnySwap, which also recently announced support for non-functional Bridges. Another cross-chain bridge also provides non-functional bridging and begins to gain traction in many chains. The Wormhole V2 bridge, for example, uses a unique generic cross-chain messaging protocol that theoretically allows any asset transfer between chains.
In the future, this common messaging format technically allows assets residing on one chain to be used in DeFi protocols on another chain without leaving the source chain. In a way, cross-chain Bridges essentially represent a subset of the predictor problem, in which providers are always looking for the ideal compromise between speed, accuracy, and security.
So it should come as no surprise that Prophetic machine provider Chainlink announced in August that it would use its new Cross-chain Interoperability Protocol (CCIP) to get into cross-chain gaming. With the increasing need for unlicensed asset transfers between more and more L1 ecosystems, the cross-chain bridge is in the middle of the future cross-chain DeFi.
In the future, it is unclear whether a bridge will eventually serve most of the cross-chain transfers. One thing is certain: the road to ultimate cross-chain interoperability will be littered with the emergence of potential solutions in various forms. In the end, the only way to arrive at the best cross-chain solution is to let the market decide for itself.
7. Development of ethereum 2-layer extension solution
As Layer 1 chains continue to threaten Ethereum's dominance as a smart contract platform, Ethereum has advanced its infrastructure by leveraging Layer 2 technology rollup. There are currently two types of rollups in the market, zero-knowledge and Optimistic, both of which currently exist on the Ethereum main network.
Even without the token release, Tier 2 has seen significant growth in TVL, which is likely to continue into 2022. With ethereum 2.0 sharding planned for 2022, and the possibility of token distribution, rollup will see greater adoption in 2022.
Optimistic rollups
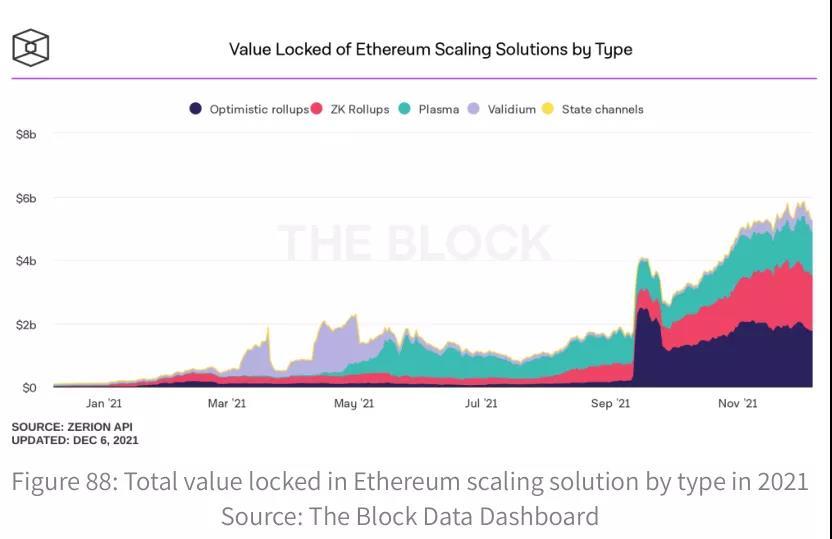
Optimisticrollups (ORUs) has a significant increase in 2021. Since the launch of Arbitrum and 0ptimistic main network on May 28 and June 22, ORUs has increased in TVL and user indicators. At the time of writing, the lock-up value of Arbitrum and Optimism is $2.6 billion and $400 million, respectively.
User indicators of Arbitrum and Optimistic are on the rise. Although Optimistic did launch Synthetix earlier, its main network is after Arbitrum. In other words, in terms of unique address, Optimistic and Arbitrum have roughly the same growth, but the peak transaction throughput of Arbitrum is significantly higher than Optimistic.
However, both Arbitrum and Optimistic are basically able to have similar transaction throughput, suggesting that Optimistic is ready for growth once decentralized applications (DApps) are allowed to deploy without permission.
Arbitrum and Optimistic have completely different positions in DApp deployment: Arbitrum actively seeks as many DApps as possible, while Optimistic strictly follows the requirements of whitelist in the deployment of DApp. Compared with Optimistic, this brings a larger ecosystem to Arbitrum. Since the number of Dapps of Arbitrum is significantly more than Optimistic(58 instead of 6), the DApp advantage chart below only lists the significant protocols of Arbitrum.
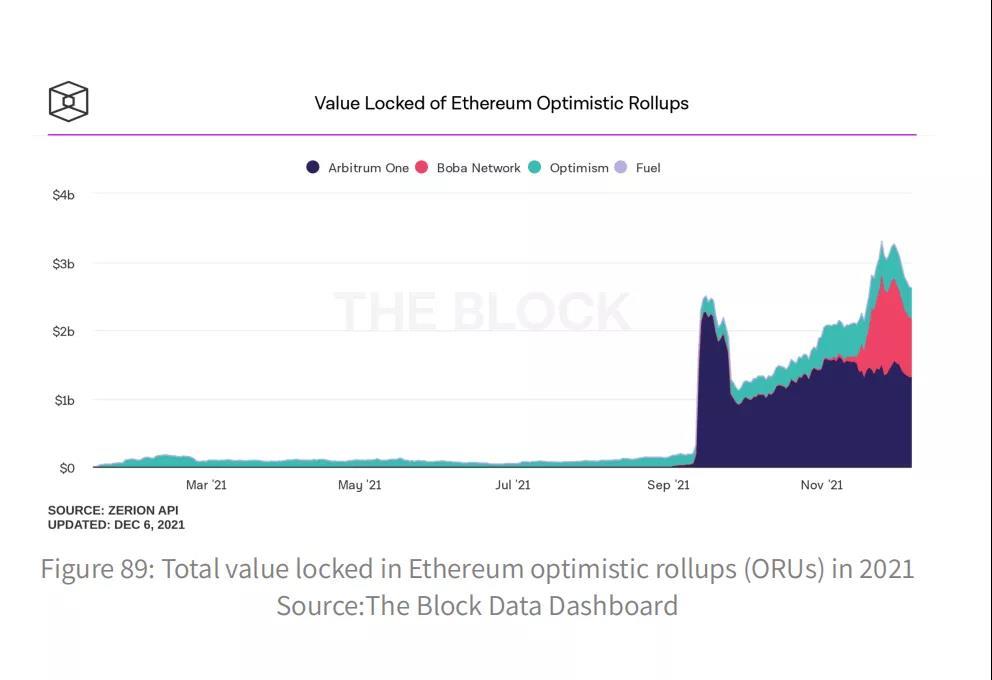
By Curve, Balancer and SushiSwap, Arbitrum has achieved significant growth. More notably, Abracadabra has also seen rapid growth in TVL, partly due to the rapid rise in the price of its local token SPELL. These DApps have always dominated Arbitrum's TVL and may continue to do so in 2022.
Optimistic, on the other hand, is dominated by Synthetix. This is partly because Optimistic only has six DApps at the time of writing this article. As more dapps are deployed around Optimistic, Synthetix's dominance will most likely eventually decline.
In addition, there are two notable ORUs that gained significant traction in the last quarter of 2021, namely Boba and Metis.
As of this writing, Metis has only one test net DEX, while Boba already has a functional bridge and a local DEX called OolongSwap that can be used for actual transactions. The Boba Network airdropped their native Boba tokens to OMG token holders on November 12.
This led to a lot of speculation about the price of OMG tokens before the airdrop. More notably, OMG's perpetual contracts were funded at a rate of -2.4% every two hours on Binance, and OMG's price collapsed after the airdrop of snapshots. Another airdrop using this model is unlikely.
That is, after the BOBA token airdrop, it experienced a sharp increase in TVL, mainly due to the TVL increase of BOBA's local DEX OolongSwap. OolongSwap has a liquidity mining incentive mechanism, which quickly attracted a large amount of funds to provide liquidity. That said, a large portion of OolongSwap's funds are likely mercenaries who could leave the ecosystem once the returns are no longer attractive.
Another notable competitor is Metis DAO, whose native token Metis rose in price after the BOBA airdrop. Going forward, given the extent to which it distorts market prices, it is unlikely that any L2s will repeat airdrops of tokens in the way BOBA did. That said, it is likely that the two largest ORUs will eventually have to issue some form of token.
Zero-Knowledge rollups
In 2021, Zero-Knowledgerollups (ZKRs) saw phenomenal growth, from $43.5 million TVL on January 1, 2021 to $1.9 billion now locked in ZKR solutions. Validium, a scalable solution that utilizes proof of validity but stores data off-chain, has also seen TVL grow throughout the year, though not as dramatically as ZKR.
One of the most notable highlights in the ZKR space was the release of dYdX, which uses StarkEx to extend transaction throughput. The exchange also launched governance tokens, which resulted in TVL growing from $96.5 million on September 8 to $930 million by the end of November, becoming the main driver of ZKRs TVL's growth.
ZKR's other projects include Loopring, ZKSwap V2, zkSync, Aztec and Polygon Hermez, all of which have increased in value since the beginning of the year, TVL's cumulative value rose from $40m at the start of the year to $943m at the end of November.
While the Validium lock has not grown in value as dramatically as the ZKR version, notable non-functional projects Sorare and ImmutableX both use StarkEx. Similar to dYdX, ImmutableX announced their utility token on July 22, which can be used for governance or for rewards.
This resulted in Immutable being TVL's highest Validium project at the end of the year, reaching almost $350 million. During the year, ZKSwap V1 actually had the highest TVL, but is no longer in use due to the release and success of V2.
In addition to ZKR and Validium's growing TVL, we can also see their usage increasing one day through deposit notifications for smart contracts based on proof-of-validity scaling projects. Although the development of different projects and the number of days with high deposits varies, most projects have sustained benefits from the need for deposit functionality.
StarkWare and Matter Labs are pioneers in the field of proof of validity. In 2021, StarkWare has launched StarkNet Alpha to the main network on November 29, with the aim of building a complete layer 2 for users and developers to connect back to the main network via ZK-Starks.
Matter Labs announced that their zkSync 2.0 will use zkEVM, an EVM-compliant compiler. Similarly, both companies are working on creating a hybrid data availability where users can choose whether their data is stored on or off the chain, developing Volition and zkPorter as their solution to merge the two forms of data storage.
Viii. Competitive prospects for Tier 1 Platforms and scale-out solutions in 2022 & NBSP;
Much of the discussion around L1 and L2 platforms in 2021 focused on scalability, especially as ethereum transaction fees and usage hit record highs at a time when encryption and NFT became a new mainstream focus. In theory, L1 and L2s have different technical limitations and security guarantees.
In fact, from a user experience perspective, they currently function similarly. To take advantage of the speed and cost improvements of L1 and L2 chains, users must first connect funds from L1 chains, such as Ethereum.
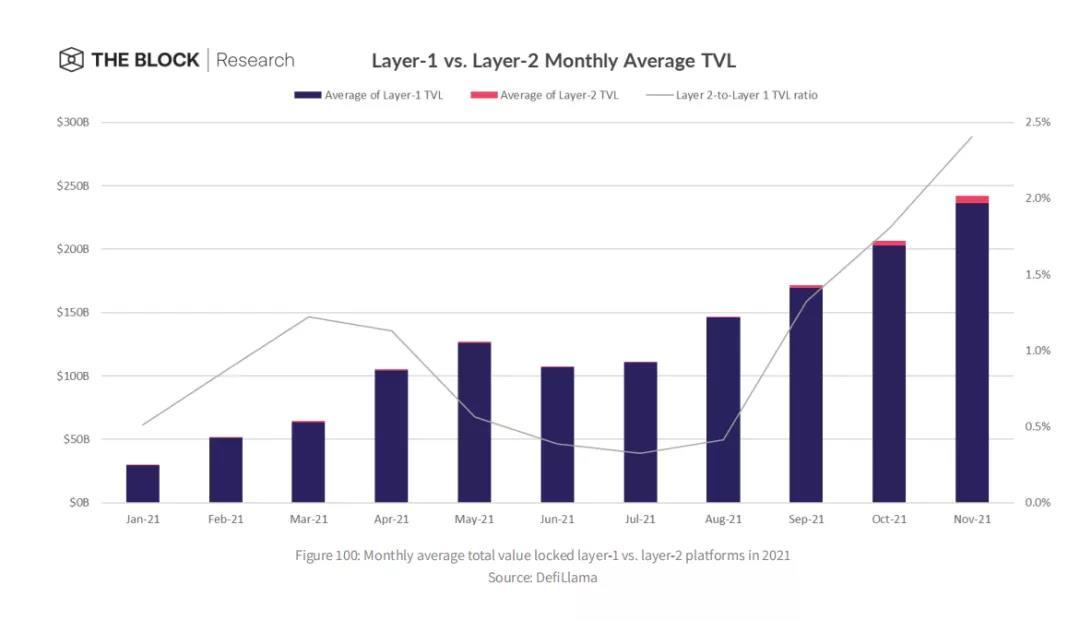
Thus, as with L1 to L1, a bridge to L2s can be a valuable indicator of the amount of money flowing from L1 to a particular L2. For example, Optimistic TVL on the Bridge has grown from about $47 million at the start of the third quarter to about $517 million as of Nov. 30.
While experiencing a more than 10-fold increase in TVL over the past few months, The bridge's TVL is still dwarfed by other major L1 cross-chain Bridges, such as BSC, whose TVL as of 30 November was approximately $31 billion.
Currently, L1s has the advantage of hosting a larger overall protocol ecosystem, as well as key infrastructure features such as prognosticators, cross-chain Bridges, centralized exchange support, application support, and more. This fact is evident when TVL in L1 and L2 protocols are compared, indicating that DeFi activity is currently dominant on L1 over L2s.
At the same time, the L2s is showing increasing traction in its growth. Typically, part of this increase can be explained by the introduction of liquidity incentives that began to appear on L2s. For example, ArbiNyan on Arbitrum launched in early September, token inflation rate and APYs are very high, which leads to a large number of mercenary capital into the Arbitrum ecosystem to obtain quick gains, but soon left.
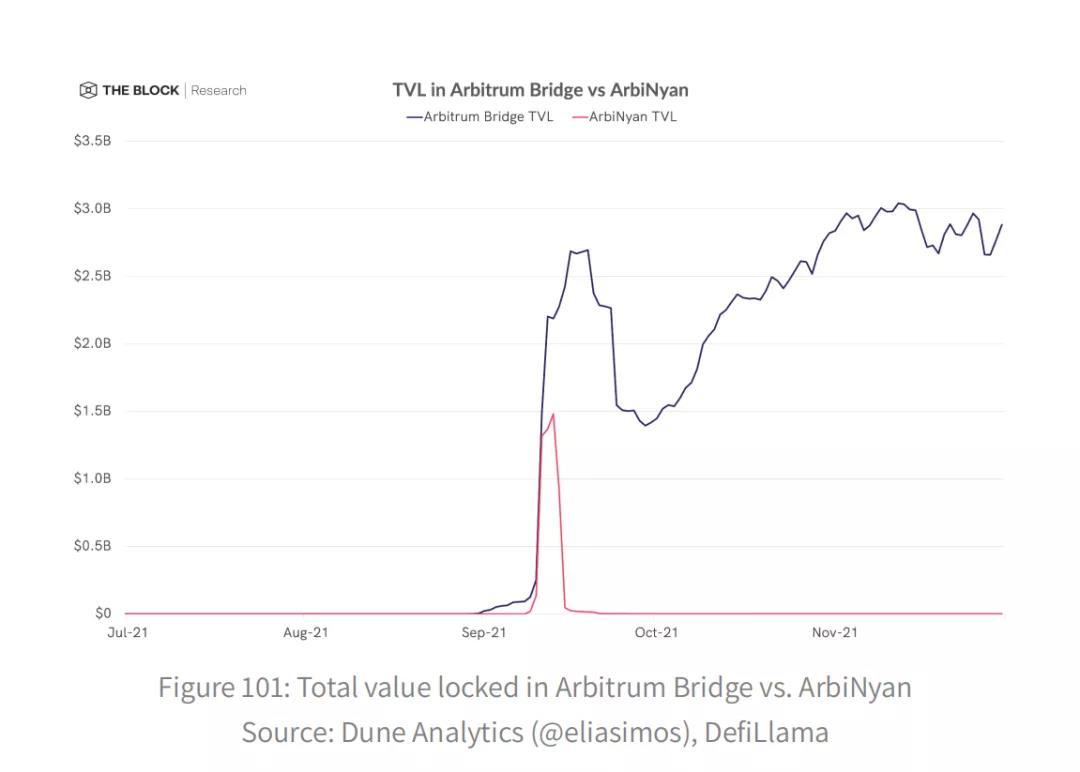
That is to say, Arbitrum and optimisticnbsp; There is still a significant increase in TVL. Although ArbiNyan's funds quickly flowed into And then out of Arbitrum, Arbitrum's TVL has continued to grow since the beginning of September. Only a handful of applications currently exist. Optimistic But it is very likely that in 2022 more DApps will run on this L2, which will make it possible. Optimistic The growth trajectory is the same as Arbitrum.
Another factor to consider is the possibility of local tokens for L2s. Fundamentally, L2s are not ready to compete with L1s, but there is every reason to believe they will in 2022. The combined effect of entry-level DApps, greater revenue generation opportunities, low fees, fast transactions, Ethereum-level security, and the possibility of local tokens is enough to jump to L2s above L1s.
The original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia
 Related Articles