11 partners of a16z tell you the direction of financial technology development in 2022
Original title: "a16z: What big problems will fintech solve in 2022?"
Original author: Angela Strange, Sumeet Singh, Tomicah Tillemann and other a16z employees
Original translation: Old yuppie who doesn't go to DAO
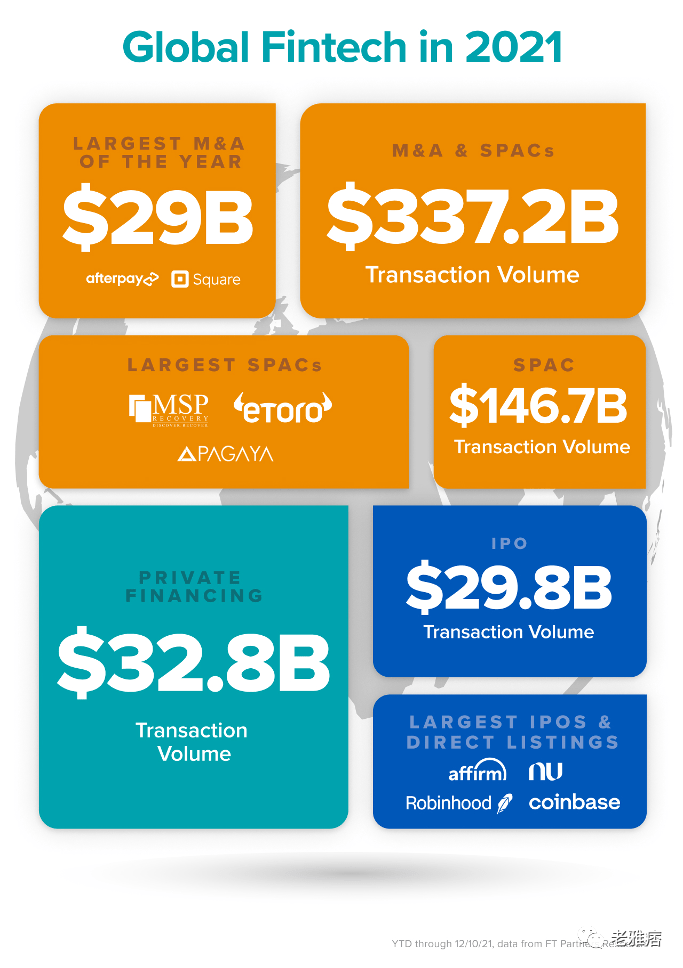
In 2021, financial services continued to have its moment - fintech raised more money than all previous years; it was a big year for fintech IPOs; and large fintech M&A activity reached an all-time high. Before the end of the year, we saw one of the largest fintech IPOs, Nubank raised $2.6 billion (as the largest digital bank), one of the largest fintech M&A, Square's acquisition of Afterpay for $29 billion, Wise's first direct listing in the UK, Coinbase's first direct listing as a fintech/cryptocurrency service, and multiple fintech SPACs.
What big problems might FinTech solve in 2022?
1. FinTech x Cryptocurrency
1. Low-carbon technology permeates all financial services
20 years ago, "Is it an Internet company?" was a common question. Today, (almost) every company is an Internet company. Ten years ago, "Is it a mobile company" was a common but now outdated question. Similarly, we will soon stop asking "Is it a cryptocurrency company?" because most companies - starting with the broader financial services industry - will have a cryptocurrency component.
As cryptocurrencies capture more and more of consumers' mind share, financial applications are adding cryptocurrency products to further gain wallet share. For example, Robinhood started with stock trading and now facilitates some cryptocurrency trading; some new banks allow customers to earn higher yields through DeFi (decentralized finance); and large banks are in the early stages of experimenting with cryptocurrency products. In 2022, we will see more cryptocurrency infrastructure built for transfers, wallets and yield-as-a-service, custody, etc., so consumers can continue to integrate and manage their fiat and crypto financial lives. We will also see a wave of new fintech companies that are powered by back-end cryptocurrency infrastructure, and what others call DeFi mullets (fintech first, DeFi later).
- Angela Strange, General Partner at a16z Fintech, and Sumeet Singh, Deal Partner at a16z Fintech
2. The web3 community will become a major political constituency in the US midterm elections
As we close out the year, one in five US voters now own cryptocurrency. According to a recent poll we conducted, web3 and the future of the internet will influence how many people vote in the 2022 US midterm elections.
Web3 voters are young and diverse. 79% of millennial voters, 73% of Hispanic voters, and 79% of Black voters are more likely to vote for a candidate who supports expanding Web3. Most of these voters came of age after the Great Recession, and many of them come from communities that have been overlooked in trying to build generational wealth. They seek a meaningful alternative to the current financial system - one that gives them direct control over their money and provides investment options for segments of society that are neglected by traditional financial institutions.
So what do these voters care about? They want policymakers to focus on regulations that combat bad behavior and illegal activity, while being careful that regulations don't hinder economic opportunity for everyday Americans. They want policymakers to support and participate in our national technology strategy. They overwhelmingly believe that web3 can give consumers more control over their data. They believe web3 can strengthen America's technological leadership on the global stage. They also want the government to play an active role in supporting community-owned web3 platforms.
There's no doubt that web3 will be a big part of next year's election, and policymakers are quickly recognizing the stakes.
- Tomicah Tillemann, global head of crypto policy at a16z, and James Rathmell, crypto advisor at a16z
3. Community-first social investment platforms
What do the GameStop saga and ConstitutionDAO have in common (besides Citadel’s Ken Griffin)? They both illustrate the desire of internet community participants to collectively use their capital for a greater goal — whether that goal is running a distributed hedge fund or buying a copy of the Constitution.
In 2022, we’ll see multiplayer, community-driven social investment platforms that tap into this internet culture of collective action. Many of the products we’re seeing being built here don’t resemble other social products, so instead of having features like leaderboards and transaction tracking, they’re built around new product primitives like asset pools, voting, and coordination to enable collective investment, whether that’s a distributed hedge fund, advancing social and environmental goals, or pooling money to buy collectively owned assets. These products will have clear advantages - embedded distribution given the multiplayer approach and higher engagement given the fun they can add.
- Sumeet Singh, a16z Financial Technology Deal Partner
Second, Fintech x Healthcare
Every Healthcare Company is a Fintech
As we’ve said before, Fintech products enable vertical SaaS businesses to diversify into new revenue streams. In healthcare — a system that accounts for 20% of U.S. GDP, we see three areas where Fintech capabilities could supercharge the industry in 2022: consumer payments and lending, provider practice capabilities, and insurance.
Healthcare payments are particularly complex due to the U.S. third-party payment system, in which providers bill for services, payers reimburse for those services, and consumers receive services. As a result, a one-size-fits-all solution, such as Stripe, is unlikely to offer the full set of capabilities needed to fully support medical practices, such as regulatory compliance and health plan integrations. This leaves an opportunity for payment gateways and financing products in specific verticals, such as buy now, pay later (BNPL), to help consumers finance their medical bills and reduce the risk of bankruptcy due to unplanned medical expenses.
On the provider side, BNPL can improve collection rates, which can be as low as 20% in some areas. There are also emerging fintech products that aim to diversify revenue and profit streams by assuming risk and helping providers normalize their business models into “per month per member” (PMPM) arrangements, as well as adding billing capabilities for new service lines.
Finally, the unbundling and re-bundling of traditional health insurance has created new fintech platforms that support the flourishing of new insurance products for individuals and businesses. These companies modularize underwriting, claims processing, provider network management, and utilization management capabilities to help companies manage risk across their insured populations in a more flexible, affordable, and transparent way.
As fintech moves into healthcare services and software, we see the potential to reshape incentives and eliminate inefficiencies, paving the way for a more value-oriented healthcare system.
- David Haber, General Partner, a16z Financial Technology, Julie Yoo, General Partner, a16z Bio
III. Fintech x Sustainability
Fintech Goes Zero Carbon
Have you noticed that the default setting on Google Maps now guides you to the most fuel-efficient route? Or how your account is opened with the "Paperless Statement" box already checked on your bill? This kind of environmentally conscious configurability is coming to the world of fintech. Imagine a checkout experience where switching between debit, credit card, ACH, PayPal, BNPL, and all the various payment methods available in 2021 will show which method is the least environmentally harmful to that particular merchant.
Or, better yet, it embeds a feature that lets you add x dollars to your purchase to offset emissions along any route you choose. Improvements in emissions data infrastructure and technology are making this rapidly possible. Payment providers, neo-banks, logistics companies, and more are likely to embed carbon offset options into their products as companies like Patch, Capture, and Wren make it easier for businesses and consumers to not only understand their climate footprint, but also to take action.
What remains to be seen, however, is what will motivate consumers to choose greener products or delivery methods over those that might be more convenient. Just as the eco-friendly route on Google Maps might actually be the slowest, today, the green options in commerce are often the most expensive. Startups at the intersection of climate and financial technology must create new incentive structures that make eco-friendly choices not only more responsible, but also more affordable and rewarding than their traditional counterparts. Think higher APRs, lower APRs, better returns, or reduced fees.
One of our favorite case studies of creative incentive alignment around this space comes from Powerledger, a blockchain platform for peer-to-peer energy trading, and Carlton United Brewery, an Australian beer company. When Carlton set a goal to be powered entirely by renewable energy by 2025, they partnered with Powerledger to create a fantasy loyalty program for eco-friendly beer drinkers: trading excess energy for kegs. Carlton customers can sign up to trade excess energy generated by their home’s solar panels for beer delivered directly to their homes.
- Mark Andrusko, a16z Fintech Deal Partner
Four Trends in Fintech
1. Beat Rising CAC Through Partnerships and Product-Led Growth
Over the past few years, we’ve seen meaningful inflation in digital customer acquisition channels (FB and GOOG) as competition increased and changes like Apple ad tracking made attribution harder. To further fuel competition, the vast majority of fintech companies have focused on the same customer profile (subprime), offering the same products (like banking, investing, lending) and a series of ever-increasing customer perks to join (free money on the internet!). So, in 2022, how will companies differentiate themselves in the face of increasingly competitive and constrained digital acquisition channels?
We believe there are two answers - the best companies will grow through products that lend themselves to product-led growth, or partnerships represent non-inflationary distribution opportunities.
On the product side, we’re seeing today’s products become tomorrow’s entry-level products; simply offering a bank or brokerage account is no longer enough to stand out, as new APIs make it incredibly easy to integrate core banking features (e.g., saving, spending, lending, investing) into nearly any app experience. Instead, the products that capture consumers’ imaginations will remix these fundamentals in new and interesting ways, leveraging community, cryptocurrency, and commerce. In particular, we expect to see more multiplayer products driving growth — currencies are inherently multiplayer (medium of exchange!), but financial products have largely been single-player games to date.
On the partnership side, we’ve seen Credit Karma’s partnership with the Houston Rockets, Chime’s partnership with the Dallas Mavericks, and Guideline’s distribution agreement with Gusto and Melio’s distribution agreement with Intuit. While these channels have price leverage and may raise prices over time, they represent the kind of predictability and volume in acquisition costs and access to supply that has been largely absent from recent digital marketing channels. Founders would be wise to take note of these examples - companies that have historically been the best at direct-to-consumer marketing are now looking to business development and partnerships for continued growth, a trend we expect to continue into 2022.
- Anish Acharya, General Partner, A16Z Fintech
2. More Fintechs to Emerge in Emerging Markets
This year, emerging markets have seen explosive startup activity, record funding, and impressive exits. Nubank’s IPO, in particular, was a watershed moment for Latin American and global fintech, representing a large exit in Latin America and generating a wave of founders in its wake. 2022 will bring more investment and innovation growth to financial services across emerging markets. We are likely to see several megatrends in the types of companies that emerge.
Historically, there has been a lot of B2C fintech in emerging markets, now we will see more B2B helping small businesses and enterprise customers digitize and optimize payments, pay employees more efficiently, purchase supplies, handle accounting, insure themselves, and more.
Second, new modern APIs will make it possible for companies to take payments, access bank account information, issue cards, bridge cryptocurrencies, verify identities, and more. Rather than needing to manually build one-off integrations with legacy financial systems, companies will be able to plug into modern infrastructure to launch new fintech products with much less upfront cost. There needs to be enough demand to justify the new infrastructure, and we are starting to reach that significance in the ecosystem.
Third, the business models that will emerge will increasingly look to other emerging markets for inspiration rather than to the US and Europe. There are business models and feature sets that are better suited to emerging markets as a whole, based on existing user behaviors, regulations, and stages of digitization. For example, many local B2B marketplaces (with embedded financial technology) have emerged in India and Latin America that don’t exist in the US or Europe, in part because they provide small businesses with access to things like credit and logistics that tend to be particularly expensive and fraught with friction in emerging markets. We’ve seen business models like super apps (both consumer and business) and community buying platforms flourish, as well as feature combinations like investment apps that started with funds rather than stock trading.
We’ve seen entrepreneurs in these regions interconnected. We met founders in São Paulo building accounting infrastructure for small businesses who regularly get advice from their peers in Jakarta via WhatsApp. Entrepreneurs in Lagos look to Karachi for inspiration for business models for their B2B marketplaces. COVID-19 has accelerated many tech trends, but it has also shrunk the world dramatically.
- Seema Amble, Partner, a16z Fintech; David Haber, General Partner, a16z Fintech; Gabriel Vasquez, Partner, a16z Fintech
3. Insurance MGAs Refocus on Underwriting
The first wave of insurance startups mostly focused on moving historically offline processes online, leaving much of the underwriting process untouched. With a prolonged low interest rate environment, insurers are more willing to test new markets and strategies to find yield. Coupled with the lack of scale in the insurance startup ecosystem compared to other markets, many capability partners view new entrants as testing partners to learn and try to find new profitable strategies. As rates rise and the market hardens, a renewed focus on underwriting differentiation and profitability will become a priority, likely driving acquisitions in the first generation of the insurance technology world, as well as new entrants focused on monetizing underwriting advantages.
- Joe Schmidt, Fintech Deal Partner at a16z
Note: The opinions expressed herein are those of the individuals of AH Capital Management, L.L.C. ("a16z") and not of a16z or its affiliates. Certain information contained herein has been obtained from third-party sources, including from portfolio companies of funds managed by a16z. While obtained from sources believed to be reliable, a16z has not independently verified the information and makes no representations as to its enduring accuracy or its appropriateness for a particular situation. In addition, the content may include third-party advertisements; a16z has not reviewed these advertisements and does not endorse the content of any advertisements contained therein.
Original link
Welcome to join the official BlockBeats community:
Telegram Subscription Group: https://t.me/theblockbeats
Telegram Discussion Group: https://t.me/BlockBeats_App
Official Twitter Account: https://twitter.com/BlockBeatsAsia

 Related Articles